
 Near-Patient Molecular Solutions Market | 2026-2036
Near-Patient Molecular Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Near-Patient Molecular Solutions Market Foresight
Silica-based membrane chemistry is pivoting toward polymerase-friendly surface modifications that reduce inhibition rates in crude sample matrices. Abbott Laboratories leverages captive supply of stabilized enzymes to protect margin structures in high-volume cartridge production. Roche Diagnostics anchors its competitive position through proprietary real-time PCR optical systems that sustain instrument pull-through revenue. Thermo Fisher Scientific specializes in modular thermal cycler architectures that extend platform life cycles across clinic and hospital deployments.
Near-patient molecular solutions encompass nucleic acid amplification and detection systems designed for operation outside centralized laboratories, typically completing diagnostic workflows within sixty minutes using sample-to-answer cartridges with integrated lysis, purification, and quantification steps. These systems serve acute care settings where therapeutic decisions depend on rapid pathogen identification or pharmacogenomic stratification. The product type dimension shows PCR platforms occupying the deepest installed base while LAMP assays capture the fastest expansion in resource-limited settings due to simpler thermal requirements. Within delivery mode, point-of-care configurations concentrate the highest per-unit pricing power, whereas home testing represents the most contested margin pool as reimbursement frameworks remain unsettled.
FDA premarket review pathways for point-of-care molecular devices shape development timelines and clinical trial investment levels for manufacturers seeking US commercialization. The Clinical Laboratory Improvement Amendments framework governs operator certification requirements, directly determining addressable site density for waived-complexity platforms. Stakeholders must monitor how CMS reimbursement decisions for multiplex respiratory panels redistribute volume between hospital laboratories and decentralized testing locations.
Market Dynamics
Integrated health systems in the United States are consolidating procurement of decentralized testing platforms, compressing vendor selection cycles and favoring cartridge economics over instrument pricing in contract negotiations.
Growth Catalysts
- CLIA-waived complexity designations:The Clinical Laboratory Improvement Amendments framework expands operator pools beyond certified laboratory personnel, enabling deployment in urgent care clinics and retail health settings.
- Hospital emergency department throughput pressure:Acute care facilities prioritize sixty-minute turnaround infectious disease panels to reduce length-of-stay metrics and isolation bed utilization.
- Silica membrane surface chemistry advances:Polymerase-friendly modifications reduce inhibition in crude matrices, eliminating preprocessing steps for respiratory and bloodstream samples.
Market Restraints
- Stabilized enzyme supply concentration:Captive production of thermostable polymerases concentrates among three specialty chemical suppliers, exposing cartridge manufacturers to input cost volatility.
- Real-time PCR optical system complexity:Proprietary fluorescence detection architectures require precision manufacturing tolerances that limit second-source instrument availability.
- Home testing reimbursement uncertainty:CMS has not established consistent coding for patient-administered molecular diagnostics, constraining addressable margin pools in consumer channels.
Strategic Opportunities
- Resource-limited setting LAMP expansion:Loop-mediated isothermal amplification assays operate without thermal cycler infrastructure, opening procurement pathways in primary care networks across India and sub-Saharan Africa.
- Pharmacogenomic stratification in oncology:Tumor mutation profiling at the point of care enables same-day targeted therapy selection, creating white space in community cancer center infusion suites.
- FDA breakthrough device designation pathway:Accelerated review timelines for antimicrobial resistance detection panels compress development-to-revenue cycles for respiratory and bloodstream infection assays.
Industry Challenges
- Multiplex assay validation complexity:Demonstrating analytical performance across pathogen combinations extends clinical trial timelines and regulatory submission preparation.
- Legacy laboratory information system integration:Point-of-care instruments require bidirectional connectivity with hospital electronic health records, demanding customized middleware development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Near-Patient Molecular Solutions Market |
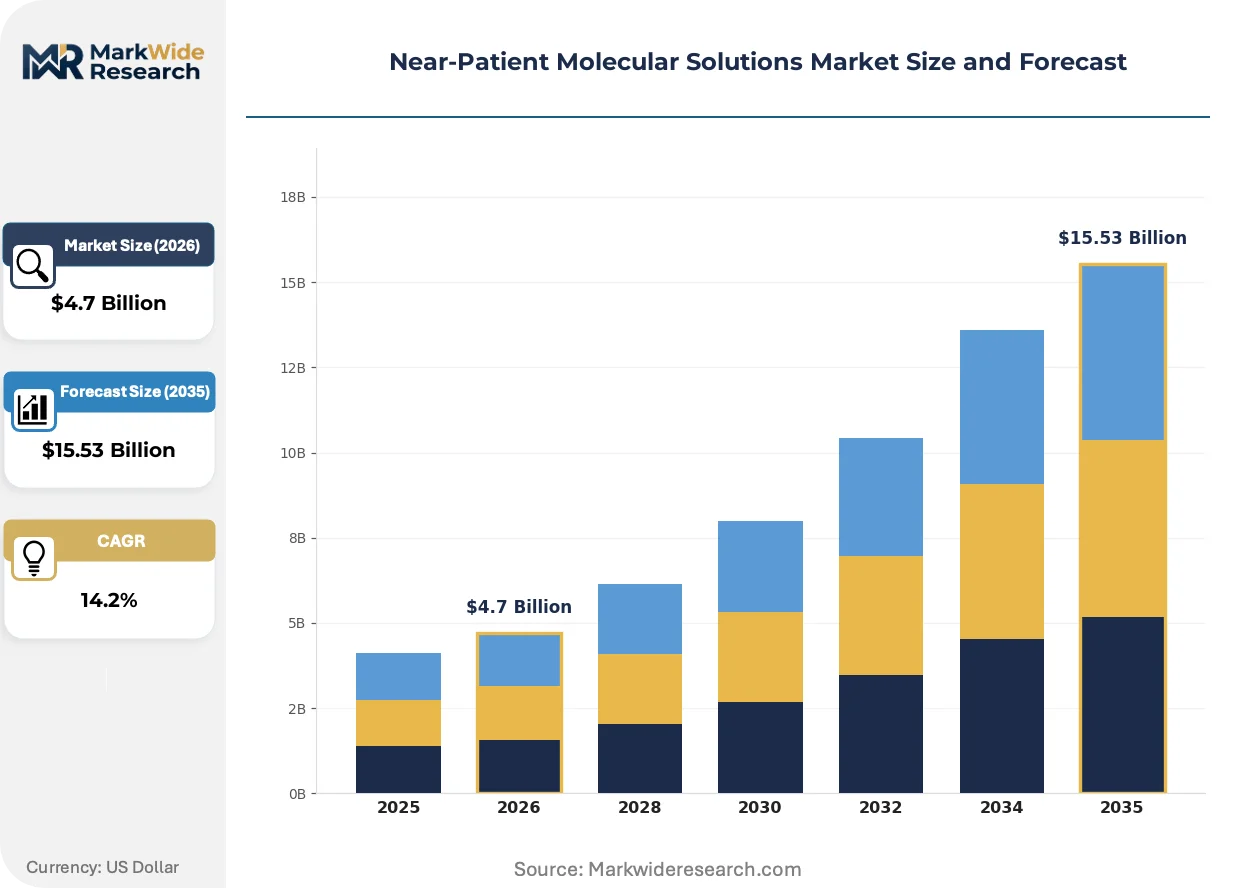
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, LAMP, NGS, Microarrays Technology: Genetic Sequencing, Biomarkers, Gene Editing, CRISPR Delivery Mode: Point-of-Care, Laboratory, Home Testing, Mobile Health End User: Clinics, Hospitals, Research Institutes, Pharmacies |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Thermo Fisher Scientific, QIAGEN, bioMérieux, Danaher, BD, Siemens Healthineers, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Near-Patient Molecular Solutions Market Shifts & Advancements
Cartridge miniaturization and integrated microfluidic architectures are compressing the boundary between central laboratory performance and point-of-care convenience, reshaping competitive differentiation around workflow integration rather than raw sensitivity specifications.
Digital PCR is rewriting the standard for absolute quantification in immunocompromised patient monitoring, where viral load precision determines prophylaxis initiation. Transplant centers and oncology units are adopting droplet-based partitioning systems at twice the pace of community hospitals. The technology is rewriting reimbursement negotiations by delivering reference-laboratory equivalence without specimen transport logistics.
EMA's In Vitro Diagnostic Medical Devices Regulation is forcing European manufacturers to recertify legacy platforms under notified body supervision, eliminating self-certification pathways for Class C infectious disease assays. The regulation is compressing the vendor landscape as smaller firms lack quality management system infrastructure for technical documentation. German and French hospital procurement consortia are responding by consolidating supplier panels to reduce compliance verification burden.
Buyers are unbundling instrument placement from consumable commitment contracts, treating platforms as interchangeable infrastructure and negotiating cartridge pricing through group purchasing organizations. This pattern concentrates volume among health systems with centralized supply chain authority, displacing direct manufacturer relationships with individual hospital laboratories. The United States exhibits the most pronounced shift, where integrated delivery networks now control seventy percent of point-of-care molecular procurement decisions.
Near-Patient Molecular Solutions Market Segmentation
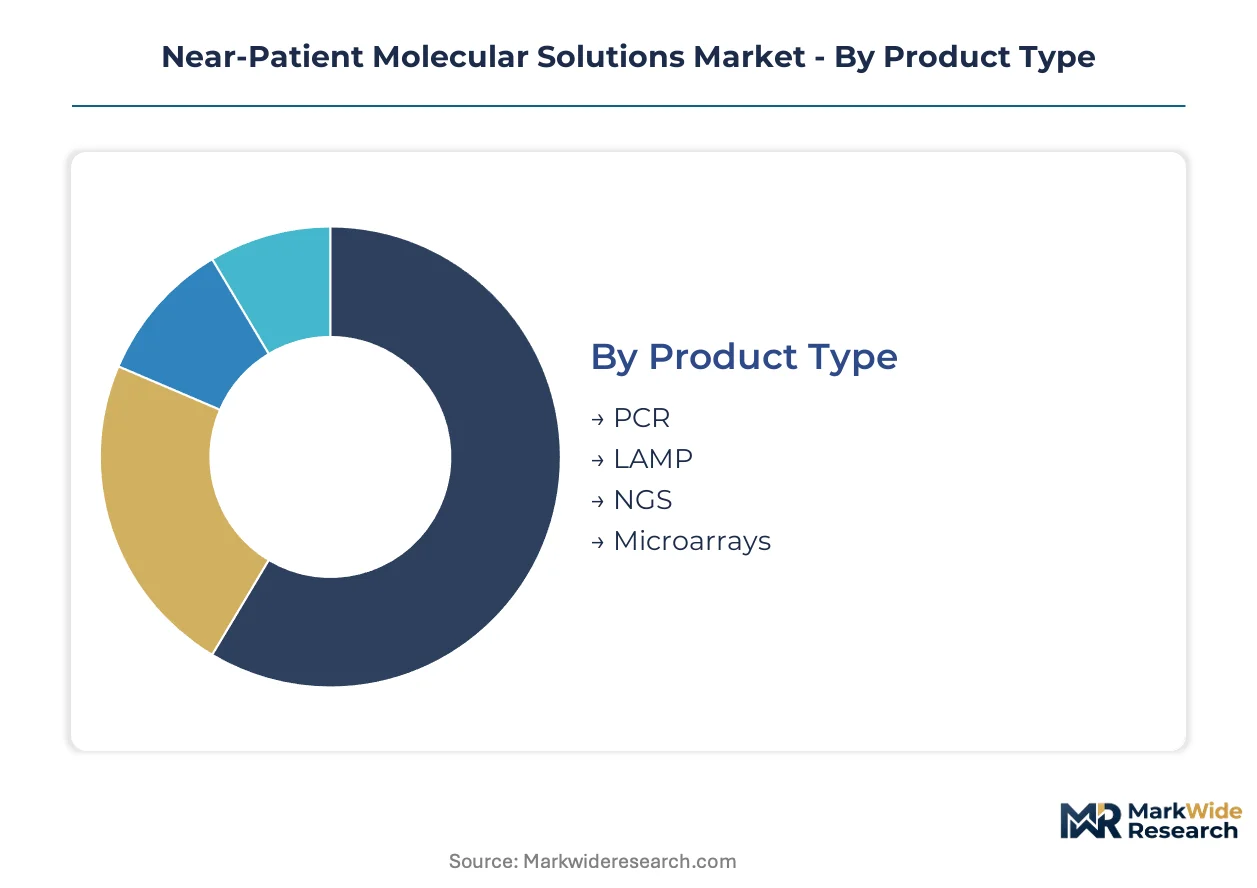
Segmentation in near-patient molecular solutions reveals how platform economics fragment across technical sophistication, deployment setting, and operator certification requirements. Understanding these divides clarifies where cartridge pull-through revenue concentrates versus where instrument placement costs dominate.
Product Type:
Standardization dominates PCR and LAMP through regulatory-cleared workflows, while NGS and microarrays retain customization for research-to-clinic translation.
- PCR:Real-time thermal cycling with fluorescence detection anchors the deepest installed base across US hospital emergency departments. Demand concentrates in integrated health systems where sixty-minute respiratory panels reduce isolation bed utilization. Abbott and Roche defend positions through proprietary optical architectures and stabilized enzyme supply chains.
- LAMP:Isothermal amplification eliminates thermal cycler infrastructure, enabling battery-operated deployment in primary care networks across India and sub-Saharan Africa. Procurement pathways favor simpler operator training and ambient-temperature reagent stability. Steepest expansion trajectory among resource-limited settings.
- NGS:Targeted amplicon sequencing bridges central laboratory accuracy with near-patient workflow compression.
- Microarrays:Solid-phase hybridization supports pharmacogenomic stratification in oncology infusion suites.
Leading the category by volume: PCR. Expanding most quickly: LAMP.
Technology:
Cost tiers separate mature genetic sequencing workflows from emerging CRISPR-based detection architectures.
- Genetic Sequencing:Sanger and next-generation platforms deliver pathogen identification with strain-level resolution for antimicrobial resistance surveillance. Hospital laboratories in Germany and France prioritize bidirectional electronic health record integration.
- Biomarkers:Protein and nucleic acid signatures enable same-day therapy selection in community cancer centers.
- Gene Editing:Engineered nucleases support research-grade assay development with clinical translation potential.
- CRISPR:Cas-mediated detection achieves single-molecule sensitivity without amplification infrastructure. US FDA breakthrough device designations accelerate review timelines for bloodstream infection panels.
Highest revenue concentration: Genetic Sequencing. Fastest regulatory pathway acceleration: CRISPR.
Delivery Mode:
Customer type stratification separates institutional procurement from contested consumer channels.
- Point-of-Care:Sample-to-answer cartridges with integrated lysis and purification command premium pricing in urgent care clinics and retail health settings. CLIA-waived complexity designations expand operator pools beyond certified laboratory personnel.
- Laboratory:Moderate-complexity platforms serve hospital satellite laboratories with higher throughput and multiplexing capacity.
- Home Testing:Patient-administered molecular diagnostics face reimbursement uncertainty as CMS has not established consistent coding. Addressable margin pools remain constrained pending coverage determinations.
- Mobile Health:Portable thermal cyclers and connectivity modules extend reach to rural and disaster-response deployments.
Deepest pricing power: Point-of-Care. Most contested margin structure: Home Testing.
End User:
Maturity gradients separate acute care throughput pressure from research-driven assay development.
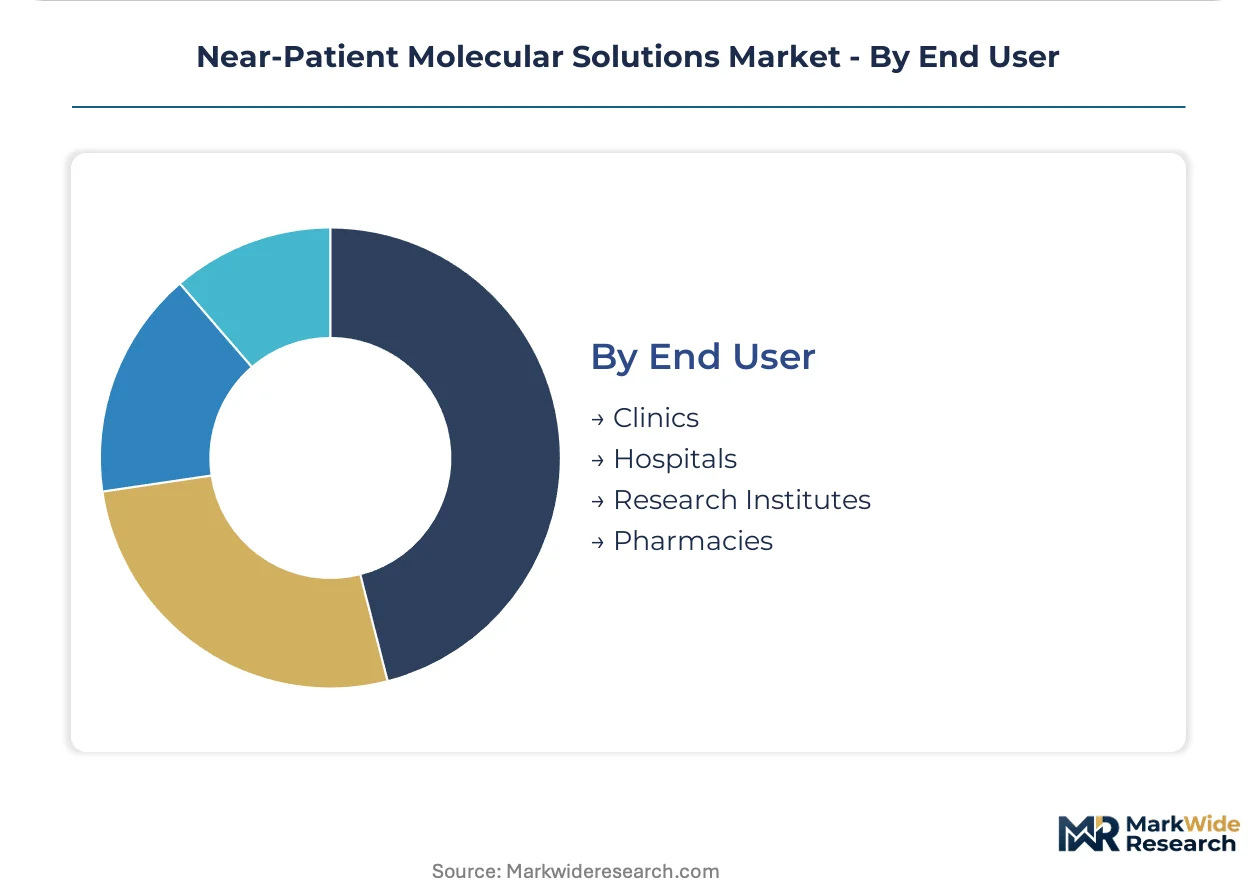
- Hospitals:Emergency departments prioritize infectious disease panels that reduce length-of-stay metrics. Integrated delivery networks in the United States control seventy percent of procurement decisions, consolidating vendor selection around cartridge economics.
- Clinics:Urgent care and retail health settings drive volume for waived-complexity respiratory platforms.
- Research Institutes:Translational programs bridge analytical validation to regulatory submission for novel biomarker panels.
- Pharmacies:Retail health expansion creates new site density for rapid streptococcal and influenza detection.
Largest volume concentration: Hospitals. Fastest site density expansion: Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate seventy percent of point-of-care molecular procurement decisions, while procurement consortia in Germany and France consolidate supplier panels under tightening EMA regulations.
United States
Hospital emergency departments prioritize sixty-minute respiratory panels to reduce isolation bed utilization and length-of-stay metrics. FDA premarket review pathways for point-of-care molecular devices shape development timelines and clinical trial investment levels. The Greater Boston cluster anchors translational programs bridging analytical validation to regulatory submission for novel biomarker panels.
Germany
Hospital procurement consortia consolidate supplier panels to reduce compliance verification burden under EMA's In Vitro Diagnostic Medical Devices Regulation. The regulation eliminates self-certification pathways for Class C infectious disease assays, compressing the vendor landscape. The Rhine-Ruhr metropolitan region concentrates quality management system infrastructure for technical documentation.
France
ANSM oversight of notified body supervision forces European manufacturers to recertify legacy platforms, favoring firms with established quality infrastructure. Hospital procurement consortia respond by consolidating supplier panels. The Paris-Saclay cluster concentrates translational research programs for antimicrobial resistance detection panels.
India
Primary care networks across India favor LAMP assays for battery-operated deployment due to simpler thermal requirements and ambient-temperature reagent stability. CDSCO regulatory pathways shape market entry timelines for multinational manufacturers. The Maharashtra-Gujarat pharmaceutical corridor concentrates contract manufacturing for stabilized enzyme supply chains.
China
NMPA regulatory frameworks govern point-of-care nucleic acid test approvals, with domestic manufacturers prioritizing CLIA-waived complexity designs for retail health expansion. The Yangtze River Delta anchors microfluidic cartridge manufacturing clusters serving regional hospital networks.
Near-Patient Molecular Solutions Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostic conglomerates defending positions through proprietary optical architectures and stabilized enzyme supply chains while mid-scale firms compete on cartridge economics. The structure concentrates around three strategic archetypes: captive supply chain operators, modular platform architects, and isothermal amplification specialists. Dominant competitive moves include backward integration into thermostable polymerase production and strategic partnerships for bidirectional electronic health record connectivity.
Among US-based diagnostic conglomerates, Abbott Laboratories and Roche Diagnostics occupy positions defined by proprietary real-time PCR optical systems and instrument pull-through revenue models. Thermo Fisher Scientific represents the modular thermal cycler architecture archetype, extending platform life cycles across clinic and hospital deployments through configurable hardware designs.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Thermo Fisher Scientific |
| QIAGEN |
| bioMérieux |
| Danaher |
| BD |
| Siemens Healthineers |
| Beckman Coulter |
| Others |
Supply & Pricing Matrix
Captive supply of stabilized enzymes anchors both the supply position and the pricing power of dominant cartridge manufacturers, insulating Abbott Laboratories and Roche Diagnostics from input cost volatility while compressing margins for second-tier competitors dependent on spot-market polymerase procurement. This backward integration into thermostable enzyme production concentrates pricing leverage among integrated diagnostic conglomerates and forces mid-scale firms to compete on cartridge economics alone.
Pricing Analysis
Volume concentrates in high-throughput hospital emergency departments where integrated delivery networks negotiate cartridge pricing through group purchasing organizations, while margins concentrate in point-of-care configurations commanding premium pricing for CLIA-waived complexity designations. Three-tier pricing structure across premium, standard, and economy levels separates proprietary optical architectures from modular thermal cycler platforms and isothermal amplification systems. Pricing pressure stems from buyers unbundling instrument placement from consumable commitments and treating platforms as interchangeable infrastructure. Retail health settings exhibit the highest price sensitivity as reimbursement frameworks for patient-administered diagnostics remain unsettled.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor hub-and-spoke patterns for reagent cartridges, with cold-chain logistics feeding hospital networks and ambient-temperature stability enabling last-mile delivery to primary care clinics. Thermostable polymerases draw from captive production facilities in the United States and contract manufacturing clusters in Maharashtra-Gujarat, while precision optical components source from German and Japanese specialty suppliers. Single-source vulnerability concentrates in stabilized enzyme supply chains where three specialty chemical suppliers dominate global output. Distribution runs through integrated health system procurement consortia and group purchasing organizations consolidating vendor panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The near-patient molecular solutions market represents a vertical-integration race where control over thermostable polymerase supply and proprietary optical architectures determines who captures cartridge pull-through revenue versus who bleeds margin on instrument placement.
For Market Incumbents: Anticipate CLIA-waived complexity designations expanding operator pools beyond certified laboratory personnel, eroding the certification moat that currently insulates premium pricing. Lock in stabilized enzyme supply through backward integration or long-term offtake agreements with Maharashtra-Gujarat contract manufacturers. Prioritize bidirectional electronic health record connectivity investments to deepen health system switching costs before middleware standardization commodifies integration capabilities. For New Entrants and Emerging Players: Community cancer center infusion suites represent the most penetrable white-space target for pharmacogenomic stratification panels, with same-day targeted therapy selection creating pull-through demand absent entrenched incumbents. Resource-limited primary care networks across India and sub-Saharan Africa offer procurement pathways for battery-operated LAMP platforms bypassing thermal cycler infrastructure requirements. Pursue FDA breakthrough device designation for antimicrobial resistance detection panels to compress regulatory timelines against slower-moving conglomerates. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated diagnostic conglomerates seeking to fill portfolio gaps in isothermal amplification or CRISPR-based detection architectures. Five-to-ten year viability hinges on sustained reimbursement expansion for multiplex respiratory panels and pharmacogenomic applications. Monitor CMS coverage determinations for patient-administered molecular diagnostics as the inflection signal separating viable home testing platforms from stranded consumer-channel investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Supply | Captive thermostable polymerase production insulates cartridge margins from input cost volatility. |
| FDA Breakthrough Device Designation | Accelerated review timelines compress development-to-revenue cycles for resistance detection panels. |
| CLIA-Waived Complexity Certification | Expands addressable site density to urgent care clinics and retail health settings beyond hospital laboratories. |
| Bidirectional EHR Connectivity Investment | Customized middleware development deepens health system switching costs and sustains instrument pull-through. |
| LAMP Platform Deployment in Primary Care | Battery-operated isothermal systems bypass thermal cycler infrastructure in India and sub-Saharan Africa. |
Research Methodology
Multi-period observation of FDA premarket submission timelines, CMS reimbursement coding decisions, and health system procurement contract structures anchored the trend analysis, supplemented by interviews with point-of-care platform engineers, hospital purchasing committee directors, GPO contracts managers, and regulatory affairs leads at diagnostic manufacturers. Secondary validation drew from FDA 510(k) and PMA filings, EMA In Vitro Diagnostic Medical Devices Regulation implementation guidance, hospital procurement databases, and CMS Medicare coverage determinations. Bottom-up triangulation across cartridge volume estimates and top-down reconciliation against instrument placement data ensured cross-verified demand quantification.
Segment-weighting across product type, delivery mode, technology, and end-user dimensions calibrated value distribution within the analytical framework, with PCR platform economics, LAMP expansion trajectories, and point-of-care versus laboratory deployment splits informing the projection model. CAGRs derived from logistic adoption curves for CLIA-waived complexity designations and health system consolidation patterns across the analysis window. Industry-specific forecast inputs incorporated stabilized enzyme supply constraints and EMA recertification timelines for legacy platform obsolescence.
Revisions become necessary when FDA guidance shifts on point-of-care nucleic acid test validation requirements, when CMS establishes or withdraws reimbursement codes for patient-administered diagnostics, or when integrated delivery network procurement consolidation accelerates beyond modeled health system concentration thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market