
 Hepatitis C Diagnosis and Treatment Market | 2026-2036
Hepatitis C Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis C Diagnosis and Treatment Market Outlook
Software-defined diagnostic algorithms embedded in polymerase chain reaction platforms is broadening what laboratories sell beyond test kits to subscription-based interpretive services. Gilead Sciences Inc leverages its nucleotide analogue portfolio to sustain dominance in direct-acting antiviral regimens. AbbVie Inc anchors its position through pangenotypic combination therapies that compete across genotype-agnostic prescribing. F. Hoffmann-La Roche Ltd differentiates with integrated cobas systems that control workflow automation from sample to result.
Hepatitis C diagnosis and treatment encompasses nucleic acid amplification testing, serological antibody detection, and interferon-free direct-acting antiviral therapy designed to achieve sustained virologic response through targeted inhibition of NS3/4A protease, NS5A replication complex, and NS5B polymerase enzymes. Its commercial purpose centers on eliminating HCV RNA from patient serum to prevent cirrhosis progression and hepatocellular carcinoma. Direct-acting antivirals command the largest margin pool as oral pangenotypic regimens displace interferon-based protocols with superior tolerability profiles. Polymerase chain reaction testing leads diagnostic technology revenue due to quantitative HCV RNA confirmation requirements, while rapid tests expand point-of-care access in resource-limited settings. Homecare settings represent the fastest-growing delivery channel as oral antiviral simplicity enables decentralized treatment initiation.
FDA clearance pathways for breakthrough-designated antivirals and WHO prequalification standards for generic direct-acting antivirals shape product entry timelines and procurement eligibility across national programs. EMA's orphan drug incentives and REACH compliance for diagnostic reagent manufacturing add layered compliance costs that favor scaled suppliers over emerging entrants. Stakeholders must monitor patent cliff dynamics for sofosbuvir-based combinations and the pace of national hepatitis elimination program funding renewals to anticipate volume shifts between originator and generic procurement channels.
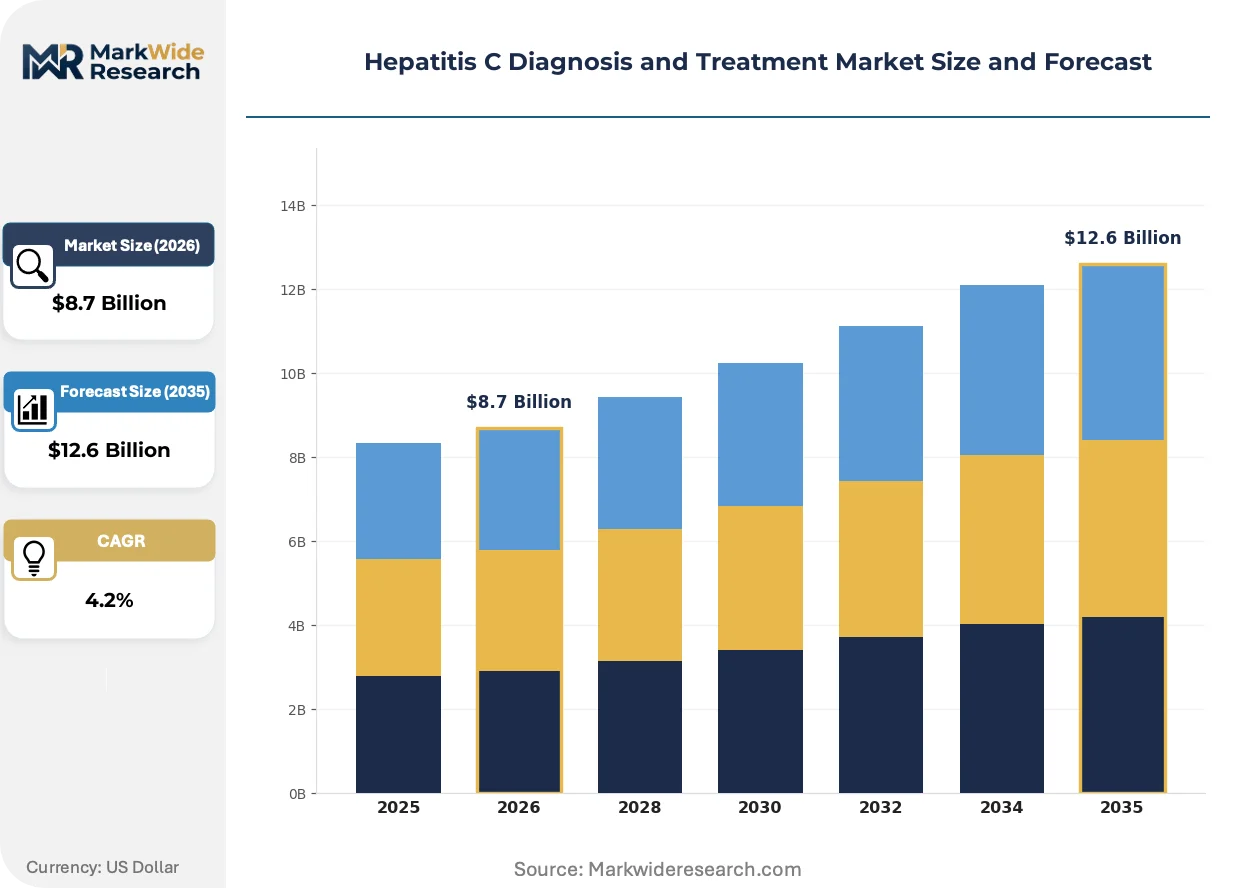
Market Dynamics
Patent expiration for sofosbuvir-based regimens is redistributing procurement volume from originator to generic channels, compressing average selling prices while expanding treated patient populations through national elimination programs.
Growth Catalysts
- Medicaid Expansion:United States state-level coverage mandates for HCV screening in correctional facilities and safety-net hospitals are generating diagnostic volume that feeds downstream antiviral demand.
- WHO Prequalification:Streamlined approval pathways for generic direct-acting antivirals enable procurement eligibility across low- and middle-income national hepatitis programs.
- Point-of-Care Molecular Platforms:Portable nucleic acid amplification systems are decentralizing RNA confirmation testing from centralized laboratories to community health settings.
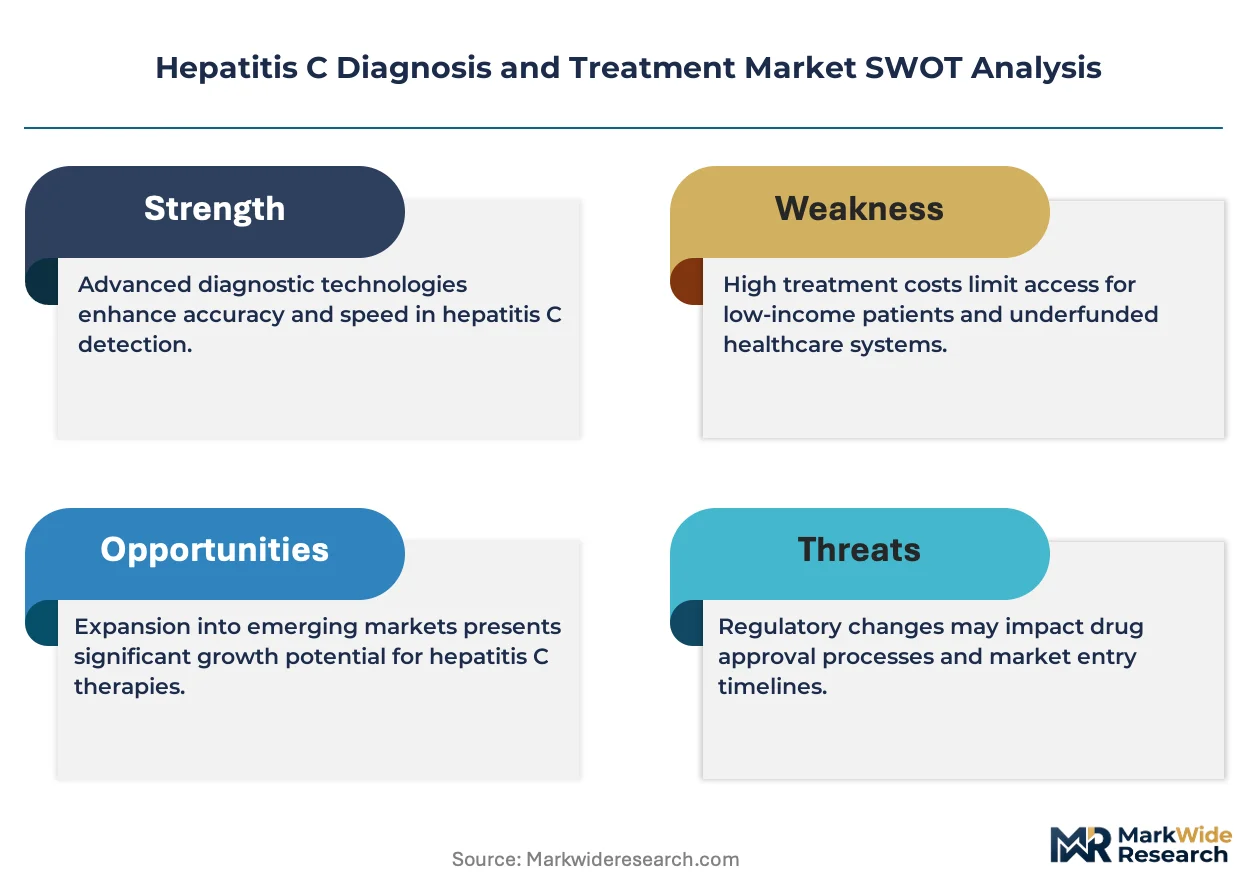
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Sofosbuvir and velpatasvir manufacturing concentrates among Indian and Chinese contract manufacturers, creating supply vulnerability to export restriction shocks.
- Reagent Cold Chain Requirements:Polymerase chain reaction diagnostic kits require sustained refrigerated transport, limiting distribution reach to rural and resource-limited geographies lacking temperature-controlled logistics infrastructure.
- Interferon Legacy Protocols:Some national treatment guidelines retain pegylated interferon eligibility criteria that delay access to modern pangenotypic regimens in public procurement channels.
Strategic Opportunities
- Prison Health Programs:United States state correctional systems represent underpenetrated screening and treatment channels where oral antiviral simplicity enables therapy completion during incarceration periods.
- Subscription-Based Interpretive Services:Software-defined diagnostic algorithms embedded in PCR platforms allow laboratories to monetize genotype resistance analysis beyond commodity test kit sales.
- Homecare Treatment Initiation:Oral pangenotypic regimens eliminate infusion requirements, enabling decentralized prescription and monitoring through telemedicine-connected primary care networks.
Industry Challenges
- Virology Specialist Shortage:Hepatology and infectious disease fellowship programs produce insufficient clinicians to manage elimination program scale-up targets, forcing task-shifting to primary care providers with limited HCV expertise.
- Resistance-Associated Substitution Complexity:NS5A resistance polymorphisms require genotype-specific regimen selection that complicates prescribing in settings lacking sequencing capacity, creating treatment failure risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis C Diagnosis and Treatment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Direct-acting Antivirals, Interferon, Ribavirin Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Diagnostic Laboratories, Homecare Settings Testing Technology: Polymerase Chain Reaction, Antigen Tests, Serological Tests, Rapid Tests |
| Companies Covered | F. Hoffmann-La Roche Ltd, Cipla Inc, Gilead Sciences Inc, Biocon, LAURUS Labs, AbbVie Inc, Bristol Myers Squibb Company, NATCO Pharma Limited, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis C Diagnosis and Treatment Market Strategic Shifts
Digital integration of diagnostic workflows with treatment decision support is compressing the time from RNA detection to antiviral initiation, reshaping how laboratories and pharmacies coordinate patient pathways.
Next-generation sequencing is expanding into HCV resistance profiling, replacing Sanger-based subtyping in academic medical centers and reference laboratories. Large health systems in California and Texas are adopting these platforms to guide retreatment decisions after direct-acting antiviral failure. The technology is expanding into routine surveillance of NS3/4A, NS5A, and NS5B mutation patterns that inform national resistance databases.
EMA's orphan drug incentives and pediatric investigation plan requirements are accelerating development of pangenotypic regimens for adolescent and pediatric populations previously excluded from standard approvals. Manufacturers must submit juvenile toxicology data and weight-based dosing pharmacokinetics to satisfy paediatric-use marketing authorisation conditions. European reference networks for rare liver diseases are coordinating multicenter trials that aggregate sufficient patient numbers across France, Germany, and Italy.
Bundled procurement contracts are consolidating diagnostic and therapeutic purchasing across integrated delivery networks, displacing separate vendor relationships for laboratories and specialty pharmacies. United States health systems in Florida and Pennsylvania are negotiating multi-year sole-source agreements that lock in PCR testing volumes alongside antiviral allocation commitments. This concentration of purchasing authority favors suppliers offering integrated sample-to-result automation with inventory management software.
Hepatitis C Diagnosis and Treatment Market Segmentation
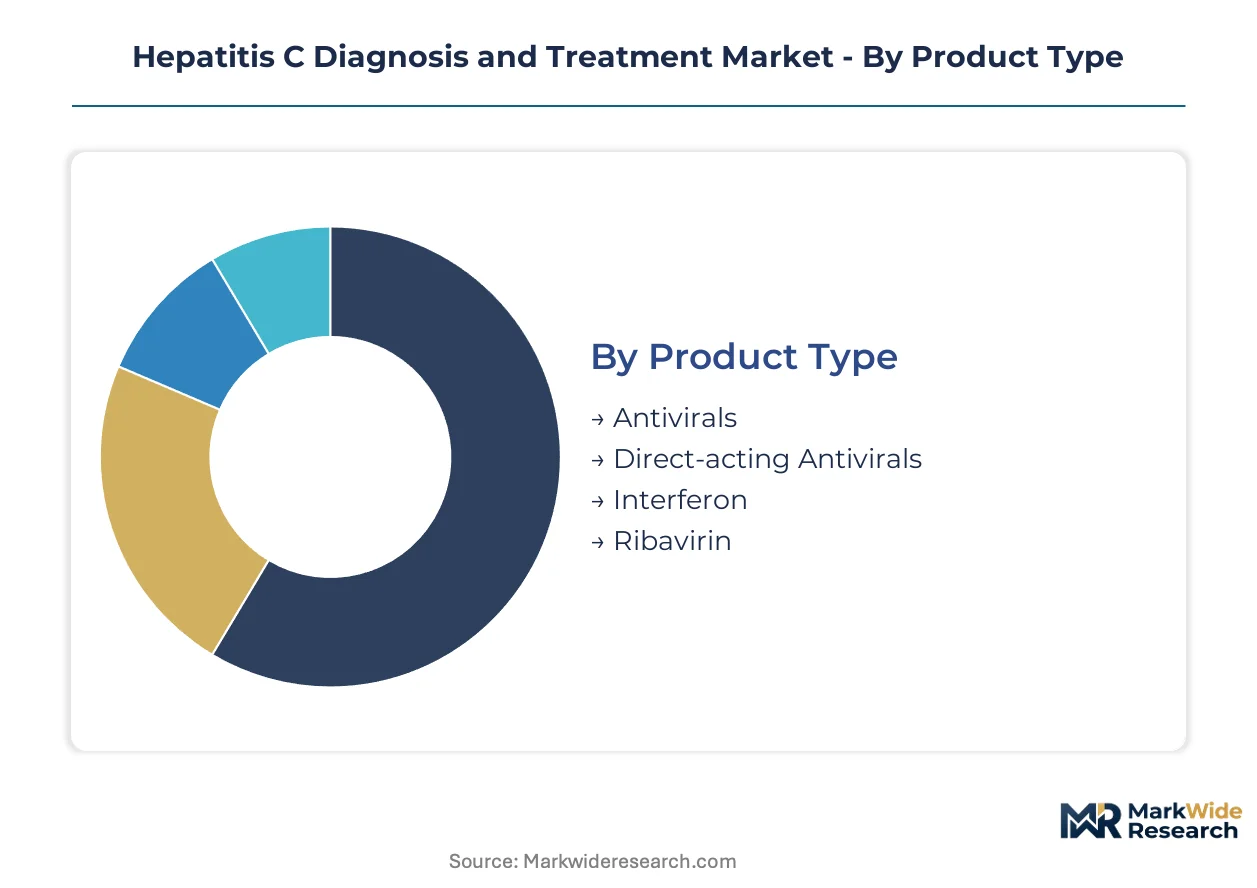
Hepatitis C market segmentation reflects divergent capital requirements across therapeutic manufacturing versus diagnostic platform deployment. Procurement patterns fragment between high-margin antiviral regimens and volume-driven testing infrastructure.
Product Type:
Capital intensity peaks with nucleotide analogue synthesis facilities requiring specialized containment and purification systems.
- Direct-acting Antivirals:NS3/4A protease inhibitors, NS5A replication complex inhibitors, and NS5B polymerase inhibitors formulated as fixed-dose combinations. Demand concentrates in United States Medicaid programs and European national health services where pangenotypic regimens displace legacy protocols. WHO prequalification for generic versions is expanding procurement eligibility across low- and middle-income elimination programs.
- Antivirals:Broad-spectrum viral suppression agents including nucleoside analogues with activity against multiple hepatitis viruses. Manufacturing requires fermentation capacity and downstream processing investment that favors scaled pharmaceutical producers.
- Interferon:Pegylated alpha interferons for retreatment scenarios and genotype 3 salvage therapy. Cold chain distribution and subcutaneous administration requirements limit adoption to specialized hepatology centers retaining legacy protocol eligibility.
- Ribavirin:Nucleoside analogue adjunct therapy used in combination with direct-acting antivirals for specific resistance patterns. Generic manufacturing concentrates among Indian contract producers supplying national elimination programs.
Direct-acting antivirals absorb the bulk of installed capacity; direct-acting antivirals are expanding most quickly as pangenotypic regimens capture prescriber preference.
Delivery Mode:
Route selection determines distribution infrastructure requirements and patient adherence monitoring complexity.
- Oral:Once-daily tablet formulations enabling decentralized therapy initiation without infusion infrastructure. United States prison health programs and European primary care networks drive volume as task-shifting reduces specialist dependency.
- Injectable:Subcutaneous pegylated interferon requiring cold chain maintenance and clinical supervision. Demand persists in retreatment protocols and settings with NS5A resistance polymorphisms.
- Intravenous:Hospital-administered formulations for acute hepatitis C management and peri-transplant prophylaxis. Academic medical centers in Germany and France maintain utilization for immunocompromised patient populations.
- Transdermal:Emerging delivery systems for interferon alternatives under investigation in pediatric investigation plans. EMA orphan drug incentives accelerate development timelines for adolescent populations.
Oral formulations command the highest margin pool; oral delivery is climbing the fastest as elimination programs prioritize adherence simplicity.
End User:
Site-of-care selection reflects workforce availability and reimbursement pathway differentiation.
- Diagnostic Laboratories:Centralized nucleic acid amplification testing with automated sample-to-result workflow. United States commercial laboratories and European hospital networks invest in integrated cobas systems controlling throughput capacity.
- Homecare Settings:Telemedicine-connected prescription and monitoring for oral antiviral completion. Medicaid expansion in United States safety-net programs and United Kingdom community pharmacy pilot programs accelerate deployment.
- Hospitals:Inpatient initiation for decompensated cirrhosis and hepatocellular carcinoma surveillance. Liver transplant centers in Spain and Italy maintain specialized hepatology units for complex retreatment decisions.
- Clinics:Federally qualified health centers and community health settings performing point-of-care rapid testing. California and Texas health systems adopt portable molecular platforms for same-day RNA confirmation.
Diagnostic laboratories absorb the bulk of installed capacity; homecare settings are gaining share fastest as oral therapy eliminates infusion requirements.
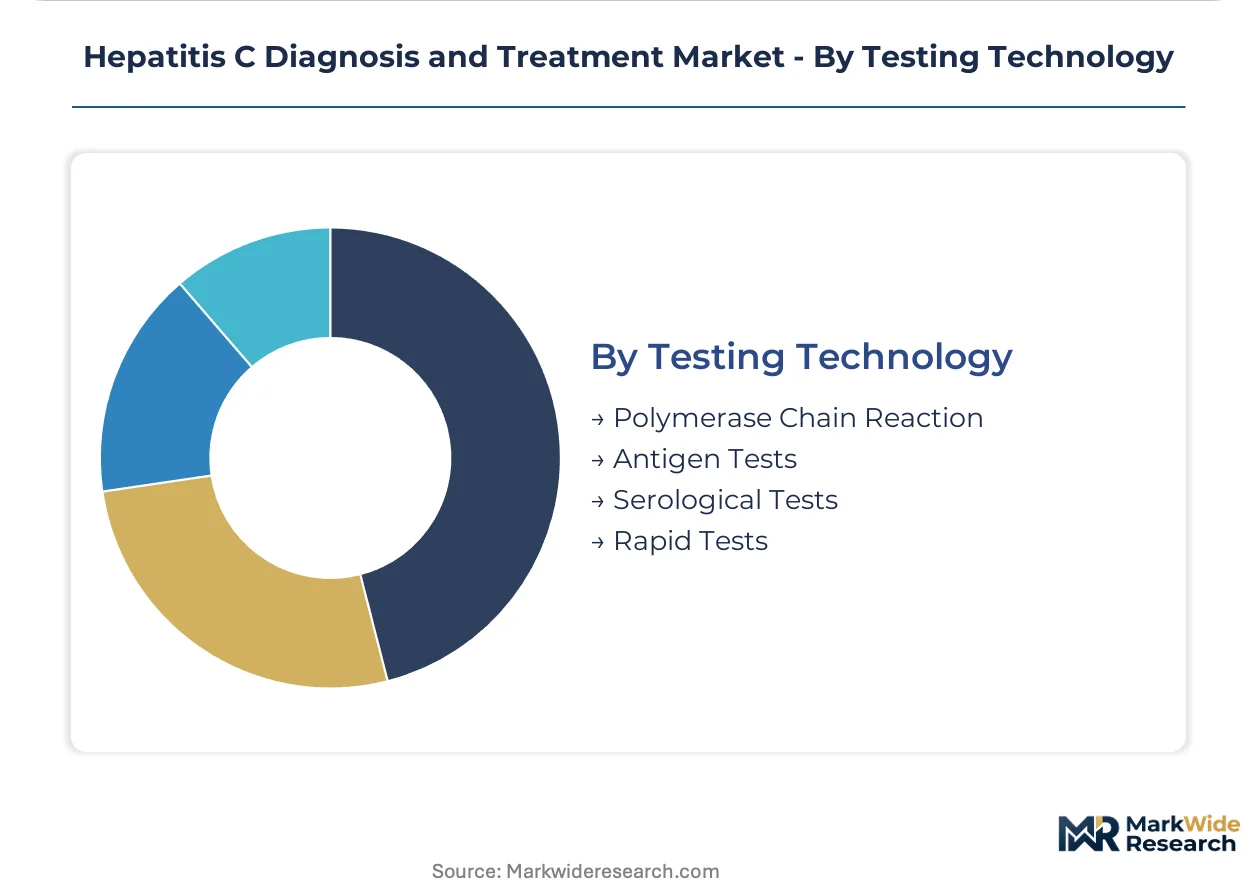
Testing Technology:
Platform selection balances sensitivity requirements against cold chain logistics and capital deployment.
- Polymerase Chain Reaction:Quantitative HCV RNA detection with genotype and resistance subtyping capabilities. Academic medical centers in California and Texas deploy next-generation sequencing for NS3/4A, NS5A, and NS5B mutation surveillance.
- Rapid Tests:Point-of-care antibody detection for screening expansion in resource-limited settings. WHO prequalification enables procurement across African and Southeast Asian national blood safety programs.
- Serological Tests:Enzyme immunoassay antibody screening in centralized laboratory workflows. European reference networks coordinate multicenter validation for rare liver disease surveillance.
- Antigen Tests:Core protein detection for early infection window period identification. Blood collection facilities in Japan and South Korea integrate antigen screening with nucleic acid testing for transfusion safety.
Polymerase chain reaction absorbs the bulk of installed capacity; rapid tests are expanding most quickly as point-of-care molecular platforms decentralize access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotechnology corridor anchors North American hepatitis C research activity, while procurement volume concentrates across Medicaid expansion states and European national health services. Regulatory pathways in multiple jurisdictions are reshaping generic entry timelines and diagnostic platform deployment.
United States
Medicaid expansion in California and Texas drives screening volume through correctional facilities and federally qualified health centers. FDA breakthrough-designated antiviral pathways compress approval timelines for pangenotypic regimens. The Liver Institute at Methodist Dallas and Houston's Texas Medical Center anchor retreatment protocol development for NS5A resistance patterns.
Germany
Academic medical centers in Berlin and Hamburg maintain specialized hepatology units for decompensated cirrhosis management. EMA orphan drug incentives accelerate pediatric investigation plans for adolescent populations. The Ruhr region's hospital networks coordinate multicenter trials through European reference networks for rare liver diseases.
India
Contract manufacturing of sofosbuvir active pharmaceutical ingredients concentrates in Hyderabad and Ahmedabad production zones. CDSCO streamlined approval pathways enable WHO prequalification for generic direct-acting antivirals. Mumbai's diagnostic laboratories expand molecular testing capacity for national elimination program procurement.
Japan
Blood collection facilities in Tokyo and Osaka integrate antigen screening with nucleic acid testing for transfusion safety protocols. PMDA accelerated review pathways support next-generation sequencing adoption for resistance profiling. Kansai region medical centers lead surveillance of NS3/4A and NS5B mutation patterns.
France
Parisian hospital networks coordinate pangenotypic regimen distribution through national health service procurement channels. ANSM pediatric-use marketing authorisation conditions drive weight-based dosing pharmacokinetics submissions. Lyon and Marseille academic centers aggregate retreatment trial data across European reference networks.
Hepatitis C Diagnosis and Treatment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the hepatitis C value chain. The therapeutic segment consolidates around nucleotide analogue patent holders and pangenotypic formulation specialists, while diagnostic platforms fragment across integrated automation suppliers and point-of-care molecular innovators. Three archetypes dominate: originator pharmaceutical manufacturers defending regimen portfolios, generic API synthesizers capturing elimination program volume, and integrated diagnostic-therapeutic bundlers. Competitive moves concentrate on patent cliff navigation through authorized generic launches and laboratory-pharmacy procurement consolidation across integrated delivery networks.
Among originator-tier anchors, Gilead Sciences Inc and AbbVie Inc exemplify pangenotypic regimen developers with nucleotide analogue and combination therapy positioning. F. Hoffmann-La Roche Ltd occupies the integrated diagnostic archetype through sample-to-result automation platforms. These three represent the dominant competitive positions: therapeutic originators with direct-acting antiviral portfolios, and diagnostic-therapeutic integrators controlling workflow automation from RNA detection to treatment initiation.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Cipla Inc |
| Gilead Sciences Inc |
| Biocon |
| LAURUS Labs |
| AbbVie Inc |
| Bristol Myers Squibb Company |
| NATCO Pharma Limited |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up diagnostic laboratory chains anchor procurement consolidation across United States Medicaid expansion states, tightening pricing discipline on reagent suppliers while funneling volume toward integrated automation platforms that bundle testing workflows with antiviral allocation commitments.
Pricing Analysis
Sustained virologic response guarantees anchor value-based contracting for pangenotypic regimens in United States correctional health programs and European national health services. Pricing stratifies across originator, authorized generic, and unbranded generic tiers differentiated by FDA breakthrough designation status and WHO prequalification eligibility. Cost compression in unbranded generic channels intensifies as Indian and Chinese contract manufacturers expand active pharmaceutical ingredient capacity. Medicaid programs exhibit highest price sensitivity; private integrated delivery networks demonstrate lowest sensitivity due to bundled procurement consolidation.
Supply Chain Analysis
Cold chain logistics costs constrain polymerase chain reaction reagent distribution to rural geographies lacking temperature-controlled infrastructure. Active pharmaceutical ingredient synthesis concentrates in India, China, and Switzerland, drawing from specialized fermentation capacity and nucleotide analogue purification systems. Supply chain vulnerability rests on export restriction exposure for sofosbuvir and velpatasvir intermediates. Distribution runs through national health service procurement channels in Europe and Medicaid-managed care organizations in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hepatitis C market operates as a vertical-integration race where diagnostic-therapeutic bundling determines procurement access, with laboratories and specialty pharmacies consolidating under single vendor relationships to capture elimination program volume.
For Market Incumbents: Cement formulary position through authorized generic launches ahead of patent cliff exposure for sofosbuvir-based combinations. Deepen backward integration into nucleotide analogue synthesis to insulate margin pressure from Indian contract manufacturer competition. Lock in multi-year sole-source agreements with United States integrated delivery networks in Florida and Pennsylvania.
For New Entrants and Emerging Players: Portable nucleic acid amplification platforms offer a technology-first wedge into point-of-care molecular testing gaps across California and Texas community health settings. Target prison health programs as the most penetrable channel where oral antiviral simplicity enables therapy completion during incarceration periods. Pursue WHO prequalification pathways to unlock procurement eligibility across low- and middle-income national elimination programs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor diagnostic platform specialists with embedded software-defined algorithms in United States commercial laboratory networks. Long-term viability hinges on subscription-based interpretive services monetization rather than commodity test kit sales. Watch patent litigation settlements between originator and generic manufacturers as the inflection signal for procurement channel rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Bundling | United States health systems in Florida consolidate PCR testing volumes with antiviral allocation commitments. |
| Authorized Generic Launch | Gilead Sciences defends market position ahead of sofosbuvir patent expiration through preemptive channel strategy. |
| Point-of-Care Molecular Platform Deployment | California community health settings adopt portable RNA confirmation systems for same-day treatment initiation. |
| Backward Integration into API Synthesis | AbbVie secures captive supply of NS5A replication complex inhibitors to reduce contract manufacturer dependency. |
| WHO Prequalification Pathway | Indian generic manufacturers unlock procurement eligibility across African national hepatitis elimination programs. |
Study Parameters
Independent corroboration across formulary directors at United States Medicaid programs, regulatory affairs leads at EMA, and procurement managers at European national health services underwrites the qualitative findings. Primary interviews with drug development executives at pangenotypic regimen developers, hospital purchasing committees at academic medical centers in Germany and France, and GPO contracts managers at United States integrated delivery networks combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare data. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation cross-check segmentation outputs.
Rate-of-change decomposition separates volume growth from price erosion dynamics across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, testing technology, and regional regulatory cluster. CAGRs derive from patient population epidemiology, treatment initiation rates, and procurement channel shift assumptions. Forecast inputs incorporate WHO hepatitis elimination program funding renewals and patent expiration timelines for sofosbuvir-based combinations.
Several conditions sit outside the modeled scope, including geopolitical export restrictions on active pharmaceutical ingredients and pandemic-related disruptions to clinical trial enrollment. Forecasts reflect documented assumptions about sustained virologic response rates and national elimination program commitment durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market