
 Thailand Telecom Market | 2026-2036
Thailand Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Telecom Market Outlook
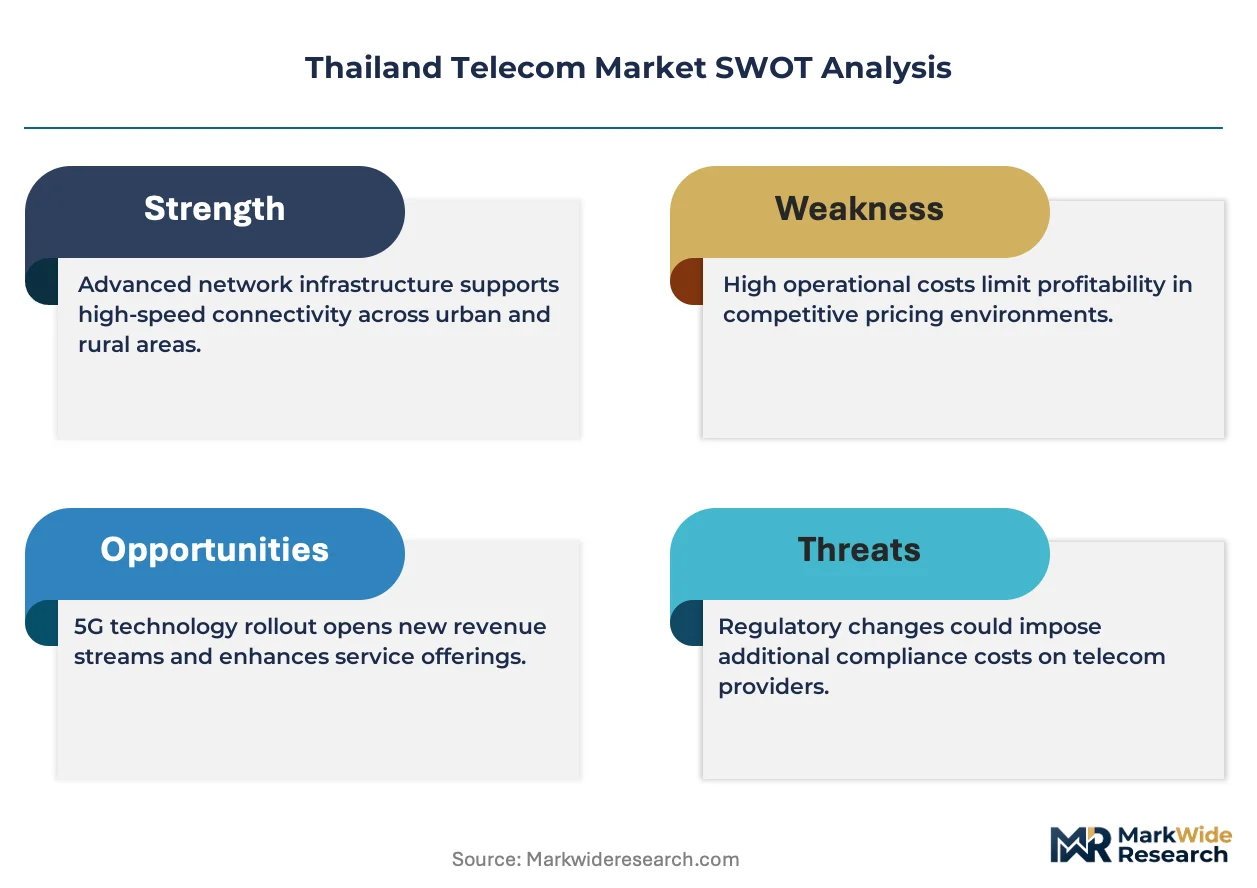
Multi-vendor network equipment sourcing is broadening across Thai operators as 5G rollout complexity rises. Advanced Info Service PCL anchors its position through deep R&D investment in millimeter-wave infrastructure. True Corp Public Company Ltd leverages its converged fixed-mobile platform to control enterprise wallet share. Jasmine International PCL competes aggressively on wholesale fiber access pricing to extend its provincial footprint.
Thailand telecom encompasses the design, deployment, and commercial operation of wireless and wireline communication infrastructure delivering voice, data, and video services at frequencies ranging from sub-1 GHz to 28 GHz and fiber transmission speeds exceeding 10 Gbps. Its primary purpose is enabling real-time information exchange for consumer, enterprise, and government end-users across geographically dispersed locations. Mobile data services generate the dominant revenue pool as video consumption and IoT connectivity expand, while fiber optic infrastructure represents the fastest-growing technology segment due to government-mandated national broadband targets. The residential customer segment remains volume-heavy, though large enterprise accounts command superior margins through customized service-level agreements and dedicated network slicing.
The National Broadcasting and Telecommunications Commission governs spectrum licensing and interconnection rules, directly shaping operator capital allocation and service pricing floors. The Personal Data Protection Act, enforced by Thailand's data protection authority, imposes stringent customer data handling standards that elevate compliance costs for cloud service bundling. Stakeholders must monitor spectrum auction timing and data localization enforcement to calibrate infrastructure investment cycles against regulatory uncertainty.
Market Dynamics
The National Broadcasting and Telecommunications Commission's 5G spectrum allocation mandates are compressing infrastructure deployment timelines while forcing operators to accelerate multi-vendor sourcing strategies. This regulatory pressure is reshaping capital allocation across fixed and wireless networks simultaneously.
Growth Catalysts
- Enterprise Cloud Migration:Thai manufacturers are accelerating adoption of cloud-based unified communications platforms. Factory automation and remote operations management are driving dedicated fiber and 5G private network contracts.
- National Broadband Policy:Government-mandated national broadband targets are channeling public investment into fiber optic backbone extension. Provincial coverage obligations are creating wholesale access opportunities for secondary operators.
- Millimeter-Wave Infrastructure:Dense urban corridors in Bangkok and the eastern seaboard industrial zones are enabling high-capacity small cell deployments. Manufacturing clusters and logistics hubs are absorbing premium connectivity services at scale.
Market Restraints
- Input Cost Volatility:Optical transceiver and baseband unit component costs fluctuate with semiconductor foundry capacity constraints. Equipment lead times from East Asian suppliers extend network rollout schedules unpredictably.
- Supply Concentration Risk:Critical radio access network equipment depends on a narrow base of Northeast Asian vendors. Thai operators face limited alternatives for massive MIMO antenna arrays and core network software.
- Data Localization Compliance:The Personal Data Protection Act imposes stringent customer data handling standards. Cloud service bundling costs escalate due to mandatory local storage infrastructure and audit requirements.
Strategic Opportunities
- Provincial Fiber Extension:Underpenetrated northeastern and northern provinces present wholesale access growth corridors. Secondary cities outside Bangkok's metropolitan zone lack competitive fixed-line alternatives.
- Network Slicing for Industry:Converged 5G and edge computing platforms enable customized service-level agreements for automotive and electronics manufacturers. Dedicated virtual networks support quality-of-service guarantees for robotic process automation.
- Eastern Economic Corridor:The government's special economic zone incentives are concentrating foreign direct investment in advanced manufacturing. Deep-water port connectivity and industrial estate development are synchronizing with telecom infrastructure planning.
Industry Challenges
- Millimeter-Wave Engineering Talent:Specialized radio frequency design and propagation modeling skills remain scarce in the domestic labor market. Operators compete with regional peers for experienced network optimization engineers.
- Legacy System Integration:Existing circuit-switched voice infrastructure and older IP multimedia subsystem cores resist seamless migration to cloud-native architectures. Interoperability testing consumes disproportionate deployment resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Telecom Market |
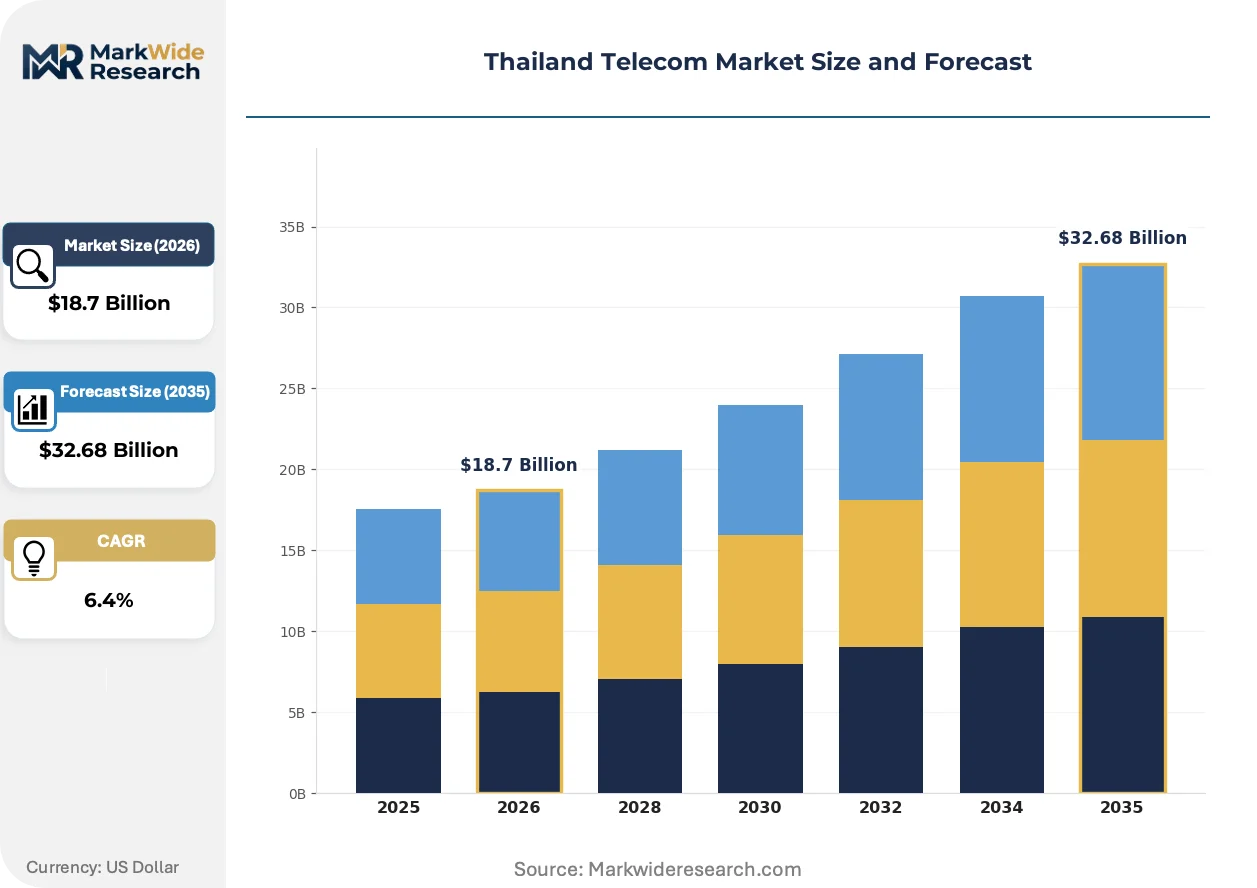
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Voice, Mobile Data, Fixed Line, Broadband Customer Type: Residential, SME, Large Enterprise, Government Technology: 4G, 5G, Fiber Optic, Satellite Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Resellers |
| Companies Covered | Total Access Communication Public Company Ltd, Jasmine Telecom Systems Public Company Ltd, Advanced Info Service PCL, Samart Corp Public Company Ltd, National Telecom, True Corp Public Company Ltd, Jasmine International PCL, Forth Smart Service Public Company Ltd, Intouch Holdings Public Company Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Telecom Market Strategic Shifts
Open radio access network architectures are disrupting traditional vendor lock-in patterns across Thai mobile infrastructure procurement. Equipment disaggregation is enabling multi-vendor interoperability while compressing total cost of ownership for dense urban deployments.
Virtualized radio access network technology is expanding into metropolitan 5G densification projects. Mobile operators in Bangkok are disaggregating hardware and software layers to mix specialized vendors for radio units and baseband processing. This architectural shift is enabling faster feature deployment cycles and reducing single-source dependency for millimeter-wave infrastructure.
The National Broadcasting and Telecommunications Commission's spectrum auction timing and coverage obligations are accelerating infrastructure sharing agreements among operators. Mandatory rural coverage benchmarks are forcing collaborative tower and fiber deployments in provincial zones. Competitive dynamics are shifting from infrastructure ownership toward service differentiation and enterprise solution bundling.
Enterprise buyers in manufacturing and logistics are consolidating telecommunications procurement under converged fixed-mobile contracts. Single-vendor relationships for fiber, mobile, and cloud services are displacing fragmented supplier management. This concentration pattern is most visible among automotive and electronics producers in the eastern seaboard industrial corridor, where integrated connectivity platforms support factory automation and supply chain visibility requirements.
Thailand Telecom Market Segmentation
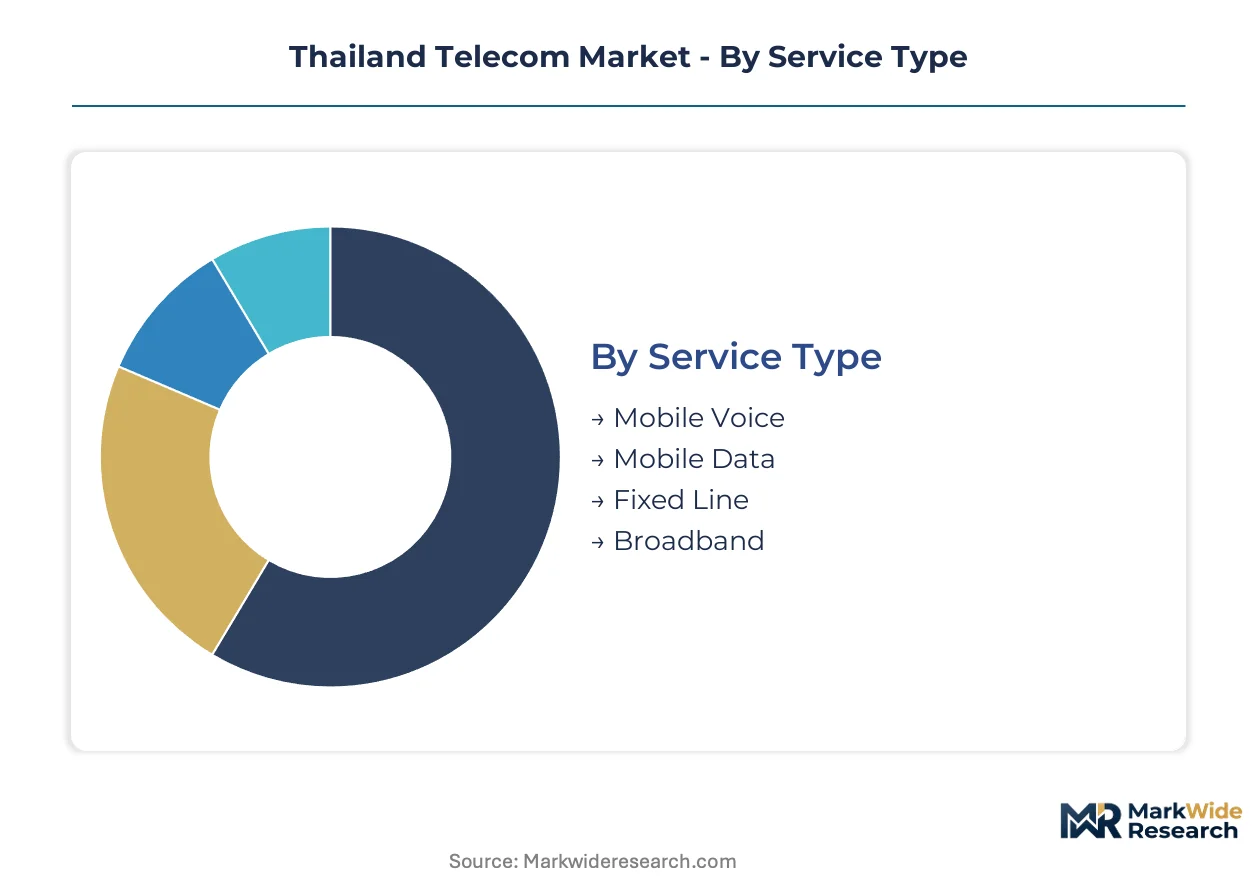
Thailand's telecom market fragments across service delivery modes, customer scale, and infrastructure generations. Understanding these divides clarifies where capital concentrates and which technology transitions reshape competitive positioning.
Service Type:
Revenue pools diverge sharply between legacy voice circuits and packet-based data transmission.
- Mobile Voice:Circuit-switched and VoLTE calling remains embedded in consumer subscription bundles. Declining average revenue per user compresses standalone voice profitability, though regulatory universal service obligations sustain rural coverage requirements.
- Mobile Data:LTE and 5G packet services absorb the majority of consumer wallet share as video streaming and social platform usage intensify. Bangkok metropolitan corridor and eastern seaboard industrial zones exhibit the highest per-capita consumption volumes.
- Fixed Line:Traditional copper-based PSTN infrastructure persists in provincial zones where fiber overbuild economics remain marginal. Legacy circuit demand concentrates among older demographic segments and small commercial establishments.
- Broadband:Fiber-to-the-home and cable modem services deliver residential and SME internet access. National broadband policy targets are accelerating provincial fiber extension beyond Bangkok's core metropolitan area.
Mature deployment sits with Fixed Line. Newer deployment is concentrated in Mobile Data.
Customer Type:
Margin structures invert between high-volume residential subscriptions and customized enterprise contracts.
- Residential:Mass-market consumers purchase standardized prepaid and postpaid bundles with limited service-level differentiation. Price sensitivity drives churn, compressing operator margins despite substantial subscriber counts.
- SME:Small and medium enterprises procure converged fixed-mobile packages with basic cloud service attachments. Provincial manufacturing clusters and retail corridors outside Bangkok represent underpenetrated expansion zones.
- Large Enterprise:Multinational manufacturers and logistics operators negotiate dedicated network slicing and private 5G deployments. Eastern Economic Corridor automotive and electronics facilities command premium connectivity with guaranteed quality-of-service terms.
- Government:Public sector procurement spans municipal broadband, emergency communications, and national security networks. Smart city initiatives in Bangkok and secondary provincial capitals are expanding infrastructure-as-a-service contracts.
Volume leadership rests with Residential. Margin expansion is concentrated in Large Enterprise.
Technology:
Spectrum allocation and fiber densification timelines determine competitive access economics.
- 4G:LTE infrastructure at 1800 MHz and 2100 MHz delivers baseline mobile broadband across provincial Thailand. Sub-6 GHz propagation characteristics enable cost-effective rural coverage compliance.
- 5G:New radio deployments at 700 MHz, 2.6 GHz, and 26 GHz support enhanced mobile broadband and ultra-reliable low-latency applications. Millimeter-wave small cells concentrate in Bangkok's central business district and eastern seaboard industrial estates.
- Fiber Optic:GPON and XGS-PON architectures transmit at 10 Gbps and beyond across national backbone and last-mile access networks. Government-mandated coverage targets are accelerating provincial extension into northeastern and northern provinces.
- Satellite:Geostationary and emerging low-earth orbit systems serve maritime, aviation, and remote terrestrial locations outside fiber and cellular footprints. Deep-water port operations and island tourism corridors absorb specialized connectivity services.
Installed base dominance sits with 4G. Steepest expansion trajectory is concentrated in Fiber Optic.
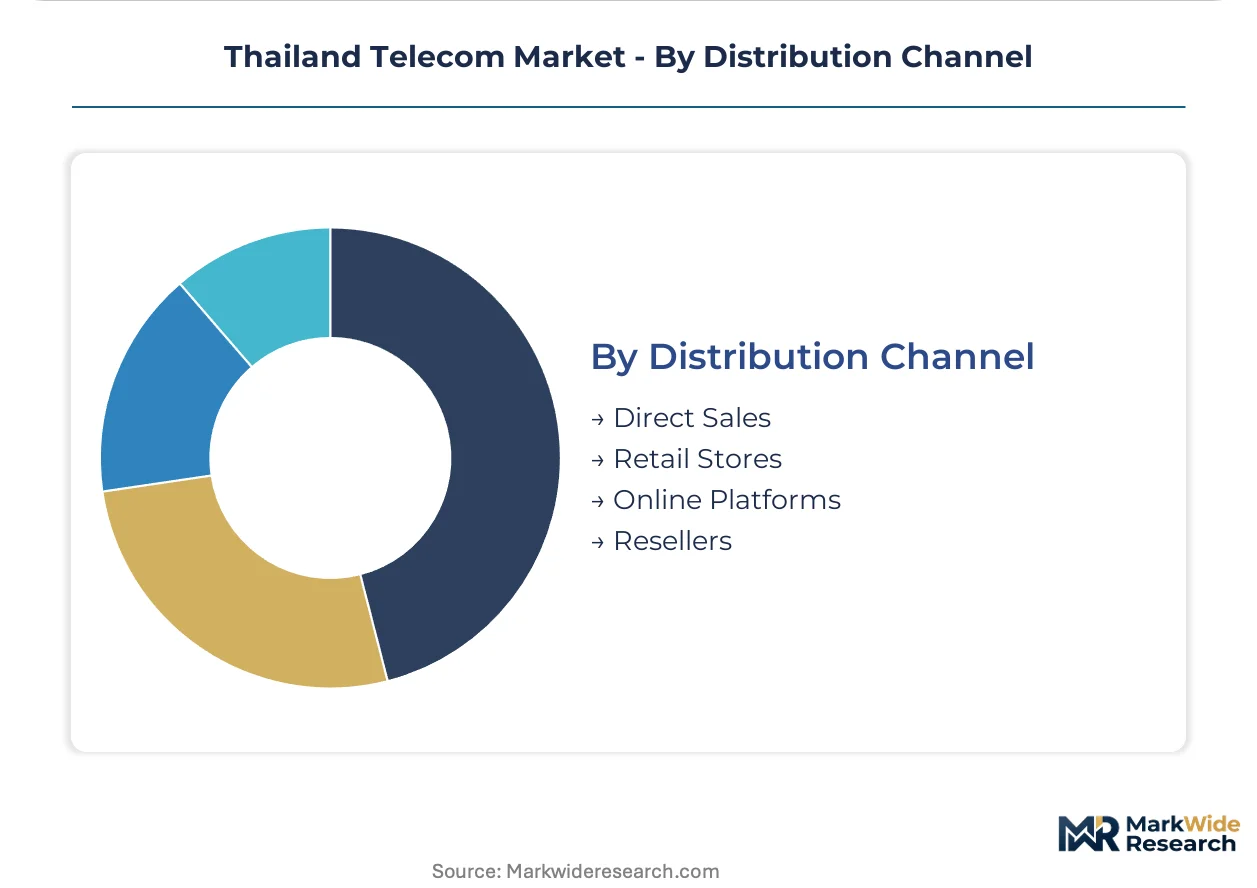
Distribution Channel:
Customer acquisition costs vary substantially across physical and digital touchpoints.
- Direct Sales:Operator field teams pursue large enterprise and government accounts with customized proposal development. Dedicated account executives manage multi-year service agreements for manufacturing and logistics clients.
- Retail Stores:Branded outlets and authorized dealer networks handle SIM activation, device financing, and postpaid contract conversions. Mall-based presence in Bangkok and provincial city centers sustains consumer brand visibility.
- Online Platforms:Self-service portals and mobile applications enable plan selection, digital payment, and eSIM provisioning. Younger demographic segments and tech-forward SMEs exhibit highest digital channel adoption rates.
- Resellers:Independent agents and system integrators bundle connectivity with IT infrastructure and cloud services. Secondary operators leverage wholesale fiber access to reach enterprise customers outside their owned infrastructure footprint.
Transaction volume sits with Retail Stores. Channel shift momentum is concentrated in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spectrum allocation and submarine cable landing stations anchor Thailand's telecom infrastructure geography. Bangkok's metropolitan corridor concentrates international bandwidth termination and domestic backbone interconnection.
Bangkok Metropolitan Region
Enterprise cloud migration and smart city initiatives drive demand in the capital corridor. The National Broadcasting and Telecommunications Commission mandates 5G coverage obligations that accelerate small cell densification. Sathorn and Silom central business districts host millimeter-wave deployments serving financial services and multinational headquarters.
Eastern Economic Corridor
Factory automation and logistics visibility requirements absorb premium private network contracts. Board of Investment incentives for advanced manufacturing synchronize infrastructure planning with industrial estate development. Chonburi and Rayong provinces concentrate automotive and electronics facilities demanding guaranteed quality-of-service connectivity.
Northeastern Provinces
Agricultural IoT and provincial government digitization create wholesale access opportunities. National broadband policy targets channel public investment into fiber backbone extension beyond Bangkok's periphery. Khon Kaen and Udon Thani lack competitive fixed-line alternatives, opening corridors for secondary operator expansion.
Northern Region
Tourism corridor connectivity and cross-border trade with Myanmar and Laos shape infrastructure priorities. The Personal Data Protection Act elevates compliance costs for cloud service bundling in hospitality and retail sectors. Chiang Mai's digital nomad concentration and industrial zones around Lampang drive divergent service requirements.
Southern Provinces
Deep-water port operations and island tourism absorb specialized maritime and satellite connectivity services. Phuket and Songkhla logistics hubs require redundant transmission paths for supply chain continuity. Rubber and palm oil plantation automation is emerging as a niche IoT demand segment.
Thailand Telecom Market Competitive Environment
Global equipment vendors compete with regional system integrators across infrastructure deployment and enterprise solution delivery. Market structure concentrates around three operator groups controlling licensed spectrum and national backbone assets. Strategic archetypes separate spectrum-rich mobile incumbents, fiber-first wholesale specialists, and converged fixed-mobile platforms. Dominant competitive moves include infrastructure sharing agreements for rural coverage compliance and enterprise solution bundling to displace fragmented supplier relationships.
Within the mobile-centric tier, Advanced Info Service PCL and True Corp Public Company Ltd exemplify converged platform operators leveraging integrated fixed-mobile assets. Jasmine International PCL occupies a position among wholesale-focused challengers competing on provincial fiber access pricing. These three entities represent distinct strategic postures: millimeter-wave R&D intensity, converged service bundling, and aggressive wholesale expansion respectively.
| Leading Market Players |
|---|
| Total Access Communication Public Company Ltd |
| Jasmine Telecom Systems Public Company Ltd |
| Advanced Info Service PCL |
| Samart Corp Public Company Ltd |
| National Telecom |
| True Corp Public Company Ltd |
| Jasmine International PCL |
| Forth Smart Service Public Company Ltd |
| Intouch Holdings Public Company Ltd |
| Others |
Value Chain & Pricing Dynamics
State-backed infrastructure financing and sovereign wealth participation in Thai tower assets concentrates ownership patterns that discipline capital deployment and compress margin tolerance across wholesale access tiers. The National Broadcasting and Telecommunications Commission's spectrum auction timing forces accelerated procurement cycles that amplify equipment cost volatility and constrain operator pricing flexibility simultaneously.
Pricing Analysis
Warranty and service-level guarantees differentiate enterprise fiber contracts from bare connectivity offerings in the Thai market. Three-tier pricing structure across premium, standard, and economy levels segments the residential broadband base, with fiber-to-the-home commanding quality premiums over legacy copper. Price differentiation rests on installation speed tiers and guaranteed uptime percentages for SME and large enterprise segments. Cost compression in the residential tier intensifies because secondary operators leverage wholesale fiber access to undercut incumbent retail pricing. Large enterprise buyers exhibit lowest price sensitivity due to dedicated network slicing requirements and private 5G quality-of-service guarantees.
Supply Chain Analysis
Maritime freight costs from Northeast Asian semiconductor hubs to Laem Chabang port fluctuate with Red Sea routing disruptions and Thai baht volatility against the US dollar. Critical radio access network equipment draws from concentrated manufacturing bases in China, South Korea, and Japan. Optical transceivers, massive MIMO antenna arrays, and baseband unit processors constitute the highest-value import dependencies. Single-source vulnerability persists for millimeter-wave small cell components where Thai operators lack qualified secondary vendor alternatives. Distribution runs through national distributor networks anchored in Bangkok with provincial extension via authorized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where the National Broadcasting and Telecommunications Commission's rural coverage mandates force capital-constrained secondary operators toward infrastructure sharing or exit.
For Market Incumbents: Deploy millimeter-wave R&D intensity as the primary defensive lever against converged platform competitors. Deepen fixed-mobile integration to capture enterprise wallet share before wholesale challengers penetrate the Eastern Economic Corridor. Advanced Info Service PCL's patent position in 26 GHz infrastructure creates switching costs that True Corp must neutralize through superior service bundling. Accelerate provincial fiber overbuild in Khon Kaen and Udon Thani to preempt Jasmine International PCL's wholesale expansion. For New Entrants and Emerging Players: System integrators with cloud service certifications represent the most viable channel partnership archetype for market penetration. Underpenetrated northeastern provinces lack competitive fixed-line alternatives and absorb national broadband subsidy flows. Target automotive suppliers in Rayong industrial estates with converged connectivity and edge computing bundles. White-space exists in satellite-backup services for southern deep-water port operations where fiber redundancy remains incomplete. For Investors and Strategic Acquirers: Distressed-cycle entries favor wholesale fiber specialists with provincial concession rights in Thailand's northeastern corridor. Long-term viability hinges on 5G spectrum renewal timelines and the Personal Data Protection Act compliance cost trajectory. Acquisition targets should demonstrate anchored tenant relationships in Eastern Economic Corridor industrial estates. Watch the National Broadcasting and Telecommunications Commission's millimeter-wave auction timing as the signal for infrastructure valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Infrastructure Sharing Agreement | Enables rural coverage compliance while splitting capital burden between Advanced Info Service and True Corp. |
| Millimeter-Wave Patent Investment | Secures propagation modeling advantages for Bangkok central business district densification projects. |
| Wholesale Fiber Access Expansion | Allows Jasmine International PCL to penetrate provincial zones without backbone construction costs. |
| Enterprise Cloud Service Bundling | Captures manufacturing automation budgets in Chonburi and Rayong through converged contracts. |
| Network Slicing Platform Development | Supports quality-of-service guarantees for robotic process automation in Eastern Economic Corridor facilities. |
Study Parameters
Regulatory filings from the National Broadcasting and Telecommunications Commission, operator annual disclosures to the Stock Exchange of Thailand, and national broadband policy documents formed the secondary backbone for market sizing. Primary interviews with network planning executives at mobile operators, procurement leads at Eastern Economic Corridor manufacturing facilities, and wholesale access managers at secondary fiber providers validated demand assumptions. Triangulation across bottom-up equipment deployment tracking and top-down service revenue aggregation anchored the forecast framework.
Bottom-up modeling of 5G small cell densification timelines and fiber-to-the-home passings was cross-checked against top-down operator capital expenditure disclosures across the analysis window. Segmentation dimensions included service delivery mode, customer scale tier, infrastructure generation, and geographic corridor. CAGRs were derived from equipment shipment trajectories and subscription growth curves. Industry-specific inputs incorporated the National Broadcasting and Telecommunications Commission's spectrum auction schedule and Board of Investment incentive synchronization with infrastructure planning.
Caveats apply where semiconductor foundry capacity constraints or Personal Data Protection Act enforcement intensity could materially shift the outlook. Forecasts reflect assumptions regarding millimeter-wave propagation performance and provincial fiber take-up rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
China ICT Market
Telecommunications
5G Connections Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
Australia Telecom Tower Market
Telecommunications
Hungary ICT Market
Telecommunications
Oman Telecommunication Market
Telecommunications
Global Esim Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
5G MVNO Market
Telecommunications
Iceland Telecom Market
Telecommunications
Cloud Telephony Service Market
Telecommunications
Chile Telecom Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Telecom Expense Management Market
Telecommunications
MVNO Market