
 Underwater Drone Market | 2026-2036
Underwater Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Drone Market Intelligence
Skilled subsea robotics engineers is bifurcating the competitive landscape into talent-rich incumbents and capacity-constrained challengers. Kongsberg Maritime leverages its Norwegian engineering base to dominate deep-water autonomous systems. Teledyne Marine Group anchors North American demand through its sensor-integrated platform architecture. Saab Seaeye Ltd specializes in compact work-class vehicles for congested offshore environments.
An underwater drone is a tethered or untethered robotic system operating below the water surface, typically rated to depths exceeding 300 meters and equipped with pressure-hardened housings, thruster arrays, and real-time telemetry links for submerged intervention or data collection. These systems execute tasks in environments lethal to human divers, including pipeline survey, hull inspection, and benthic habitat mapping. Remotely Operated Vehicles retain the largest installed base due to proven reliability in heavy intervention roles, though Autonomous Underwater Vehicles capture the fastest expansion trajectory as battery energy density and machine-vision navigation improve. Oil & Gas Companies represent the most concentrated end-user spending pool, while Research Institutions drive specification innovation for extreme-depth platforms.
The International Maritime Organization's safety conventions shape hull inspection standards, compelling operators to adopt certified robotic alternatives to diver-led methods. The US FAA and Coast Guard coordinate unmanned maritime system air-sea interface protocols, while Norway's Petroleum Safety Authority mandates annual subsea facility surveys that drones increasingly perform. Stakeholders must weigh capital deployment toward autonomous architectures against the service-revenue durability of tethered fleets as regulatory thresholds for human-free operations continue tightening.
Market Dynamics
Autonomous navigation architectures are bifurcating fleet procurement strategies between tethered service-revenue models and untethered capital-deployment systems. The International Maritime Organization's tightening safety conventions are compressing certification timelines for human-free subsea operations.
Growth Catalysts
- Offshore decommissioning mandates:Norway's Petroleum Safety Authority requires annual subsea facility surveys that robotic systems increasingly execute. North Sea operators are expanding autonomous vehicle fleets to meet inspection frequency requirements without diver deployment.
- Battery energy density improvements:Solid-state lithium-sulfur cells are extending autonomous underwater vehicle endurance beyond 72 hours. Research institutions in California and Massachusetts are driving specification innovation for extreme-depth platforms.
- Subsea infrastructure aging:Gulf of Mexico pipeline networks installed during the 1980s construction boom require continuous structural assessment. Inspection demand concentrates around Houston's subsea engineering cluster.
Market Restraints
- Titanium alloy supply concentration:Pressure-hardened hull fabrication depends on Russian and Chinese sponge titanium suppliers. Western fabricators face input cost volatility and export control friction.
- Deep-water acoustic telemetry limitations:Signal attenuation below 6,000 meters restricts real-time command integrity for full-ocean-depth vehicles. Satellite uplink dependency creates operational dead zones.
- Certification timeline compression:The International Maritime Organization's revised safety conventions are extending type-approval cycles for autonomous systems. Small manufacturers lack capital to sustain multi-year validation programs.
Strategic Opportunities
- Offshore wind foundation inspection:Floating turbine installations off Scotland and Massachusetts require periodic subsea structural assessment. Autonomous platforms can execute cable burial surveys without vessel tethering.
- Machine-vision navigation convergence:Simultaneous localization and mapping algorithms fused with synthetic aperture sonar are enabling GPS-denied autonomy. This technology pairing opens congested port environments to robotic hull cleaning.
- US Coast Guard unmanned system protocols:Coordinated air-sea interface standards are creating regulatory clarity for hybrid aerial-underwater platforms. Survey contractors are positioning for integrated coastal zone mapping contracts.
Industry Challenges
- Subsea robotics engineering scarcity:Deep-water pressure vessel design and underwater acoustic engineering talent pools concentrate in Norway and Scotland. Challengers struggle to recruit against Kongsberg Maritime and Saab Seaeye compensation benchmarks.
- Legacy ROV fleet integration:Tethered vehicle operators resist capital write-downs on depreciated work-class systems. Hybrid autonomy retrofits require software architecture reconciliation that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Drone Market |
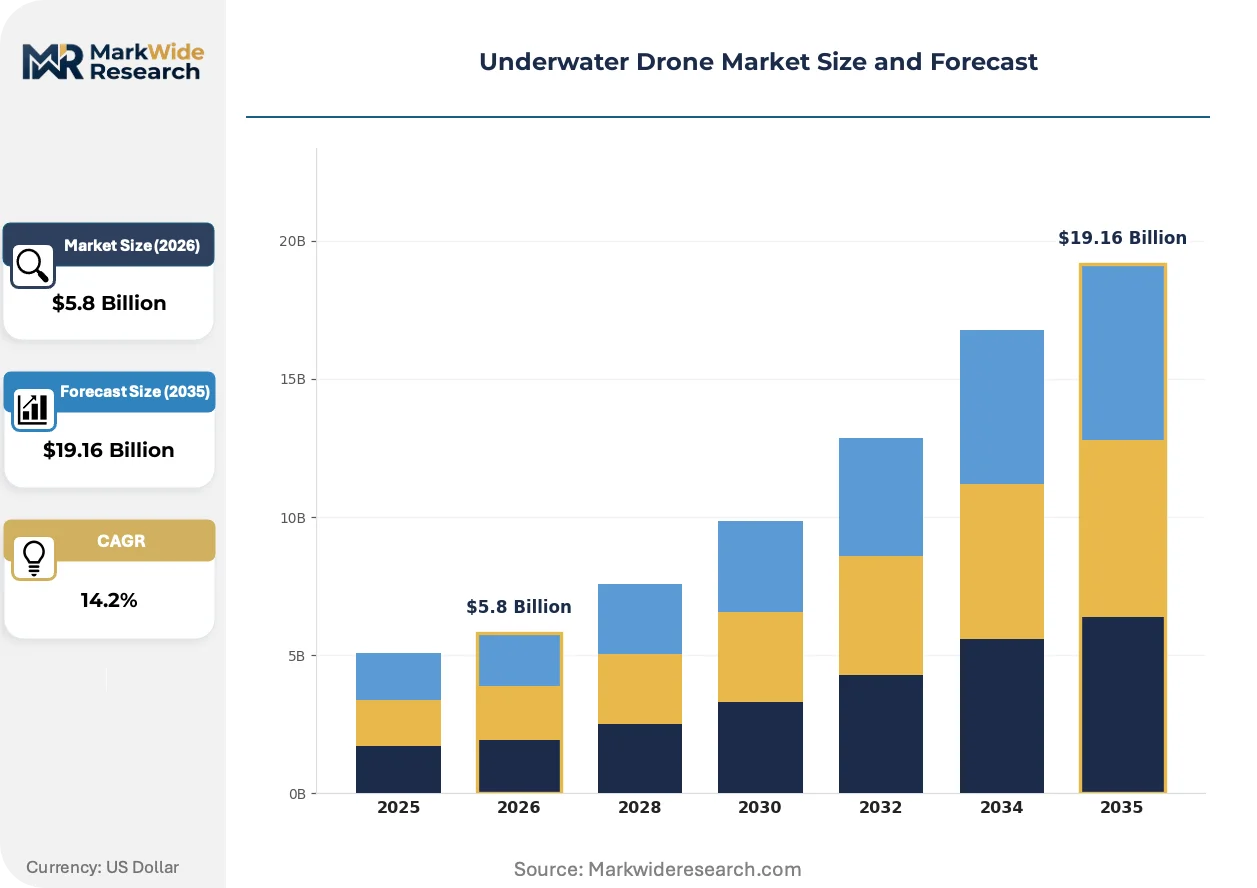
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.16 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remotely Operated Vehicles, Autonomous Underwater Vehicles, Hybrid Drones, Accessories Application: Ocean Exploration, Environmental Monitoring, Military Operations, Infrastructure Inspection End User: Research Institutions, Government Agencies, Oil & Gas Companies, Marine Contractors Technology: Sonar Systems, Camera Systems, Navigation Systems, Communication Systems |
| Companies Covered | Saab Seaeye Ltd, Teledyne Marine Group, Lockheed Martin Corporation, The Boeing Company, Kongsberg Maritime, ECA Group, Bluefin Robotics, Oceaneering International, Inc., TechnipFMC plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Drone Market Strategic Shifts & Innovations
Acoustic positioning systems are yielding to optical and inertial alternatives as shallow-water applications multiply. Machine-vision navigation is compressing the technical barrier between remotely operated and fully autonomous platforms.
Synthetic aperture sonar is fragmenting the geophysical survey segment by delivering centimetric seabed resolution at survey speeds three times faster than conventional side-scan systems. Offshore wind developers in the North Sea are specifying SAS-equipped autonomous vehicles for cable route predesign. The technology is compressing survey duration contracts and displacing multibeam echosounder vendors from pre-construction work.
The EU's CSRD disclosure requirements are mandating supply chain emissions transparency for subsea service contractors. Vessel charterers must now report Scope 3 emissions from robotic inspection operations. Norwegian oil and gas operators are prioritizing electric-powered autonomous vehicles with documented carbon footprints to satisfy auditor verification.
Service unbundling is separating hardware ownership from operational deployment in the offshore inspection segment. Major oil and gas companies are divesting captive ROV fleets and contracting inspection-as-a-service from specialist operators. This procurement pattern is most visible in the Gulf of Mexico, where BP and Shell have transferred subsea robotics assets to Oceaneering and TechnipFMC service divisions.
Underwater Drone Market Segmentation
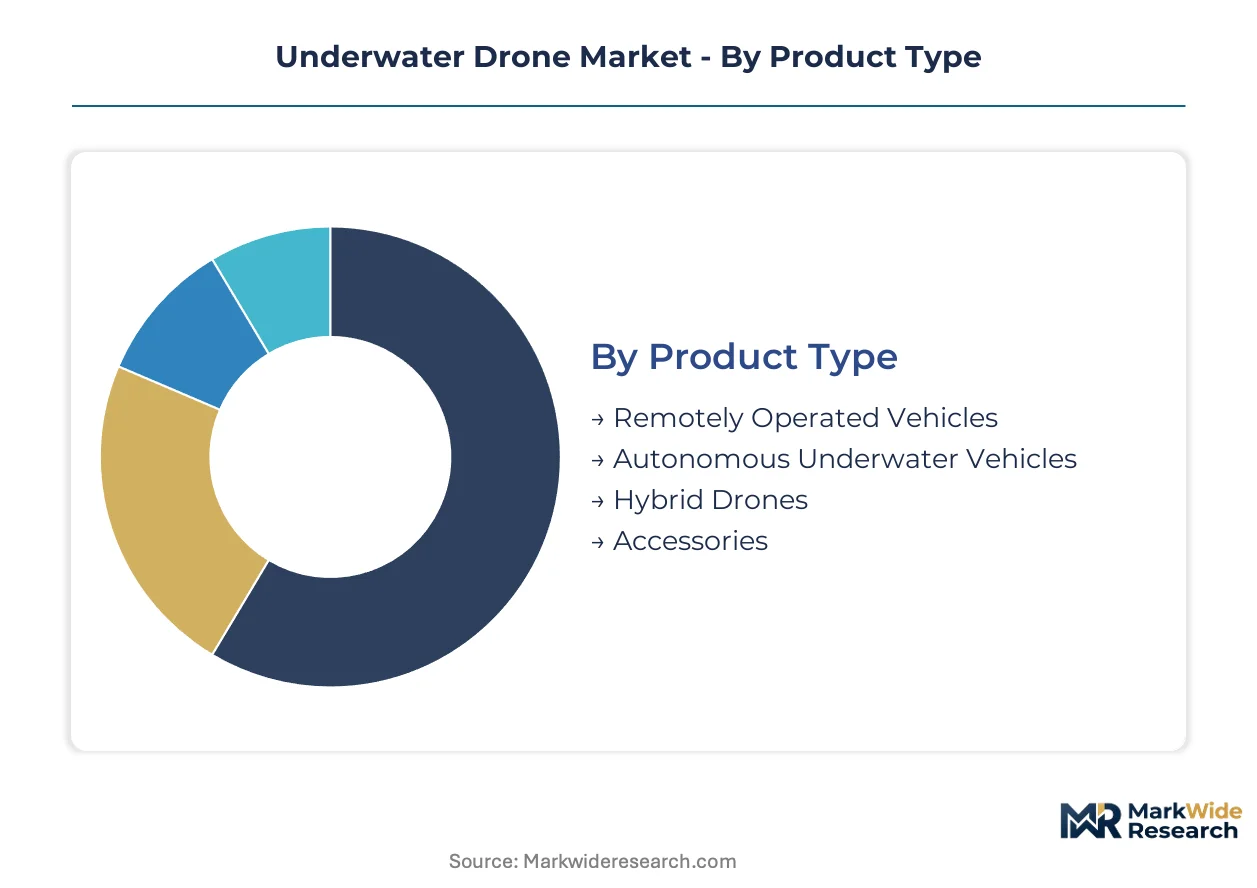
Segmentation in the underwater drone market reflects divergent certification requirements and procurement economics across tethered, autonomous, and hybrid architectures. Regulatory thresholds from the International Maritime Organization and national maritime safety authorities shape equipment specifications differently for each product category.
Product Type:
Regulatory differentiation between tethered and untethered systems determines capital deployment strategies and certification timelines across fleet procurement decisions.
- Remotely Operated Vehicles:Tethered robotic platforms with real-time surface control via umbilical cables rated for depths exceeding 3,000 meters. Oil & Gas Companies in Norway's North Sea basin deploy work-class ROVs for pipeline intervention where human-free operations remain prohibited. The International Maritime Organization's safety conventions maintain diver-alternative certification pathways that favor proven tethered reliability.
- Autonomous Underwater Vehicles:Untethered battery-powered systems executing pre-programmed missions without surface umbilical dependence. Research Institutions in Massachusetts and California specify long-endurance AUVs for benthic habitat mapping where acoustic telemetry limitations are acceptable trade-offs. Solid-state lithium-sulfur cell advances are extending mission duration beyond 72 hours.
- Hybrid Drones:Dual-mode architectures switching between tethered precision and autonomous endurance.
- Accessories:Pressure-hardened sensor pods, manipulator arms, and telemetry modules.
Remotely Operated Vehicles handle the majority of throughput; Autonomous Underwater Vehicles are climbing the fastest on share.
Application:
Cost tier differentiation separates capital-intensive inspection contracts from research-funded exploration missions with divergent equipment durability requirements.
- Infrastructure Inspection:Subsea facility assessment for pipelines, platforms, and wind turbine foundations requiring pressure-rated hulls and real-time defect documentation. Norway's Petroleum Safety Authority mandates annual surveys that robotic systems increasingly execute without diver deployment. Gulf of Mexico operators contract inspection-as-a-service from specialist marine contractors.
- Military Operations:Mine countermeasures, harbor security, and submerged reconnaissance with encrypted acoustic links and hardened electronic warfare resistance. Government Agencies specify platforms with STANAG interoperability for NATO coalition compatibility.
- Ocean Exploration:Deep-water bathymetry and geological survey for academic and commercial discovery objectives.
- Environmental Monitoring:Long-duration water quality assessment and marine life tracking missions.
Infrastructure Inspection commands the largest contract values; Military Operations show the steepest budget acceleration among government end-users.
End User:
Volume concentration varies sharply between capital-constrained research programs and asset-heavy oil and gas operators with sustained inspection obligations.
- Oil & Gas Companies:Integrated energy majors and independent operators with captive or contracted subsea robotics fleets for continuous infrastructure assessment. North Sea decommissioning mandates and Gulf of Mexico aging pipeline networks drive recurring procurement. BP and Shell have transferred robotics assets to specialist service divisions in the Gulf of Mexico.
- Research Institutions:Academic and government laboratories driving specification innovation for extreme-depth platforms and novel sensor integration. California and Massachusetts institutions pioneer solid-state battery and machine-vision navigation advances.
- Government Agencies:Naval, coast guard, and environmental regulators with mission-specific durability requirements.
- Marine Contractors:Specialist service providers executing inspection-as-a-service for asset owners divesting captive fleets.
Oil & Gas Companies dominate installed base volume; Research Institutions are expanding most quickly as federal ocean science budgets increase.
Technology:
Maturity gradients separate established acoustic and optical systems from emerging navigation architectures with divergent integration complexity.
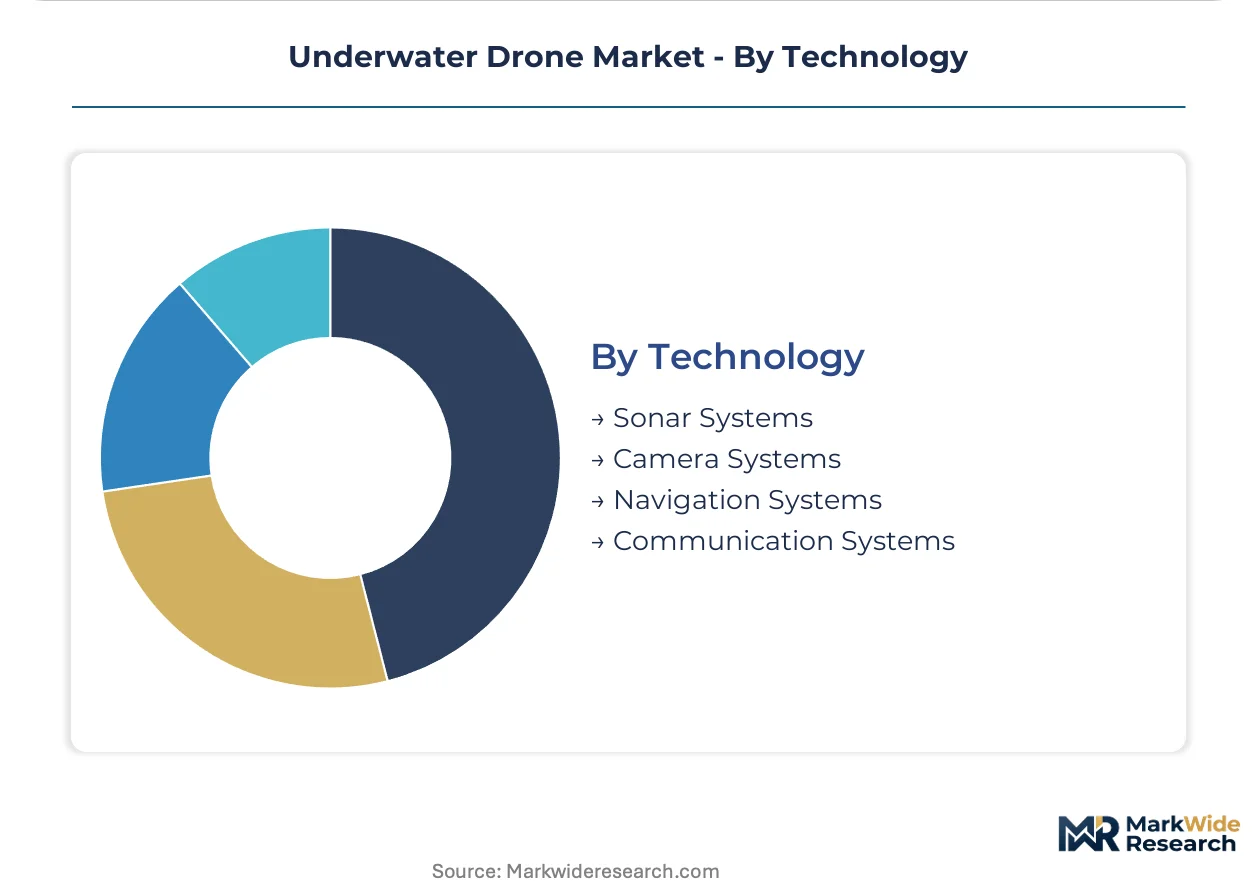
- Sonar Systems:Acoustic sensing for seabed mapping and obstacle avoidance including synthetic aperture sonar delivering centimetric resolution at survey speeds three times faster than conventional side-scan. Offshore wind developers in the North Sea specify SAS-equipped vehicles for cable route predesign.
- Navigation Systems:Inertial measurement units, Doppler velocity logs, and simultaneous localization and mapping algorithms enabling GPS-denied autonomy. Machine-vision navigation is compressing the technical barrier between remotely operated and fully autonomous platforms.
- Camera Systems:High-definition and low-light optical sensors for visual inspection and documentation.
- Communication Systems:Acoustic modems and optical links for submerged telemetry with surface vessels.
Sonar Systems anchor current procurement spending; Navigation Systems are gaining share fastest as autonomy requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian operators command premium pricing for deep-water autonomous systems while Gulf of Mexico contractors compete on inspection-service rates. This asymmetry reflects divergent regulatory stringency and labor cost structures across the North Sea and US offshore basins.
Norway
North Sea decommissioning mandates and annual subsea facility survey requirements drive fleet expansion among oil and gas operators. The Petroleum Safety Authority enforces strict inspection protocols that favor certified robotic alternatives to diver-led methods. Kongsberg and Bergen host concentrated engineering clusters where subsea robotics talent pools support domestic manufacturers.
United States
Gulf of Mexico pipeline networks installed during the 1980s construction boom require continuous structural assessment and drive inspection-as-a-service contracting. The FAA and Coast Guard coordinate unmanned maritime system air-sea interface protocols for regulatory clarity. Houston's subsea engineering cluster anchors North American demand for work-class tethered vehicles.
United Kingdom
Offshore wind foundation inspection demand is accelerating around floating turbine installations off Scotland. The Maritime and Coastguard Agency implements IMO safety conventions through domestic certification requirements. Aberdeen maintains subsea robotics engineering capabilities despite oil and gas fleet divestment trends.
China
Deep-water acoustic telemetry research and pressure-hardened hull fabrication capacity concentrate in coastal manufacturing zones. The Ministry of Industry and Information Technology supports indigenous autonomous underwater vehicle development through state funding programs. Qingdao and Shanghai harbor expanding test facilities for full-ocean-depth platforms.
Japan
Research institutions drive specification innovation for extreme-depth platforms and novel sensor integration. METI funding channels support solid-state battery and machine-vision navigation advances for long-endurance missions. Tokyo and Yokohama host concentrated marine robotics engineering groups serving academic and commercial end-users.
Underwater Drone Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the underwater drone market. The competitive structure bifurcates between talent-rich incumbents with captive engineering bases and capacity-constrained challengers dependent on contract labor. Three strategic archetypes dominate: integrated defense conglomerates with classified program experience, maritime specialists with Norwegian or Swedish engineering heritage, and oilfield service contractors with vessel-integrated deployment capabilities. Competitive moves concentrate on strategic partnerships for sensor integration and geographic expansion through regional inspection-service contracts.
Among Scandinavian maritime specialists, Kongsberg Maritime and Saab Seaeye Ltd occupy positions reflecting deep-water engineering heritage. Teledyne Marine Group anchors North American market presence through sensor-integrated platform architecture. Defense-oriented conglomerates including Lockheed Martin Corporation and The Boeing Company exemplify the classified-program archetype with government agency customer relationships. Oilfield service contractors Oceaneering International, Inc. and TechnipFMC plc represent the vessel-integrated deployment model following asset transfers from integrated energy majors.
| Leading Market Players |
|---|
| Saab Seaeye Ltd |
| Teledyne Marine Group |
| Lockheed Martin Corporation |
| The Boeing Company |
| Kongsberg Maritime |
| ECA Group |
| Bluefin Robotics |
| Oceaneering International, Inc. |
| TechnipFMC plc |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Norwegian pressure-hull fabricators shapes both supply concentration and price floors for deep-water autonomous systems. Kongsberg Maritime and Saab Seaeye leverage captive engineering bases to command premium pricing, while challengers face margin compression from titanium alloy input volatility.
Pricing Analysis
Configured-to-order pricing for work-class ROVs carries a 40-60% premium over standard inspection-grade AUVs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the mid-tier segment is intensifying because of inspection-as-a-service contracting by Gulf of Mexico operators. Oilfield service contractors exhibit highest price sensitivity, while research institutions prioritize specification compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs for titanium sponge from Russian and Chinese suppliers have elevated working capital requirements for Western fabricators. Pressure-hardened hull fabrication draws from Norway, China, and the United States, with solid-state battery cell supply anchored in Japan and South Korea. Single-source vulnerability in acoustic telemetry modules creates procurement risk for full-ocean-depth platforms. Distribution runs through vessel-integrated service contractors in Houston and specialist operators in Aberdeen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous navigation architectures constitute a high-growth disruption, with machine-vision SLAM convergence and IMO certification compression creating winner-take-most dynamics.
For Market Incumbents: Consolidate engineering talent pools in Bergen and Kongsberg through compensation benchmarking and captive training programs. Acquire specialist sensor-integrators to lock in synthetic aperture sonar supply before offshore wind specification standardization. Battery chemistry partnerships with solid-state developers in Massachusetts and California represent critical vertical integration leverage against endurance-compromised challengers. For New Entrants and Emerging Players: Post-decommissioning inspection contracts in the North Sea offer a service-layer gap where incumbents under-serve small-field operators with legacy ROV assets. Target floating offshore wind foundation assessment off Scotland and Massachusetts, where autonomous cable burial surveys lack established contractors. Position through pay-per-survey revenue models that eliminate capital deployment barriers for asset-light wind developers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among inspection-as-a-service operators with vessel-integrated deployment capabilities, as evidenced by BP and Shell asset transfers to Oceaneering and TechnipFMC. Long-term viability favors platforms with documented carbon footprints satisfying EU CSRD disclosure requirements. Watch for IMO type-approval timeline compression as the signal indicating regulatory acceleration toward human-free operations.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | IMO type-approval acceleration differentiates compliant platforms from multi-year validation laggards. |
| Sensor Integration Partnership | Synthetic aperture sonar alliances with offshore wind developers predesign cable routes three times faster. |
| Battery Supply Agreement | Solid-state lithium-sulfur cell contracts with Japanese and South Korean suppliers extend mission endurance. |
| Geographic Expansion | Scotland and Massachusetts floating wind markets lack established autonomous inspection contractors. |
| Service Model Transition | Inspection-as-a-service contracting captures recurring revenue from oil majors divesting captive fleets. |
Research Approach
Operator-level perspectives from ROV fleet managers, subsea engineering directors, offshore wind project developers, and marine contractor procurement heads anchored the qualitative base. Secondary validation drew from IMO safety convention documentation, Norway Petroleum Safety Authority inspection protocols, US Coast Guard unmanned system guidelines, and SEC filings from oilfield service contractors. Bottom-up segment sizing triangulated against top-down market aggregation across tethered, autonomous, and hybrid platform architectures.
Sensitivity analysis tested forecast robustness across battery energy density improvement trajectories, titanium alloy price volatility scenarios, and IMO certification timeline compression assumptions. Segmentation dimensions modeled include product architecture, application intensity, end-user capital structure, and regional regulatory stringency. CAGRs derived from logistic diffusion curves fitted to autonomous platform adoption patterns, with solid-state battery commercialization and machine-vision navigation maturation as primary inflection inputs.
Underlying assumptions cover continued IMO safety convention tightening, stable Norway-US-China supply chain configuration, and offshore wind installation pace, with deviation risk concentrated in acoustic telemetry breakthroughs below 6,000 meters and export control expansion on titanium sponge. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Latin America Autonomous Mobile Robot Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
Dispensing Robots Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Cordless Router Market