
 Mobile Voice Market | 2026-2036
Mobile Voice Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Voice Market Intelligence
The premium carrier tier is consolidating around guaranteed-quality voice services with dedicated spectrum allocations, while commodity voice is consolidating into over-the-top applications riding generic data pipes. AT&T Inc. leverages its FirstNet partnership to sustain priority call routing for public safety agencies. Verizon Communications Inc. anchors its position through millimeter-wave 5G deployments that differentiate ultra-low-latency voice offerings from standard mobile packages.
Mobile voice encompasses real-time audio communication transmitted via cellular networks, circuit-switched legacy infrastructure, or packet-based IP protocols requiring codecs such as AMR-WB for wideband fidelity and guaranteed mean opinion scores above 3.5 for commercial acceptability. Its primary purpose remains person-to-person connectivity, though enterprise use now embeds voice into unified communications workflows with CRM integration and AI transcription. VoLTE and 5G technology segments command the margin pool as carriers sunset 2G and 3G networks, reallocating spectrum to higher-efficiency platforms. Enterprise end users represent the fastest-growing demand vector as organizations migrate from on-premises PBX hardware to cloud-based and hybrid deployment models that collapse capital expenditure into per-seat operational subscriptions.
FCC regulations govern number portability and rural call completion in the United States, while Ofcom enforces wholesale access pricing in the United Kingdom, and TRAI mandates interconnect usage charges in India, collectively shaping how carriers price cross-network voice termination and where new entrants gain footholds. GDPR in Europe and emerging data localization frameworks elsewhere constrain how voice metadata traverses jurisdictional boundaries, complicating cloud-hosted service architectures. Stakeholders must monitor spectrum auction calendars and sunset timelines for legacy protocols, as these regulatory and technical milestones determine the pace at which infrastructure investment converts to service revenue.
Market Dynamics
Carrier migration from circuit-switched infrastructure to packet-based VoLTE and 5G voice cores is compressing legacy revenue streams while forcing spectrum reallocation decisions that reshape competitive economics.
Growth Catalysts
- VoLTE Technology Maturation:Carriers in India and Brazil are sunsetting 2G networks to reclaim spectrum for high-efficiency voice-over-LTE services, reducing per-call infrastructure costs.
- TRAI Interconnect Mandates:India's regulator has lowered termination charges, enabling new entrants to price aggressively against incumbents while expanding addressable subscriber bases.
- Enterprise Cloud Migration:Organizations across Germany and South Korea are abandoning on-premises PBX hardware for subscription-based unified communications platforms with embedded voice.
Market Restraints
- Legacy Infrastructure Stranded Costs:Carriers in Italy and Spain face accelerated depreciation of 3G equipment as 5G voice cores require parallel capital deployment.
- Regulatory Fragmentation:GDPR in Europe and emerging data localization frameworks in Indonesia constrain cross-border voice metadata routing, complicating cloud-hosted architectures.
- Over-the-Top Substitution:WhatsApp, Telegram, and Signal voice services capture person-to-person traffic that carriers once monetized through metered calling plans.
Strategic Opportunities
- Public Safety Priority Routing:Dedicated spectrum partnerships with first-responder agencies in Australia and Canada create defensible revenue pools with long contract tenors.
- AI-Enabled Voice Analytics:Real-time transcription and sentiment analysis integration with Salesforce and HubSpot CRMs opens enterprise upsell paths beyond basic connectivity.
- Rural Broadband-Voice Bundles:USDA Rural Development programs in the United States subsidize combined fiber-voice deployments that carriers can leverage for subscriber acquisition.
Industry Challenges
- Codec Interoperability Complexity:AMR-WB, EVS, and legacy AMR-NB fragmentation across device ecosystems forces carriers to maintain multiple transcoding paths, increasing operational overhead.
- Certification Timeline Compression:FCC Part 27 equipment authorization and CE marking requirements for 5G voice terminals are lengthening time-to-market for new device launches.
- Legacy System Integration Friction:Hybrid deployments combining cloud PBX with remaining TDM trunking require specialized SIP-I to ISUP interworking expertise that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Voice Market |
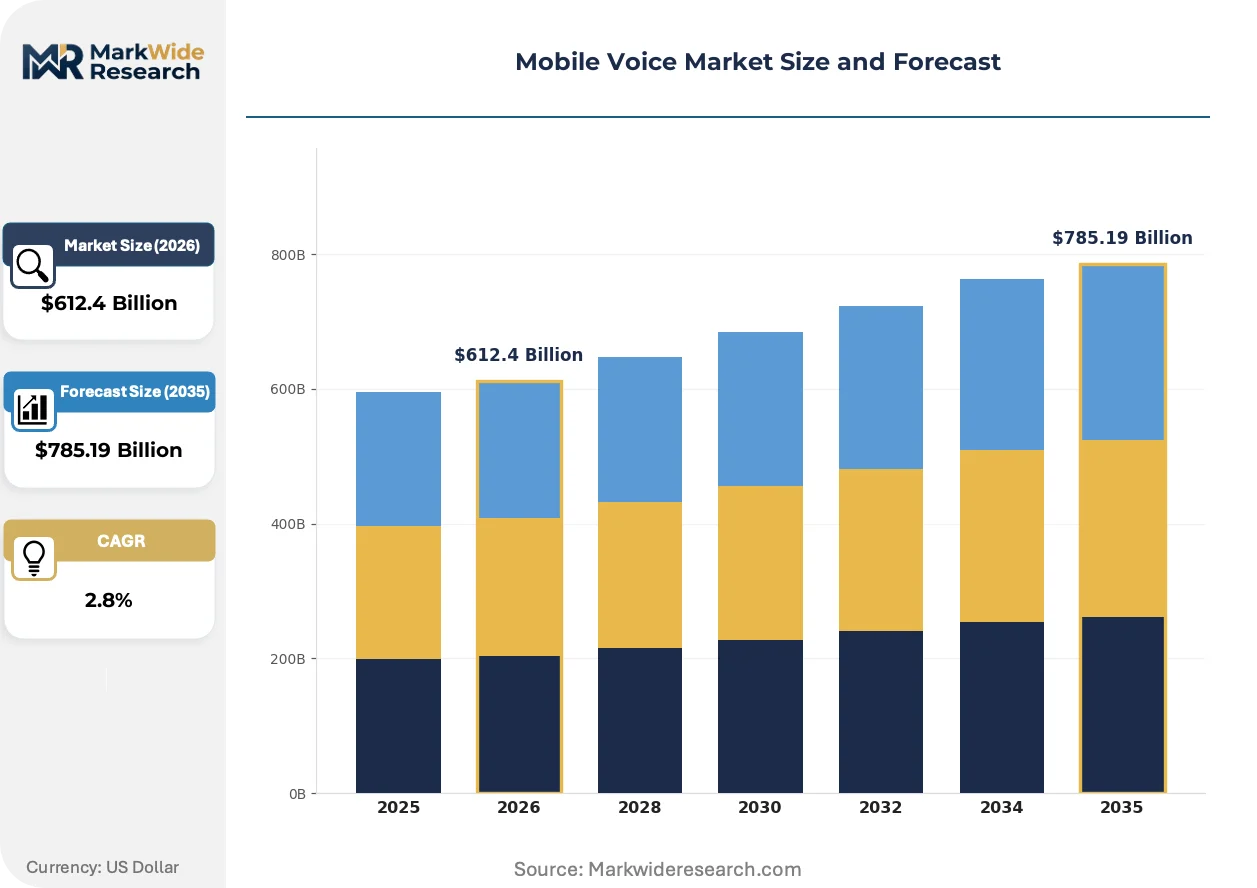
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $785.19 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: VoLTE, VoIP, PSTN, Wireless End User: Consumers, Enterprises, Government, Educational Institutions Technology: 4G, 5G, Wi-Fi, Satellite Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed |
| Companies Covered | AT&T Inc., Verizon Communications Inc., China Mobile Ltd., Deutsche Telekom AG, SoftBank Group Corp., Nippon Telegraph and Telephone Corporation, China Telecom Corp Ltd., Telefonica SA, Vodafone Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Voice Market Strategic Shifts & Innovations
Voice service architecture is fragmenting between carrier-controlled quality-guaranteed tiers and application-layer alternatives, with artificial intelligence and edge computing redrawing where intelligence resides in the call path.
WebRTC is decentralizing real-time voice processing from centralized carrier switches toward browser-based endpoints and edge compute nodes. Enterprise IT departments in the Netherlands and Singapore are deploying WebRTC gateways that bypass traditional PSTN interconnection for internal communications. This shift is decentralizing termination revenue away from incumbent carriers toward cloud infrastructure providers and software vendors.
GDPR's data minimization mandates are forcing European carriers to rearchitect call detail record retention and lawful intercept capabilities. France's CNIL has issued binding guidance on voice biometric data processing that exceeds baseline EU requirements. German healthcare providers and financial institutions are now demanding on-premise voice processing to satisfy both GDPR and sector-specific confidentiality rules.
Subscription fatigue among small and mid-sized enterprises is compressing voice service evaluation cycles from annual to quarterly. Channel partners in the United Kingdom and Japan are unbundling hardware, software, and connectivity into separately negotiable components. Manufacturing verticals in Mexico and Vietnam demonstrate the strongest preference for month-to-month contracts with zero upfront equipment commitments.
Mobile Voice Market Segmentation
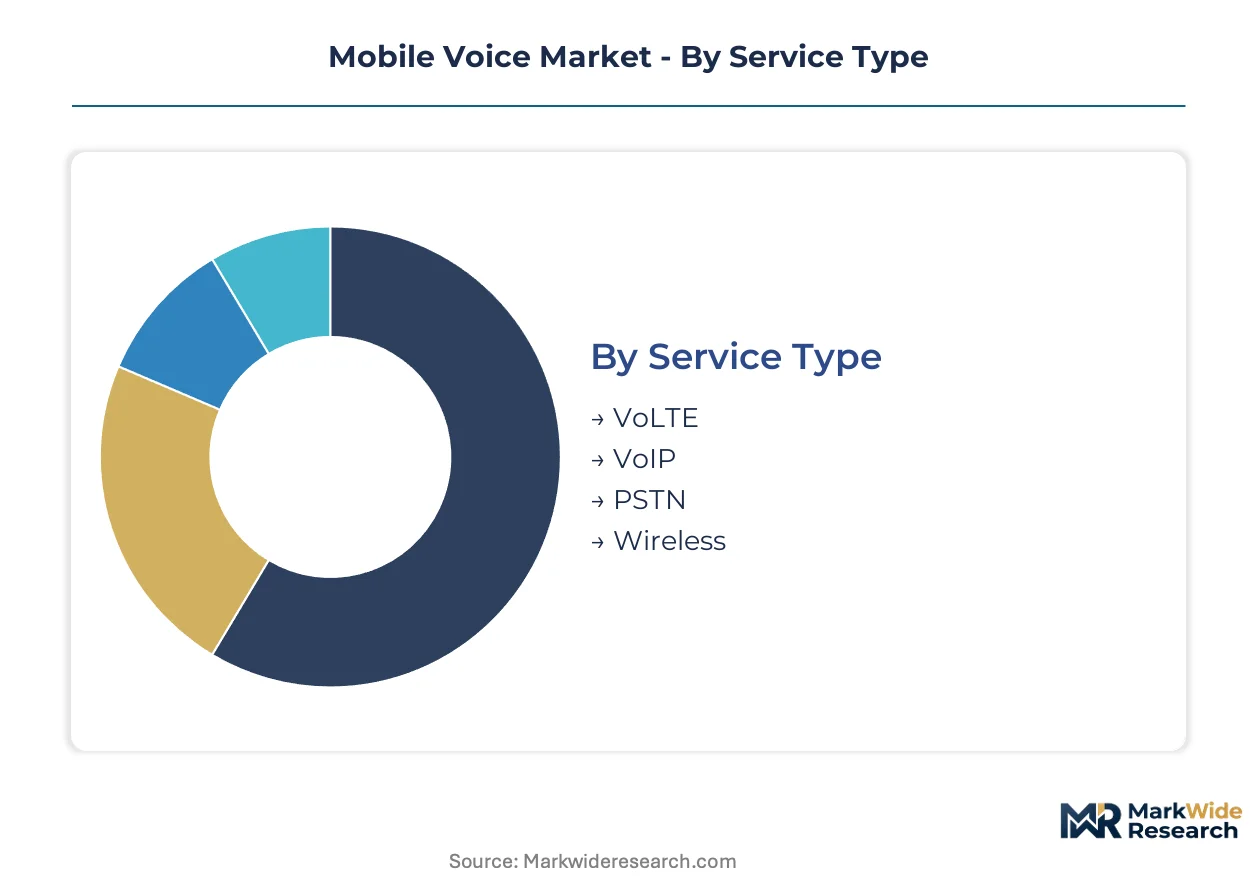
Mobile voice segmentation reveals how carriers, enterprises, and regulators allocate capital across competing infrastructure architectures. Each dimension—service delivery method, user category, access technology, and deployment model—carries distinct margin profiles and regulatory exposure that shape vendor strategy and buyer procurement cycles.
Service Type:
Carrier procurement teams select voice service architectures based on spectrum efficiency targets and legacy migration timelines.
- VoLTE:Packet-switched voice over LTE cores using AMR-WB and EVS codecs delivers superior spectral efficiency against circuit-switched alternatives. Indian carriers under TRAI interconnect mandates deploy VoLTE aggressively to terminate 2G networks while maintaining rural coverage obligations.
- VoIP:Session Initiation Protocol-based voice routing over generic data pipes enables over-the-top providers to bypass traditional termination fees. Enterprise demand in Germany and South Korea concentrates on VoIP for unified communications integration with Salesforce and Microsoft Teams workflows.
- PSTN:Legacy circuit-switched infrastructure retains residual utility for regulated universal service obligations and lawful intercept compliance. Italian and Spanish carriers face accelerated depreciation of PSTN assets as 5G voice cores require parallel capital deployment.
- Wireless:Dedicated spectrum voice services including FirstNet partnerships and private LTE networks serve public safety and industrial verticals with guaranteed quality-of-service tiers.
VoLTE leads on scale; VoIP leads on momentum.
End User:
Customer procurement authority and evaluation cycles vary sharply across consumer, enterprise, and institutional segments.
- Enterprises:Organizations migrating from on-premises PBX hardware to cloud-based unified communications platforms generate the steepest expansion trajectory for subscription voice services. German manufacturing verticals and South Korean financial services firms demand AI transcription and CRM integration as standard features.
- Consumers:Individual subscribers increasingly route person-to-person voice traffic through WhatsApp, Telegram, and Signal, compressing carrier metered calling plan revenue. Indian consumers under Reliance Jio pricing pressure have accelerated VoLTE adoption while accepting compressed voice margins.
- Government:Public safety agencies in Australia and Canada procure dedicated spectrum priority routing with decade-long contract tenors, creating defensible revenue pools insulated from over-the-top substitution.
- Educational Institutions:Universities and K-12 districts in the United States leverage USDA Rural Development subsidies to bundle fiber-voice deployments for campus and remote learning connectivity.
Enterprises dominate absolute spend; government anchors contract duration.
Technology:
Access technology selection determines codec compatibility, latency performance, and spectrum licensing requirements.
- 5G:Millimeter-wave and sub-6 GHz deployments enable ultra-low-latency voice with network slicing for guaranteed quality tiers. Verizon Communications anchors differentiation through 5G voice offerings that separate premium enterprise packages from standard mobile subscriptions.
- 4G:LTE infrastructure supports the bulk of current VoLTE traffic as carriers sunset 2G and 3G networks to reclaim spectrum. Brazilian carriers mirror Indian deployment patterns, using 4G voice cores to reduce per-call infrastructure costs during network transition periods.
- Wi-Fi:Unlicensed spectrum voice offload reduces cellular congestion in dense urban environments and enterprise campuses. Dutch and Singaporean IT departments deploy WebRTC gateways that bypass PSTN interconnection for internal Wi-Fi-based communications.
- Satellite:Low-earth orbit and geostationary systems extend voice coverage to maritime, aviation, and remote terrestrial locations outside cellular footprint.
4G carries current volume; 5G captures investment priority.
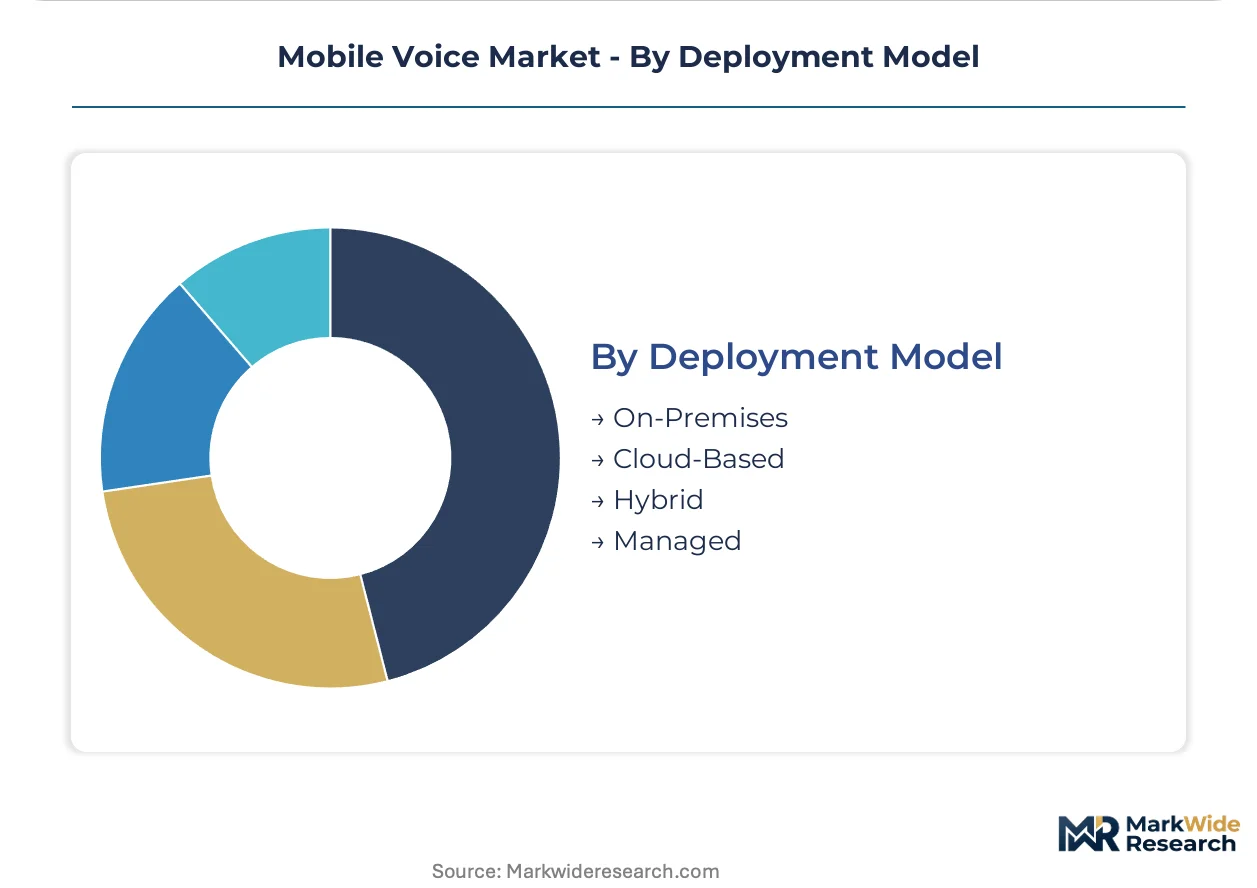
Deployment Model:
Capital structure preferences and data sovereignty requirements drive selection between on-premises, cloud, and hybrid architectures.
- Cloud-Based:Subscription models collapse capital expenditure into per-seat operational costs, attracting small and mid-sized enterprises with quarterly evaluation cycles. United Kingdom and Japanese channel partners unbundle hardware, software, and connectivity into separately negotiable components to address subscription fatigue.
- Hybrid:Combinations of cloud PBX with remaining TDM trunking require specialized SIP-I to ISUP interworking expertise that remains scarce in the market. German healthcare providers demand hybrid deployments to satisfy GDPR data minimization mandates alongside sector-specific confidentiality rules.
- On-Premises:Legacy PBX hardware retains presence in regulated industries requiring physical control over call detail records and lawful intercept capabilities. French CNIL binding guidance on voice biometric data processing exceeds baseline EU requirements, reinforcing on-premises retention in sensitive applications.
- Managed:Outsourced voice infrastructure operations appeal to organizations lacking internal SIP trunking and codec interoperability expertise.
Cloud-Based leads on new adoption; Hybrid leads on migration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent in network architecture and spectrum management concentrates in carrier headquarters clusters across Germany, India, Japan, the United Kingdom, and the United States. These workforce pools anchor infrastructure investment decisions and regulatory lobbying capacity.
United States
Enterprise cloud migration and FirstNet public safety deployments drive carrier capital allocation. FCC net neutrality rulings reshape interconnection economics for cross-network voice termination. Dallas-Fort Worth and Atlanta metro areas host major carrier network operations centers where VoLTE core upgrades proceed fastest.
India
Reliance Jio's aggressive pricing has compressed voice margins while expanding VoLTE subscriber bases into rural markets. TRAI interconnect usage charge mandates enable new entrants to undercut incumbents on termination pricing. Mumbai and Bangalore clusters concentrate network engineering talent for 5G voice core development.
Germany
Manufacturing verticals demand AI-integrated unified communications with embedded voice transcription. GDPR data minimization mandates force carriers to rearchitect call detail record retention architectures. Frankfurt and Munich host the largest enterprise voice service procurement teams in continental Europe.
United Kingdom
Channel partners unbundle hardware, software, and connectivity to address enterprise subscription fatigue. Ofcom wholesale access pricing mandates constrain incumbent carrier termination revenue streams. London's financial services district generates concentrated demand for guaranteed-quality voice with CRM integration.
Japan
SoftBank and NTT anchor millimeter-wave 5G voice deployments for ultra-low-latency enterprise offerings. METI spectrum allocation policies prioritize industrial IoT voice applications alongside consumer services. Tokyo-Osaka corridor concentration of electronics manufacturers drives private LTE voice network adoption.
Mobile Voice Market Key Industry Players
Top-tier vendors anchor spectrum-rich national carrier positions, while mid-tier challengers compete through wholesale access and niche vertical specialization. The market structure concentrates around vertically integrated network operators with direct spectrum licenses, supplemented by regional challengers leveraging regulatory-mandated interconnection. Three archetypes dominate: spectrum-integrated incumbents with legacy infrastructure, cloud-native challengers bypassing PSTN termination, and public safety specialists with dedicated priority routing contracts. Competitive moves center on spectrum auction positioning for 5G voice cores and strategic partnerships with enterprise software vendors for unified communications integration.
Within the spectrum-integrated tier, AT&T Inc. and Verizon Communications Inc. occupy positions defined by their FirstNet and millimeter-wave infrastructure commitments respectively. Deutsche Telekom AG exemplifies the European carrier archetype navigating GDPR constraints while expanding cloud-based enterprise voice services. China Mobile Ltd. anchors the Asia-Pacific volume position through VoLTE subscriber scale across its national footprint.
| Leading Market Players |
|---|
| AT&T Inc. |
| Verizon Communications Inc. |
| China Mobile Ltd. |
| Deutsche Telekom AG |
| SoftBank Group Corp. |
| Nippon Telegraph and Telephone Corporation |
| China Telecom Corp Ltd. |
| Telefonica SA |
| Vodafone Group |
| Others |
Cost & Logistics Intelligence
Captive spectrum licensing anchors both supply positioning and pricing power for mobile voice carriers, as exclusive frequency allocations in the United States, India, and Germany create irreplicable cost structures that downstream buyers cannot arbitrage away. This integration pattern forces enterprise procurement teams to accept carrier-determined subscription tiers or migrate entirely to over-the-top alternatives with degraded quality guarantees.
Pricing Analysis
Bundled voice-data packages dominate consumer segments while unbundled SaaS-tiered subscriptions capture enterprise migration from legacy PBX hardware. Price differentiation rests on quality-of-service tiers and geographic spectrum scarcity, with millimeter-wave 5G deployments commanding premiums over standard LTE voice. Cost compression in commodity voice runs through Reliance Jio's aggressive Indian pricing, which has reset margin expectations across emerging markets. Small and mid-sized enterprises exhibit highest price sensitivity, driving quarterly contract renegotiation cycles, while public safety agencies accept decade-long commitments for priority routing guarantees.
Supply Chain Analysis
Dual-sourcing requirements for network equipment mandate multi-vendor qualification across radio access, core infrastructure, and handset ecosystems, forcing carriers to maintain parallel supplier relationships. Hardware concentration centers on China, South Korea, and Taiwan for baseband processors, radio frequency components, and antenna systems. Codec licensing fees from AMR-WB and EVS patent pools feed from specialized intellectual property holders outside traditional equipment vendors. Single-source vulnerability in advanced semiconductor fabrication constrains 5G voice core deployment timelines. Distribution runs through carrier-direct enterprise sales teams and unbundled channel partners in the United Kingdom and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in mobile voice rests on spectrum efficiency gains from VoLTE and 5G voice cores collapsing per-call infrastructure costs, alongside enterprise upsell into AI-integrated unified communications tiers.
For Market Incumbents: Lock in public safety priority routing contracts with decade-long tenors in Australia and Canada to insulate revenue pools from over-the-top substitution. Accelerate 2G and 3G network sunsetting to reclaim spectrum for high-efficiency voice cores, reducing operational overhead while maintaining rural coverage obligations through regulatory forbearance.
For New Entrants and Emerging Players: Begin with WebRTC gateway deployments for enterprise internal communications in the Netherlands and Singapore, bypassing PSTN termination fees entirely. Target manufacturing verticals in Mexico and Vietnam with month-to-month cloud PBX contracts, as these segments demonstrate strongest preference for zero upfront equipment commitments and fastest evaluation cycles.
For Investors and Strategic Acquirers: Roll-up economics work for regional cloud-native challengers because GDPR data localization mandates fragment service architectures and prevent single-platform dominance across European jurisdictions. Acquire targets with established SIP-I to ISUP interworking expertise, as hybrid deployment talent scarcity creates defensive moats. Watch TRAI interconnect charge rulings as the signal indicating whether Indian pricing pressure exports to other emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Reallocation Partnership | FirstNet agreements with public safety agencies create decade-long revenue visibility for AT&T. |
| AI-Enabled Voice Analytics Integration | Real-time transcription partnerships with Salesforce and HubSpot open enterprise upsell paths. |
| VoLTE Network Sunsetting | Indian carriers under TRAI mandates reclaim 2G spectrum for high-efficiency voice services. |
| WebRTC Gateway Deployment | Dutch and Singaporean IT departments bypass PSTN interconnection for internal communications. |
| Hybrid Cloud PBX Migration | German healthcare providers satisfy GDPR mandates while maintaining TDM trunking for compliance. |
Research Approach
Direct dialogue with carrier network operations executives, enterprise IT procurement officers, regulatory affairs specialists at TRAI and FCC, and channel partner sales directors grounded qualitative findings, validated against secondary sources including spectrum auction records, carrier SEC 10-K filings, Ofcom wholesale pricing determinations, and enterprise unified communications adoption surveys. Bottom-up and top-down triangulation cross-checked subscriber volume estimates against infrastructure deployment disclosures.
Bottom-up modeling aggregated segment-level adoption curves across service type, end user category, access technology, and deployment model dimensions, while top-down analysis calibrated aggregate market expansion against macroeconomic indicators and regulatory milestone timelines. CAGRs derived from fitted growth curves incorporating VoLTE subscriber migration rates, 5G voice core capital deployment schedules, and enterprise cloud PBX subscription trajectories. Industry-specific inputs included spectrum efficiency coefficients for AMR-WB and EVS codecs, and interconnect charge sensitivity elasticities from Indian market dynamics.
Caveats apply where FCC net neutrality rulings, TRAI interconnect mandates, or GDPR data localization enforcement could materially shift the outlook for carrier pricing power and cloud service architectures. Deviation in spectrum auction timing or legacy network sunsetting schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
MVNO Market
Telecommunications
Myanmar Telecom Market
Telecommunications
Video Door Phones Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
Germany ICT Market
Telecommunications
A2P Messaging Market
Telecommunications
IP Telephony Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Global International Calling Apps Market
Telecommunications
Indonesia ICT Market
Telecommunications
Kuwait Telecom Market
Telecommunications
5G Connections Market
Telecommunications
Vietnam ICT Market