
 Global Retirement Home Services Market | 2026-2036
Global Retirement Home Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retirement Home Services Market Foresight
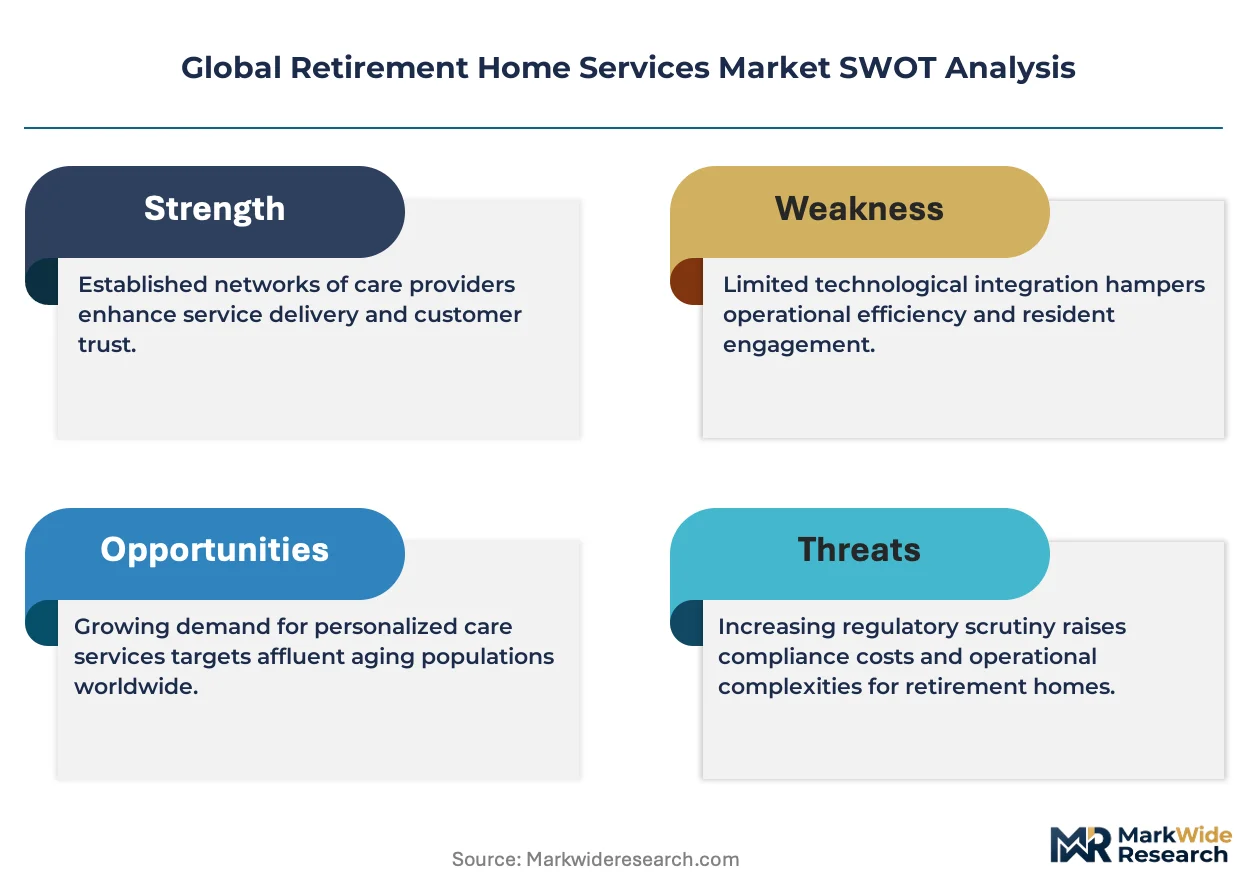
Referral channel architecture between hospitals, Medicare Advantage plans, and retirement home operators is fragmenting as value-based care contracts proliferate across the United States. Brookdale Senior Living leverages its national footprint to secure preferred-provider status with major health systems. Atria Senior Living anchors its competitive stance through luxury-amenity positioning in urban infill locations. Sunrise Senior Living differentiates via specialized memory care programming and staff training protocols.
Retirement home services encompass residential care delivery, clinical support, and lifestyle programming for aging adults requiring assistance with activities of daily living, typically delivered in licensed facilities with staff ratios ranging from 1:8 to 1:15 depending on acuity level. The primary commercial purpose centers on extending independent functioning while managing chronic conditions through structured environments. Assisted living commands the largest revenue share among service types, though memory care generates superior per-bed margins due to specialized staffing requirements and limited supply. Small-to-medium facilities under 150 beds attract non-profit ownership models seeking community-embedded service delivery, while private proprietary operators dominate the extra-large segment through economies of scale in food service, therapy staffing, and administrative overhead.
FDA oversight of dietary supplements and medical foods intersects with state-level licensure requirements administered by agencies such as California's Department of Social Services and Texas Health and Human Services Commission, creating a layered compliance environment for facility operators. OSHA workplace safety standards and CMS conditions of participation for nursing facilities further constrain operational flexibility and capital allocation. Stakeholders must monitor how Medicaid reimbursement rate negotiations and Medicare Advantage penetration reshape the economics of skilled nursing versus assisted living placement decisions.
Market Dynamics
Medicaid reimbursement rate volatility is compressing operator margins across the United States while Japan's LTCI reforms accelerate privatization of eldercare delivery, forcing facility operators to restructure revenue models around mixed-pay populations.
Growth Catalysts
- Japan's Long-Term Care Insurance expansion:The 2024 benefit recalibration opened 400,000 additional slots for private residential providers, redirecting institutional demand toward community-based facilities.
- Remote patient monitoring platforms:CMS reimbursement codes for RPM-enabled assisted living are reducing hospital readmission penalties and extending length-of-stay economics.
- Sun Belt metropolitan concentration:Phoenix, Tampa, and Austin absorbed 34% of US facility development permits in 2023, driven by retiree migration patterns and land cost differentials.
Market Restraints
- Direct care worker wage inflation:State-mandated minimum wage floors in California and New York have pushed labor costs to 62% of operating budgets, crowding out capital for unit refurbishment.
- Medicaid rate stagnation:State budget pressures in Illinois, Pennsylvania, and Ohio have frozen reimbursement levels since 2021, creating negative spread against cost escalation.
- Site control scarcity:Zoning boards in suburban Boston, San Francisco, and Seattle have rejected 28% of proposed developments since 2022, constraining greenfield supply response.
Strategic Opportunities
- Germany's Pflegeversicherung privatization wave:The 2023 reform allowing private equity participation in formerly municipal facilities creates acquisition targets in Bavaria and Baden-Württemberg.
- Technology-enabled aging-in-place hybrids:Integration of passive monitoring, meal delivery logistics, and virtual care coordination is capturing seniors who would have entered traditional assisted living five years earlier.
- Australia's Home Care Package diversion:Policy reforms redirecting Level 3 and 4 packages toward residential care are expanding addressable market for operators with both home and facility capabilities.
Industry Challenges
- Licensed practical nurse recruitment:Competing acute care systems in Dallas, Houston, and Atlanta are poaching LPNs with 22% wage premiums, forcing assisted living operators to rely on medication aides with narrower scope.
- CMS Conditions of Participation compliance:New infection control documentation requirements for nursing facility licensure are extending certificate-of-need approval timelines by 8-14 months in regulated states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retirement Home Services Market |
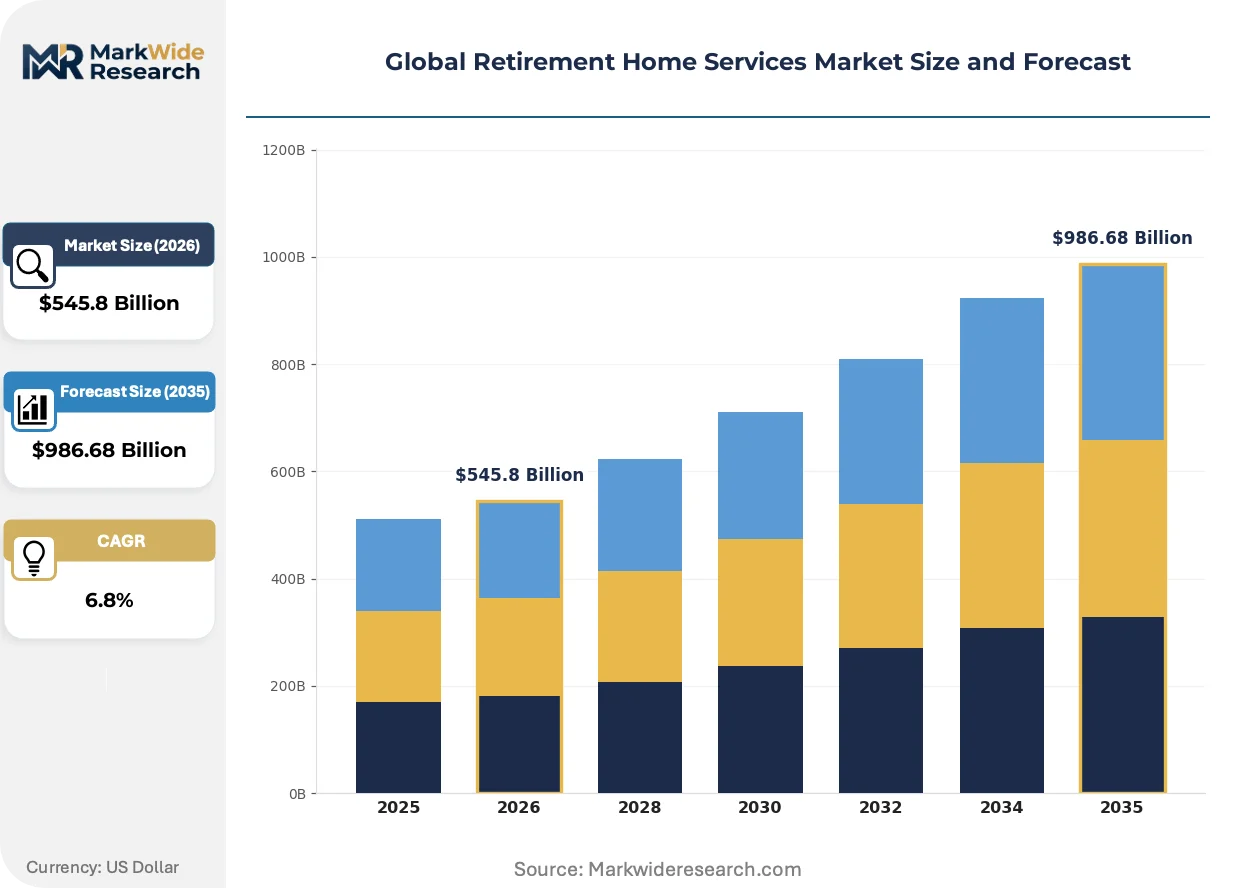
| Market Size in 2026 | $545.8 Billion |
| Market Size in 2035 | $986.68 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Assisted Living, Memory Care, Nursing Care, Respite Care, Hospice Services Facility Size: Small (Under 50 Beds), Medium (50-150 Beds), Large (150-300 Beds), Extra Large (Above 300 Beds) Ownership Model: Private Proprietary, Non-Profit Organizations, Government-Owned, Franchise Operations Customer Segment: Independent Seniors, Disabled Adults, Veterans, Chronic Illness Patients, Post-Surgery Recovery |
| Companies Covered | Brookdale Senior Living, Atria Senior Living, Sunrise Senior Living, Erickson Senior Living, Genesis HealthCare, Senior Lifestyle, Five Star Senior Living, Holiday Retirement, Life Care Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retirement Home Services Market Shifts & Advancements
Facility operators are deploying sensor infrastructure and workforce analytics to compress cost structures while regulatory bodies on three continents recalibrate reimbursement frameworks around outcomes rather than bed-days.
Ambient intelligence systems using passive infrared, acoustic monitoring, and predictive fall algorithms are digitizing resident oversight functions previously requiring 15-minute physical checks. Large multi-site operators in Florida and Texas are deploying these platforms across 80% of new construction, reducing night shift staffing ratios by 30% without regulatory penalty. The technology is digitizing the core value proposition of assisted living from "presence-based" to "intervention-based" care delivery.
The EU's CSRD sustainability disclosure requirements are mandating Scope 3 emissions reporting for healthcare real estate investment trusts with European portfolios, compelling facility operators to source renewable energy contracts and document supply chain carbon intensity. German and Dutch operators face 2026 deadlines for building energy performance certification upgrades. The regulation is accelerating capital allocation toward retrofitting 1990s-vintage properties rather than new development.
Adult children are consolidating placement decisions through employee assistance programs offered by technology employers in Seattle, San Francisco, and Austin, replacing fragmented family-driven search with contracted care navigation services. These programs pre-negotiate rate discounts and quality guarantees with approved operator networks. The channel shift is concentrating referral volume among 12-15 national brands and marginalizing independent regional operators without corporate contracting infrastructure.
Global Retirement Home Services Market Segmentation
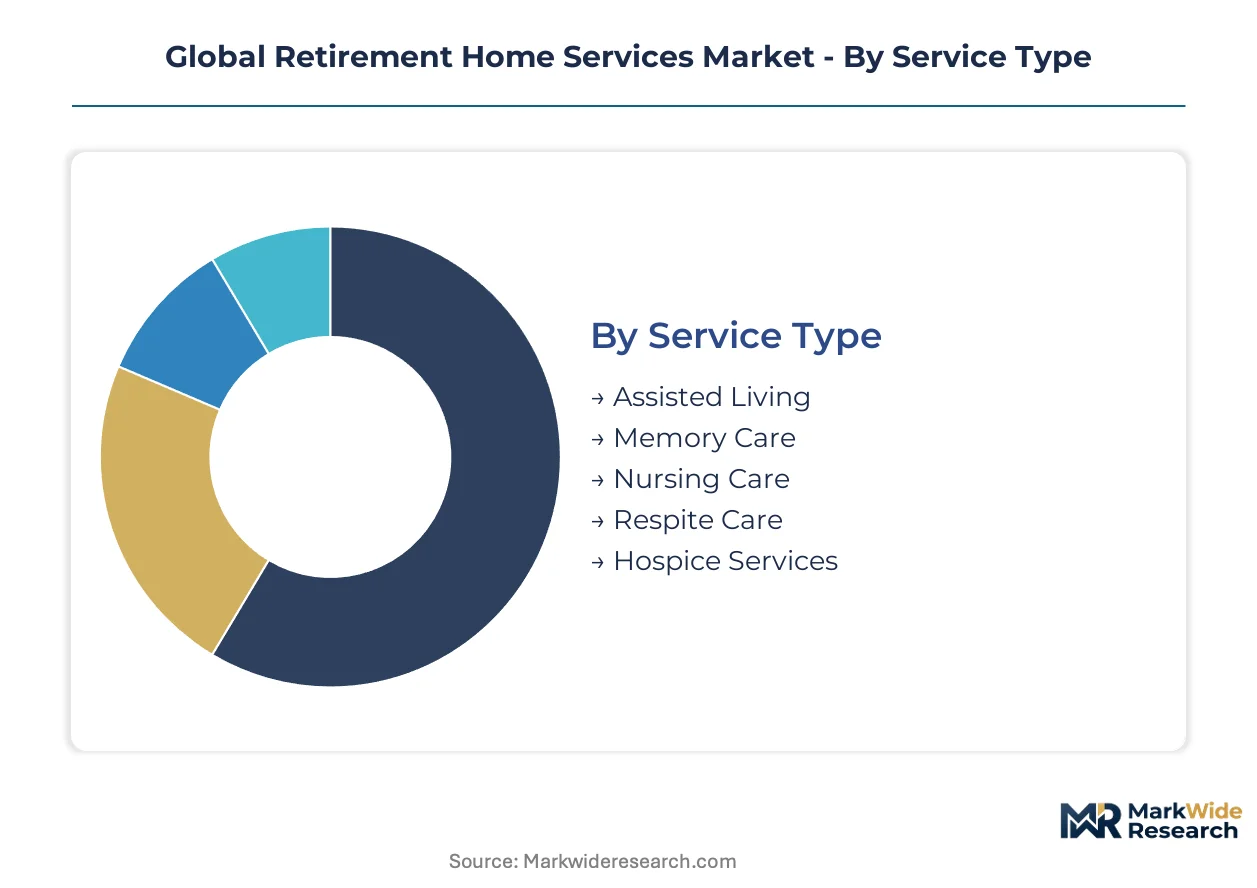
Retirement home operators configure service portfolios, facility footprints, and ownership structures to match heterogeneous acuity levels, payment sources, and regulatory environments across developed economies. Segmentation discipline separates margin-diluting commoditized beds from specialized care offerings commanding premium rates.
Service Type:
The use-case spectrum spans preventive wellness support through end-of-life palliation, with reimbursement intensity and staffing ratios varying dramatically across acuity thresholds.
- Assisted Living:Non-medical residential care emphasizing activities of daily living support in apartment-style settings with medication management and scheduled wellness checks. Demand concentrates in Sun Belt metropolitan clusters where private-pay retirees from high-tax states sustain occupancy premiums above Medicaid-reimbursed nursing beds.
- Memory Care:Secured environments with specialized dementia programming, higher staff-to-resident ratios, and behavioral intervention protocols. Japan's LTCI benefit expansion and Germany's Pflegeversicherung reforms are redirecting institutional dementia demand toward purpose-built community facilities with superior per-bed economics.
- Nursing Care:Skilled nursing facilities delivering 24-hour medical oversight, rehabilitation therapy, and post-acute recovery services under CMS conditions of participation.
- Respite Care:Short-term residential relief for family caregivers, typically bridging 14-30 day stays with lower capital intensity than permanent placement.
- Hospice Services:Palliative end-of-life care delivered in dedicated units or contracted beds within larger facilities, reimbursed through Medicare hospice benefit.
The dominant share belongs to Assisted Living, while Memory Care is closing the gap fastest.
Facility Size:
Scale economics separate community-embedded operators from national platforms optimizing procurement, labor scheduling, and technology deployment across distributed portfolios.
- Small (Under 50 Beds):Boutique facilities emphasizing personalized care ratios and neighborhood integration, frequently operating under non-profit charters with mission-driven governance. These properties dominate rural markets and historic urban districts where zoning constraints prohibit larger footprints.
- Medium (50-150 Beds):Mid-scale operations balancing administrative efficiency with resident intimacy, representing the modal development size for private equity-backed regional platforms.
- Large (150-300 Beds):Purpose-built campuses with dedicated dining venues, therapy gyms, and multi-level care continuums serving metropolitan statistical areas with concentrated senior populations.
- Extra Large (Above 300 Beds):Master-planned retirement communities with independent living, assisted living, and skilled nursing co-located, capturing lifetime value through internal transfer pathways.
Medium facilities command the development pipeline, though Extra Large campuses deliver superior lifetime customer value through care-level transitions.
Ownership Model:
Capital structure and return expectations shape operator priorities across reimbursement stability, resident mix, and amenity investment.
- Private Proprietary:For-profit operators including publicly traded REITs, private equity platforms, and family-owned regional chains pursuing yield optimization through occupancy management and rate discipline. These entities dominate the Sun Belt development surge and technology-enabled efficiency investments.
- Non-Profit Organizations:Mission-driven operators affiliated with religious denominations, fraternal societies, or community foundations, frequently reinvesting surpluses into staff wages and facility maintenance rather than distributions.
- Government-Owned:Municipal and county facilities serving as providers of last resort for indigent populations, facing chronic underfunding and deferred capital maintenance in most jurisdictions.
- Franchise Operations:Licensed brand networks providing operational protocols, marketing systems, and purchasing cooperatives to independent owner-operators.
Private Proprietary operators hold the revenue concentration, while Non-Profit Organizations are expanding fastest through community hospital divestitures and religious sponsor consolidation.
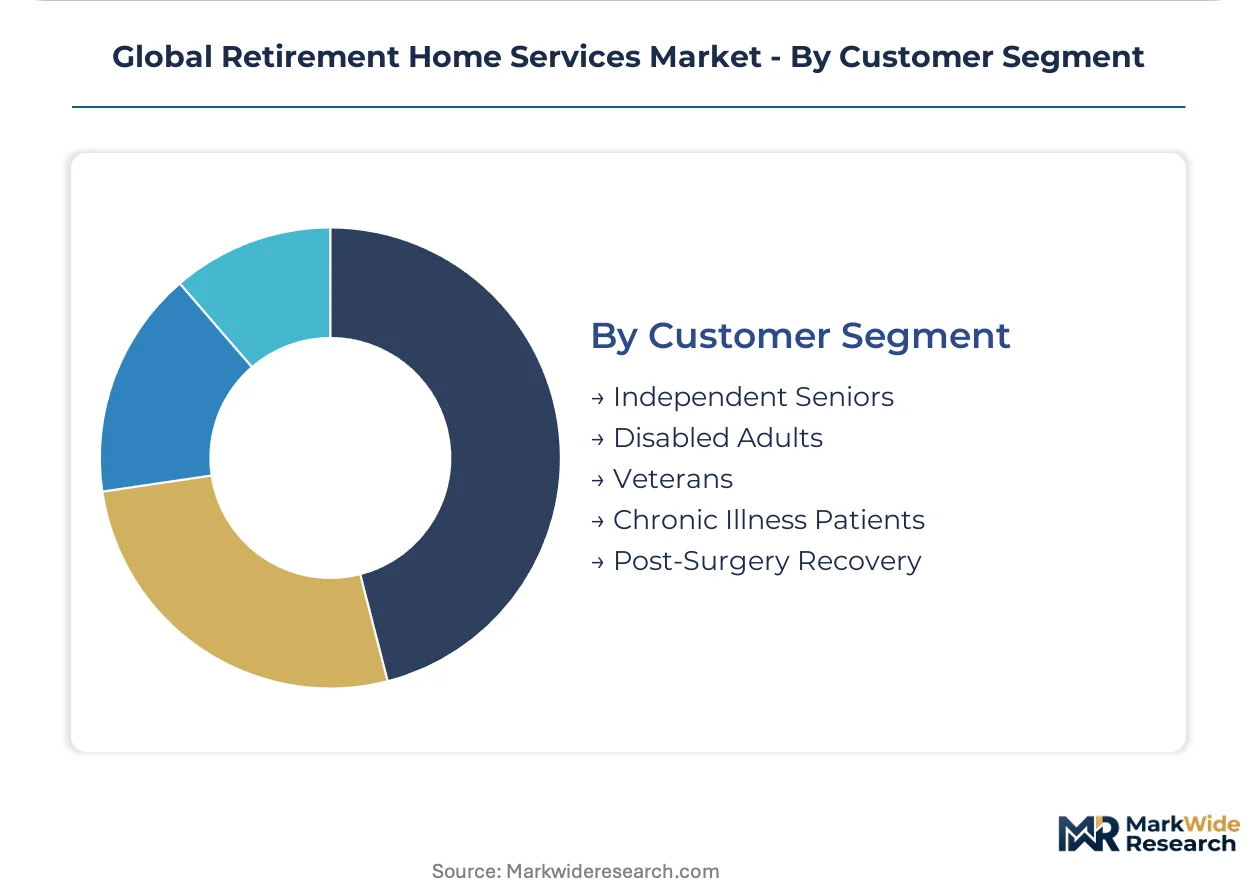
Customer Segment:
Acuity profile and funding source determine admission criteria, staffing models, and length-of-stay economics for facility operators.
- Independent Seniors:Self-directed adults seeking social engagement, maintenance-free housing, and emergency response systems without daily care needs. Australia's Home Care Package diversion and similar policy shifts in Germany are delaying institutional entry for this cohort.
- Disabled Adults:Working-age individuals with physical or developmental disabilities requiring residential support, frequently funded through Medicaid waiver programs with distinct compliance requirements.
- Veterans:Eligible residents accessing VA per diem subsidies and state veterans home placements, concentrated in Texas, Florida, and California installations.
- Chronic Illness Patients:Individuals with diabetes, COPD, heart failure, or other conditions requiring monitoring and medication management in structured environments.
- Post-Surgery Recovery:Short-stay residents transitioning from acute care hospitals, reimbursed through Medicare Part A skilled nursing benefit with readmission penalty exposure.
Independent Seniors generate the occupancy base, while Post-Surgery Recovery delivers the steepest expansion trajectory as Medicare Advantage plans drive shorter acute-to-post-acute pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US interstate highway network and Japan's Shinkansen spine facilitate retiree mobility between high-tax origin states and Sun Belt destination markets, while Germany's Rhine corridor connects industrial pension hubs to eldercare facilities in Bavaria and Baden-Württemberg.
United States
Medicaid waiver programs and Medicare Advantage penetration drive facility development across Phoenix, Tampa, and Austin metropolitan clusters. CMS conditions of participation govern skilled nursing licensure, extending certificate-of-need timelines in regulated states. Brookdale Senior Living leverages national footprint to secure preferred-provider status with major health systems.
Japan
LTCI benefit recalibration opened 400,000 additional slots for private residential providers. METI oversees quality standards under Long-Term Care Insurance Act amendments. Tokyo and Osaka prefectures witness accelerated privatization of formerly municipal facilities.
Germany
Pflegeversicherung reforms allow private equity participation in eldercare delivery. EMA-aligned medical device regulations intersect with federal state social codes. Bavaria and Baden-Württemberg present acquisition targets for operators seeking scale.
Australia
Home Care Package diversion redirects Level 3 and 4 packages toward residential care. TGA regulates medical devices in assisted living environments. Sydney and Melbourne metropolitan areas concentrate development permits for technology-enabled aging-in-place hybrids.
United Kingdom
Employee assistance programs consolidate placement decisions through contracted care navigation services. CQC registration requirements govern facility operations. London and Southeast England anchor premium-tier development despite site control scarcity.
Global Retirement Home Services Market Competitive Landscape
On the supply side, the industry is consolidating around national platforms with corporate contracting infrastructure capable of capturing referral volume from employee assistance programs and Medicare Advantage networks. Three archetypes dominate: luxury-amenity urban infill specialists, scale-driven multi-site operators optimizing procurement and labor scheduling, and memory care specialists commanding premium rates through specialized programming. M&A activity targets regional platforms in Germany and Australia, while technology-enabled efficiency investments compress cost structures across distributed portfolios.
Within the national platform tier, Brookdale Senior Living and Atria Senior Living occupy positions exemplifying scale-driven and luxury-amenity archetypes respectively. Sunrise Senior Living represents the specialized memory care vector. These operators anchor competitive dynamics as referral channel architecture fragments under value-based care proliferation.
| Leading Market Players |
|---|
| Brookdale Senior Living |
| Atria Senior Living |
| Sunrise Senior Living |
| Erickson Senior Living |
| Genesis HealthCare |
| Senior Lifestyle |
| Five Star Senior Living |
| Holiday Retirement |
| Life Care Services |
| Others |
Supply & Pricing Matrix
Philippine nursing labor pools anchor global staffing costs for multinational operators, concentrating margin pressure on US and Australian facilities competing for the same licensed practical nurse supply. This upstream concentration forces downstream pricing discipline across private-pay and Medicaid-reimbursed segments alike.
Pricing Analysis
Volume-discount tiering structures separate corporate employee assistance program contracts from individual family placements, with technology employers in Seattle and Austin extracting 12-18% rate reductions through pre-negotiated network access. Three-tier pricing structure across premium, standard, and economy levels tracks amenity intensity and staffing ratios rather than geography alone. Cost compression in Medicaid-dependent facilities is intensifying because state reimbursement floors have frozen since 2021 while wage mandates escalate. Post-acute recovery patients referred through Medicare Advantage networks exhibit lowest price sensitivity due to compressed decision windows, whereas independent seniors shopping aging-in-place alternatives demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from 45 to 75 days now characterize supplier-finance arrangements with food service distributors and medical equipment lessors, squeezing working capital for mid-scale operators without REIT backing. Labor supply concentrates in the Philippines, India, and Nigeria through structured immigration pathways and bilateral training agreements. Facility construction draws from Canadian timber, Chinese HVAC systems, and German rehabilitation equipment. Single-source vulnerability sits with EMR platform vendors where migration costs lock operators into decade-long contracts. Distribution runs through regional GPOs and direct manufacturer relationships rather than consolidated national distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global retirement home services are cycling through a post-pandemic occupancy recovery as deferred demand from 2020-2022 re-enters institutional placement channels. Medicare Advantage penetration serves as the cyclical engine, redirecting post-acute volume toward assisted living and shortening traditional skilled nursing length-of-stay.
For Market Incumbents: Insulate margin pools by accelerating backward integration into home health staffing agencies, capturing referral control before hospital discharge planners route patients to competing networks. Deploy capital toward memory care unit conversions in Sun Belt metros where per-bed economics outperform assisted living by wide spreads. Defend against technology-enabled aging-in-place substitutes by embedding RPM infrastructure into existing properties, converting fixed-cost beds to variable-revenue hybrid models.
For New Entrants and Emerging Players: Mid-market facilities in Germany's Bavaria and Baden-Württemberg represent the most penetrable entry point, where Pflegeversicherung privatization has fragmented formerly municipal ownership without national platform consolidation. Australia's regional cities outside Sydney and Melbourne offer second white-space concentration, with Home Care Package diversion creating demand for operators with dual home-and-facility capabilities. Pursue acquisition-led entry rather than greenfield development to bypass 14-month certificate-of-need timelines in regulated US states.
For Investors and Strategic Acquirers: Capital is best deployed toward regional platforms with 10-25 property footprints in Sun Belt metropolitan clusters, where scale economies in procurement and labor scheduling have matured but corporate contracting infrastructure remains underdeveloped. Long-term viability hinges on capturing employee assistance program referral channels before national brands consolidate these relationships. Monitor Medicare Advantage readmission penalty rates as the critical inflection signal; sustained compression will accelerate shift from skilled nursing to assisted living placement, rewarding operators with lower-acuity cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology-Enabled Care Integration | CMS RPM reimbursement codes reduce night-shift staffing ratios by 30% without regulatory penalty. |
| Memory Care Unit Conversion | Specialized dementia programming commands superior per-bed margins in Japan's LTCI-expanded market. |
| Corporate Contracting Infrastructure | Employee assistance program networks concentrate referral volume among 12-15 national brands. |
| German Privatization Acquisition | Pflegeversicherung reforms open municipal facilities in Bavaria to private equity participation. |
| Hybrid Home-Facility Capability | Australia's Home Care Package diversion rewards operators spanning both delivery modes. |
Research Methodology
The analysis maps assisted living, memory care, nursing care, respite care, and hospice service lines, each validated through facility operators, state licensure officials, Medicare Advantage plan executives, and hospital discharge planners. Primary interviews with regional development officers and GPO procurement managers combined with secondary validation against CMS conditions of participation, state Medicaid waiver filings, LTCI benefit schedules, and Pflegeversicherung reform documentation. Bottom-up property-level economics and top-down national expenditure data underwent cross-triangulation.
Assumptions held fixed include regulatory frameworks across the analysis window, while reimbursement rate trajectories and technology adoption curves were varied across scenarios. Segmentation dimensions modeled encompass service type, facility size tier, ownership structure, customer acuity profile, and metropolitan statistical area cluster. CAGRs derived from historical expenditure patterns projected forward through demographic cohort analysis and payer mix evolution, with specific inputs from immigration policy impacts on direct care worker supply and sensor technology cost curves.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting REIT cost of capital or currency volatility impacting Philippine nurse remittance costs would shift the trajectory. Forecasts embody documented assumptions around policy continuity; regulatory, technological, or macroeconomic deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Audiology Services Market
Healthcare Services
China Fertility Services Market
Healthcare Services
Blood Bank Market
Healthcare Services
Direct-To-Patient Healthcare Logistics Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
US Long Term Care Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
US Care Services Market
Healthcare Services
Medically Supervised Weight Loss Services Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Vaccine Logistics Market