
 Global Medical Device Cleaning Market | 2026-2036
Global Medical Device Cleaning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Device Cleaning Market Foresight
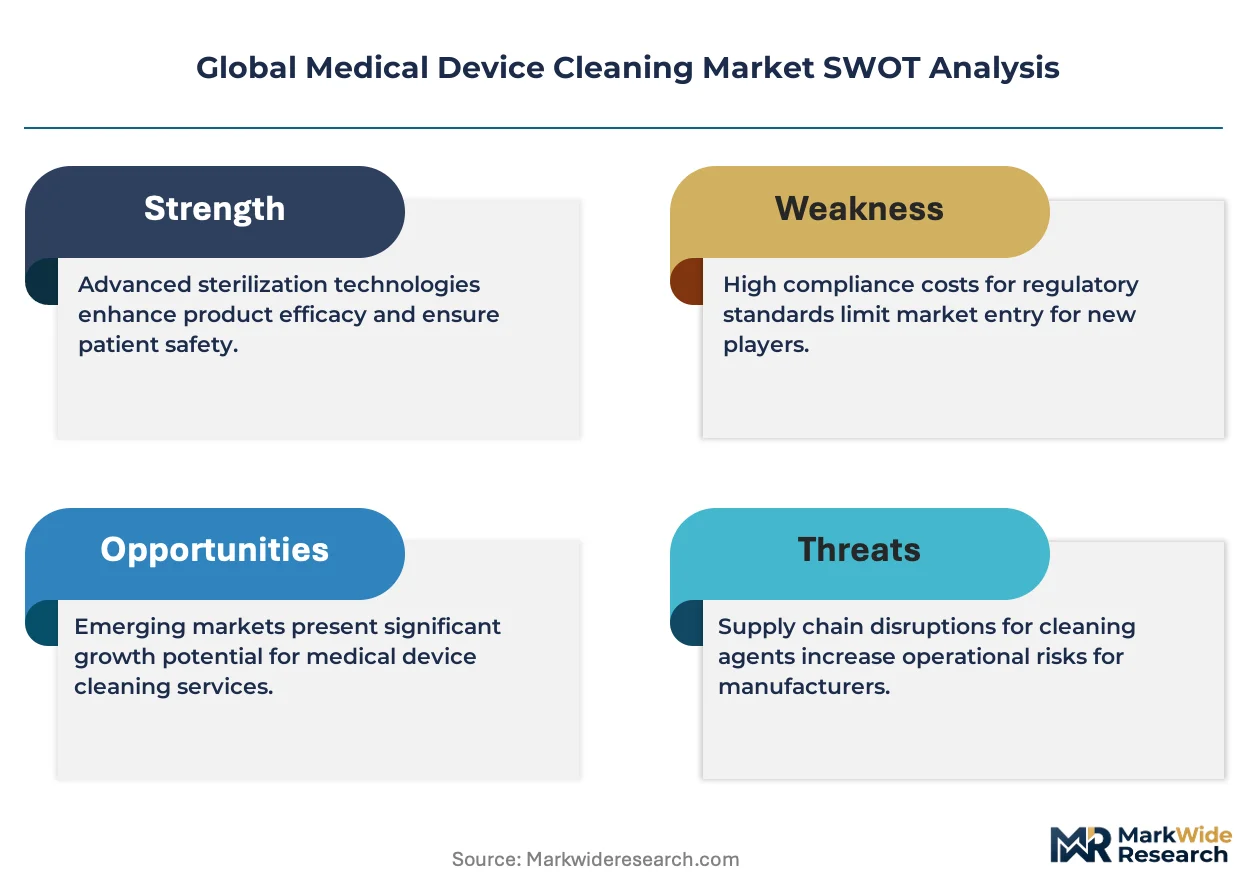
Ambulatory surgical centers is reorganizing procurement priorities for medical device cleaning systems, shifting volume from centralized hospital sterile processing departments toward smaller-footprint automated platforms. STERIS plc leverages its installed base of washer-disinfectors to sustain service-contract revenue across outpatient networks. Getinge Group anchors European market presence through dedicated endoscope reprocessing divisions. Ecolab Inc. competes on chemical formulation density, offering concentrated enzymatic detergents that reduce shipping volumes for distributed clinic sites.
Medical device cleaning encompasses the validated removal of biological soil, pharmaceutical residues, and particulate matter from reusable instruments through mechanical, chemical, or thermal processes, with critical parameters including water purity measured at <0.1 endotoxin units per milliliter and cleaning efficacy verified through protein residual testing. Washer-disinfectors and automated cleaners dominate capital expenditure budgets due to labor substitution benefits and traceability requirements, while enzymatic technology leads consumable demand because protease-lipase-amylase formulations dissolve fixed organic matter faster than neutral detergents alone. Endoscope application segments command premium pricing given narrow-lumen geometries and biofilm persistence risks that exceed requirements for standard surgical instruments.
FDA enforces reprocessing validation under 21 CFR 820 quality system regulations, while EPA governs effluent discharge from cleaning chemistries through Clean Water Act permits; in Europe, MDR and REACH jointly constrain both device biocompatibility and chemical environmental fate. These layered compliance obligations compel manufacturers to maintain dual regulatory dossiers for transatlantic product registration. Stakeholders must monitor evolving validation standards for novel materials such as additive-manufactured titanium lattice structures that challenge conventional soil removal verification methods.
Market Dynamics
Outpatient surgical migration is compressing reprocessing footprints, forcing manufacturers to miniaturize washer-disinfector architectures without sacrificing FDA 21 CFR 820 validation protocols. Ambulatory surgical centers now demand single-cycle traceability that matches hospital sterile processing departments.
Growth Catalysts
- EPA effluent mandates:Clean Water Act permit tightening accelerates capital replacement of legacy cleaning chemistries with closed-loop water recovery systems in United States outpatient facilities.
- Additive manufacturing:Titanium lattice implants with internal porosities require validated cleaning protocols that standard brush-based methods cannot achieve, creating specialized equipment demand.
- Japan surgical volume:METI demographic projections show accelerated day-surgery expansion through 2035, concentrating enzymatic detergent procurement in Tokyo-Osaka corridor.
Market Restraints
- Isopropyl alcohol feedstock volatility:Solvent-based disinfectant formulations face input cost swings tied to propylene cracking economics, compressing margin on low-concentration retail products.
- Single-use device substitution:Cardiac catheter and endoscope manufacturers are expanding disposable portfolios that bypass reprocessing entirely, threatening reusable instrument cleaning volume in electrophysiology labs.
- REACH authorization delays:ECHA scrutiny of quaternary ammonium compounds extends formulation registration timelines, freezing product line extensions for European chemical suppliers.
Strategic Opportunities
- Germany MDR implementation:Notified body bottlenecks create temporary service gaps where third-party validated cleaning-as-a-service models can capture outsourced sterile processing from overwhelmed hospitals.
- Enzyme-detergent convergence:Protease-lipase-amylase blends combined with surfactant micelle technology enable single-step cleaning that reduces cycle time and water consumption for high-throughput ambulatory centers.
- Direct-to-clinic distribution:Bypassing traditional hospital supply chain intermediaries allows concentrated chemical manufacturers to capture margin and secure multi-year service contracts with United States multi-site surgery networks.
Industry Challenges
- Validation engineer scarcity:FDA 510(k) cleaning validation protocols require specialized microbiology and materials science expertise that outpatient facilities cannot staff internally, creating dependency on third-party consultants.
- Legacy washer-disinfector integration:New enzymatic formulations must demonstrate compatibility with existing thermal disinfection cycles without triggering alarm protocols or chamber corrosion in decade-old capital equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Device Cleaning Market |
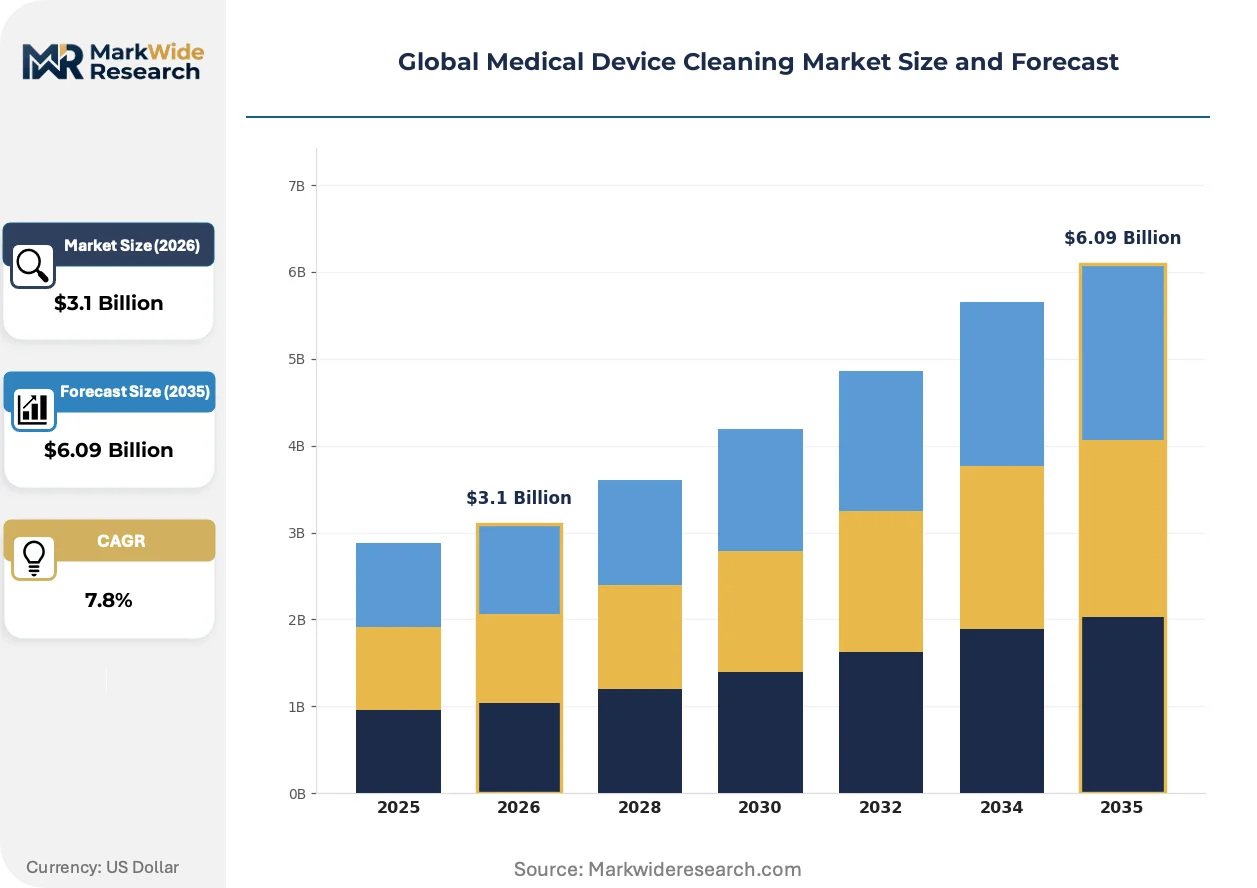
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Cleaners, Ultrasonic Cleaners, Manual Cleaning, Washer-Disinfectors, Sterile Processing Equipment Application: Surgical Instruments, Endoscopes, Dental Tools, Hospital Instruments, Laboratory Devices End User: Hospitals, Ambulatory Care Centers, Clinical Laboratories, Research Institutes, Specialty Clinics Technology: Enzymatic, Detergent Cleaning, Drying Systems, Steam Cleaning, Chemical Sterilization |
| Companies Covered | STERIS plc, Getinge Group, 3M, Ecolab Inc., Cantel Medical Corporation, Ruhof Corporation, Advanced Sterilization Products, Metrex Research, LLC, BODE Chemie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Device Cleaning Market Shifts & Advancements
Reprocessing technology is bifurcating between hospital-scale automation and clinic-scale minimalism, with regulatory validation requirements remaining constant across both footprints. This tension drives divergent R&D investment patterns among equipment manufacturers.
Single-use enzymatic detergent pods are fragmenting bulk chemical purchasing in ambulatory surgical centers. These pre-measured units eliminate dilution error and reduce storage requirements for space-constrained outpatient facilities. STERIS and Ecolab are accelerating pod format launches to defend installed base relationships as smaller-footprint competitors enter with cartridge-based alternatives.
EU MDR Article 10 technical documentation requirements now mandate cleaning validation data for all reusable surgical instruments, extending liability to device manufacturers rather than end-user facilities. German notified bodies are enforcing this through enhanced audit protocols. Japanese PMDA is observing EU implementation before drafting parallel guidance, creating temporary regulatory arbitrage for exporters.
After-sales service unbundling is separating equipment maintenance contracts from chemical supply agreements in United States procurement. Ambulatory surgery chains now negotiate washer-disinfector service independently from enzymatic detergent purchasing, compressing bundled pricing power for integrated suppliers. This pattern is most advanced in Texas and Florida where multi-site surgery networks have achieved sufficient scale to justify dedicated sterile processing technicians.
Global Medical Device Cleaning Market Segmentation
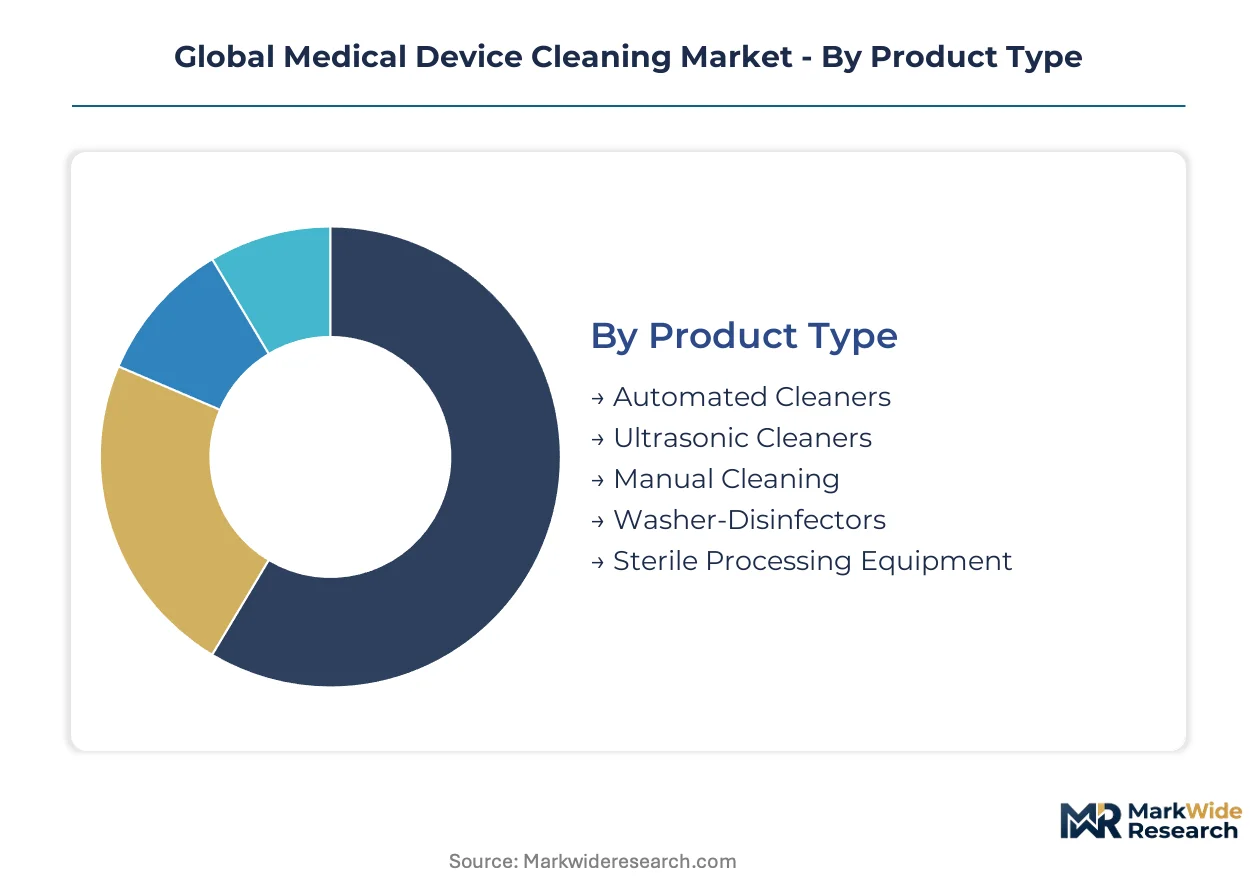
Segmentation in medical device cleaning reveals divergent margin capture between capital-intensive equipment platforms and recurring consumable formulations. Procurement patterns split sharply between hospital-scale sterile processing departments and ambulatory surgical centers with constrained footprints.
Product Type:
Washer-disinfectors and automated platforms concentrate the highest capital margins, while manual cleaning supplies compete on volume throughput.
- Automated Cleaners:Robotic washing platforms integrate thermal disinfection cycles with automated loading systems. Demand clusters in United States multi-site ambulatory surgery networks seeking labor substitution and FDA 21 CFR 820 traceability compliance.
- Ultrasonic Cleaners:Cavitation-based units deploy high-frequency sound waves to dislodge soil from complex instrument geometries. German dental laboratories and Japanese precision device manufacturers specify these for additive-manufactured titanium lattice implants where brush access fails.
- Manual Cleaning:Brush-and-detergent protocols persist for delicate flexible endoscopes and legacy instrument sets.
- Washer-Disinfectors:Thermal disinfection chambers dominate hospital sterile processing department capital budgets.
- Sterile Processing Equipment:Integrated lines combine washing, disinfection, and sterilization in continuous workflow configurations.
Washer-disinfectors hold installed capacity. Automated cleaners are rotating up the share rankings.
Application:
Endoscope reprocessing commands premium pricing multiples due to narrow-lumen biofilm risks and FDA validation stringency.
- Surgical Instruments:Standard scalpels, forceps, and retractors require validated removal of biological soil and pharmaceutical residues. United States hospital sterile processing departments drive volume through high surgical throughput and Joint Commission audit pressure.
- Endoscopes:Flexible gastrointestinal and bronchoscopy devices present tortuous channel geometries where biofilm persistence exceeds standard instrument contamination profiles. Tokyo-Osaka corridor clinics in Japan and German university hospitals concentrate demand for automated reprocessing with single-use scope alternatives threatening volume.
- Dental Tools:Handpieces and ultrasonic scalers require rapid turnaround in high-volume practice settings.
- Hospital Instruments:General ward equipment including infusion pumps and monitoring devices.
- Laboratory Devices:Pipettes, centrifuge rotors, and analytical instrument components.
Endoscopes absorb the steepest pricing premiums. Surgical instruments maintain baseline volume scale.
End User:
Ambulatory surgical centers are displacing hospital procurement share fastest as outpatient migration accelerates capital equipment miniaturization.
- Hospitals:Centralized sterile processing departments operate washer-disinfector fleets with dedicated validation engineering staff. United States health systems and German Klinikum networks sustain demand for high-throughput automated platforms with integrated water purification.
- Ambulatory Care Centers:Freestanding surgery facilities demand compact footprint equipment with single-cycle traceability matching hospital standards. Texas and Florida multi-site networks negotiate unbundled service contracts separating equipment maintenance from chemical supply.
- Clinical Laboratories:Diagnostic testing facilities require specialized cleaning for analytical precision.
- Research Institutes:Academic and pharmaceutical research operations with protocol-specific contamination control.
- Specialty Clinics:Ophthalmology, urology, and pain management focused practices.
Hospitals retain the deepest installed base. Ambulatory care centers are climbing the fastest in procurement growth.
Technology:
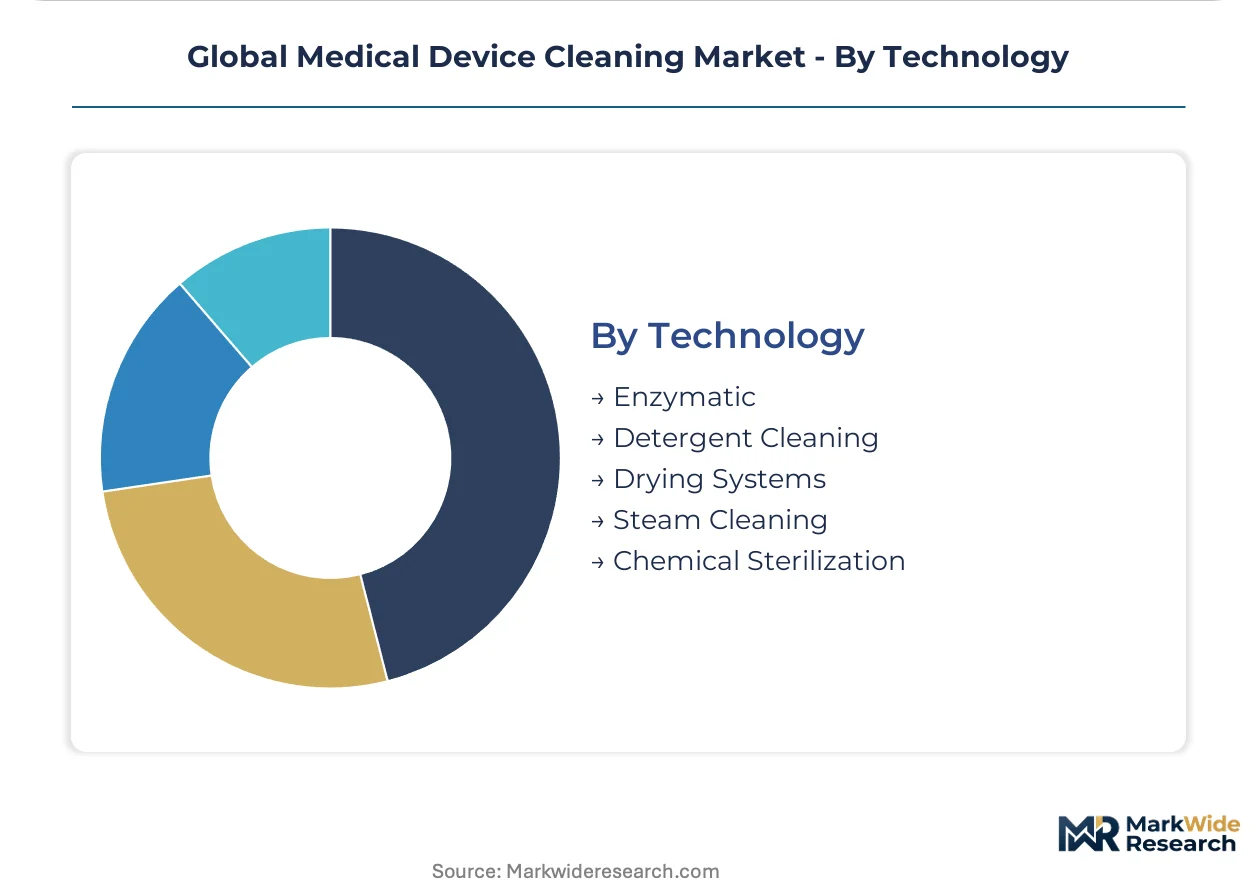
Enzymatic formulations capture recurring revenue streams through protease-lipase-amylase blend chemistry that outperforms neutral detergents on fixed organic matter.
- Enzymatic:Protease-lipase-amylase detergent blends dissolve protein, fat, and carbohydrate residues through catalytic hydrolysis. Concentrated formulations reduce shipping volumes for distributed United States clinic sites while REACH authorization delays in Europe freeze quaternary ammonium compound alternatives.
- Detergent Cleaning:Surfactant-based neutral and alkaline chemistries provide baseline soil removal for standard surgical instruments. German chemical suppliers and Japanese formulators compete on micelle technology integration with enzyme blends for single-step protocols.
- Drying Systems:Forced-air and vacuum-assisted moisture removal prevents corrosion and biofilm regrowth.
- Steam Cleaning:Saturated steam under pressure for pre-sterilization soil reduction.
- Chemical Sterilization:Peracetic acid and glutaraldehyde-based high-level disinfection.
Enzymatic technology commands formulation premiums. Detergent cleaning maintains broad compatibility coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles handles concentrated medical device imports that feed West Coast sterile processing supply chains. German rail corridors connect chemical manufacturing clusters in the Rhine-Ruhr region to hospital networks across Central Europe. Japan's Shinkansen freight integration enables rapid distribution of enzymatic formulations from Osaka production facilities to Tokyo surgical centers.
United States
Texas and Florida multi-site ambulatory surgery networks negotiate unbundled service contracts separating equipment maintenance from chemical supply. FDA enforces reprocessing validation under 21 CFR 820 quality system regulations with escalating audit frequency. The Dallas-Fort Worth corridor concentrates third-party sterile processing facilities serving outpatient migration from traditional hospital settings.
Germany
Klinikum hospital networks sustain demand for high-throughput automated platforms with integrated water purification systems. EU MDR Article 10 technical documentation requirements mandate cleaning validation data for all reusable surgical instruments through enhanced notified body audit protocols. The Rhine-Main region around Frankfurt anchors chemical formulation manufacturing for enzymatic detergent exports.
Japan
METI demographic projections show accelerated day-surgery expansion through 2035, concentrating enzymatic detergent procurement in the Tokyo-Osaka corridor. PMDA observes EU MDR implementation before drafting parallel guidance, creating temporary regulatory arbitrage for exporters. The Nagoya manufacturing belt produces precision washer-disinfector components for domestic installation and Asian export.
United Kingdom
NHS sterile processing departments face capital budget compression while maintaining Joint Commission-equivalent audit standards. MHRA transitional arrangements for EU MDR recognition extend device registration timelines, delaying new cleaning chemistry approvals. The Cambridge-Oxford-London triangle concentrates research-intensive medical device development requiring specialized reprocessing validation.
India
CDSCO medical device rules expansion brings reusable instrument cleaning under formal regulatory scope for the first time. Government hospital procurement favors cost-optimized manual cleaning protocols over capital-intensive automation. The Maharashtra-Gujarat industrial corridor manufactures washer-disinfector components for domestic assembly and regional export to Southeast Asian markets.
Global Medical Device Cleaning Market Competitive Landscape
Concentration sits with diversified infection control conglomerates that bundle equipment, chemicals, and validation services. The market structure shows moderate consolidation at the top tier with fragmented competition among regional chemical formulators and specialized equipment fabricators. Two strategic archetypes dominate: integrated platform providers spanning washer-disinfectors through enzymatic detergents, and focused chemical specialists competing on formulation density and shipping efficiency. Dominant competitive moves include unbundling of after-sales service contracts from chemical supply agreements, and geographic expansion through third-party validated cleaning-as-a-service models.
Among diversified platform providers, STERIS plc and Getinge Group exemplify the integrated archetype spanning capital equipment through recurring consumable revenue. Ecolab Inc. occupies a distinct position as a chemical formulation specialist competing on concentrated enzymatic detergent density that reduces logistics costs for distributed clinic sites. These three companies represent contrasting strategic postures within a market where procurement unbundling is compressing traditional bundled pricing power.
| Leading Market Players |
|---|
| STERIS plc |
| Getinge Group |
| 3M |
| Ecolab Inc. |
| Cantel Medical Corporation |
| Ruhof Corporation |
| Advanced Sterilization Products |
| Metrex Research, LLC |
| BODE Chemie GmbH |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for concentrated enzymatic detergents from German chemical clusters compress margin capture for distributed United States clinic networks while reinforcing pricing power at formulation origin. This inventory-to-delivery gap shapes procurement negotiations between ambulatory surgery chains and integrated platform providers.
Pricing Analysis
Volume-discount tiering separates multi-site ambulatory networks purchasing washer-disinfector service contracts from independent clinics buying single-use enzymatic pods at list price. Certification-grade differentiation between FDA 510(k) validated formulations and standard chemistries widens spreads. Pricing pressure stems from unbundled procurement separating equipment maintenance from chemical supply agreements. Independent specialty clinics exhibit highest price sensitivity; hospital sterile processing departments with GPO contracts show lowest.
Supply Chain Analysis
Germany and the United States anchor enzymatic detergent formulation, while Japan produces precision washer-disinfector components for Asian export. Supply chains draw from petrochemical feedstocks for surfactant bases and specialized fermentation capacity for protease-lipase-amylase blends. Single-source vulnerability concentrates in quaternary ammonium compound precursors facing REACH authorization delays. Distribution runs through hospital supply chain intermediaries and direct-to-clinic channels serving multi-site surgery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where interoperability between washer-disinfector telemetry and enzymatic dosing systems creates ecosystem lock-in. Single-use device substitution in endoscopy accelerates the urgency of integrated reprocessing platform defense.
For Market Incumbents: Secure validation-engineering talent pools through acquisition of third-party sterile processing consultants as FDA 21 CFR 820 audit frequency escalates. Deepen backward integration into concentrated enzymatic formulation manufacturing to defend margin compression from chemical feedstock volatility. Channel control through direct-to-clinic distribution contracts with Texas and Florida multi-site networks reinforces installed base relationships against cartridge-based entrants. For New Entrants and Emerging Players: Lead with single-use enzymatic pod formats targeting space-constrained ambulatory surgical centers in the Tokyo-Osaka corridor where METI day-surgery expansion concentrates demand. White-space exists in cleaning-as-a-service models for German Klinikum networks overwhelmed by EU MDR Article 10 technical documentation requirements. Go-to-market through third-party validation partnerships bypasses internal FDA 510(k) expertise gaps. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because consumable enzymatic chemistry generates predictable replacement demand tethered to surgical volume. Acquisition targets include regional chemical formulators with REACH-authorized quaternary ammonium portfolios and specialized ultrasonic cleaner fabricators serving additive-manufactured implant niches. Watch FDA guidance on novel material cleaning validation as inflection signal for equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cleaning-as-a-Service Model Launch | Captures outsourced sterile processing from German hospitals facing EU MDR notified body bottlenecks. |
| Enzyme-Detergent Convergence R&D | Reduces cycle time and water consumption for high-throughput United States ambulatory centers. |
| Direct-to-Clinic Distribution Expansion | Bypasses hospital supply intermediaries to secure multi-year contracts with surgery networks. |
| Third-Party Validation Partnership | Addresses FDA 510(k) expertise scarcity constraining outpatient facility compliance capacity. |
| Single-Use Pod Format Introduction | Eliminates dilution error and storage constraints for space-constrained clinic sites. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with sterile processing department managers, biomedical engineers, GPO contracts managers, and ambulatory surgery center administrators; and secondary validation through FDA 510(k) filings, EPA Clean Water Act permit databases, hospital procurement records, and EU MDR notified body audit protocols. Bottom-up equipment installation counts and top-down chemical consumption estimates were triangulated against surgical volume projections.
Across the projection horizon, the analytical framework modeled demand by product type, application, end-user facility scale, and technology chemistry class. CAGRs were derived from surgical migration trends, regulatory enforcement intensity, and capital replacement cycles. Forecast inputs included METI demographic projections for Japanese day-surgery expansion and EPA effluent mandate implementation timelines.
Forecasts assume regulatory continuity in FDA 21 CFR 820 quality system enforcement and EU MDR Article 10 technical documentation requirements; material policy shifts would require re-modeling. Specific risks include accelerated single-use device substitution in electrophysiology, REACH authorization delays freezing European chemical product lines, and isopropyl alcohol feedstock volatility disrupting solvent-based disinfectant margins. Recalibration cycles align with material shifts in surgical volume migration patterns and regulatory validation standard updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Biologic Injectors Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Otoscope Devices Market