
 Meningitis Diagnosis and Treatment Market | 2026-2036
Meningitis Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Meningitis Diagnosis and Treatment Market Outlook
Hospital procurement channels are rewriting how meningitis diagnostics reach end users, with group purchasing organizations and integrated delivery networks consolidating vendor selection into fewer decision points. Pfizer Inc. leverages its vaccine manufacturing scale to secure long-term supply contracts with national immunization programs. Roche Holding AG anchors the molecular diagnostics segment through automated PCR platforms deployed across reference laboratories. Sanofi S.A. competes in the conjugate vaccine space with formulations targeting multiple serogroups.
Meningitis diagnosis and treatment encompasses the clinical identification of meningeal inflammation through cerebrospinal fluid analysis, pathogen detection via nucleic acid amplification, and therapeutic intervention with bactericidal or viricidal agents achieving adequate blood-brain barrier penetration. The primary purpose is to reduce mortality and neurological sequelae from bacterial, viral, and fungal CNS infections through rapid pathogen characterization and targeted antimicrobial or immunological therapy. Vaccines command the largest revenue share within product type segments due to national immunization schedules and outbreak response stockpiling, while diagnostic kits represent the fastest-expanding category as point-of-care PCR platforms decentralize testing from centralized labs to emergency departments. Lumbar puncture remains the foundational procedure for CSF collection, though MRI technology adoption is climbing as non-invasive differentiation between bacterial and viral etiologies gains clinical priority.
The FDA regulates in vitro diagnostic devices for meningitis pathogen detection under the de novo and 510(k) pathways, with breakthrough device designation accelerating review for assays addressing antimicrobial resistance profiling. The EMA's In Vitro Diagnostic Medical Devices Regulation imposes stricter clinical evidence requirements on CE-marked meningitis test kits entering European markets, reshaping competitive access for non-European manufacturers. Stakeholders must monitor how evolving pharmacovigilance requirements for novel adjuvanted vaccines will influence development timelines and post-market surveillance obligations across multiple regulatory jurisdictions.
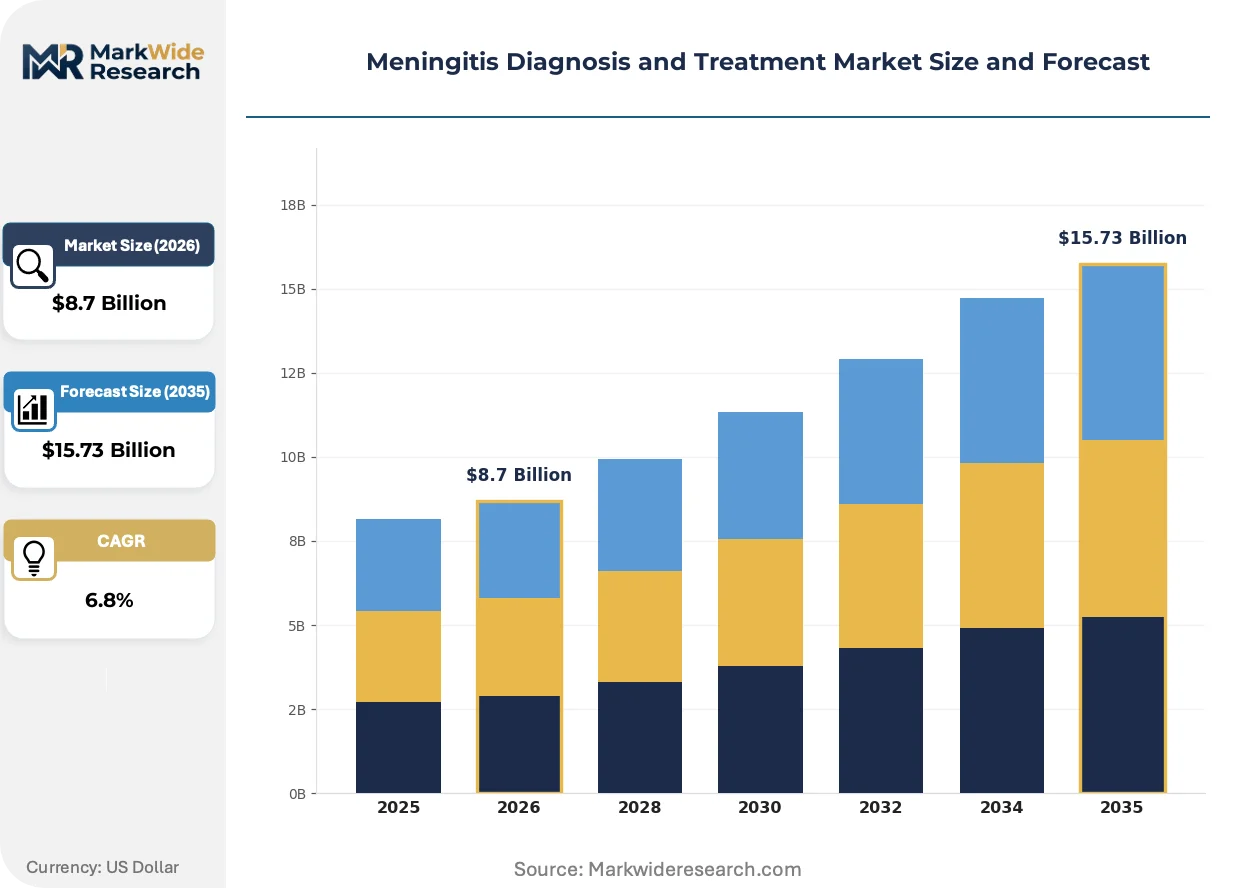
Market Dynamics
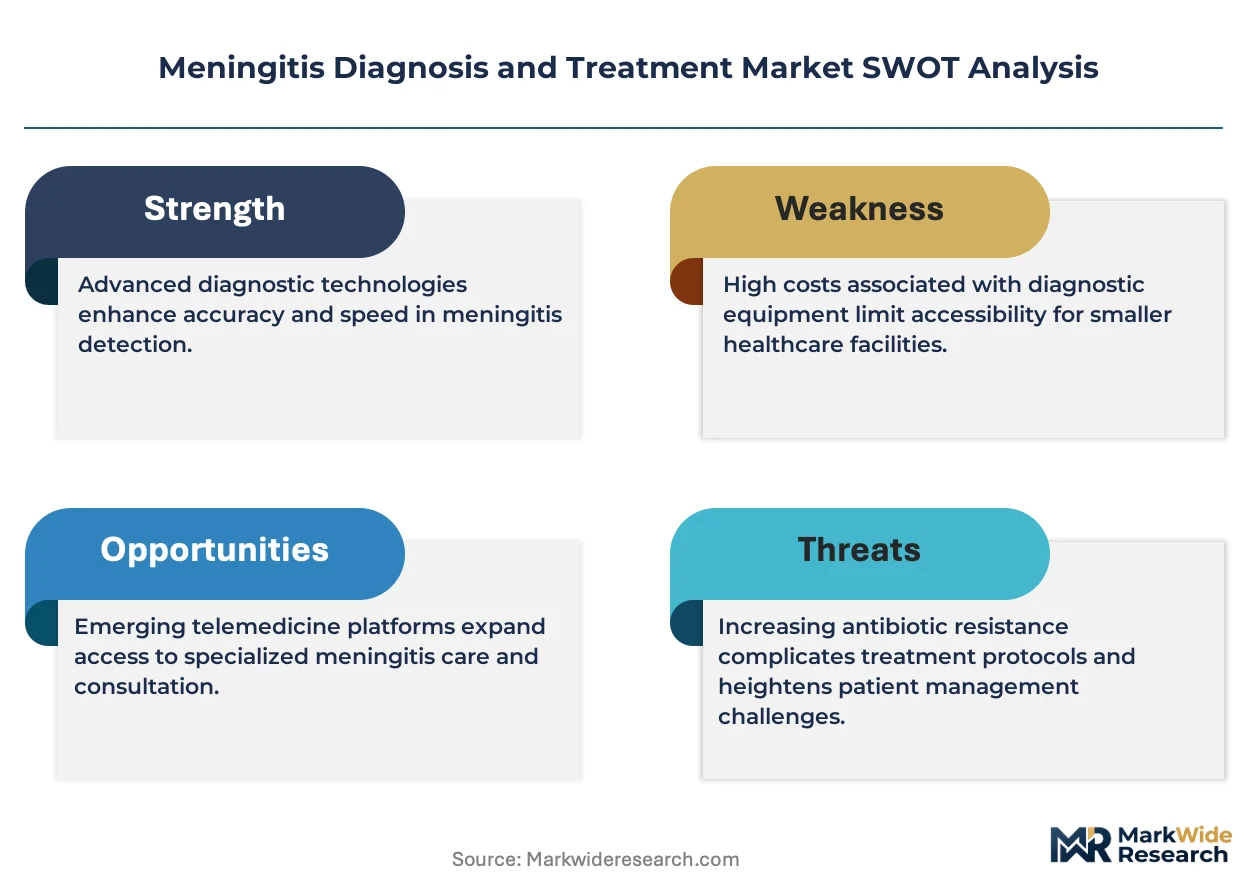
Hospital procurement consolidation is compressing vendor access windows as integrated delivery networks centralize laboratory purchasing decisions under single formulary committees, fundamentally altering how diagnostic platforms reach clinical endpoints.
Growth Catalysts
- Accelerated FDA breakthrough pathway:The FDA's breakthrough device designation compresses review timelines for PCR-based meningitis assays, enabling faster commercialization of antimicrobial resistance profiling tools.
- Emergency department decentralization:Point-of-care nucleic acid amplification platforms are displacing centralized lab workflows, reducing time-to-diagnosis from hours to minutes in acute care settings.
- National immunization stockpiling:Government outbreak response protocols in the United States and United Kingdom drive recurring bulk purchases of conjugate vaccines against multiple serogroups.
Market Restraints
- Reagent supply concentration:PCR enzyme and probe manufacturing clusters in Germany and Switzerland create single-source dependencies for diagnostic kit producers.
- EMA clinical evidence barriers:The In Vitro Diagnostic Medical Devices Regulation imposes retrospective clinical performance studies on legacy assays, delaying CE mark renewals.
- Lumbar puncture substitution risk:Non-invasive MRI protocols for CSF analysis are capturing differential diagnosis cases previously requiring invasive collection.
Strategic Opportunities
- Underpenetrated African markets:Sub-Saharan meningitis belt countries lack centralized laboratory infrastructure, creating first-mover advantage for portable molecular diagnostic platforms.
- Pharmacovigilance data monetization:Novel adjuvanted vaccine post-market surveillance obligations generate recurring revenue streams from real-world evidence contracts.
- AI-augmented pathogen identification:Machine learning integration with automated PCR systems enables multiplexed detection beyond current panel limitations.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of computational biologists capable of interpreting next-generation sequencing outputs from CSF metagenomic analysis is constraining reference laboratory expansion.
- Legacy LIS integration friction:Hospital information system vendors charge prohibitive interface fees for connecting new diagnostic instruments to established laboratory networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meningitis Diagnosis and Treatment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antimicrobials, Contrast Agents, Diagnostic Kits Technology: PCR, ELISA, MRI, Lumbar Puncture End User: Hospitals, Diagnostics Labs, Ambulatory Surgical Centers, Research Institutes Treatment Approach: Pharmacological, Supportive Care, Immunotherapy, Preventive Care |
| Companies Covered | GlaxoSmithKline plc, Johnson & Johnson, Pfizer Inc., Abbott Laboratories, Roche Holding AG, Merck & Co., Inc., Novartis AG, Siemens Healthineers, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meningitis Diagnosis and Treatment Market Strategic Shifts
Diagnostic workflows are fragmenting across care settings as speed requirements override traditional centralized testing economics, while regulatory frameworks struggle to keep pace with multiplexed detection capabilities.
FilmArray and similar syndromic panels is digitizing pathogen identification by embedding automated result interpretation algorithms that eliminate manual curve analysis. Emergency departments in tertiary hospitals are adopting these platforms within eighteen-month procurement cycles. This compression of technical expertise into cartridge-based systems is digitizing the skill base required for meningitis diagnosis, displacing specialized microbiology training from the point of care.
REACH chemical authorization requirements in the European Union are restricting polymerase reagent formulations containing specific fluorophores, forcing diagnostic manufacturers to reformulate detection chemistries. The industrial consequence is extended validation timelines for CE-marked kits entering European markets. Multiplex PCR assay producers are responding by establishing dual-source reagent qualification programs to maintain supply continuity.
Group purchasing organizations are unbundling service contracts from instrument placement agreements, separating preventive maintenance from capital equipment financing. Hospital laboratory directors are negotiating standalone service tiers based on uptime guarantees rather than bundled per-test pricing. This disaggregation is most visible in United States integrated delivery networks, where procurement teams now treat diagnostics as distinct capital and operating expenditure line items.
Meningitis Diagnosis and Treatment Market Segmentation
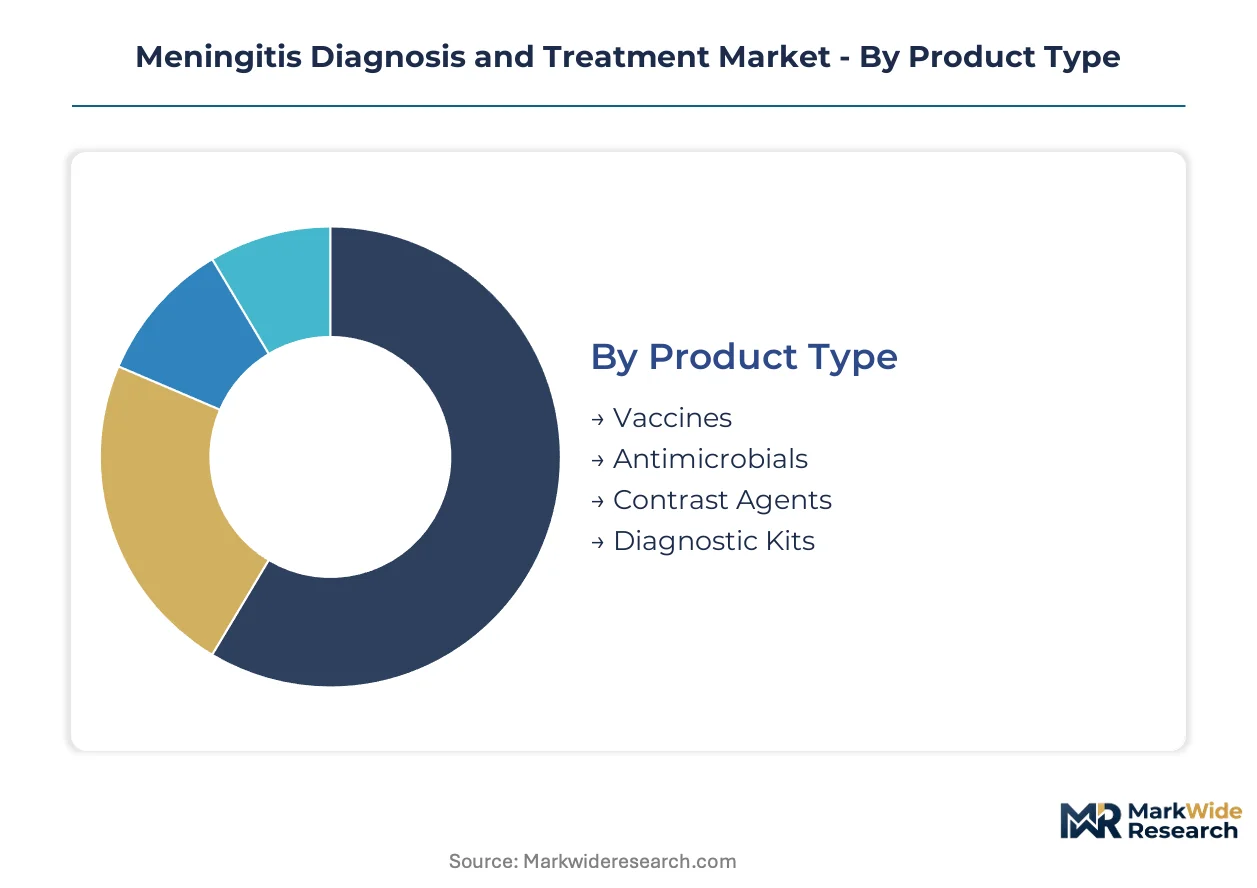
Meningitis diagnosis and treatment spans preventive, diagnostic, and therapeutic modalities with distinct procurement channels and regulatory pathways. Each segment category reflects divergent margin structures, technology maturity curves, and customer concentration patterns that reshape competitive positioning.
Product Type:
Vaccines anchor the highest-volume procurement contracts through national immunization programs, while diagnostic kits penetrate emergency departments with compressed sales cycles.
- Vaccines:Conjugate formulations targeting multiple serogroups dominate tender-based purchasing from government health agencies. The United States and United Kingdom stockpile serogroup B and ACWY vaccines under outbreak response protocols, creating recurring bulk orders with multi-year supply guarantees.
- Diagnostic Kits:Syndromic PCR panels and rapid antigen detection assays are displacing culture-based methods in tertiary hospital laboratories. Point-of-care nucleic acid amplification platforms are expanding fastest in emergency departments seeking sub-60-minute turnaround times.
- Antimicrobials:Third-generation cephalosporins and carbapenems achieve blood-brain barrier penetration for bacterial meningitis treatment.
- Contrast Agents:Gadolinium-based formulations enhance MRI detection of meningeal inflammation and complications.
Established volume favors vaccines; emerging adoption favors diagnostic kits.
Technology:
Cost tier differentiation separates capital-intensive imaging platforms from disposable molecular assays with lower per-test economics.
- PCR:Automated nucleic acid amplification systems multiplex pathogen detection with antimicrobial resistance profiling in single cartridge workflows. Reference laboratories in Germany and Switzerland concentrate reagent manufacturing, creating supply dependencies for kit producers seeking CE mark entry.
- Lumbar Puncture:Cerebrospinal fluid collection remains the foundational diagnostic procedure for cell count, glucose, protein, and direct pathogen visualization. Invasive collection requirements limit adoption in resource-constrained settings lacking trained neuroradiologists.
- ELISA:Enzyme-linked immunosorbent assays detect bacterial antigens and host inflammatory markers at lower per-test cost than molecular methods.
- MRI:Magnetic resonance imaging enables non-invasive differentiation between bacterial and viral etiologies without CSF collection risks.
Capital deployment concentrates in MRI; operational expenditure growth centers on PCR.
End User:
Customer type determines pricing power, with integrated delivery networks extracting volume discounts unavailable to standalone facilities.
- Hospitals:Tertiary medical centers consolidate laboratory purchasing through formulary committees, bundling diagnostic platforms with service contracts. Emergency departments within these systems are decentralizing PCR testing from centralized labs to point-of-care stations.
- Diagnostics Labs:Independent reference laboratories process outsourced CSF analysis for smaller hospitals lacking in-house microbiology capacity.
- Ambulatory Surgical Centers:Limited meningitis case volume restricts capital equipment investment to rapid antigen tests only.
- Research Institutes:Academic medical centers drive next-generation sequencing adoption for metagenomic pathogen discovery in atypical CNS infections.
Procurement consolidation favors hospitals; specialized complexity favors diagnostics labs.
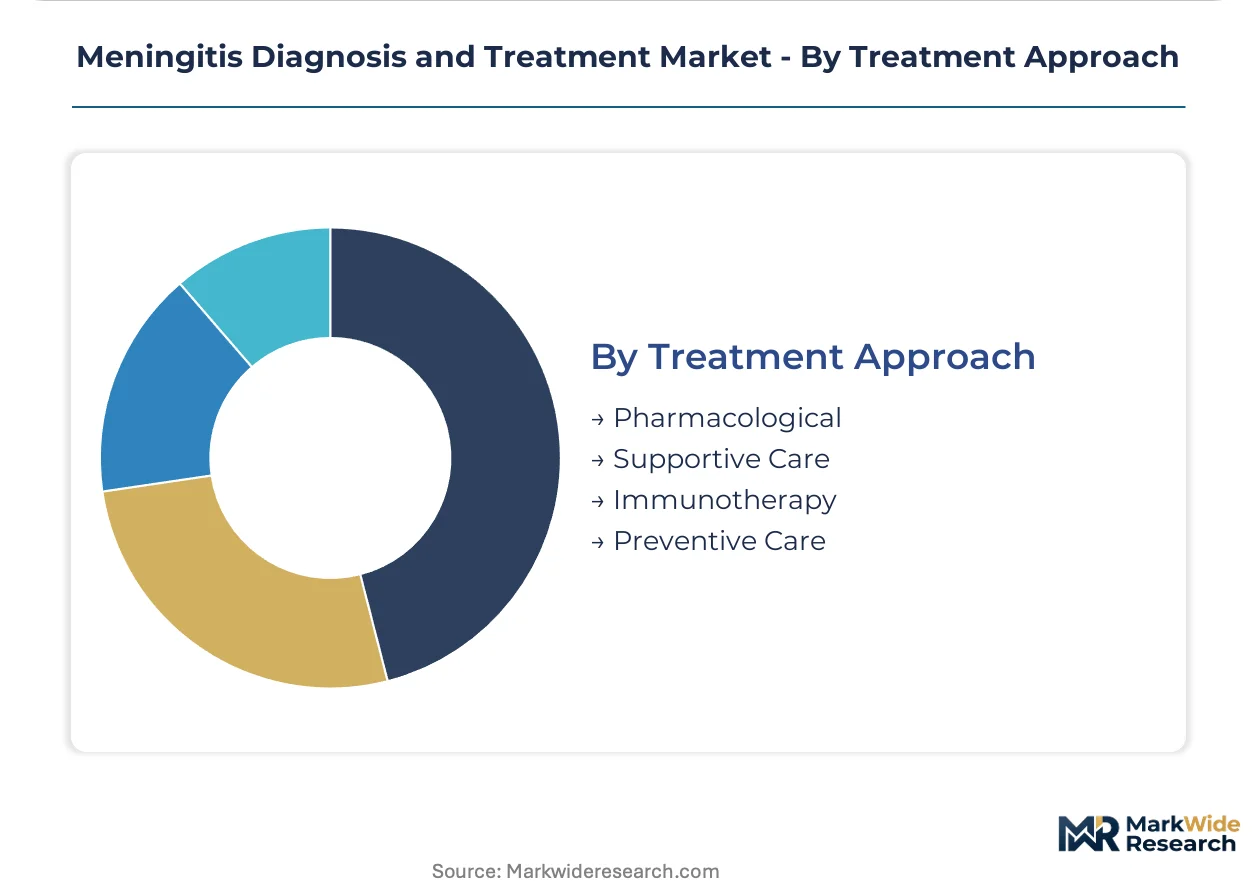
Treatment Approach:
Maturity gradients separate decades-old supportive protocols from novel immunotherapy development programs with extended regulatory timelines.
- Pharmacological:Empiric antibiotic administration precedes pathogen identification in suspected bacterial cases, with vancomycin plus ceftriaxone protocols standardizing across emergency departments. Antimicrobial stewardship programs are narrowing empiric coverage windows as rapid diagnostics shorten time-to-speciation.
- Preventive Care:Vaccination schedules and chemoprophylaxis for close contacts interrupt transmission chains during institutional outbreaks.
- Supportive Care:Intracranial pressure management and seizure prophylaxis address neurological complications without pathogen-directed mechanism.
- Immunotherapy:Adjunctive corticosteroids reduce inflammatory sequelae in bacterial meningitis; monoclonal antibody approaches remain investigational.
Clinical volume concentrates in pharmacological intervention; pipeline investment flows toward immunotherapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems extract 15–20% price premiums over German procurement contracts for identical PCR diagnostic platforms, while Swiss reagent manufacturers capture margin advantages from supply scarcity across both markets.
United States
Integrated delivery networks in Texas and California centralize laboratory purchasing through formulary committees, compressing vendor access windows. The FDA's breakthrough device designation accelerates commercialization timelines for antimicrobial resistance profiling assays. Boston's academic medical corridor drives next-generation sequencing adoption for atypical CNS infection research.
Germany
Reference laboratories in Munich and Heidelberg concentrate PCR enzyme and probe manufacturing, creating supply dependencies for European diagnostic kit producers. REACH chemical authorization requirements restrict specific fluorophore formulations, forcing reformulation of detection chemistries. The country's national pharmaceutical regulator imposes extended validation timelines for CE-marked kits entering domestic markets.
United Kingdom
National Health Service trusts stockpile serogroup B and ACWY vaccines under outbreak response protocols, generating recurring bulk orders. The MHRA operates post-Brexit regulatory autonomy with accelerated assessment pathways for novel diagnostics. London's tertiary hospital clusters decentralize PCR testing from centralized labs to emergency department point-of-care stations.
India
Maharashtra and Karnataka states lack centralized laboratory infrastructure for CSF analysis, creating first-mover opportunities for portable molecular platforms. The CDSCO regulates in vitro diagnostic devices with evolving clinical evidence requirements for domestic manufacturers. Mumbai's private hospital chains consolidate purchasing decisions under corporate laboratory networks.
Switzerland
Roche's domestic manufacturing base anchors automated PCR platform supply chains across Western European reference laboratories. Swissmedic maintains stringent pharmacovigilance requirements for novel adjuvanted vaccines with extended post-market surveillance obligations. Basel's industrial cluster concentrates reagent production capabilities that feed diagnostic supply chains into Germany and France.
Meningitis Diagnosis and Treatment Market Competitive Environment
Vaccine-scale manufacturers and molecular diagnostic specialists split the market into procurement channels with divergent margin structures and customer concentration patterns. Three strategic archetypes dominate: multinational pharmaceutical conglomerates leveraging vaccine manufacturing scale for national immunization tenders, automated diagnostic platform developers capturing reference laboratory workflows, and point-of-care molecular assay producers penetrating emergency department decentralization trends. Competitive moves concentrate on strategic partnerships for reagent supply security and geographic licensing arrangements for regulatory pathway acceleration.
Among pharmaceutical conglomerates, GlaxoSmithKline plc and Pfizer Inc. occupy positions anchored by conjugate vaccine portfolios targeting multiple serogroups. Roche Holding AG exemplifies the automated diagnostic archetype through reference laboratory platform deployment. Sanofi S.A. represents the diversified multinational model spanning both preventive and therapeutic modalities.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Pfizer Inc. |
| Abbott Laboratories |
| Roche Holding AG |
| Merck & Co., Inc. |
| Novartis AG |
| Siemens Healthineers |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
Swiss and German reagent manufacturing clusters anchor PCR probe and enzyme supply for meningitis diagnostic kits, concentrating margin capture upstream while hospital group purchasing organizations extract downstream price concessions through volume aggregation. This upstream-downstream tension compresses midstream kit producers between input scarcity premiums and procurement consolidation pressure.
Pricing Analysis
Configured-to-order PCR platforms command 25-40% premiums over standard cartridge-based systems due to antimicrobial resistance panel customization and LIS integration requirements. Three-tier pricing structure across premium, standard, and economy levels separates reference laboratory automation from emergency department point-of-care units and basic antigen detection kits. Price differentiation hinges on FDA breakthrough designation status and service contract bundling. Cost compression in economy-tier rapid antigen tests is intensifying because of Indian domestic manufacturer entry. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks least.
Supply Chain Analysis
Contract manufacturing for PCR cartridges concentrates with Roche's Basel facilities, Thermo Fisher's Massachusetts operations, and select German CDMOs serving European diagnostic firms. Geographic supply concentration spans Switzerland, Germany, and the United States for precision reagent formulation. Raw material dependencies include fluorophore chemistries, thermostable polymerases, and medical-grade plastics. Single-source vulnerability persists for CE-marked probe synthesis under REACH authorization constraints. Distribution runs through hospital GPOs and reference laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as point-of-care PCR penetration in emergency departments remains below 35% across major health systems, with FDA breakthrough pathway acceleration compressing commercialization timelines for new entrants.
For Market Incumbents: Pre-empt emerging point-of-care specialists by acquiring portable molecular platform developers before regulatory clearance widens their hospital access. Secure backward integration into fluorophore chemistry production to neutralize REACH-driven supply disruptions. Roche and Abbott's installed base advantages erode if cartridge standardization opens procurement to lower-cost alternatives. For New Entrants and Emerging Players: Pursue Maharashtra and Karnataka state hospital networks in India where centralized laboratory infrastructure gaps create first-mover windows for portable PCR systems. Target African meningitis belt countries lacking CSF analysis capacity. Partner with Médecins Sans Frontières for outbreak response validation to accelerate credibility building with procurement agencies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic platform developers holding FDA breakthrough designation but requiring hospital system partnerships for commercial scale. Five-to-ten year viability rests on syndromic panel expansion beyond meningitis into broader CNS infection detection. Watch for AI-augmented pathogen identification FDA submissions as inflection signals for technology obsolescence risk in legacy PCR platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates review timelines for antimicrobial resistance profiling assays against standard 510(k) pathways. |
| Hospital System Partnership | Locks in multi-year cartridge supply agreements with integrated delivery networks consolidating laboratory purchasing. |
| CE Marking Pathway Expansion | Opens European reference laboratory access despite EMA's stricter clinical evidence requirements for legacy assays. |
| Reagent Supply Dual-Source Qualification | Mitigates REACH chemical authorization risks by qualifying alternative fluorophore formulations for European markets. |
| Software Companion Development | Enables AI-augmented pathogen identification integration with automated PCR systems for multiplexed detection beyond current panels. |
Study Parameters
Operator-level perspectives from hospital laboratory directors, GPO contracts managers, diagnostic platform engineers, and regulatory affairs specialists anchored the qualitative base. These primary inputs combined with secondary validation from FDA 510(k) and breakthrough device filings, EMA In Vitro Diagnostic Medical Devices Regulation guidance documents, ClinicalTrials.gov meningitis assay registrations, and hospital procurement database records. Bottom-up segment sizing triangulated against top-down epidemiological incidence models for bacterial and viral CNS infections.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, optimistic, and conservative cases reflecting differential assumptions on point-of-care PCR adoption velocity and national immunization program expansion. Segmentation dimensions modeled include product type, technology platform, end-user facility tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to 2026 baseline values, incorporating hospital capital expenditure cycle timing and vaccine tender award patterns as industry-specific forecast inputs.
Sensitivities concentrate around FDA breakthrough pathway approval delays, REACH chemical authorization scope expansion, and African market infrastructure investment pacing. Forecasts reflect assumptions on procurement consolidation velocity and reagent supply continuity that material deviation could revise. Cross-checking against IQVIA hospital purchasing data and WHO meningitis surveillance reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Saudi Arabia in-Vitro Diagnostics (IVD) Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Global Companion Animal Diagnostics Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Global Liver Cancer Diagnostics Market
Diagnostics
Microdialysis Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Fructosamine Reagents Market