
 Forestry Equipment Tire Market | 2026-2036
Forestry Equipment Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Forestry Equipment Tire Market Analysis
Modular tire-and-wheel assembly bundling is broadening procurement options for forestry contractors seeking reduced field downtime. Michelin leverages its integrated rubber compounding expertise to sustain premium positioning in severe-service applications. Trelleborg Group anchors its competitive stance through specialized polyurethane formulations that resist cuts and impacts in slash pile environments. Nokian Tyres Plc dominates Nordic markets with deep-lug patterns engineered for frozen terrain traction.
Forestry equipment tires are heavy-duty pneumatic or solid structures built with reinforced sidewalls, multi-ply nylon or steel cord carcasses, and tread compounds rated for 30-50% deflection under load, designed to traverse slash debris, steep grades, and soft soils while supporting feller bunchers, skidders, and forwarders weighing 10-40 metric tons. Harvesting tires command the largest volume share due to continuous ground contact during cut-to-length operations, while polyurethane material grades represent the fastest-expanding segment as rental fleets prioritize puncture immunity over ride comfort. Extra-large size categories concentrate margin pools where specialized bead construction and heat-resistant compounds justify premium positioning against standard agricultural crossovers.
The EPA enforces emission-linked equipment standards that indirectly accelerate tire replacement cycles as heavier aftertreatment systems alter weight distribution, while OSHA logging safety regulations mandate maintained traction surfaces that push contractors toward certified tread-depth minimums. In Europe, REACH restricts aromatic oil extenders in rubber compounds, compelling reformulation investments that filter through to end-user pricing. Stakeholders must monitor how emerging biopolymer feedstock certifications reshape material qualification protocols and supplier eligibility across public timber concession contracts.
Market Dynamics
Mechanized cut-to-length harvesting in Nordic operations is compressing tire replacement cycles as heavier equipment and extended seasonal runs accelerate tread wear and sidewall fatigue.
Growth Catalysts
- REACH chemical reformulation mandates:European ECHA standards for reduced aromatic oil extenders in rubber compounds are forcing manufacturers to invest in alternative polymer science, creating premium tiers for compliant products.
- Amazon basin logging corridor expansion:Brazilian terrain severity in Mato Grosso and Pará states accelerates wear rates and replacement frequency for severe-service tread patterns.
- Polyurethane puncture immunity:Solid tire construction eliminates field downtime from slash debris penetration, attracting rental fleet operators prioritizing utilization rates over ride comfort.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply concentration exposes compounders to input cost swings that compress margin stability.
- Steel cord supply concentration:Chinese metallurgical capacity dominates bead wire and belt reinforcement supply, creating geographic single-source risk.
- Aftertreatment weight penalties:EPA Tier 4 Final emission systems add mass to harvester chassis, redistributing axle loads beyond original tire load ratings.
Strategic Opportunities
- Biopolymer feedstock certification:EU Green Deal procurement criteria for public timber concessions favor suppliers with certified sustainable rubber sourcing.
- Modular tire-and-wheel bundling:Pre-assembled drop-in units reduce field mounting time for contractors operating remote cut blocks.
- Sensor-integrated tire monitoring:Pressure and temperature telemetry convergence with telematics platforms enables predictive replacement scheduling.
Industry Challenges
- Compounding chemist scarcity:Formulation expertise for severe-service tread compounds sits concentrated with aging technical workforces in Finland and Germany.
- Bead construction capex intensity:Multi-ply steel cable winding equipment for extra-large categories requires dedicated capital allocation distinct from agricultural tire lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forestry Equipment Tire Market |
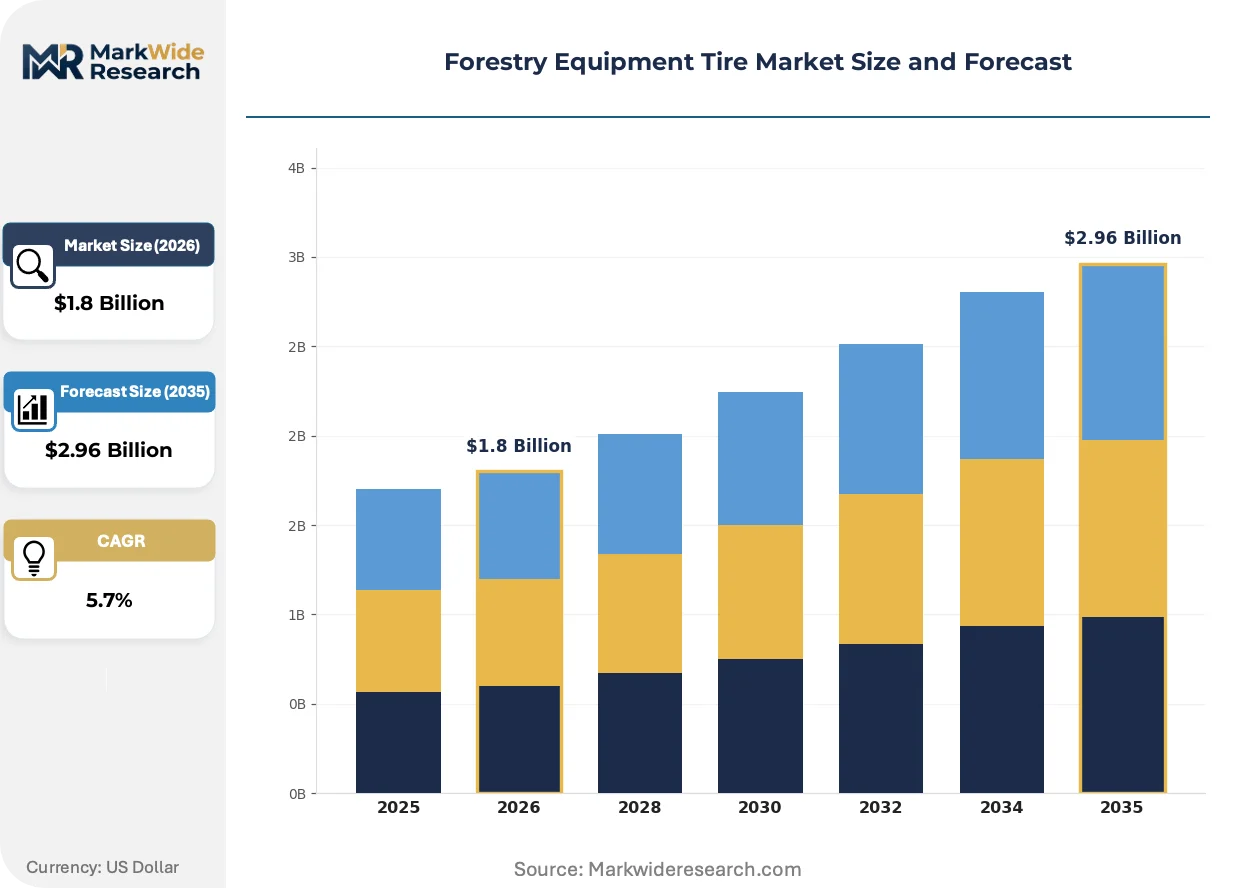
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skid Steer Tires, Log Loaders Tires, Feller Buncher Tires, Harvesting Tires Material: Rubber, Polyurethane, Steel, Composite End User: Forestry Contractors, Equipment Rental Companies, Logging Firms, Timber Producers Size: Small, Medium, Large, Extra Large |
| Companies Covered | Titan International, Inc., The Yokohama Rubber Co. Ltd., Michelin, Trelleborg Group, Continental AG, Nokian Tyres Plc, Balkrishna Industries Limited, Maxxis International, Bridgestone Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forestry Equipment Tire Market Emerging Trajectories
Active innovation centers on material substitution for puncture resistance, regulatory chemistry reformulation, and procurement model unbundling that separates tire supply from equipment OEM channels.
Polyurethane solid tire construction is expanding into rental fleet specifications as contractors prioritize immunity from slash pile punctures over pneumatic ride quality. Forwarder and skidder operators in Brazil and the Nordic region specify these compounds for 24-hour utilization schedules. The technology is expanding into premium positioning against cross-over agricultural tires by eliminating field service calls.
REACH aromatic oil restrictions are compelling reformulation of tread compounds across all European-sourced production. ECHA enforcement of polycyclic aromatic hydrocarbon limits forces substitution with alternative plasticizers and processing oils. Harvesting tire categories face the steepest cost pass-through as severe-service compounds historically relied on high-aromatic extenders for cut resistance.
Fleet operators are unbundling tire procurement from harvester OEM supply agreements, establishing direct relationships with specialized manufacturers for replacement cycles. This disintermediation concentrates in large Nordic contractor cooperatives and Brazilian integrated logging groups with sufficient volume to justify dedicated technical service relationships. The shift compresses channel margins for equipment distributors while rewarding compounders with field engineering capabilities.
Forestry Equipment Tire Market Segmentation
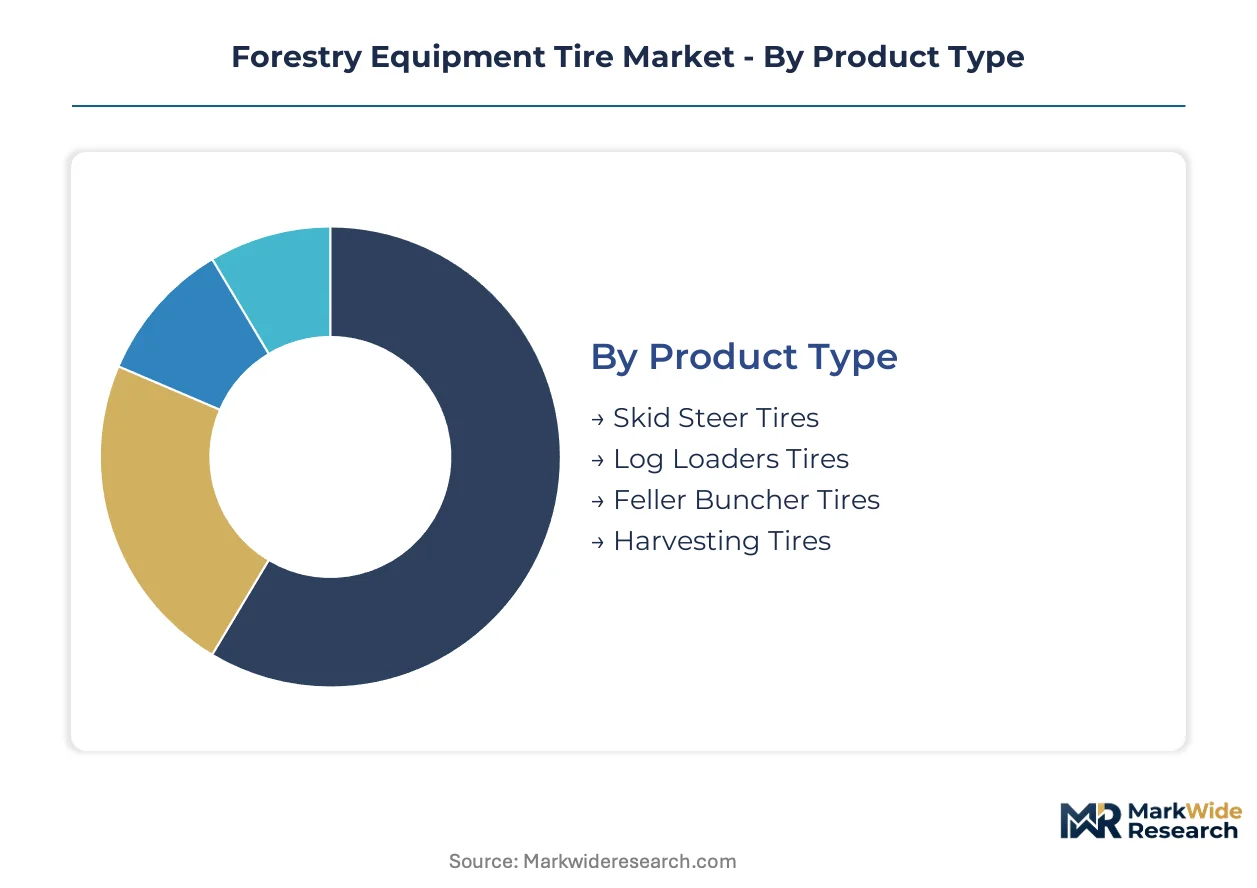
Forestry equipment tire procurement splits across operational intensity, terrain severity, and fleet ownership models. Contractors and rental operators prioritize different specifications based on utilization rates and field service access.
Product Type:
Tread pattern depth, lug geometry, and carcass construction vary sharply across equipment categories.
- Harvesting Tires:Deep-lug patterns with 30-50% deflection ratings support continuous ground contact during cut-to-length operations. Nordic mechanized harvesting compresses replacement cycles as heavier equipment and extended seasonal runs accelerate tread wear.
- Feller Buncher Tires:Reinforced sidewalls resist stumps and slash debris during felling and bunching operations. Brazilian Amazon basin logging corridors in Mato Grosso and Pará states concentrate demand where terrain severity accelerates wear rates.
- Log Loaders Tires:High-load capacity compounds handle concentrated axle pressures during timber stacking and sorting.
- Skid Steer Tires:Compact dimensions suit smaller-scale thinning and maintenance operations with lower duty cycles.
Mature deployment sits with harvesting tires. Newer deployment is concentrated in feller buncher specifications as mechanized felling expands.
Material:
Compound selection trades puncture immunity against ride quality and heat dissipation.
- Polyurethane:Solid construction eliminates field downtime from slash debris penetration. Rental fleet operators in Brazil and Nordic regions specify these compounds for 24-hour utilization schedules prioritizing equipment availability.
- Rubber:Pneumatic structures with multi-ply nylon or steel cord carcasses provide deflection cushioning for operator ergonomics. REACH compliance in Europe is tightening chemical composition standards for aromatic oil extenders in rubber compounds.
- Steel:Bead wire and belt reinforcement deliver structural integrity under extreme loads.
- Composite:Hybrid formulations blend cut resistance with reduced weight for specialized applications.
Established volume sits with rubber compounds. Polyurethane specifications are climbing the fastest as rental fleet penetration deepens.
End User:
Procurement authority separates between owner-operators and third-party equipment providers.
- Equipment Rental Companies:Solid tire preferences dominate to maximize utilization rates and minimize field service calls. Direct manufacturer relationships are unbundling from harvester OEM supply agreements for replacement cycles.
- Forestry Contractors:Cooperative purchasing power in Nordic markets enables dedicated technical service relationships and modular tire-and-wheel bundling.
- Logging Firms:Integrated operations with captive maintenance crews favor pneumatic structures for ride quality.
- Timber Producers:Large concession holders align procurement with EU Green Deal sustainability certification requirements.
Traditional procurement sits with logging firms. Equipment rental companies are gaining share fastest through fleet standardization.
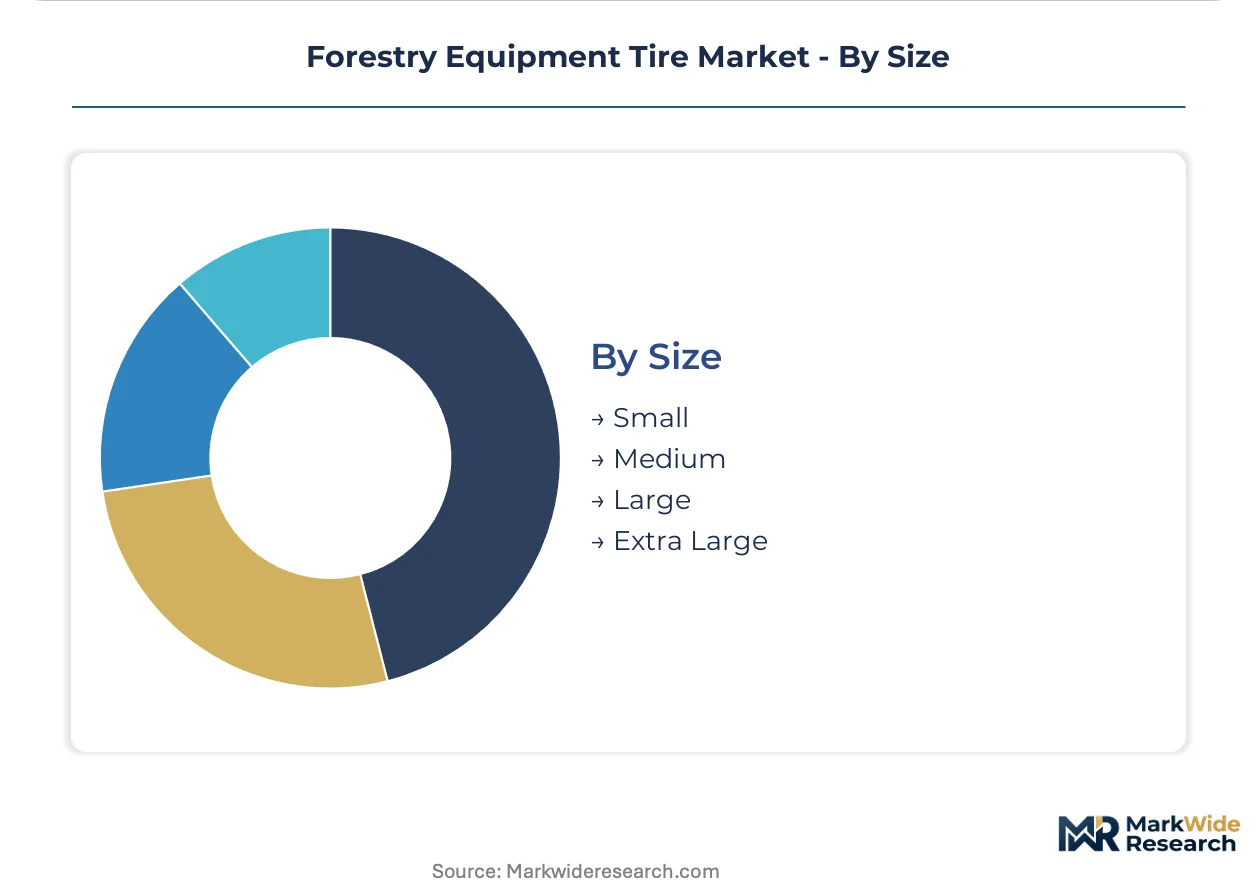
Size:
Dimensional categories correlate with equipment mass and axle load distribution.
- Extra Large:Specialized bead construction and heat-resistant compounds justify premium positioning. Multi-ply steel cable winding equipment requires dedicated capital allocation distinct from agricultural tire lines.
- Large:Standard severe-service specifications for forwarders and skidders in the 10-40 metric ton range.
- Medium:Cross-over agricultural tire substitutes for lighter-duty forwarding and secondary extraction.
- Small:Compact equipment and maintenance vehicle applications with limited volume concentration.
Volume concentration sits with large sizes. Margin pools are deepest in extra-large categories where technical specialization creates differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in European and Asian compounding facilities while consumption gravitates toward mechanized harvesting belts in Brazil and the Nordic region. This geographic split shapes logistics costs and technical service deployment priorities across the value chain.
Brazil
Amazon basin logging corridors in Mato Grosso and Pará states generate concentrated demand for severe-service tread patterns as terrain severity accelerates wear rates. ANVISA oversees chemical safety standards for imported rubber compounds while IBAMA environmental licensing shapes concession access. Equipment rental fleets in Rondônia and Acre prioritize polyurethane specifications for 24-hour utilization schedules.
Sweden
Mechanized cut-to-length harvesting compresses replacement cycles as heavier equipment and extended seasonal runs accelerate tread wear. The Swedish Chemicals Agency enforces REACH-aligned restrictions on aromatic oil extenders in rubber compounds. Forestry contractor cooperatives in Västerbotten and Norrbotten leverage collective purchasing power for modular tire-and-wheel bundling arrangements.
Finland
Deep-lug patterns engineered for frozen terrain traction dominate specifications across Lapland and North Ostrobothnia harvesting zones. ECHA compliance mandates drive reformulation investments that filter through to end-user pricing. Technical compounding expertise concentrates in southern industrial clusters around Helsinki and Tampere.
Germany
KBA type-approval requirements intersect with EU Green Deal procurement criteria for public timber concessions favoring certified sustainable rubber sourcing. The KBA also enforces standards for bead wire and belt reinforcement specifications. Industrial tire manufacturing capacity clusters in Baden-Württemberg and Lower Saxony serve as supply anchors for Central European markets.
United States
EPA Tier 4 Final emission systems add mass to harvester chassis, redistributing axle loads beyond original tire load ratings and compressing replacement cycles. OSHA logging safety regulations mandate maintained traction surfaces that push contractors toward certified tread-depth minimums. Pacific Northwest operations in Oregon and Washington concentrate demand for slash-resistant sidewall specifications.
Forestry Equipment Tire Market Vendor Landscape
The competitive structure tilts toward integrated rubber compounders with captive polymer science capabilities. Three to five major groups anchor premium positioning through specialized bead construction and heat-resistant formulations. The field segments into integrated tire-and-wheel system suppliers, standalone severe-service compounders, and agricultural cross-over producers. Dominant competitive moves include direct contracting with large forestry cooperatives and capacity expansion in extra-large size categories requiring dedicated steel cable winding equipment.
Among European integrated manufacturers, Michelin, Trelleborg Group, and Nokian Tyres Plc exemplify distinct archetypes within the premium tier. The French group leverages compounding expertise across severe-service applications. The Swedish-Danish entity anchors positioning through specialized polyurethane formulations. The Finnish manufacturer occupies a position defined by frozen-terrain traction engineering. These three represent the technical specialization barrier that agricultural cross-over producers struggle to penetrate.
| Leading Market Players |
|---|
| Titan International, Inc. |
| The Yokohama Rubber Co. Ltd. |
| Michelin |
| Trelleborg Group |
| Continental AG |
| Nokian Tyres Plc |
| Balkrishna Industries Limited |
| Maxxis International |
| Bridgestone Corporation |
| Others |
Supply Flow & Price Mechanics
REACH aromatic oil restrictions in European-sourced production are compelling reformulation investments that manufacturers must recover through tiered pricing structures, while Brazilian rental fleet consolidation amplifies volume bargaining power against compounders lacking field engineering capabilities.
Pricing Analysis
Margin tightening in extra-large size categories reflects dedicated steel cable winding equipment requirements that agricultural crossover producers cannot amortize. Pricing stratifies across premium, standard, and economy tiers based on bead construction complexity and heat-resistant compound certification. Cost-down pressure on standard agricultural crossovers accelerates because Nordic contractor cooperatives unbundle procurement from OEM supply agreements. Equipment rental companies exhibit highest price sensitivity due to fleet standardization mandates, while integrated logging firms with captive maintenance crews accept premium positioning for pneumatic ride quality.
Supply Chain Analysis
Aging technical workforces in Finnish and German compounding clusters constrain formulation expertise availability for severe-service tread compounds. Manufacturing gravity centers on Finland, Germany, and China, with the latter dominating steel cord and bead wire supply. Raw material sourcing draws from Thai and Indonesian natural rubber concentration, Chinese metallurgical capacity for reinforcement, and petroleum-derived polyurethane precursors. Single-source vulnerability sits with Chinese steel cord supply for extra-large categories. Distribution runs through equipment OEM channels for initial fitment and direct manufacturer relationships for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The forestry equipment tire market is consolidating around compounders with captive polymer science capabilities, as REACH compliance investments and specialized bead construction capex force marginal agricultural crossover producers toward exit.
For Market Incumbents: Anticipate biopolymer feedstock certification requirements from EU Green Deal procurement criteria by securing certified sustainable rubber sourcing for public timber concession eligibility. Deepen backward integration into polyurethane precursor supply to defend margin position against natural rubber price volatility. Prioritize capacity expansion in extra-large size categories requiring dedicated steel cable winding equipment distinct from agricultural lines. For New Entrants and Emerging Players: Capture modular tire-and-wheel bundling opportunities with Brazilian integrated logging groups in Mato Grosso and Pará states where terrain severity accelerates replacement frequency. Target sensor-integrated tire monitoring convergence with telematics platforms as the most penetrable white space, leveraging predictive replacement scheduling to disintermediate established channel relationships. Pursue direct technical service relationships rather than OEM distribution partnerships. For Investors and Strategic Acquirers: The window for entry favors compounders with proven REACH-compliant formulation libraries and established Nordic cooperative supply contracts. Long-term viability hinges on positioning ahead of biopolymer certification mandates reshaping supplier eligibility. Monitor ECHA enforcement intensity on polycyclic aromatic hydrocarbon limits as the inflection indicator for reformulation cost pass-through capacity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Compound Reformulation | ECHA polycyclic aromatic hydrocarbon enforcement forces alternative plasticizer substitution across European production. |
| Polyurethane Solid Tire Capacity Expansion | Rental fleet operators in Brazil and Nordic regions prioritize puncture immunity for 24-hour utilization schedules. |
| Biopolymer Feedstock Certification | EU Green Deal procurement criteria favor suppliers with certified sustainable rubber sourcing for public timber concessions. |
| Modular Tire-and-Wheel Bundling | Pre-assembled drop-in units reduce field mounting time for contractors operating remote cut blocks in Västerbotten. |
| Sensor-Integrated Tire Monitoring | Pressure and temperature telemetry convergence with telematics platforms enables predictive replacement scheduling. |
Methodological Framework
Multi-period observation of replacement cycle compression, REACH compliance cost pass-through, and rental fleet penetration rates anchored the trend analysis, supplemented by interviews with tire compound R&D directors, forestry contractor cooperative procurement leads, OEM aftermarket service heads, and rental fleet maintenance managers. Secondary validation drew from ECHA regulatory filings, ANVISA chemical safety standards, IBAMA environmental licensing records, customs trade data for natural rubber and steel cord flows, and SEC disclosures from integrated tire manufacturers. Bottom-up equipment population modeling and top-down value chain margin analysis were triangulated against primary field intelligence.
The input-output matrix framework mapped harvester and forwarder unit shipments against tire replacement intervals by terrain severity zone, with segmentation across product type, material grade, end-user procurement authority, and size category. CAGRs were derived from regression analysis of historical replacement frequency trends and projected equipment fleet expansion across the modeling period. Industry-specific forecast inputs included EPA Tier 4 Final aftertreatment weight distribution impacts on axle load ratings and Brazilian Amazon basin logging corridor licensing velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural rubber price volatility, Chinese steel cord supply disruption, and ECHA enforcement intensity on aromatic oil extender substitution. Forecasts reflect documented assumptions regarding mechanized harvesting adoption rates and biopolymer certification timeline adoption. Material deviation in Thai-Indonesian supply concentration or REACH reformulation cost recovery capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Bead Wire (Tyre Bead Wire) Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Global Automotive Tire Inflator Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Europe Agricultural Tires Market