
 Self-Healing Tire Market | 2026-2036
Self-Healing Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Healing Tire Market Analytics
The capital-intensity divergence between integrated polymer producers and tire-assemblers is unwinding competitive stability across the self-healing tire landscape. Michelin leverages captive R&D in reactive elastomer chemistry to sustain technology leadership in European passenger segments. Bridgestone Corporation anchors its position through backward integration into smart sensor modules, controlling critical telemetry inputs for fleet monitoring systems. Continental AG differentiates via manufacturing scale across heavy-duty applications, occupying dominant supply positions with German commercial vehicle builders.
Self-healing tires incorporate sealant layers—typically polyurethane or synthetic elastomer compounds—that autonomously close punctures up to specified diameters through viscoelastic flow and polymer rebonding, maintaining inflation pressure without driver intervention during commercial or passenger vehicle operation. Passenger tires command the largest current volume position, though heavy-duty tires carry disproportionate margin pools due to fleet downtime costs and OEM specification premiums. Smart sensors integrated with tire pressure monitoring represent the fastest-expanding technology dimension, as telematics providers and fleet operators demand real-time integrity verification alongside physical puncture resistance.
The EPA regulates volatile organic compound emissions in tire manufacturing processes, while NHTSA safety standards govern puncture-retention performance claims for highway-rated tires in the United States. REACH and the EU F-Gas Regulation constrain sealant chemistry choices across European production, pushing manufacturers toward bio-based polyurethane alternatives and closed-loop material recovery systems. Stakeholders must monitor evolving chemistry restrictions alongside fleet electrification timelines, as battery weight distribution and torque characteristics reshape load-bearing requirements and puncture-risk profiles for next-generation vehicle platforms.
Market Dynamics
Fleet electrification timelines are compressing R&D cycles for self-healing tire architectures, as battery weight distribution and instantaneous torque loads demand recalibrated sealant viscosity and belt reinforcement specifications across commercial vehicle platforms.
Growth Catalysts
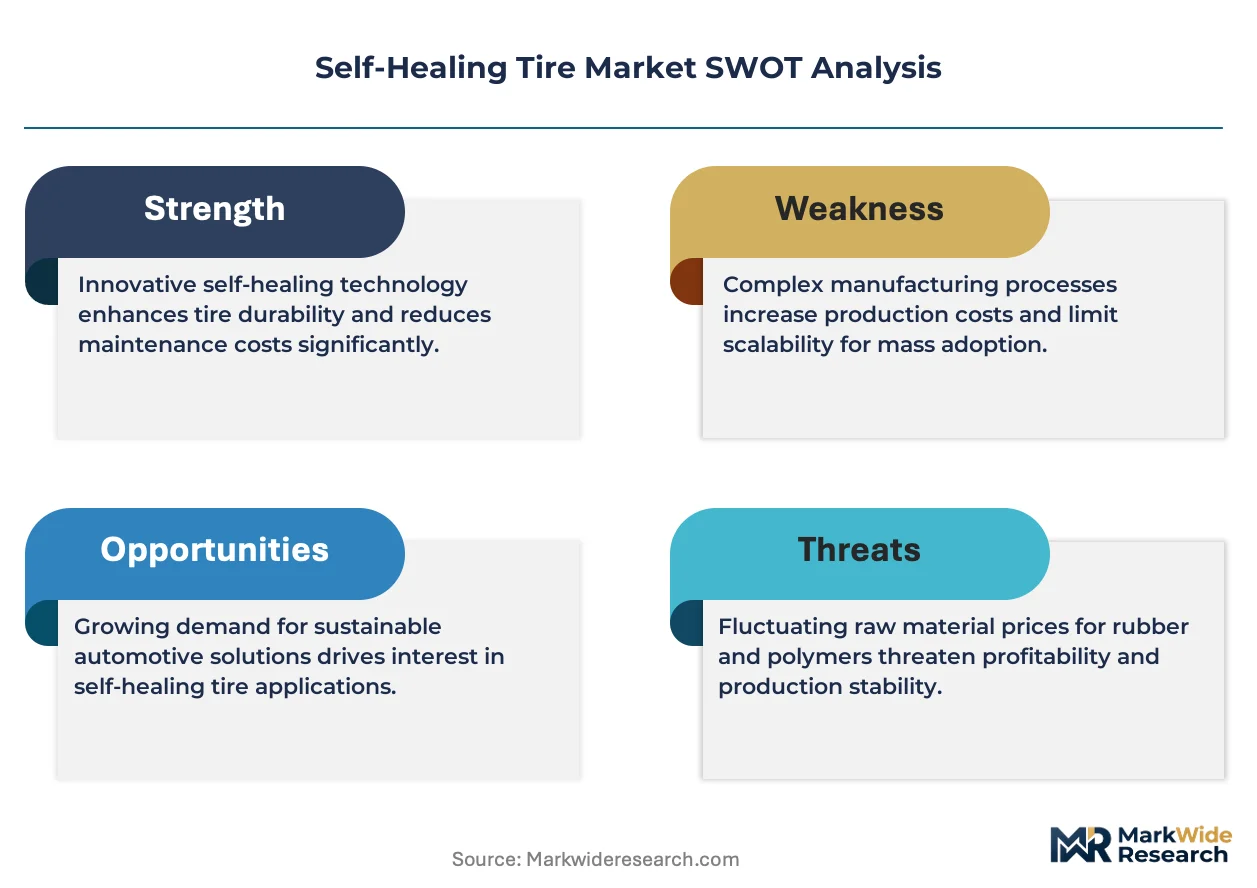
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases in sealant formulations is accelerating bio-based polyurethane chemistry development among European compounders, creating first-mover advantages for compliant suppliers.
- Last-mile delivery electrification:E-commerce logistics operators in Germany and the Netherlands are specifying self-healing tires for electric van fleets to eliminate roadside service calls and protect battery thermal management systems from jacking-related damage.
- Smart sensor convergence:Integration of pressure telemetry with autonomous sealant verification is enabling predictive maintenance contracts for heavy-duty operators, bundling physical puncture resistance with real-time integrity monitoring.
Market Restraints
- Petrochemical feedstock volatility:Isocyanate and polyol input costs for polyurethane sealants fluctuate with crude oil derivatives, compressing compounder margins and destabilizing long-term OEM pricing agreements.
- REACH compliance complexity:The European Chemicals Agency's evolving substance restrictions require continuous reformulation of sealant chemistries, extending product certification timelines and raising regulatory affairs overhead.
- Conventional tire substitution:Run-flat constructions and tire pressure monitoring systems retain cost advantages in passenger segments, limiting self-healing penetration to premium specifications and commercial applications.
Strategic Opportunities
- Indian commercial vehicle aftermarket:Underpenetration of advanced tire technologies among long-haul truck operators presents white space for sealant-layer retrofit solutions and mobile installation services.
- Battery-electric bus mandates:Urban transit procurement specifications in France and Spain are beginning to require puncture-resistant tire technologies to minimize depot maintenance and maximize fleet utilization rates.
- Closed-loop material recovery:Pyrolysis and chemical depolymerization infrastructure development enables circular sealant feedstock sourcing, aligning with EU Green Deal circular economy targets and reducing virgin material dependence.
Industry Challenges
- Reactive polymer formulation expertise:The specialized knowledge required for viscoelastic flow engineering and rebonding kinetics is concentrated among a limited cohort of elastomer chemists, constraining R&D team scaling.
- Homologation timeline compression:NHTSA puncture-retention testing protocols and ECE R30 certification requirements demand extensive track validation, extending new product introduction cycles beyond fleet procurement planning horizons.
- Legacy fleet integration complexity:Retrofitting self-healing architectures onto existing wheel rim designs requires dimensional recalibration, creating friction with aftermarket distributors accustomed to conventional mounting procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Healing Tire Market |
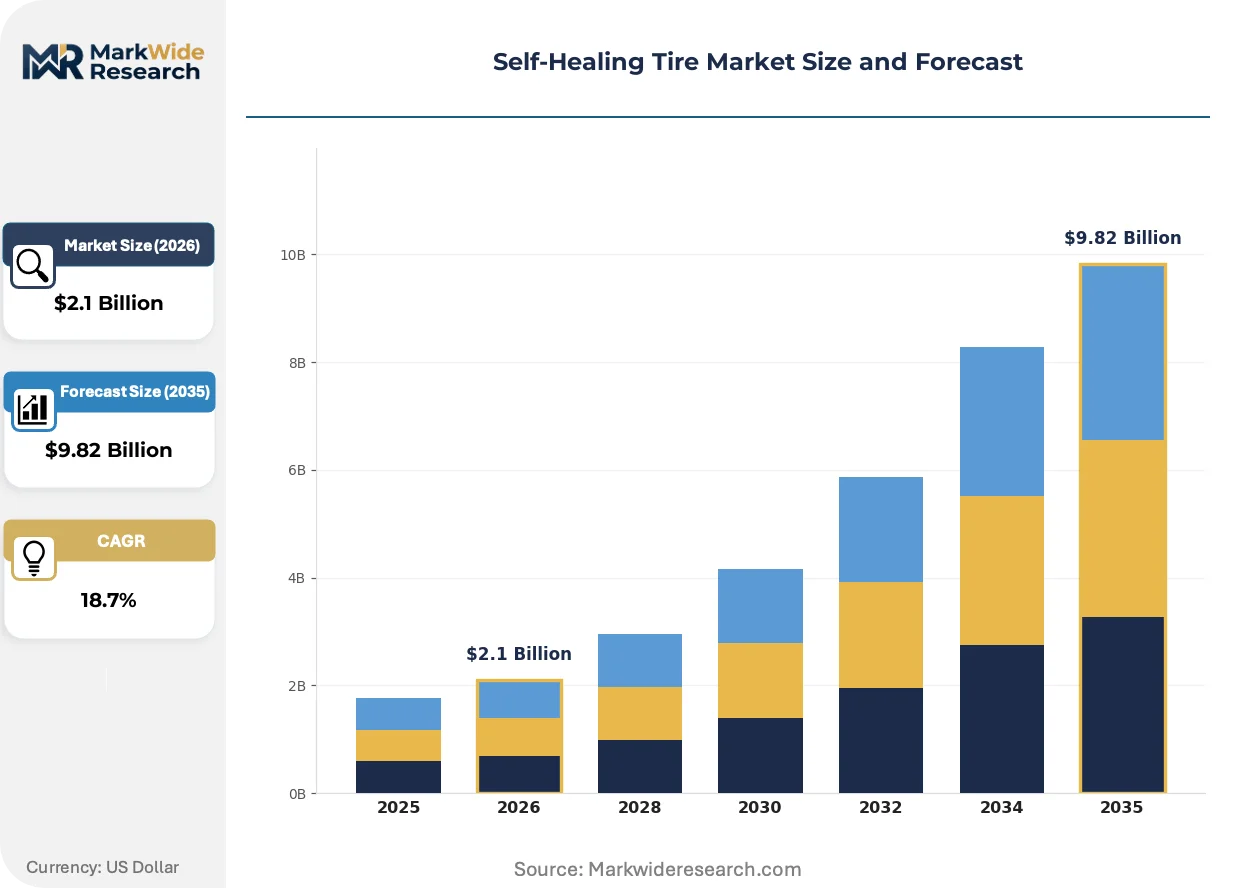
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.82 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Tires, Commercial Tires, Heavy-Duty Tires, Motorcycle Tires Material: Polyurethane, Rubber, Nanomaterials, Synthetic Elastomers Technology: Self-Healing Polymers, Reactive Materials, Smart Sensors, Tire Pressure Monitoring End User: OEMs, Aftermarket Providers, Fleet Operators, Retail Customers |
| Companies Covered | Michelin, Bridgestone Corporation, Goodyear Tire & Rubber Company, Continental AG, Pirelli & C. S.p.A., Hankook Tire & Technology Co., Ltd., Kumho Tire Co., Inc., Yokohama Rubber Company, Toyo Tire Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Healing Tire Market Evolving Landscape
Material science advances and embedded electronics are converging to redefine tire architecture, shifting competitive advantage toward suppliers capable of integrating physical puncture resistance with digital verification capabilities.
Micro-electromechanical pressure sensors embedded within tire carcass layers are miniaturizing to dimensions compatible with commercial tire manufacturing tolerances. Heavy-duty fleet operators in Germany are adopting these integrated modules to correlate sealant activation events with vehicle telematics. The technology is miniaturizing cost structures for standalone monitoring hardware, compressing the total installed price differential between smart and conventional self-healing configurations.
REACH authorization requirements for diisocyanate-containing products are tightening occupational exposure controls across European manufacturing facilities. Compounders must implement closed-loop handling systems and worker training protocols to maintain production licenses. Passenger tire assemblers with German production footprints are accelerating bio-based sealant qualification programs to preempt supply interruptions from substance restriction expansions.
Service bundling is displacing component-only procurement among North American commercial fleet operators. Tire-as-a-service contracts incorporating sealant performance guarantees, proactive replacement scheduling, and telemetry-based wear analysis are capturing maintenance budget allocations previously directed to spot purchases. This model is concentrating procurement authority with integrated tire manufacturers and eroding independent distributor margins in long-haul trucking segments.
Self-Healing Tire Market Segmentation
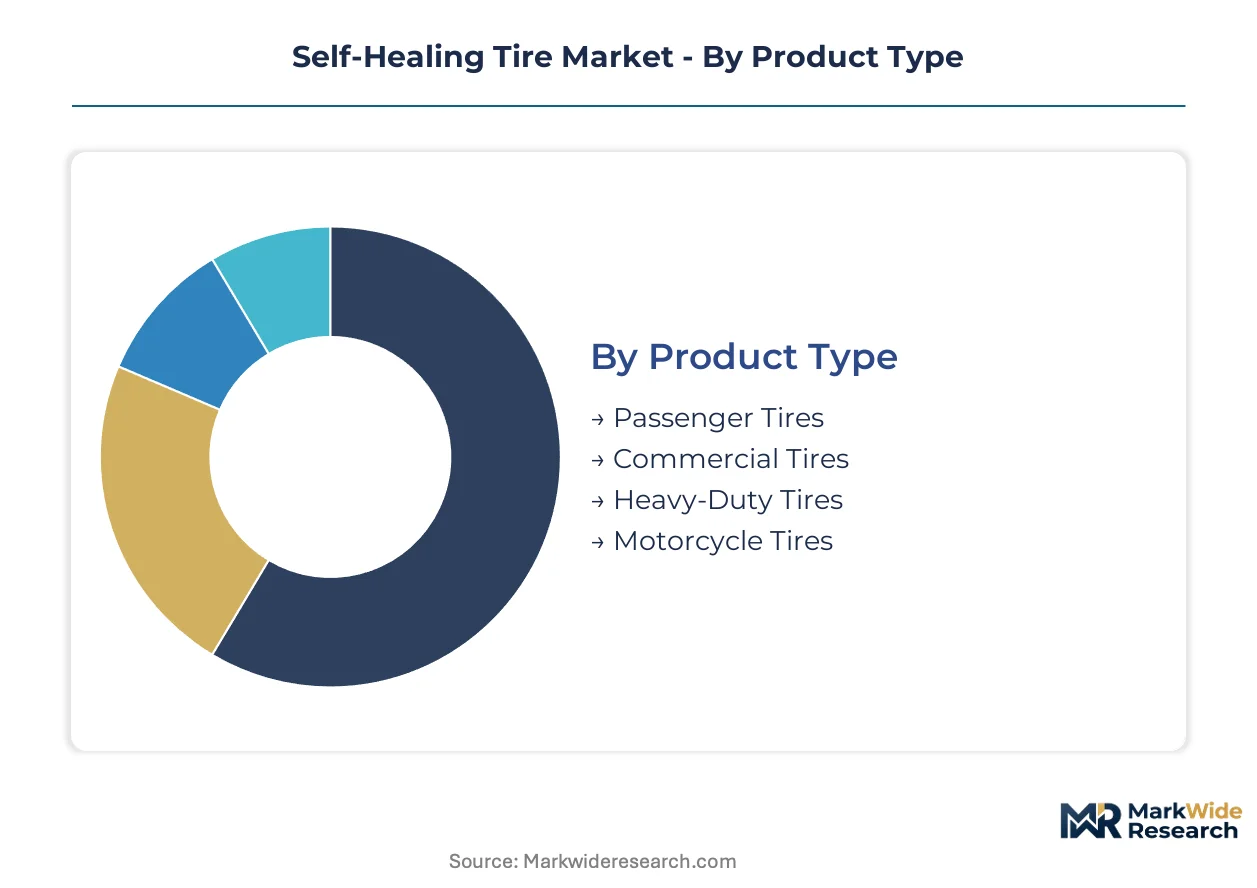
Segmentation in self-healing tires reveals how regulatory chemistry constraints, electrification load requirements, and fleet telemetry demands are fragmenting addressable markets across incompatible specification clusters. Each dimension carries distinct margin profiles and certification burdens that reshape supplier competitive positioning.
Product Type:
REACH substance restrictions and NHTSA puncture-retention protocols apply differentially across load ratings, creating compliance cost asymmetries between passenger and commercial specifications.
- Passenger Tires:Sealant layers in P-metric configurations prioritize ride comfort and low rolling resistance through thin-gauge polyurethane formulations. German automotive OEM integration programs concentrate demand for premium touring specifications with autobahn-speed durability ratings.
- Commercial Tires:Fleet operators across Germany and the Netherlands specify these for electric van platforms to eliminate roadside service calls and protect battery thermal management systems from jacking damage. Last-mile electrification is compressing procurement cycles for puncture-resistant LT-rated configurations.
- Heavy-Duty Tires:German commercial vehicle builders dominate procurement through OEM specification premiums tied to downtime cost avoidance.
- Motorcycle Tires:Limited adoption due to sidewall flexibility requirements and weight constraints on two-wheel platforms.
Passenger tires handle the majority of throughput; commercial tires are expanding most quickly on share as fleet electrification accelerates.
Material:
Cost tiers separate bio-based qualification programs from conventional petrochemical feedstocks, with EU F-Gas compliance creating premium positioning for sustainable chemistry suppliers.
- Polyurethane:Viscoelastic sealant compounds dominate through autonomous puncture closure via polymer rebonding kinetics. Bio-based polyol development among European compounders is accelerating under REACH diisocyanate exposure controls.
- Synthetic Elastomers:Reactive chemistry enables specified-diameter puncture sealing without driver intervention. Isocyanate and polyol input cost volatility compresses compounder margins and destabilizes long-term OEM pricing agreements.
- Rubber:Conventional natural and synthetic rubber matrices offer limited self-healing functionality compared to engineered sealant layers.
- Nanomaterials:Emerging filler technologies for reinforcement and thermal conductivity enhancement in next-generation architectures.
Polyurethane commands the volume position; synthetic elastomers are climbing the fastest as fleet specifications harden around durability guarantees.
Technology:
Application maturity separates physical puncture resistance from digital verification capabilities, with integrated telemetry capturing maintenance budget reallocations from component-only procurement.
- Self-Healing Polymers:Core viscoelastic flow engineering enables autonomous sealant activation through polymer rebonding without external intervention. This remains the foundational architecture across all product categories.
- Smart Sensors:Micro-electromechanical pressure modules embedded within tire carcass layers miniaturize to commercial manufacturing tolerances. Heavy-duty fleet operators in Germany adopt these to correlate sealant activation with vehicle telematics.
- Reactive Materials:Advanced chemistry formulations with enhanced rebonding kinetics for extreme temperature and load conditions.
- Tire Pressure Monitoring:Standalone pressure telemetry systems without integrated sealant verification capabilities face displacement by converged smart sensor platforms.
Self-healing polymers handle the majority of throughput; smart sensors are gaining share fastest as tire-as-a-service contracts bundle physical resistance with real-time integrity monitoring.
End User:
Customer type determines procurement authority concentration, with integrated manufacturers capturing maintenance budgets previously directed to independent distributors through service bundling.
- Fleet Operators:North American long-haul trucking segments and European last-mile electric van operators drive specification premiums through downtime cost quantification. Predictive maintenance contracts bundle sealant performance guarantees with telemetry-based wear analysis.
- OEMs:German commercial vehicle builders and passenger car manufacturers integrate self-healing architectures at platform development stages, locking in multi-year supply positions through homologation timelines.
- Aftermarket Providers:Independent distributors face margin erosion as tire-as-a-service models concentrate procurement authority with integrated manufacturers.
- Retail Customers:Premium passenger tire specifications for individual vehicle owners remain limited by cost advantages of run-flat constructions and conventional tire pressure monitoring systems.
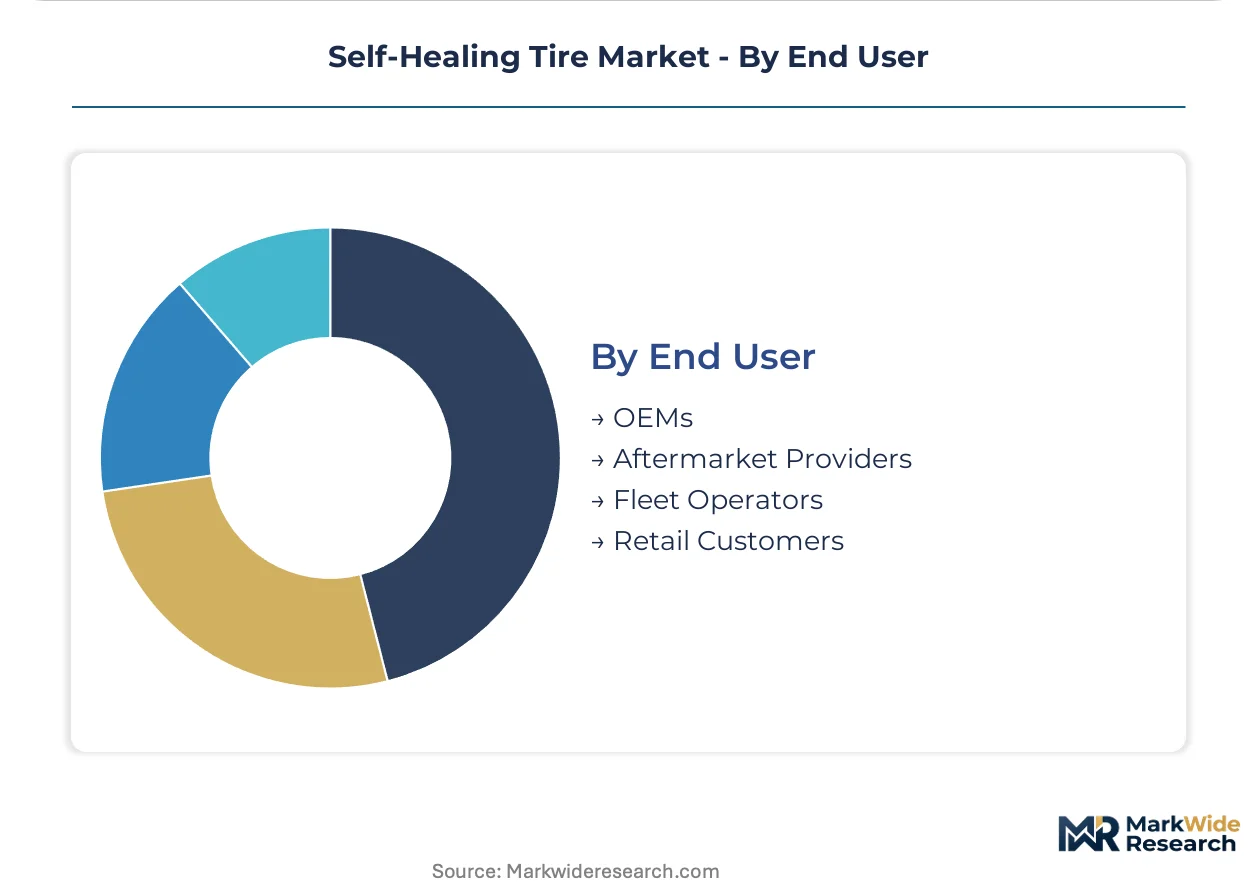
Fleet operators handle the majority of throughput; OEMs are climbing the fastest on share as battery-electric bus mandates in France and Spain harden puncture-resistance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Germany absorb premium pricing without volume elasticity, while Indian long-haul truckers demand retrofit solutions at cost points conventional tires match. This demand-elasticity contrast structures regional prioritization for sealant-layer suppliers.
Germany
Autobahn-speed durability ratings and commercial vehicle OEM integration programs concentrate specification premiums in Baden-Württemberg and Bavaria. The KBA enforces ECE R30 certification timelines that compress new product introduction cycles. Stuttgart's automotive engineering cluster anchors reactive elastomer chemistry development for passenger touring segments.
United States
North American long-haul trucking fleets quantify downtime costs to justify self-healing tire procurement. The EPA regulates volatile organic compound emissions in tire manufacturing processes. Michigan and Ohio's automotive supplier corridors host NHTSA puncture-retention testing facilities that validate highway-rated performance claims.
Netherlands
Last-mile delivery electrification in Amsterdam and Rotterdam drives electric van fleet specifications. REACH compliance requirements constrain sealant chemistry choices across European production. Eindhoven's polymer research institutes accelerate bio-based polyurethane qualification programs.
India
Underpenetration of advanced tire technologies among long-haul truck operators creates white space for retrofit solutions. The BIS maintains tire safety standards that shape aftermarket import regulations. Maharashtra's commercial vehicle manufacturing belt around Pune and Mumbai concentrates mobile installation service demand.
France
Battery-electric bus mandates in Paris and Lyon harden puncture-resistance requirements for urban transit procurement. The EU Green Deal circular economy targets push manufacturers toward closed-loop material recovery systems. Île-de-France's depot maintenance networks maximize fleet utilization through predictive tire replacement scheduling.
Self-Healing Tire Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated polymer producers commanding reactive chemistry expertise and tire-assemblers controlling distribution scale. The market structures around three tiers: captive R&D specialists, backward-integrated sensor module producers, and manufacturing-scale heavy-duty suppliers. Two dominant competitive moves define current positioning: strategic partnerships between compounders and fleet telematics providers, and geographic expansion through homologation-track investments in multiple regulatory jurisdictions.
Within the integrated manufacturer tier, Michelin, Bridgestone Corporation, and Continental AG occupy positions that exemplify divergent capability anchoring. The French S.A. represents technology leadership through captive elastomer chemistry programs. The Japanese Corporation exemplifies backward integration into telemetry hardware. The German AG anchors manufacturing scale across commercial vehicle supply relationships.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone Corporation |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Pirelli & C. S.p.A. |
| Hankook Tire & Technology Co., Ltd. |
| Kumho Tire Co., Inc. |
| Yokohama Rubber Company |
| Toyo Tire Corporation |
| Others |
Value Network & Pricing Analysis
Manufacturing scale asymmetries between integrated polymer producers and tire-assemblers create divergent cost floors across specification tiers. German production footprints command premium positioning through REACH-compliant chemistry investments, while Asian compounders compete on polyol feedstock proximity.
Pricing Analysis
Tire-as-a-service contracts now capture the dominant lifetime value tier, bundling sealant performance guarantees with predictive replacement scheduling. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated specifications from aftermarket retrofit solutions. Pricing pressure stems from isocyanate cost volatility compressing compounder margins. Fleet operators exhibit lowest price sensitivity due to downtime cost quantification, while retail passenger segments remain highly elastic.
Supply Chain Analysis
Germany and the Netherlands anchor European sealant formulation capacity, while China and South Korea feed polyol and isocyanate precursors. Raw material dependencies center on crude-derived diisocyanates, bio-based polyol development streams, and specialized elastomer additives. Single-source vulnerability concentrates in petrochemical feedstock corridors exposed to energy price shocks. Distribution runs through OEM direct-supply agreements and integrated fleet service contracts, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-healing tire architectures represent high-growth disruption as EU F-Gas Regulation deadlines force chemistry transitions across European production. Fleet electrification compresses R&D cycles while expanding addressable maintenance budgets.
For Market Incumbents: Consolidate reactive polymer formulation expertise through captive elastomer chemistry programs and backward integration into smart sensor modules. Defend against telemetry-agnostic entrants by controlling fleet data architectures. Prioritize homologation-track investments across NHTSA and ECE R30 certification pathways to compress new product introduction timelines.
For New Entrants and Emerging Players: Anchor in Indian commercial vehicle aftermarket retrofit solutions, where underpenetration of advanced tire technologies creates white space for mobile installation services. Target battery-electric bus mandates in France and Spain as specification-forcing procurement channels. Pursue bio-based polyurethane qualification partnerships with Eindhoven polymer research institutes to preempt REACH authorization barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated tire manufacturers with tire-as-a-service contract portfolios. Long-term viability across the projection horizon rests on chemistry compliance capabilities and telematics integration depth. Monitor EU Green Deal circular economy target acceleration as inflection signal for pyrolysis infrastructure investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smart Sensor Modules | Bridgestone Corporation controls critical telemetry inputs for fleet monitoring systems. |
| Bio-Based Polyurethane Qualification | European compounders secure first-mover advantages under REACH diisocyanate exposure controls. |
| Tire-as-a-Service Contract Expansion | Integrated manufacturers capture maintenance budgets previously directed to independent distributors. |
| Homologation-Track Investment | Michelin sustains technology leadership through ECE R30 and NHTSA validation infrastructure. |
| Closed-Loop Material Recovery | Pyrolysis infrastructure development aligns with EU Green Deal circular economy targets. |
Research Methodology
Initial hypotheses were tested against primary input from tire R&D directors, fleet procurement managers, polymer compounder executives, and aftermarket distribution heads and refined through secondary validation across customs trade data, EPA emission filings, ECHA substance restriction updates, and SEC 10-K disclosures. Bottom-up segment sizing triangulated with top-down market reconstruction.
Variance decomposition across the modeling period isolates volume drivers from price-mix effects. Segmentation dimensions span product type, material chemistry, technology integration level, and end-user procurement authority. CAGRs derive from regression against fleet electrification timelines and regulatory compliance cost curves. Industry-specific inputs incorporate battery weight distribution specifications and sealant viscosity recalibration requirements.
Underlying assumptions cover REACH authorization timelines, NHTSA testing protocol stability, and petrochemical feedstock price bands, with deviation risk concentrated in regulatory expansion beyond diisocyanates and faster-than-expected fleet electrification procurement cycles. Recalibration cycles align with material shifts in EU F-Gas Regulation phasedown schedules and battery-electric platform rollout announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
United States Tire Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Automotive Retread Tires Market