
 Global Tire Curing Press Market | 2026-2036
Global Tire Curing Press Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tire Curing Press Market Outlook
The EU Green Deal is decoupling European tire curing press procurement from conventional hydraulic systems by embedding carbon intensity thresholds into industrial equipment standards. HF TireTech Group leverages its German engineering heritage to sustain premium positioning in energy-efficient press design. Mitsubishi Heavy Industries Machinery Systems Ltd. anchors Asian supply through integrated control system manufacturing in Japan. Himile Mechanical Science and Technology Co. Ltd. dominates domestic bidding for Chinese tire greenfield projects with localized service networks.
A tire curing press is a specialized industrial machine that applies controlled heat, typically between 160°C and 200°C, and pressure to shape and vulcanize green tires into finished products with precise tread patterns and structural integrity. The machine's curing chamber and heat transfer system determine cycle time consistency and final tire uniformity for high-speed automotive applications. Electric presses command expanding share in European and Japanese installations where factory electrification targets reshape capital planning. Hydraulic presses retain volume leadership across emerging Asian tire hubs where upfront cost sensitivity and heavy-duty commercial tire output predominate. Robotic operating modes represent the fastest-growing configuration as tire manufacturers pursue unmanned curing halls to offset labor shortages and tighten process control.
The EPA enforces emissions standards that indirectly shape curing press energy specifications for tires sold into the US vehicle fleet, while REACH and RoHS in Europe restrict hazardous substances in press coatings and electronic components. China's MIIT promotes GB standards for industrial equipment efficiency that filter into domestic tire factory procurement criteria. Stakeholders must monitor how divergent carbon accounting rules across Washington, Brussels, and Beijing fragment equipment certification requirements and reshape supplier compliance investments.
Market Dynamics
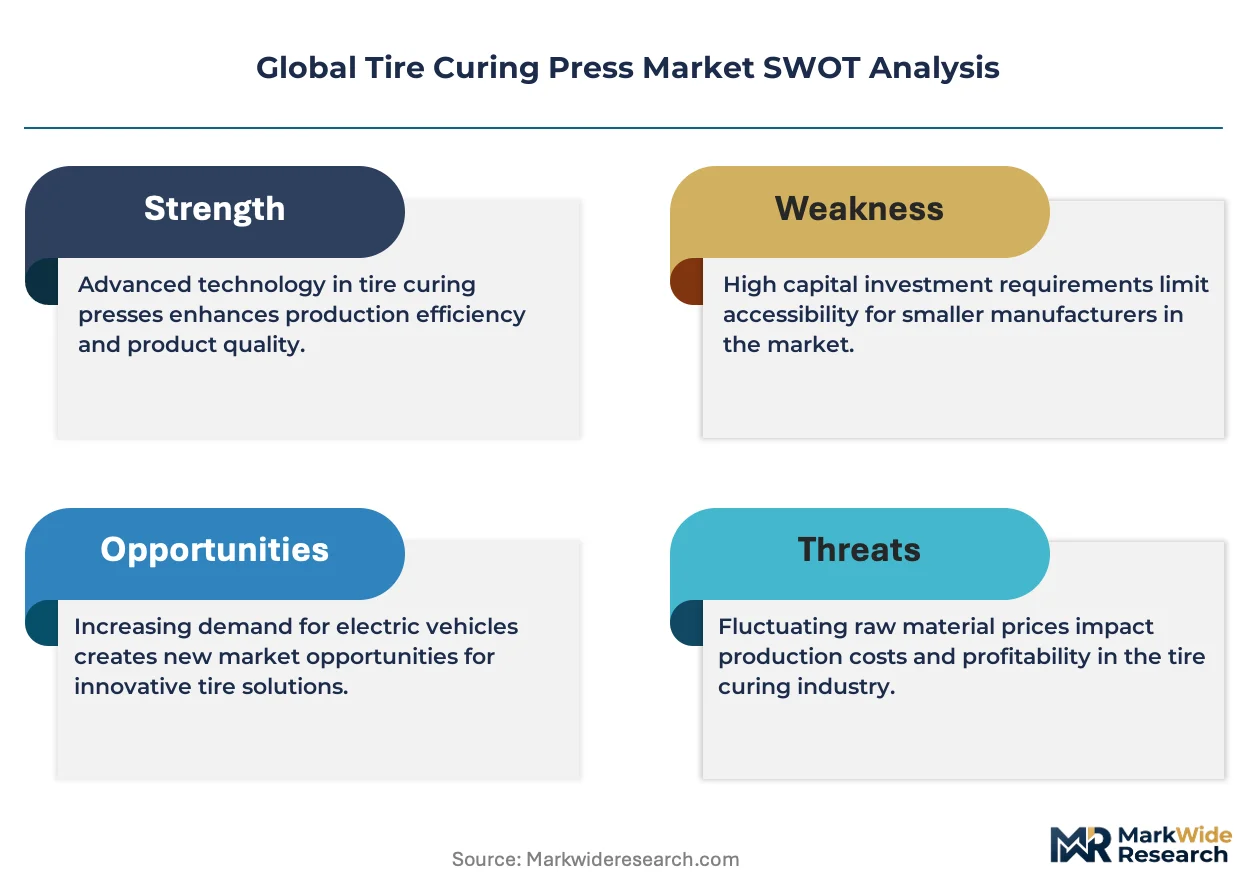
Factory electrification mandates across automotive supply chains are compressing the replacement cycle for hydraulic curing presses, forcing tire manufacturers to front-load capital expenditure for electric alternatives despite longer depreciation schedules on legacy equipment.
Growth Catalysts
- EU Green Deal industrial decarbonization:Carbon intensity thresholds embedded into equipment procurement specifications are accelerating replacement demand for energy-efficient curing systems in European tire plants.
- Passenger vehicle fuel efficiency mandates:Original equipment tire manufacturers are expanding curing capacity to supply lighter, lower-rolling-resistance tire designs required by NHTSA and EPA fleet standards.
- China greenfield automation:Domestic tire makers are commissioning fully automated curing lines with integrated robotic handling to minimize labor exposure in high-temperature production environments.
Market Restraints
- Steel alloy input volatility:Curing press frame and platen manufacturing depends on specialized heat-resistant steel grades subject to energy-intensive production cost swings.
- German engineering supply concentration:Premium electric press design capabilities cluster with a narrow base of Central European system integrators, creating procurement bottlenecks for Asian tire makers seeking European-grade efficiency.
- Hydraulic fluid environmental compliance:REACH restrictions on mineral oil formulations and biodegradability requirements are adding retrofit costs to installed hydraulic press bases.
Strategic Opportunities
- India tire manufacturing expansion:PLI scheme incentives for automotive component localization are attracting greenfield tire investments requiring complete curing press installation.
- Digital twin integration:Convergence of physics-based press simulation with real-time thermal sensor networks enables predictive maintenance contracts as a recurring revenue stream.
- US IRA clean manufacturing credits:Domestic content bonuses for industrial equipment are creating preferential positioning for presses assembled with qualifying North American electrical components.
Industry Challenges
- Vulcanization thermal engineering expertise:The specialized knowledge required for heat transfer system design is concentrating among retiring specialists, constraining supplier engineering capacity.
- Legacy hydraulic-electrical integration:Mixed-fleet tire plants face control system incompatibility when retrofitting electric presses alongside existing hydraulic curing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tire Curing Press Market |
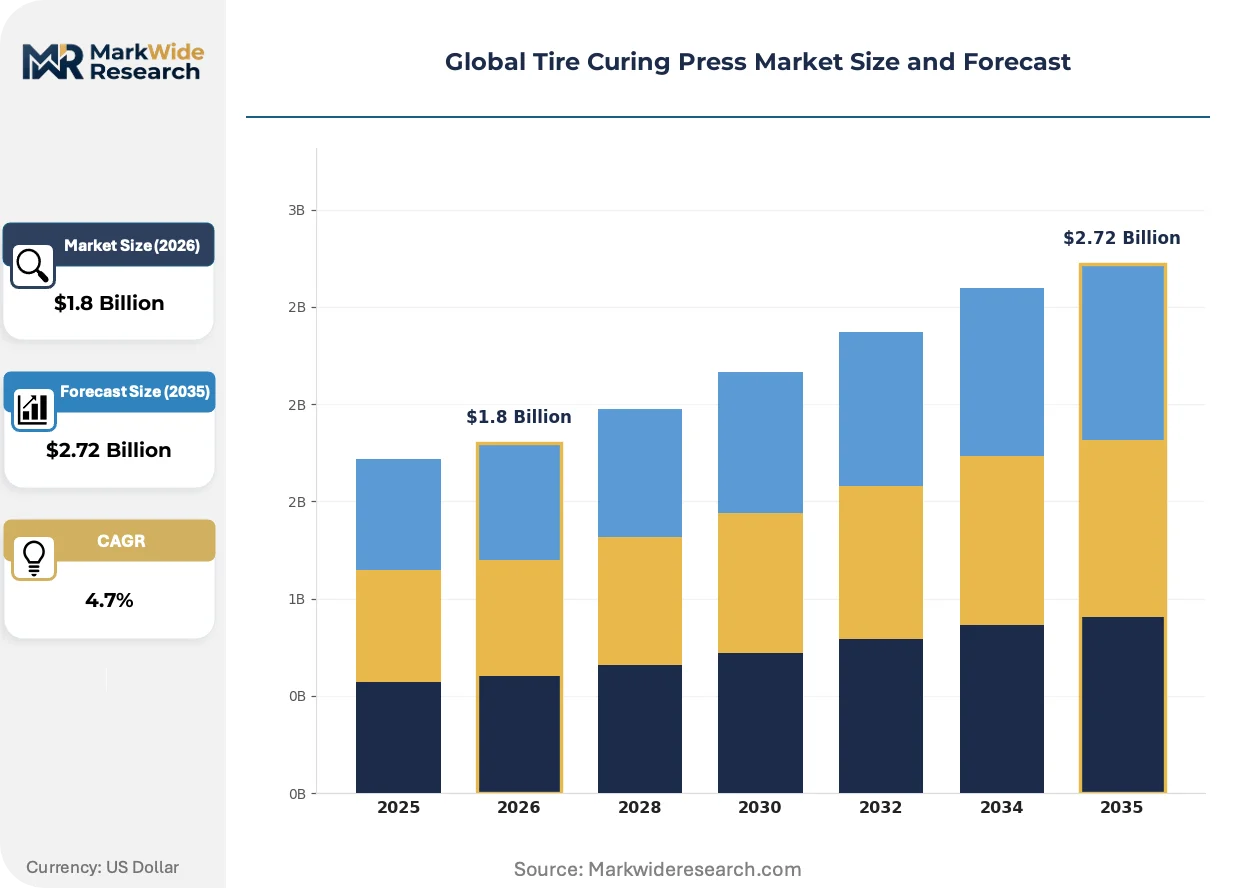
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Press, Electric Press, Pneumatic Press, Mechanical Press Operating Mode: Automatic, Semi-Automatic, Manual, Robotic End User: Passenger Vehicle Manufacturers, Commercial Vehicle Manufacturers, Aftermarket Providers, Tire Retreaders Component: Heat Transfer System, Control System, Press Frame, Curing Chamber |
| Companies Covered | HF TireTech Group, Mitsubishi Heavy Industries Machinery Systems Ltd., McNeil & NRM Inc., Larsen & Toubro Heavy Engineering, Kobe Steel Ltd., Himile Mechanical Science and Technology Co. Ltd., Greatoo Intelligent Equipment Inc., Harburg-Freudenberger Maschinenbau GmbH, Guilin Rubber Machinery Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tire Curing Press Market Strategic Shifts
Active thermal management and closed-loop control architectures are replacing open-loop hydraulic actuation as the dominant technical paradigm, compressing cycle time variability and enabling tighter final tire uniformity specifications.
Electric servo-motor press actuation is electrifying the power transmission architecture of curing systems, replacing hydraulic pumps and fluid circuits with direct-drive torque motors. Japanese and European tire manufacturers are specifying all-electric configurations for new greenfield installations despite 15-25% capital cost premiums. This transition is electrifying supplier R&D allocation toward motor thermal management and precision position control algorithms.
REACH substance restrictions and RoHS hazardous material limits are constraining coating formulations for curing press platens and bladder materials. Industrial consequence includes accelerated qualification timelines for alternative polymer formulations in high-temperature applications. European tire equipment procurement is most affected, with buyers now requiring full material disclosure documentation upstream of contract award.
Service contract unbundling is fragmenting the traditional bundled purchase model for curing press installations. Tire manufacturers are separating equipment procurement from multi-year maintenance agreements, awarding service to specialized regional technicians rather than OEM captive networks. This pattern is most visible in China's independent tire manufacturing sector, where domestic press makers compete aggressively on upfront price while foreign specialists capture aftermarket service margins.
Global Tire Curing Press Market Segmentation
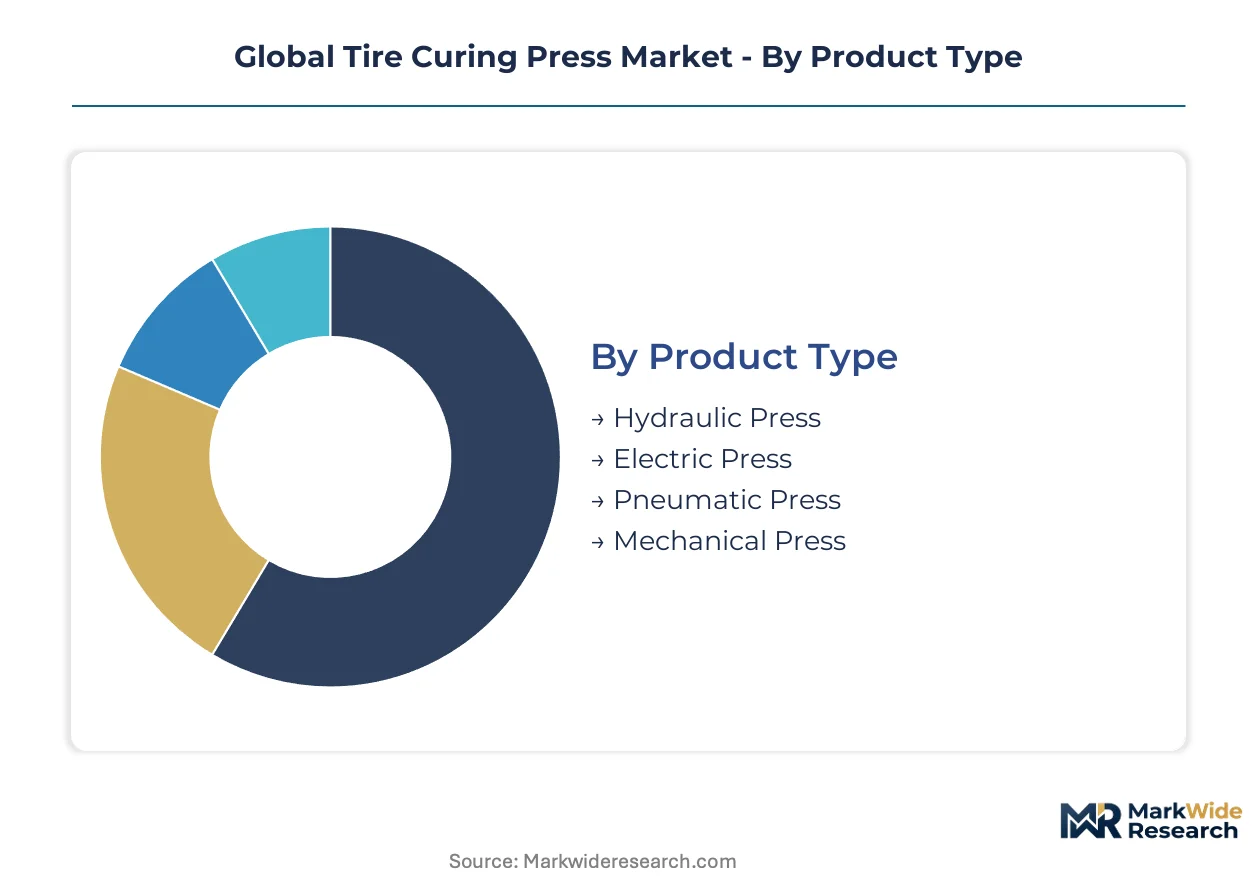
Tire curing press procurement decisions fragment across four distinct axes: power transmission architecture, automation intensity, customer tire category, and subsystem criticality. Each dimension carries divergent margin profiles and supplier qualification barriers that reshape competitive positioning.
Product Type:
Supply concentration in precision servo-motor manufacturing concentrates premium electric press production among Japanese and German system integrators.
- Hydraulic Press:Fluid-actuated power transmission using mineral oil circuits and piston-driven platens dominates installed base across emerging Asian tire hubs. Demand concentrates in China and India where upfront capital sensitivity and heavy-duty commercial tire output predominate, though REACH fluid restrictions are adding compliance retrofit costs.
- Electric Press:Direct-drive servo-motor actuation eliminates hydraulic infrastructure and enables sub-millimeter position control for high-uniformity passenger tires. European and Japanese tire manufacturers specify all-electric configurations for greenfield installations despite capital cost premiums, driven by factory electrification mandates and carbon intensity thresholds.
- Pneumatic Press:Compressed-air actuation serves niche low-volume retreading applications with simplified maintenance requirements.
- Mechanical Press:Crank-linkage systems persist in legacy installations requiring minimal electronic complexity.
Today's leader: Hydraulic Press. Tomorrow's challenger: Electric Press.
Operating Mode:
Cost tier stratification separates unmanned robotic installations from labor-dependent manual configurations.
- Automatic:Programmable logic controllers manage full curing cycles with integrated temperature-pressure profiling for high-volume passenger tire lines.
- Semi-Automatic:Operator-assisted loading with automated curing phase control balances throughput and labor flexibility for mid-scale tire plants.
- Manual:Direct operator control of heat and pressure parameters serves specialty tire prototyping and small-batch production.
- Robotic:Articulated arm systems for green tire loading and finished tire extraction enable fully unmanned curing halls. China domestic tire makers are scaling greenfield plants with integrated robotic handling to minimize labor exposure in high-temperature environments, representing the steepest expansion trajectory among operating configurations.
Volume concentration favors Automatic. Margin expansion concentrates in Robotic.
End User:
Application-specific performance requirements differentiate OEM tire uniformity standards from aftermarket cost optimization.
- Passenger Vehicle Manufacturers:Original equipment specifications demand sub-millimeter runout tolerances and thermal profile consistency for high-speed rated tires. NHTSA and EPA fleet efficiency mandates are expanding curing capacity for lighter, lower-rolling-resistance tire designs.
- Commercial Vehicle Manufacturers:Heavy-duty truck and bus tire production prioritizes cycle durability over uniformity precision, with longer curing cycles and reinforced bead construction.
- Aftermarket Providers:Replacement tire production scales across broad size ranges with flexible mold changeover systems.
- Tire Retreaders:Curing press specifications focus on precured tread bonding and lower-pressure envelope systems for commercial tire renewal.
Technology investment intensity peaks with Passenger Vehicle Manufacturers. Capacity expansion velocity concentrates in Commercial Vehicle Manufacturers.
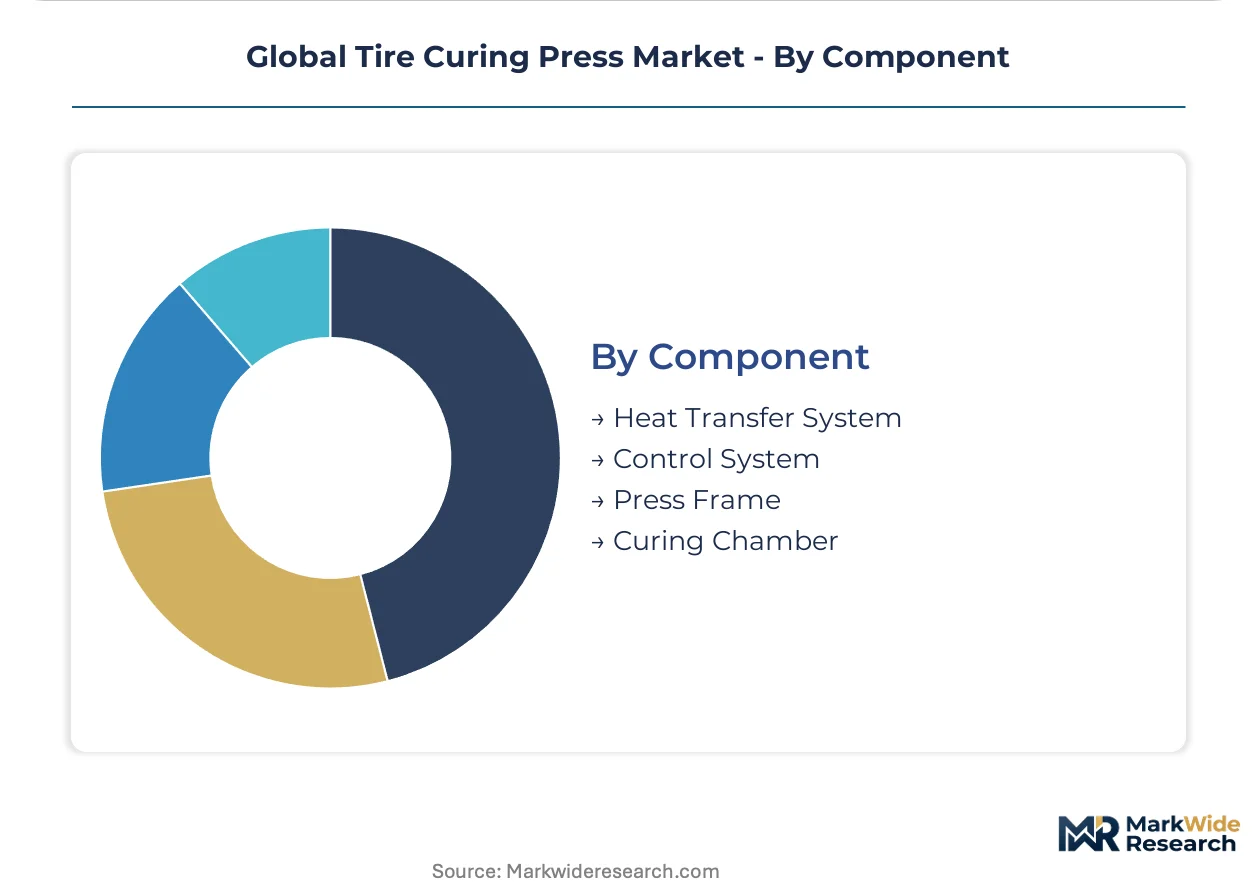
Component:
Subsystem margin distribution concentrates in thermal engineering and control electronics versus structural fabrication.
- Heat Transfer System:Steam, electric, or thermal oil circuits delivering 160°C to 200°C with ±2°C zone control determine cycle time consistency and final tire uniformity. EU Green Deal decarbonization requirements are pressuring redesign for lower energy intensity.
- Control System:Programmable automation controllers and HMI interfaces integrate press operation with factory MES networks. Japanese and European suppliers anchor premium positioning through integrated manufacturing.
- Press Frame:Heat-resistant steel alloy structures provide dimensional stability under thermal cycling and mold clamping loads.
- Curing Chamber:Segmented mold containment systems with bladder inflation mechanisms define final tread pattern replication.
Value capture concentrates in Heat Transfer System. Differentiation potential sits with Control System.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial vulcanization equipment manufacturing during the early automotive era, establishing engineering standards that persist in contemporary curing press design. The sector's geographic footprint now spans three continents with distinct procurement patterns shaped by local tire production economics and regulatory frameworks.
China
Domestic tire makers are commissioning fully automated greenfield plants with robotic curing lines to serve electric vehicle OEMs. MIIT promotes GB standards for industrial equipment efficiency that filter into factory procurement criteria. Shandong Province hosts the densest concentration of press installations, where Himile Mechanical Science and Technology Co. Ltd. leverages localized service networks to dominate bidding for new capacity.
Germany
Original equipment tire manufacturers are retrofitting curing halls to meet EU Green Deal carbon intensity thresholds embedded in equipment standards. REACH restrictions on hydraulic fluid formulations and RoHS hazardous material limits constrain coating selections for press platens. The Ruhr industrial corridor retains premium electric press engineering capabilities, though supplier concentration creates procurement bottlenecks for Asian buyers seeking European-grade efficiency.
United States
NHTSA and EPA fleet efficiency mandates are expanding curing capacity for lighter, lower-rolling-resistance tire designs required in passenger vehicle OEM supply. The Inflation Reduction Act clean manufacturing credits create preferential positioning for presses assembled with qualifying North American electrical components. Southeast tire manufacturing clusters in South Carolina and Tennessee are front-loading capital expenditure for electric alternatives despite longer depreciation schedules on legacy hydraulic equipment.
Japan
METI factory electrification targets are reshaping capital planning for integrated tire makers with domestic curing operations. Mitsubishi Heavy Industries Machinery Systems Ltd. anchors Asian supply through control system manufacturing anchored in Japanese industrial centers. The Kansai region maintains specialized servo-motor integration expertise for high-uniformity passenger tire applications.
India
PLI scheme incentives for automotive component localization are attracting greenfield tire investments requiring complete curing press installation. Commercial vehicle tire output predominates in current capacity expansion, prioritizing cycle durability over uniformity precision. Gujarat and Tamil Nadu industrial corridors are emerging as primary destinations for hydraulic press deployments where upfront capital sensitivity shapes procurement decisions.
Global Tire Curing Press Market Competitive Environment
Premium-margin players sit above commodity-margin players across energy efficiency certification and control system integration depth. The vendor base stratifies into three tiers: German and Japanese system integrators commanding electric press premiums, Chinese fabricators capturing volume through localized service networks, and mid-scale specialists serving retreading and niche applications. Consolidation pressure is accelerating as factory electrification mandates compress replacement cycles and tire manufacturers consolidate supplier relationships around multi-site service capability.
Within the premium engineering tier, HF TireTech Group exemplifies German heritage positioning in energy-efficient press design, while Mitsubishi Heavy Industries Machinery Systems Ltd. represents integrated control system manufacturing anchored in Japanese industrial infrastructure. Himile Mechanical Science and Technology Co. Ltd. occupies the scale-driven domestic Chinese segment, leveraging proximity to greenfield tire plant investments. These three archetypes illustrate how geographic origin and manufacturing integration depth determine competitive positioning across diverging regional procurement criteria.
| Leading Market Players |
|---|
| HF TireTech Group |
| Mitsubishi Heavy Industries Machinery Systems Ltd. |
| McNeil & NRM Inc. |
| Larsen & Toubro Heavy Engineering |
| Kobe Steel Ltd. |
| Himile Mechanical Science and Technology Co. Ltd. |
| Greatoo Intelligent Equipment Inc. |
| Harburg-Freudenberger Maschinenbau GmbH |
| Guilin Rubber Machinery Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of servo-motor control systems anchors premium pricing power for Japanese and German system integrators, while outsourced fabrication of hydraulic assemblies compresses margins for Chinese volume suppliers serving cost-sensitive greenfield projects.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by energy efficiency certification grade and control system integration depth. Premium electric presses from German and Japanese suppliers command substantial markups based on EU Green Deal carbon intensity compliance and sub-millimeter position control specifications. Price erosion runs through the hydraulic press tier as Himile and Greatoo compete aggressively on upfront capital costs for Chinese domestic tire makers. Aftermarket service unbundling intensifies buyer price sensitivity among independent tire manufacturers seeking to separate equipment procurement from maintenance contracts.
Supply Chain Analysis
Single-source vulnerability sits with specialized heat-resistant steel alloy suppliers concentrated in Germany, Japan, and South Korea. Curing press frame and platen manufacturing draws from nickel-chromium-molybdenum steel grades subject to energy-intensive production cost swings. REACH restrictions on mineral oil formulations and RoHS hazardous material limits constrain hydraulic fluid and coating supply alternatives. Distribution runs through OEM captive networks for premium electric installations, while regional service specialists capture aftermarket margins in China's independent tire sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as factory electrification mandates and EU carbon intensity thresholds shift procurement criteria toward energy-efficient press specifications with premium engineering content.
For Market Incumbents: Lock in multi-site service contracts with Asian tire makers before domestic Chinese suppliers expand aftermarket capabilities. Defend margin position by deepening backward integration into servo-motor thermal management systems, the component tier where Japanese specialists currently anchor premium positioning. Accelerate qualification of alternative polymer formulations for high-temperature bladder applications ahead of tightening REACH substance restrictions. For New Entrants and Emerging Players: Enter via India's PLI scheme-funded greenfield tire corridor, where commercial vehicle capacity expansion creates demand for hydraulic press installations with lower technical barriers. Target Gujarat and Tamil Nadu industrial clusters with localized service partnerships that offset German and Japanese incumbents' control system integration advantages. Position around rapid mold changeover systems for aftermarket tire producers seeking flexible production configurations. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service specialists because tire manufacturers are unbundling maintenance contracts from equipment procurement, fragmenting the traditional OEM captive service model. Focus acquisition screening on technicians with MIIT GB standards certification and proven robotic curing line integration experience. Watch for inflection when Chinese domestic press makers begin capturing premium electric press share in Southeast Asian export markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Motor Manufacturing | Japanese and German suppliers anchor premium positioning through captive control system production. |
| Digital Twin Platform Development | Physics-based press simulation enables predictive maintenance contracts as recurring revenue streams. |
| Green Manufacturing Transition | EU Green Deal carbon intensity thresholds force heat transfer system redesign for lower energy intensity. |
| Long-term Supply Agreement | Steel alloy input volatility drives tire makers toward fixed-price contracts with specialized foundries. |
| Joint Venture for Regional Service Networks | Foreign specialists partner with local technicians to capture aftermarket margins in China's independent sector. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with tire plant maintenance directors, OEM procurement teams, aftermarket service heads, and thermal engineering specialists with secondary validation from MIIT GB standard filings, EU ETS equipment certification databases, SEC 10-K disclosures from listed tire manufacturers, and customs trade data on heat-resistant steel alloy imports. Bottom-up press installation counts triangulated against top-down tire production capacity estimates.
Segment-weighting approaches distributed value and volume across power transmission architecture, automation intensity, end-use tire category, and subsystem criticality dimensions. CAGRs derived from regression analysis of historical replacement cycles, greenfield investment announcements, and regulatory mandate timelines. Forecast inputs incorporated factory electrification policy trajectories from METI and EU Green Deal implementation schedules alongside tire OEM fuel efficiency compliance requirements from NHTSA and EPA.
Inputs from plant-level engineering contacts were available through the study window; gaps in proprietary thermal sensor network performance data introduce uncertainty bands around digital twin adoption velocity. Forecasts reflect assumptions about REACH substance restriction timelines and steel alloy cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Truck and Bus Tires Market