
 Global Ultra High Performance Tire Market | 2026-2036
Global Ultra High Performance Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultra High Performance Tire Market Outlook
China's eastern manufacturing corridor is reshaping supply dynamics for ultra high performance tires as domestic producers expand high-speed-rated capacity. Michelin leverages captive rubber sourcing and vertical integration to sustain margin control across European and North American channels. Bridgestone anchors its position through R&D intensity in run-flat and noise-reduction architectures. Continental AG differentiates via embedded sensor technology for tire-pressure and tread-wear monitoring.
Ultra high performance tires incorporate specialized silica-reinforced tread compounds, aramid or rayon belt packages, and speed ratings of W, Y, or above to sustain sustained velocities exceeding 168 mph while delivering lateral grip coefficients above 0.9g on dry surfaces. The summer tire category dominates absolute volume within product-type splits, though all-season variants are capturing incremental share in temperate climates where consumers avoid seasonal changeovers. Sports cars and performance SUVs represent the densest margin pools within end-user segmentation, with original equipment fitment commanding premium pricing over replacement channels.
EU regulators through ECHA and the F-Gas Regulation enforce rolling-resistance and wet-grip labeling standards that filter non-compliant products from member-state markets. NHTSA in the United States maintains separate UTQG grading protocols for treadwear, traction, and temperature resistance, creating a dual-compliance burden for multinational suppliers. China's SAMR and GB standards authorities are tightening local certification requirements for speed-rated tires sold through domestic channels. Stakeholders must monitor divergent test protocols between jurisdictions and anticipate whether Chinese standard harmonization or EU label expansion will dictate the next product-design cycle.
Market Dynamics
Factory-fit contracts from German and Italian sports car manufacturers are compressing replacement channel margins while accelerating R&D cycles for speed-rated compounds.
Growth Catalysts
- ECHA Rolling-Resistance Mandates:EU labeling standards under ECHA and the F-Gas Regulation are filtering non-compliant products from member-state markets, creating captive demand for certified ultra high performance tires.
- Silica-Reinforced Compound Advances:Specialized tread formulations incorporating advanced silica packages are enabling W and Y speed ratings while maintaining wet-grip coefficients above regulatory minimums.
- China's Eastern Manufacturing Corridor:Domestic producers in Jiangsu and Zhejiang provinces are scaling high-speed-rated capacity, reshaping supply availability for Asian performance vehicle markets.
Market Restraints
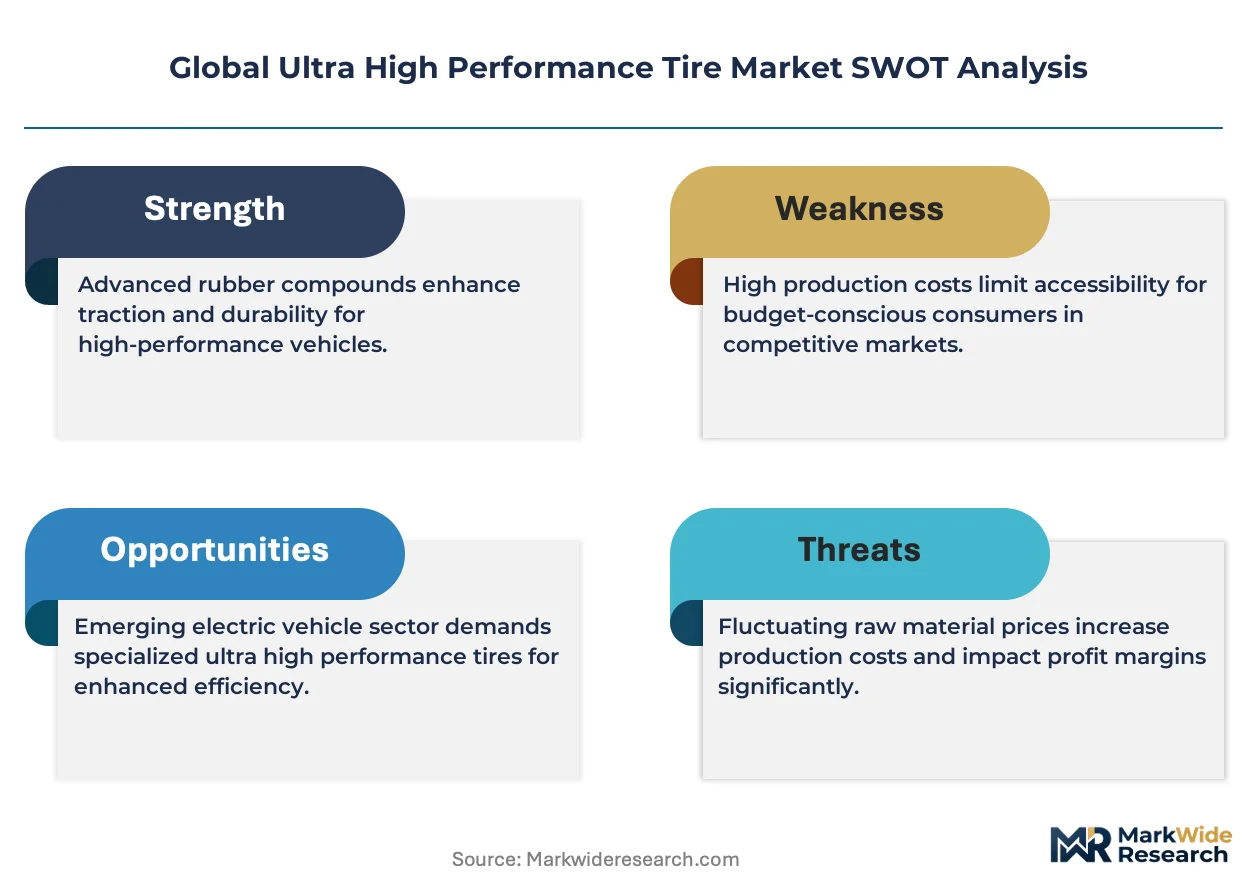
- Aramid and Rayon Input Volatility:Belt package materials face price instability from petrochemical feedstock fluctuations and specialty fiber supply constraints.
- Speed-Rating Certification Burden:China's SAMR and GB standards authorities impose divergent test protocols that extend approval timelines for multinational suppliers.
- Run-Flat Architecture Tradeoffs:Reinforced sidewall designs necessary for extended mobility applications compromise ride comfort and increase unsprung weight penalties.
Strategic Opportunities
- Embedded Sensor Integration:Tire-pressure and tread-wear monitoring systems are converging with vehicle telematics platforms, creating recurring revenue streams through data services.
- All-Season Variant Expansion:Temperate climate markets in the US Pacific Northwest and UK Midlands show underpenetration for high-performance all-season products that eliminate seasonal changeover costs.
- India's Performance SUV Segment:BIS certification pathways for imported speed-rated tires remain underdeveloped, presenting first-mover advantages for compliant suppliers.
Industry Challenges
- Compound Formulation Talent Scarcity:Specialized knowledge in silica dispersion chemistry and low-rolling-resistance polymer science concentrates among a limited pool of R&D specialists in Germany and Japan.
- Dual-Compliance Test Burden:NHTSA UTQG grading protocols for treadwear and traction operate on separate methodologies from EU wet-grip assessments, forcing redundant validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultra High Performance Tire Market |
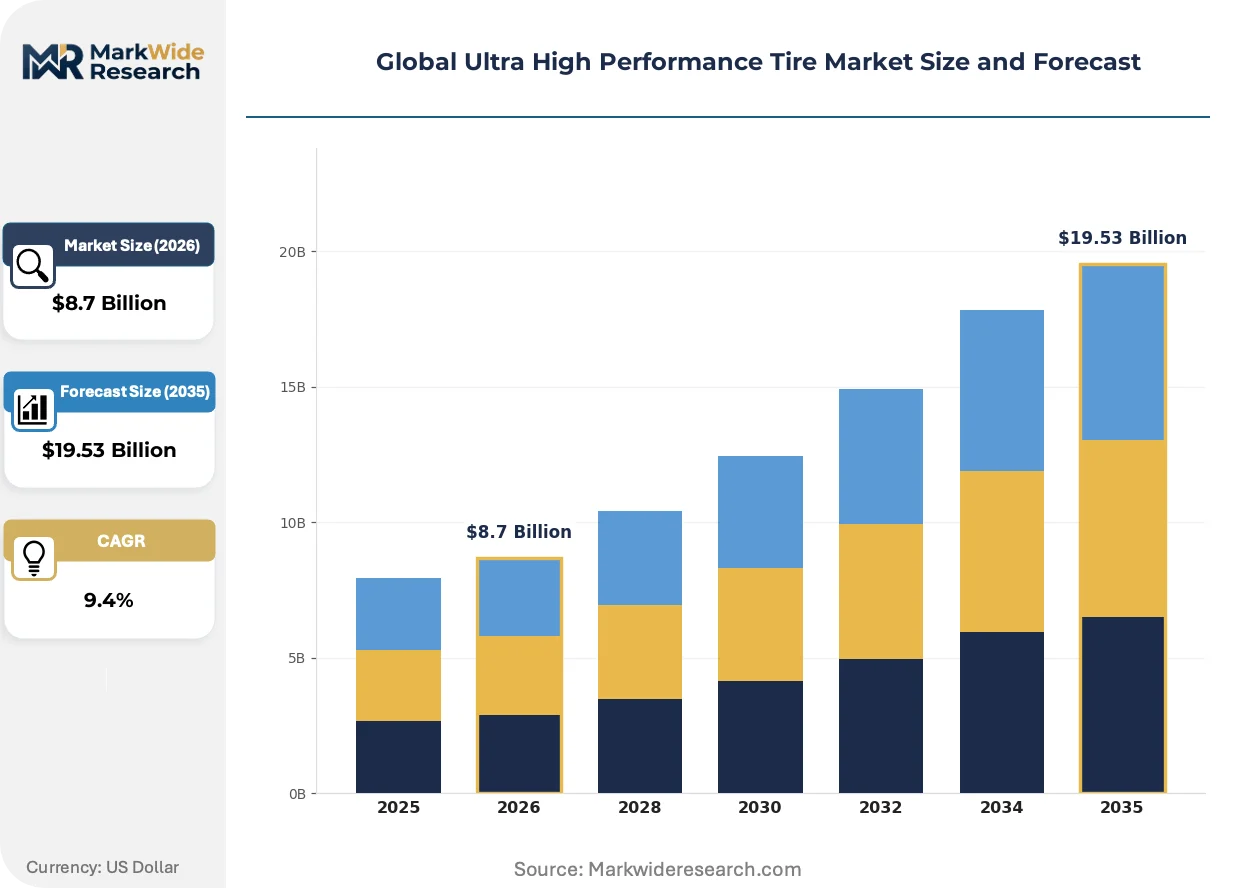
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Season, Summer, Winter, Performance End User: Passenger Vehicles, SUVs, Trucks, Sports Cars Distribution Channel: Online Retail, Specialty Stores, Automotive Dealerships, Mass Merchants Size: Low Profile, Standard Profile, Wide Profile, Others |
| Companies Covered | Michelin, Bridgestone Corporation, Goodyear Tire & Rubber Company, Continental AG, Pirelli, Sumitomo Rubber Industries, Hankook Tire & Technology, Yokohama Rubber Co. Ltd., Toyo Tire Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultra High Performance Tire Market Strategic Shifts
Digital twin technology is virtualizing tire development workflows, compressing prototype cycles while regulatory pressure on rolling resistance intensifies compound innovation.
Simulation-based tread pattern optimization is virtualizing the traditional physical prototyping phase. Performance tire divisions at major suppliers now deploy finite element analysis for block stiffness and siping geometry before mold production. This shift collapses development timelines from 18 months to under 10 months for new speed-rated introductions.
ECHA enforcement of updated F-Gas Regulation thresholds for tire manufacturing emissions is accelerating solvent-free mixing process adoption. Compounders must reformulate carbon black dispersions and eliminate aromatic oils from tread packages. Original equipment channels face the steepest compliance costs, passing through price adjustments to sports car manufacturers.
Direct-to-consumer fitment scheduling through manufacturer-owned digital platforms is displacing traditional wholesale-distributor relationships in replacement channels. Performance vehicle owners in Germany and California now book installation appointments concurrent with tire purchase, bypassing independent dealer networks. This channel compression threatens margin pools for regional tire distributors while capturing behavioral data for predictive replacement marketing.
Global Ultra High Performance Tire Market Segmentation
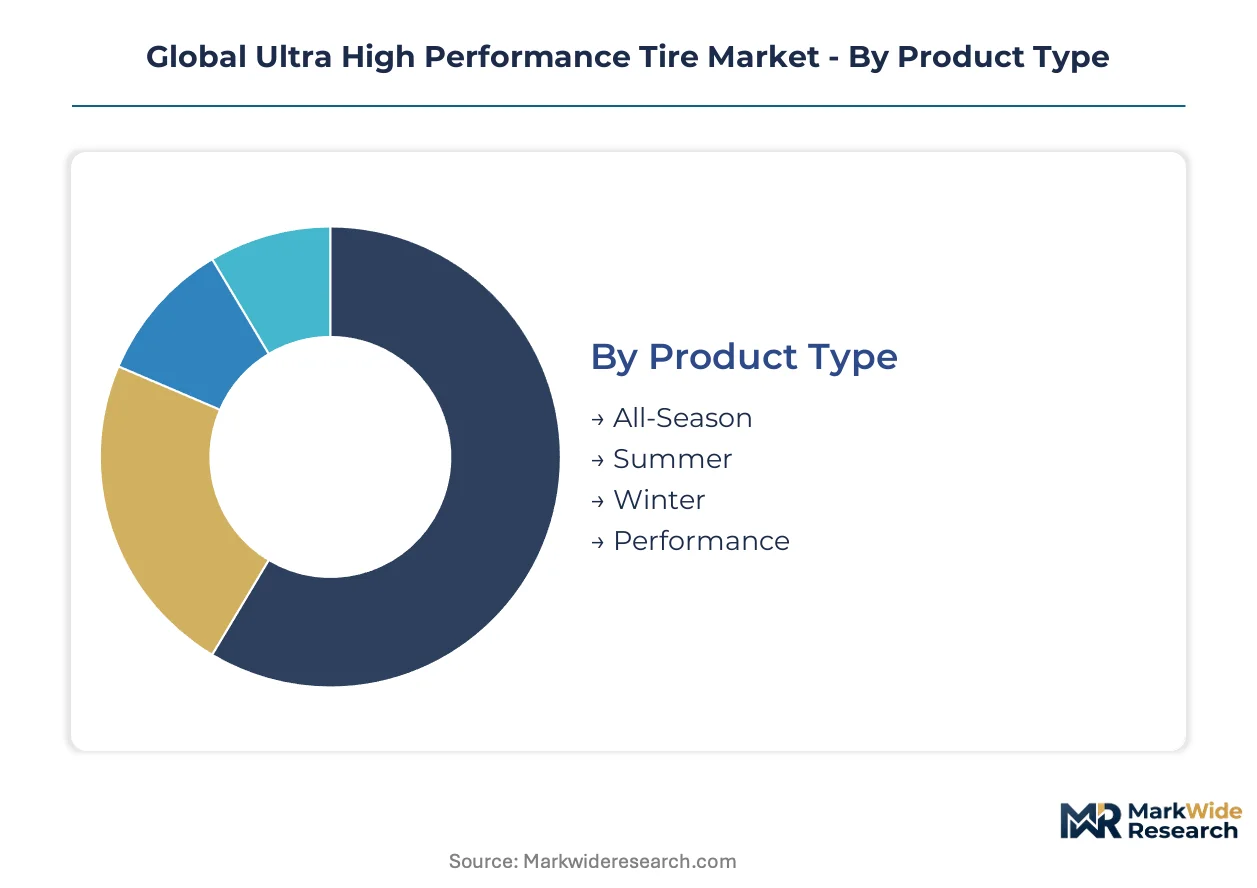
Ultra high performance tire segmentation reveals divergent technical requirements across climate zones, vehicle architectures, and procurement channels. Manufacturers must calibrate compound formulations, speed ratings, and sidewall constructions to match specific end-use stress profiles rather than pursuing universal specifications.
Product Type:
Mature summer compounds dominate absolute volume while emerging all-season formulations capture temperate-market share through convenience positioning.
- Summer:Specialized tread compounds incorporating advanced silica packages deliver W and Y speed ratings with dry lateral grip coefficients above 0.9g. Sports car manufacturers in Germany and Italy specify summer-only fitments for factory delivery, anchoring premium pricing in original equipment channels.
- All-Season:Tread patterns balance siping density for wet traction against block rigidity for dry cornering, compromising ultimate performance for year-round utility. Demand concentrates in the US Pacific Northwest and UK Midlands where seasonal changeover costs outweigh performance tradeoffs.
- Winter:Ultra high performance winter variants employ specialized rubber compounds maintaining elasticity below 7°C alongside aggressive tread voids for snow evacuation. Niche positioning limits volume to Nordic markets and Alpine corridor applications.
- Performance:Entry-level ultra high performance classification bridges mass-market touring tires with dedicated speed-rated products, targeting price-sensitive enthusiasts in China's eastern manufacturing corridor.
Summer retains volume leadership; all-season holds the steepest expansion curve.
End User:
Cost tier segmentation separates factory-fit premium channels from price-sensitive replacement procurement patterns.
- Sports Cars:Mid-engine and rear-wheel-drive architectures demand asymmetric tread patterns and reinforced shoulder blocks for sustained lateral loading. Italian and German OEMs contract exclusive supply agreements, compressing replacement channel margins while accelerating R&D cycles.
- SUVs:Performance SUV applications require higher load ratings and reinforced sidewall structures to manage elevated center-of-gravity dynamics. China's luxury SUV segment drives disproportionate growth for 19-inch and above fitments.
- Passenger Vehicles:Sedan-based performance variants from Japanese and Korean manufacturers prioritize NVH reduction alongside speed capability, favoring comfort-biased compound tuning.
- Trucks:Light truck performance applications remain limited to modified pickup configurations, with demand clustering in Texas and California aftermarket channels.
Sports cars command margin leadership; SUVs demonstrate the steepest expansion trajectory.
Distribution Channel:
Volume concentration varies sharply between original equipment capture and replacement channel fragmentation.
- Automotive Dealerships:Factory-authorized service centers dominate warranty-period replacements and brand-loyal repurchase cycles. German luxury networks in particular enforce strict OE-specification adherence, limiting cross-brand substitution.
- Specialty Stores:Independent performance tire retailers provide fitment expertise and alignment services for enthusiast segments. California and Florida host densest specialty store networks supporting modified vehicle cultures.
- Online Retail:Direct-to-consumer platforms capture growing share through fitment verification tools and mobile installation scheduling. Channel compression threatens regional distributor margins while generating behavioral data for predictive marketing.
- Mass Merchants:Big-box retailers compete on price for commoditized fitments, though limited speed-rated inventory constrains ultra high performance participation.
Automotive dealerships retain volume leadership; online retail is climbing the fastest.
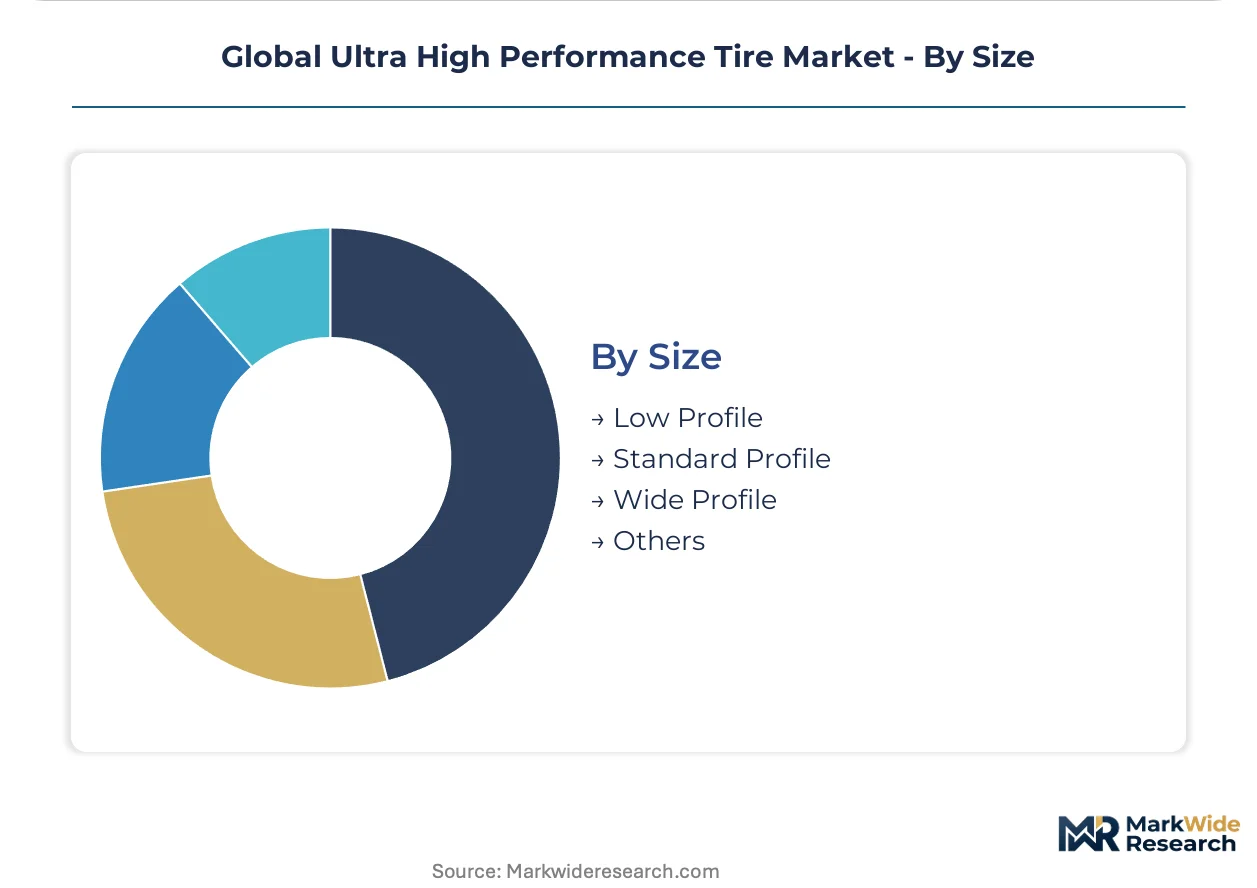
Size:
Application geometry dictates load rating, sidewall compliance, and contact patch optimization requirements.
- Low Profile:Aspect ratios below 35 prioritize steering response and brake cooling through minimal sidewall deflection. Sports car OEMs specify low-profile fitments for 20-inch and above wheel diameters, accepting ride quality tradeoffs.
- Wide Profile:Section widths exceeding 275mm maximize contact patch for high-horsepower applications. German autobahn-tuned vehicles and American muscle cars drive specification diversity in this category.
- Standard Profile:Balanced aspect ratios between 40 and 50 maintain everyday usability for performance sedans and crossovers. Volume concentration supports manufacturing scale advantages.
- Others:Niche fitments including staggered axle configurations and run-flat reinforcements address specific vehicle platform requirements.
Standard profile retains volume leadership; low profile is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automotive logistics infrastructure underwrites Europe's role in ultra high performance tire distribution, while China's Ningbo-Zhoushan port complex anchors Asian supply chain throughput for high-speed-rated compounds.
United States
NHTSA's UTQG grading protocols for treadwear and traction create compliance complexity for speed-rated imports. California's specialty tire retail density supports enthusiast culture around modified vehicles. The Pacific Northwest corridor shows underpenetration for all-season ultra high performance variants.
Germany
Autobahn-tuned vehicle specifications drive demand for W and Y speed ratings above 168 mph sustained velocity. ECHA enforcement of F-Gas Regulation thresholds accelerates solvent-free mixing process adoption among compounders. Baden-Württemberg's automotive engineering cluster hosts R&D facilities for silica-reinforced tread formulations.
China
Domestic luxury SUV expansion concentrates demand for 19-inch and above fitments in the Yangtze River Delta. SAMR and GB standards authorities impose divergent speed-rating certification protocols that extend approval timelines. Jiangsu and Zhejiang provinces scale manufacturing capacity for high-speed-rated products.
Italy
Mid-engine and rear-wheel-drive sports car architectures require asymmetric tread patterns with reinforced shoulder blocks. EU tire-labeling regulations under ECHA filter non-compliant products from member-state markets. Modena and Maranello anchor factory-fit contract negotiations between OEMs and tire suppliers.
India
Performance SUV segment growth outpaces sedan-based variants in Maharashtra and Karnataka. BIS certification pathways for imported speed-rated tires remain underdeveloped, creating regulatory friction. Chennai's automotive corridor attracts first-mover suppliers seeking compliant market entry.
Global Ultra High Performance Tire Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in compound and belt package supply. The vendor base concentrates around five multinational conglomerates with captive rubber sourcing and vertical manufacturing control. Two strategic archetypes dominate: integrated compound-to-tire manufacturers and technology-licensing specialists. Competitive moves center on embedded sensor integration partnerships and direct-to-consumer platform deployment.
Among European-headquartered suppliers, Continental AG exemplifies the embedded technology archetype through tire-pressure and tread-wear monitoring systems. Bridgestone Corporation anchors the run-flat architecture segment with R&D intensity in noise-reduction sidewall designs. Michelin represents backward integration excellence through captive natural rubber sourcing and compound formulation control.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone Corporation |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Pirelli |
| Sumitomo Rubber Industries |
| Hankook Tire & Technology |
| Yokohama Rubber Co. Ltd. |
| Toyo Tire Corporation |
| Others |
Value Chain & Pricing Dynamics
Aramid and rayon fiber price volatility from petrochemical feedstock swings determines both the spread between premium and entry-tier ultra high performance tire pricing and the geographic clustering of belt-package manufacturing. Suppliers with captive synthetic fiber production command tier-one positioning, while compounders exposed to spot aramid markets absorb margin compression that reshapes sourcing footprints toward integrated rubber-fiber corridors.
Pricing Analysis
Volume-discount tiering structures separate original equipment contracts from replacement channel procurement, with factory-fit agreements commanding premium positioning through exclusive speed-rating certifications and co-development R&D clauses. Price differentiation rests on wet-grip grade thresholds under ECHA labeling and the presence of embedded sensor architectures for telematics integration. Cost compression in the replacement tier is intensifying because Chinese domestic brands are scaling W and Y speed-rated capacity in Jiangsu province. Sports car OEMs demonstrate the lowest price sensitivity, while mass-market performance sedan owners in the Pacific Northwest exhibit acute elasticity to seasonal promotion cycles.
Supply Chain Analysis
Upstream feedstock dependencies center on natural rubber plantations in Thailand and Indonesia, high-purity silica processing in China, and aramid fiber production in the United States and Japan. Synthetic rubber polymerization draws from styrene and butadiene feedstocks anchored in South Korean and German petrochemical complexes. Single-source vulnerability concentrates in specialty silica grades required for low-rolling-resistance compounds, where three suppliers control qualification pathways for ECHA-compliant formulations. Distribution runs through Rotterdam's automotive logistics hub for European OEM channels, while Ningbo-Zhoushan anchors Asian throughput for high-speed-rated export volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra high performance tire penetration sits at early-cycle expansion, with embedded sensor integration and direct-to-consumer platform adoption representing underexploited vectors that will capture incremental margin pools as vehicle telematics standardizes.
For Market Incumbents: Pre-empt Chinese domestic scaling by securing exclusive factory-fit contracts with German and Italian sports car manufacturers before SAMR certification pathways mature for local competitors. Deepen backward integration into natural rubber sourcing to insulate margin structures from commodity volatility, while accelerating solvent-free mixing process adoption to satisfy tightening F-Gas Regulation thresholds. For New Entrants and Emerging Players: Pursue all-season variant white space in the US Pacific Northwest and UK Midlands, where temperate climate convenience positioning remains underpenetrated relative to summer-dominant portfolios. Target India's performance SUV segment through Chennai corridor manufacturing partnerships before BIS certification pathways solidify around incumbent qualification histories. Deploy direct-to-consumer fitment scheduling platforms to bypass entrenched wholesale-distributor relationships and capture behavioral data assets. For Investors and Strategic Acquirers: ECHA's updated F-Gas Regulation enforcement reshapes the acquisition landscape toward compounders with proven solvent-free formulation capabilities and captive silica supply agreements. Long-term viability across the projection horizon favors integrated manufacturers with R&D concentration in Germany or Japan, where specialized polymer science talent pools concentrate. Watch for SAMR harmonization signals with EU test protocols as the inflection indicator for Chinese market access rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Sensor Integration | Convergence with vehicle telematics platforms creates recurring data-service revenue streams for tire-pressure monitoring. |
| Solvent-Free Mixing Adoption | ECHA F-Gas Regulation compliance eliminates aromatic oils and carbon black dispersion solvents from tread compound production. |
| Direct-to-Consumer Platform Deployment | Manufacturer-owned digital fitment scheduling bypasses independent dealer networks and captures replacement cycle behavioral data. |
| All-Season Variant Expansion | Temperate climate markets in the Pacific Northwest and UK Midlands show underpenetration for year-round high-performance products. |
| Backward Integration into Natural Rubber | Captive plantation sourcing insulates margin structures from commodity price volatility in Southeast Asian supply corridors. |
Study Parameters
Desk research of trade customs data, SEC filings from tire manufacturers, ECHA regulatory submissions, and vehicle production databases preceded structured interviews with OEM platform engineers, aftermarket distributor operations heads, compound R&D directors, and SAMR certification consultants. Primary fieldwork captured procurement patterns across German luxury dealership networks, California specialty tire retail channels, and Yangtze River Delta manufacturing clusters. Secondary validation drew from NHTSA UTQG grading protocols, EU tire-labeling compliance registries, and IHS Markit vehicle registration data. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions.
Assumptions held fixed include ECHA enforcement intensity, NHTSA protocol stability, and Chinese domestic brand speed-rating qualification timelines; varied parameters encompassed aramid fiber price trajectories and embedded sensor adoption curves across premium vehicle segments. The analytical framework modeled volume and value outputs across product type, end-user vehicle architecture, distribution channel, and regional production cluster dimensions throughout the forecast period. CAGRs derived from segment-level elasticity functions applied to vehicle production forecasts and replacement cycle frequency assumptions, with silica-reinforced compound cost curves and speed-rating certification throughput rates as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, synthetic rubber feedstock pricing, or EU-China regulatory harmonization timelines would shift the trajectory. Cross-checking against vehicle OEM procurement disclosure patterns and customs trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
EV Tire Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Agricultural Tires Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Two Wheeler Tire Market