
 Automotive Intelligent Tires Market | 2026-2036
Automotive Intelligent Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Intelligent Tires Market Analysis
Embedded systems engineering talent scarcity is redrawing competitive boundaries across the Automotive Intelligent Tires landscape. Bridgestone Corporation leverages captive semiconductor partnerships to secure sensor supply chains. Continental AG anchors European production with dedicated cleanroom facilities for tire-integrated chip fabrication. Michelin Group differentiates through proprietary radio-frequency protocols that bypass third-party connectivity modules.
Automotive intelligent tires integrate microelectromechanical sensors, conductive elastomer compounds, and low-power wireless transceivers within the tire carcass to transmit real-time pressure, temperature, and tread-depth data to vehicle control units. These systems enable predictive maintenance scheduling, autonomous vehicle path planning, and dynamic load balancing across commercial fleets. Sensor-embedded tires command the dominant revenue share as OEMs mandate continuous telemetry for electric vehicle range optimization. Connectivity solutions represent the fastest-expanding technology segment as 5G vehicle-to-infrastructure protocols mature. Fleet operators constitute the highest-margin end-user channel due to volume procurement contracts and outcome-based service agreements.
NHTSA mandates TPMS integration on all US light vehicles, while ECE R64 governs run-flat performance standards across Europe and Japan's METI enforces JIS compatibility for connected mobility platforms. These frameworks compel manufacturers to maintain parallel certification laboratories, elevating fixed costs for new entrants. Stakeholders must weigh captive sensor production against fabless partnerships as semiconductor geopolitics intensify and tire OEMs renegotiate long-term foundry access.
Market Dynamics
Semiconductor supply chain volatility is forcing tire manufacturers to choose between captive sensor fabrication and fabless partnerships, fundamentally restructuring competitive moats around chip access rather than rubber chemistry alone.
Growth Catalysts
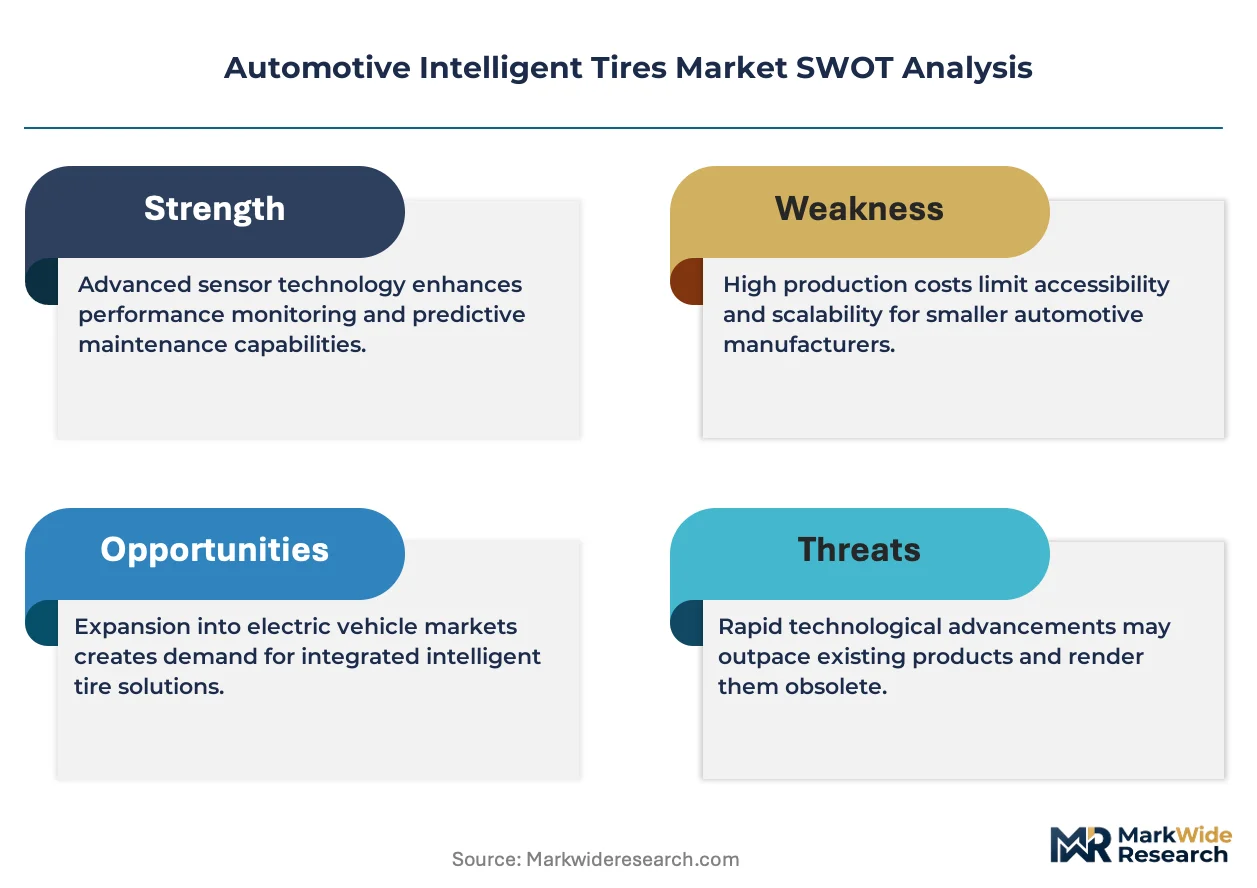
- NHTSA TPMS Mandates:Federal requirements for continuous tire-pressure monitoring on all US light vehicles compel OEM integration of telemetry-enabled tires as standard equipment.
- Electric Vehicle Range Optimization:Real-time pressure and temperature data from embedded sensors cut rolling resistance losses, extending per-charge driving distance for battery-electric platforms.
- Fleet Outcome-Based Contracts:Commercial vehicle operators now procure tires through uptime-guarantee agreements that require predictive maintenance enabled by continuous tread and pressure monitoring.
Market Restraints
- MEMS Foundry Concentration:Advanced tire-integrated sensor production depends on Taiwanese and South Korean semiconductor fabrication capacity subject to geopolitical disruption.
- ECE R64 Certification Burden:European run-flat performance standards demand parallel testing protocols that extend product development timelines and elevate fixed laboratory costs.
- Conductive Elastomer Input Costs:Specialized carbon-black and graphene compounds for sensor signal transmission face petrochemical feedstock price volatility.
Strategic Opportunities
- India Commercial Fleet Penetration:The country's logistics modernization under PLI scheme incentives creates first-mover advantage for sensor-embedded tire service providers targeting long-haul trucking.
- 5G V2I Protocol Maturation:Vehicle-to-infrastructure connectivity standards enable direct tire-to-traffic-management data streams for autonomous corridor routing.
- EU F-Gas Regulation Tailwinds:Pressure monitoring systems reduce pneumatic maintenance cycles, cutting fluorinated gas consumption in tire inflation equipment and qualifying for compliance credits.
Industry Challenges
- Embedded Systems Talent Scarcity:Cross-functional engineers capable of integrating MEMS design with elastomer mechanics command premium compensation and limited availability.
- Multi-Jurisdiction Certification Complexity:Simultaneous NHTSA, ECE R64, and JIS compatibility testing creates documentation bottlenecks and launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Intelligent Tires Market |
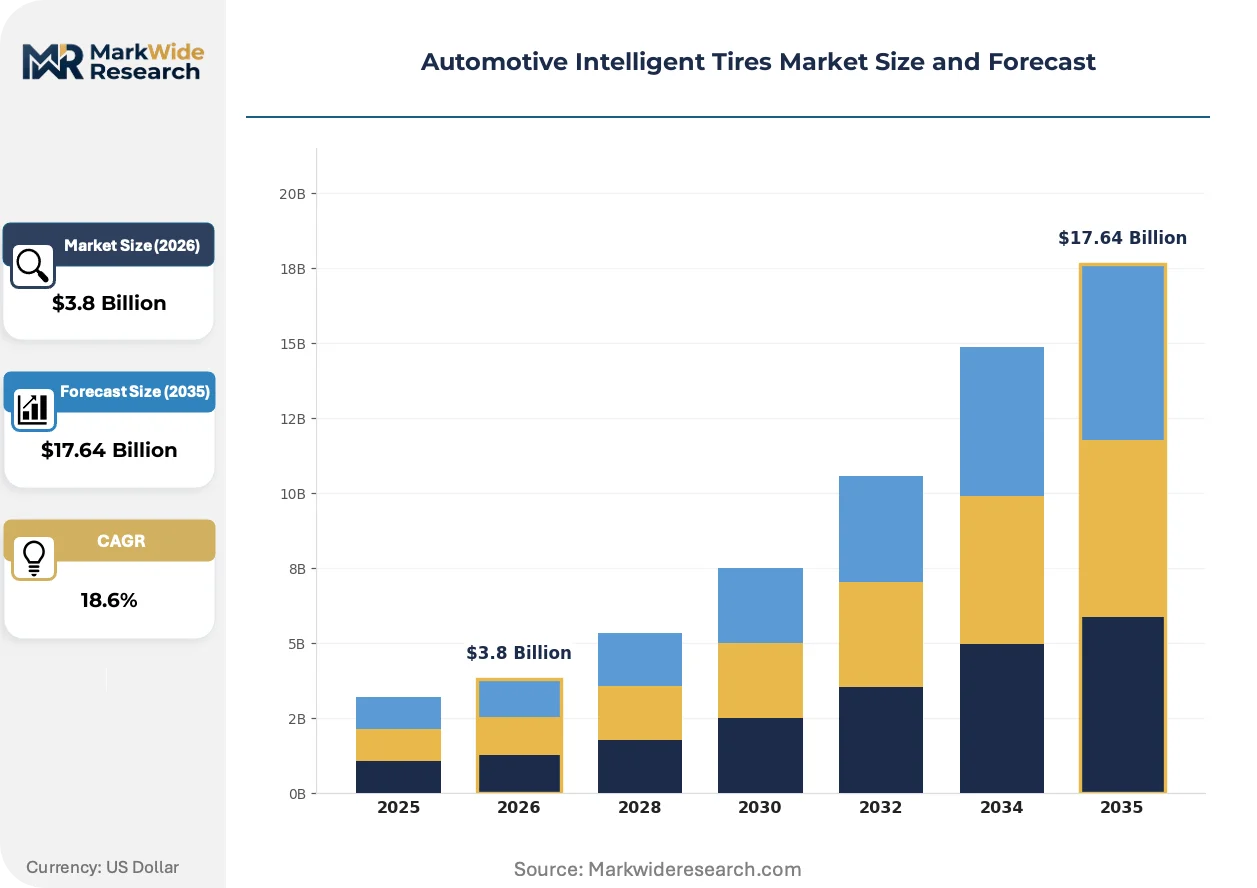
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor-Embedded Tires, Self-Inflating Tires, Run-Flat Tires, Smart Tire Systems Technology: Pressure Monitoring, Temperature Detection, Wear Sensors, Connectivity Solutions End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Application: Passenger Vehicles, Commercial Trucks, SUVs, High-Performance Vehicles |
| Companies Covered | Bridgestone Corporation, Continental AG, Michelin Group, The Goodyear Tire & Rubber Company, Hankook Tire & Technology Co. Ltd., Sumitomo Rubber Industries Ltd., Nokian Tyres Plc, Pirelli & C. S.p.A., Toyo Tire Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Intelligent Tires Market Emerging Trajectories
Radio-frequency identification protocols are replacing Bluetooth Low Energy modules as the dominant tire-to-vehicle communication standard, compressing bill-of-materials costs while extending battery-free operational lifespans.
Self-powered piezoelectric energy harvesters embedded within tire sidewalls are displacing conventional coin-cell batteries as the primary power source for continuous telemetry transmission. Commercial fleet operators in Germany and Japan are mandating these maintenance-free architectures for new procurement cycles. The shift eliminates scheduled battery replacement intervals and is displacing third-party service contracts from tire maintenance channels.
The EU F-Gas Regulation and companion ECE R64 amendments now require tire-pressure monitoring systems to demonstrate electromagnetic compatibility across 5G automotive frequency bands. Manufacturers must redesign antenna geometries and shielding configurations to satisfy updated certification protocols. European OEMs are accelerating supplier qualification timelines to meet 2026 model-year compliance deadlines.
Long-term tire leasing arrangements bundled with predictive analytics subscriptions are eroding traditional unit-sale revenue models in commercial vehicle channels. Fleet managers in the United States and Germany now prioritize per-kilometer cost predictability over upfront capital expenditure minimization. This preference rotation concentrates procurement authority with telematics-integrated service providers rather than independent tire distributors.
Automotive Intelligent Tires Market Segmentation
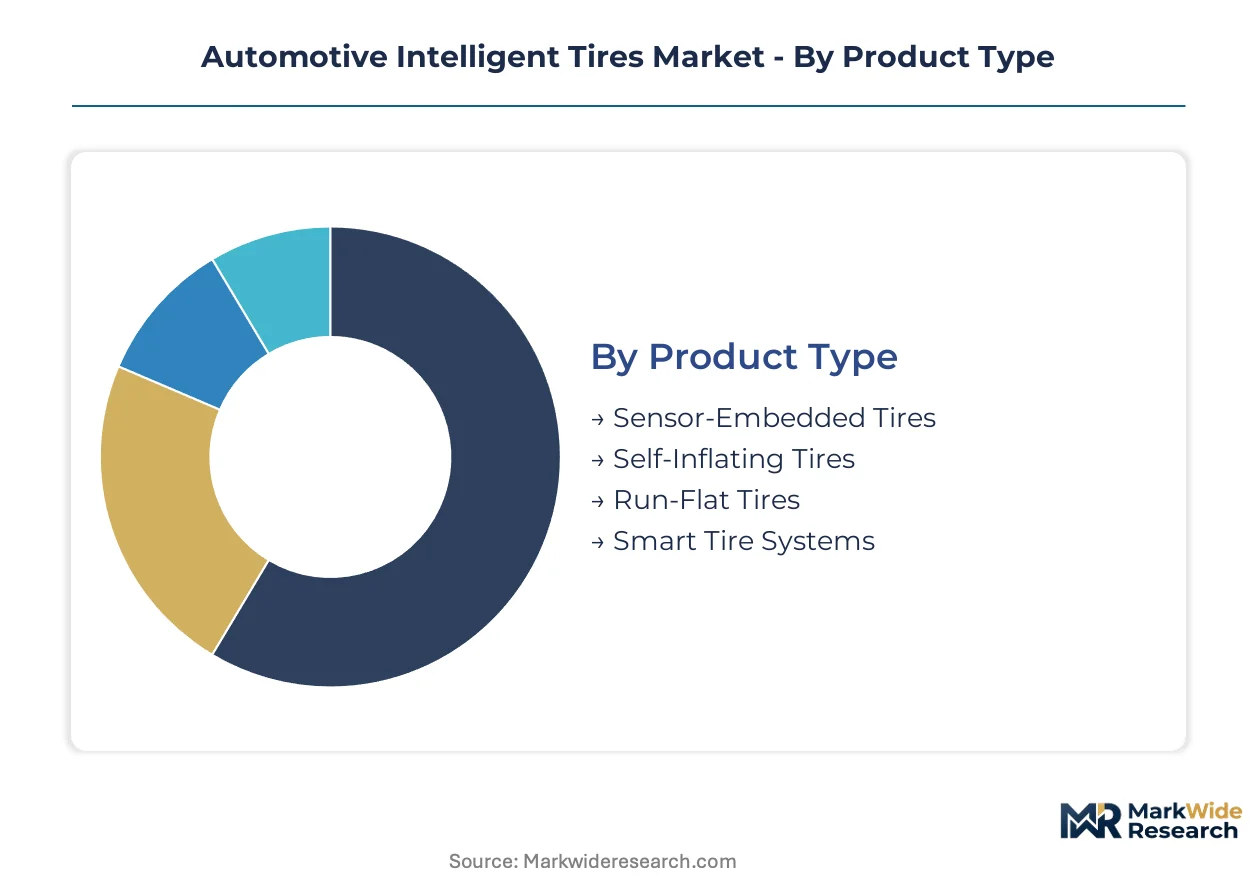
Automotive intelligent tires segment along four distinct axes that determine procurement authority, margin structure, and certification burden. Product type classifications separate hardware-embedded systems from software-defined monitoring platforms. Technology segmentation isolates sensor modalities that face divergent regulatory timelines across NHTSA, ECE R64, and METI jurisdictions.
Product Type:
NHTSA TPMS mandates apply differentially across product categories, with continuous monitoring requirements favoring embedded architectures over retrofit solutions.
- Sensor-Embedded Tires:Microelectromechanical pressure and temperature sensors integrate directly into tire carcass during vulcanization, transmitting data via low-power wireless protocols to vehicle control units. OEM procurement in Germany and Japan concentrates here as electric vehicle manufacturers mandate real-time telemetry for range optimization algorithms. NHTSA compliance deadlines accelerate fleet retrofit cycles in the United States.
- Self-Inflating Tires:Internal pumping mechanisms maintain optimal pressure without external inflation equipment, reducing pneumatic maintenance cycles and fluorinated gas consumption. Demand clusters with commercial fleet operators in India and Germany seeking uptime guarantees under outcome-based service contracts. EU F-Gas Regulation credits create procurement preference for maintenance-free architectures.
- Run-Flat Tires:Reinforced sidewall constructions enable limited-distance operation after pressure loss, governed by ECE R64 performance standards.
- Smart Tire Systems:Integrated hardware-software platforms combining multiple sensor modalities with cloud analytics subscriptions.
Sensor-embedded tires handle the majority of throughput; self-inflating tires are climbing the fastest on share as fleet operators eliminate scheduled maintenance intervals.
Technology:
Technology selection determines foundry access requirements and electromagnetic compatibility certification scope under evolving 5G automotive frequency standards.
- Pressure Monitoring:Capacitive and piezoresistive MEMS transducers measure inflation status with ±1 PSI accuracy, forming the baseline for NHTSA-mandated TPMS integration. Volume concentrates in passenger vehicle OEM channels where regulatory compliance drives standard equipment fitment.
- Temperature Detection:Thermocouple and infrared sensor arrays track thermal buildup during high-speed operation, critical for electric vehicle battery thermal management integration.
- Wear Sensors:Conductive elastomer compounds with embedded electrodes measure tread depth via resistance changes, enabling predictive replacement scheduling.
- Connectivity Solutions:Radio-frequency transceivers and 5G vehicle-to-infrastructure modules enable direct tire-to-traffic-management data streaming.
Pressure monitoring dominates installed base; connectivity solutions show the steepest expansion trajectory as autonomous vehicle protocols mature.
End User:
Procurement authority patterns split between capital-expenditure-minimizing vehicle assemblers and total-cost-of-ownership-optimizing fleet operators.
- OEMs:Original equipment manufacturers specify intelligent tire architectures during platform development, locking in multi-year supply agreements with sensor-integrated designs. German and Japanese automotive headquarters anchor design-in activity for global model ranges.
- Fleet Operators:Commercial vehicle managers procure through per-kilometer leasing arrangements with predictive analytics subscriptions, prioritizing uptime over upfront cost. Indian long-haul trucking modernization under PLI scheme incentives creates first-mover opportunity.
- Aftermarket Providers:Independent distributors and service chains handle retrofit installations for in-service vehicles.
- Vehicle Assemblers:Contract manufacturers integrate intelligent tires during final assembly under OEM direction.
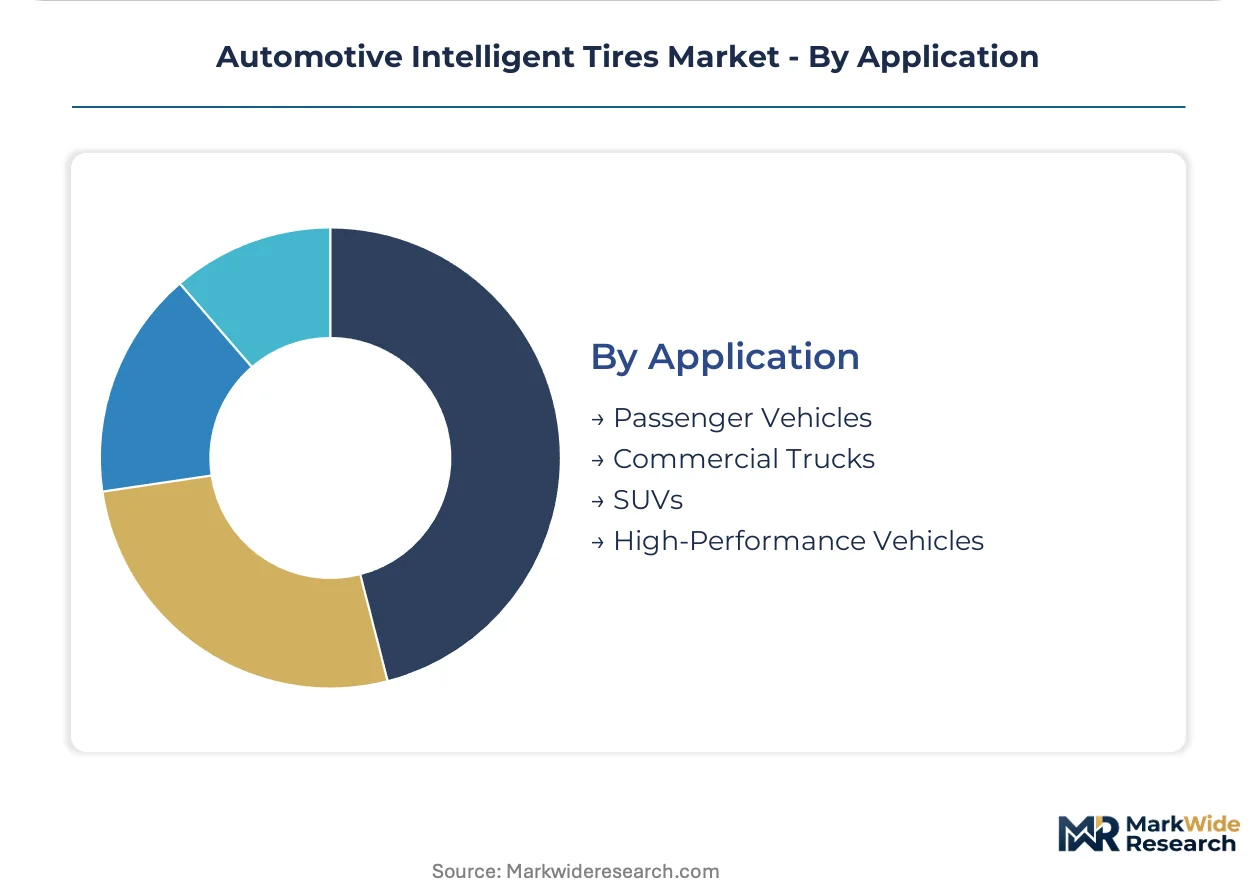
Fleet operators command the highest margins; OEMs represent the largest absolute volume channel.
Application:
Application segmentation aligns with load-bearing requirements and duty-cycle intensity that determine sensor durability specifications.
- Commercial Trucks:Heavy-duty cycles with sustained high loads demand reinforced sensor packaging and extended temperature operating ranges. Procurement concentrates with German and US fleet operators under outcome-based uptime contracts requiring predictive maintenance capabilities.
- Passenger Vehicles:Light-duty applications prioritize cost-optimized TPMS compliance with minimal sensor complexity. NHTSA mandates drive standard fitment across all US light vehicle platforms.
- SUVs:Mixed on-off road duty cycles require enhanced shock resistance and wider temperature tolerance.
- High-Performance Vehicles:Extreme speed and cornering loads necessitate high-frequency data sampling and specialized thermal management.
Commercial trucks absorb the majority of sensor-embedded tire value; high-performance vehicles are gaining share fastest as telemetry integration becomes a differentiation feature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan consume intelligent tires primarily through OEM integration for electric vehicle range optimization, while the United States and India exhibit stronger fleet-operator procurement for commercial uptime guarantees.
United States
NHTSA TPMS mandates drive standard fitment across all light vehicle platforms, compelling automakers to embed sensor-integrated tires during assembly. Fleet operators in Texas and the Midwest negotiate per-kilometer leasing contracts that prioritize predictive maintenance capabilities over upfront capital expenditure. The Southeast automotive corridor, anchored by Tennessee and South Carolina assembly plants, concentrates design-in activity for domestic OEM supply chains.
Germany
Continental AG and BMW Group headquarters in Munich anchor European innovation clusters for tire-integrated chip fabrication. The EU F-Gas Regulation creates procurement preference for maintenance-free architectures that reduce fluorinated gas consumption in inflation equipment. Baden-Württemberg's automotive supplier density supports dedicated cleanroom facilities for MEMS sensor production serving premium OEM channels.
Japan
METI enforces JIS compatibility standards for connected mobility platforms, accelerating supplier qualification timelines for tire-to-vehicle communication protocols. Toyota and Honda headquarters in Aichi Prefecture drive integration of self-powered piezoelectric harvesters to eliminate battery replacement intervals. The Kanto region's semiconductor ecosystem provides captive foundry access for domestic tire manufacturers.
India
Commercial fleet modernization under the PLI scheme incentivizes sensor-embedded tire adoption for long-haul trucking corridors connecting Delhi-Mumbai and Chennai-Bengaluru. The country's logistics sector prioritizes uptime guarantees through outcome-based service contracts rather than traditional unit purchases. Gujarat and Maharashtra industrial zones concentrate aftermarket installation capacity for retrofit TPMS compliance.
China
Domestic electric vehicle manufacturers mandate continuous telemetry integration for battery thermal management and range optimization algorithms. MIIT standards for vehicle-to-infrastructure connectivity accelerate 5G-enabled tire data streaming for autonomous corridor development. The Yangtze River Delta automotive cluster, centered on Shanghai and Jiangsu, hosts parallel certification laboratories for NHTSA and ECE R64 compliance testing.
Automotive Intelligent Tires Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor partnerships and proprietary radio-frequency protocols defining competitive moats. Tire manufacturers with dedicated foundry access or backward integration into MEMS fabrication command supply security advantages over fabless competitors. Two dominant strategic archetypes emerge: vertically integrated compounders controlling sensor-to-elastomer integration, and connectivity-focused specialists licensing protocol stacks. Capacity expansion in European cleanroom facilities and strategic partnerships for 5G module integration represent the primary competitive moves reshaping positioning.
Within the integrated tier, Bridgestone Corporation and Continental AG exemplify manufacturers securing captive semiconductor supply chains through dedicated foundry partnerships or in-house fabrication investments. Michelin Group occupies a distinct position emphasizing proprietary communication protocols that reduce dependency on third-party connectivity modules. These three companies anchor the competitive structure, with their strategic choices around sensor production versus fabless collaboration setting patterns that specialists and regional players must navigate.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Continental AG |
| Michelin Group |
| The Goodyear Tire & Rubber Company |
| Hankook Tire & Technology Co. Ltd. |
| Sumitomo Rubber Industries Ltd. |
| Nokian Tyres Plc |
| Pirelli & C. S.p.A. |
| Toyo Tire Corporation |
| Others |
Supply Flow & Price Mechanics
Conductive elastomer compounds replacing conventional carbon-black formulations are simultaneously shifting procurement geography toward petrochemical hubs and compressing margin structures for sensor-embedded tire manufacturers. This substitution dynamic concentrates price-setting power with compound specialists while forcing tire OEMs to absorb feedstock volatility through long-term offtake structures.
Pricing Analysis
Long-term offtake agreements dominate procurement between tier-one tire manufacturers and semiconductor foundries, locking in volume commitments for MEMS sensors across multi-year horizons. Price differentiation stems from certification tier—ECE R64 compliance commands premium positioning—and volume scale, with fleet operators extracting discounts through consolidated procurement. Pricing pressure intensifies in the aftermarket channel as retrofit TPMS providers compete on installation speed. Fleet operators exhibit lowest price sensitivity due to outcome-based contract structures, while independent vehicle owners prioritize upfront cost minimization.
Supply Chain Analysis
Taiwanese and South Korean semiconductor fabrication capacity constitutes the critical chokepoint for tire-integrated MEMS sensor supply, with geopolitical disruption risk elevating inventory carrying costs across the value chain. Raw material dependencies center on conductive carbon-black, graphene compounds, and low-power wireless transceiver modules. Single-source vulnerability concentrates in advanced MEMS foundry access, where captive partnerships differentiate integrated manufacturers from fabless competitors. Distribution runs through OEM direct supply agreements for new vehicle fitment, with aftermarket channels serving retrofit demand via regional tire service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive intelligent tires occupy an early-cycle expansion phase as NHTSA mandates and EU F-Gas Regulation compliance deadlines accelerate embedded sensor adoption beyond early-adopter fleet operators into mainstream OEM specification.
For Market Incumbents: Compound captive foundry partnerships through dedicated cleanroom investments in Germany and Japan to secure MEMS supply against geopolitical disruption. Deepen backward integration into conductive elastomer production to buffer petrochemical feedstock volatility. Prioritize ECE R64 certification maintenance as European run-flat standards tighten electromagnetic compatibility requirements. For New Entrants and Emerging Players: JIS fast-track certification pathways in Japan offer accelerated market access for connectivity-protocol specialists seeking OEM qualification. White-space opportunity concentrates in India's PLI-backed commercial fleet modernization, where outcome-based service contracts remain underpenetrated by established players. Pursue telematics-integrated leasing arrangements rather than unit-sales positioning to align with fleet operator procurement preferences. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated compounders with captive sensor-to-elastomer production capabilities and established foundry relationships. Long-term viability favors manufacturers controlling both MEMS fabrication and proprietary radio-frequency protocol stacks. Monitor 5G vehicle-to-infrastructure protocol maturation as the inflection signal for connectivity-solution valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Partnership | Secures semiconductor supply continuity against Taiwan Strait disruption risk. |
| ECE R64 Certification Investment | Unlocks European OEM procurement for run-flat intelligent tire platforms. |
| 5G V2I Module Integration | Enables direct tire-to-traffic-management data streaming for autonomous corridors. |
| Piezoelectric Harvester Deployment | Eliminates battery replacement intervals under EU F-Gas maintenance-free mandates. |
| India Fleet Service Expansion | Captures PLI-scheme logistics modernization in Delhi-Mumbai trucking corridors. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers, and aftermarket service technicians converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against NHTSA regulatory filings, ECE R64 certification databases, vehicle production records, and customs trade data for conductive elastomer inputs. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product type architecture, sensor modality technology, end-user procurement authority, and application duty-cycle intensity. CAGRs were derived through regression analysis of historical adoption curves adjusted for regulatory mandate timing and electric vehicle platform rollout schedules. Forecast inputs incorporated MEMS foundry capacity expansion announcements and 5G automotive protocol standardization milestones.
Underlying assumptions cover regulatory enforcement continuity, semiconductor supply normalization, and fleet operator contract-structure preference stability, with deviation risk concentrated in geopolitical disruption to Taiwanese foundry access and petrochemical feedstock price spikes. Practitioners should keep alternative scenarios live as MEMS fabrication geographic diversification and autonomous vehicle deployment timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Passenger Tire Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Tire Cord Market