
 Commercial Vehicle Forged Aluminum Alloy Wheels Market | 2026-2036
Commercial Vehicle Forged Aluminum Alloy Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Forged Aluminum Alloy Wheels Market Insights
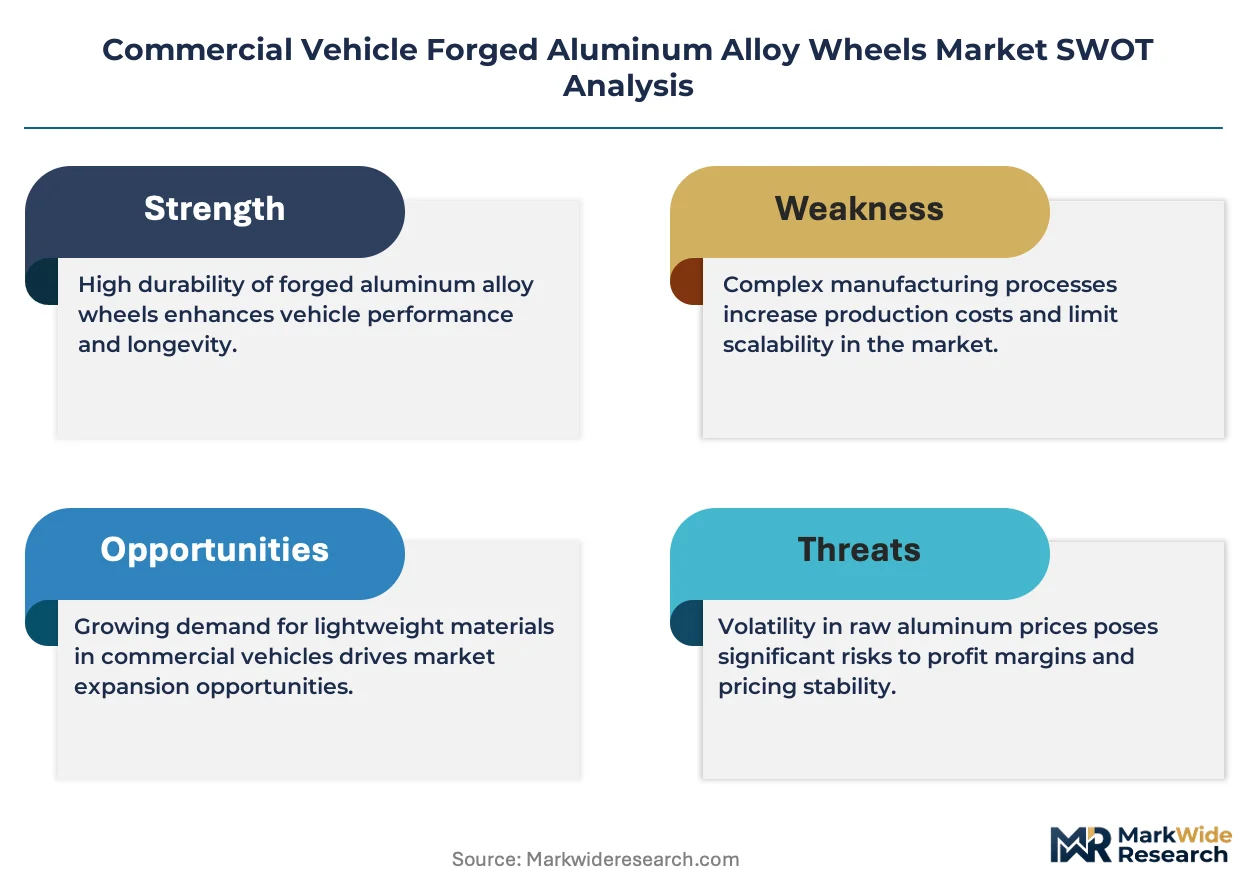
The split between premium forged wheels and commodity cast alternatives is realigning procurement patterns across commercial vehicle fleets. MAXION Wheels leverages its vertical manufacturing footprint to sustain cost discipline at scale. Lizhong Wheel Group anchors its position through dominance in Asia-Pacific production capacity. Howmet Aerospace differentiates via specialization in aerospace-grade alloy formulations that transfer to heavy-duty commercial specifications.
Commercial vehicle forged aluminum alloy wheels are rotationally symmetric components produced from heat-treatable aluminum alloys, typically 6061-T6 or comparable grades, through closed-die forging processes that yield grain structures with tensile strengths exceeding 310 MPa and fatigue resistance critical for sustained highway loading cycles. Their primary purpose is to reduce unsprung mass, thereby improving fuel economy, brake cooling, and tire wear profiles in Class 4-8 trucks and buses. Lightweight wheels command the strongest margin pools as fleet operators prioritize total cost of ownership reductions, while heavy-duty wheels represent the largest volume category driven by replacement cycles in long-haul applications. Advanced forging technology is displacing conventional forging in premium segments as manufacturers pursue thinner wall sections without sacrificing structural integrity.
The EPA, NHTSA, and ISO 9001 quality frameworks collectively shape product standards, testing protocols, and market access requirements for forged aluminum wheels in the United States, with fuel economy and greenhouse gas regulations directly translating to weight-reduction specifications in OEM supply agreements. The Department of Transportation's Federal Motor Vehicle Safety Standards mandate impact and fatigue testing that favor forged construction over cast alternatives for severe-service applications. Stakeholders must monitor evolving alloy recycling mandates and carbon border adjustments that will increasingly determine supplier qualification criteria.
Market Dynamics
Fleet procurement officers now weight wheel specifications against EPA Phase 3 greenhouse gas standards that mandate progressive weight reduction in Class 8 tractors. This regulatory compression is forcing specification upgrades across replacement cycles faster than historical norms.
Growth Catalysts
- EPA Phase 3 Standards:The regulation mandates 2% annual efficiency improvements in heavy-duty trucks, translating directly to unsprung mass reduction targets that favor forged aluminum over steel wheels in OEM specifications.
- 6061-T6 Alloy Optimization:Heat treatment protocols developed for aerospace applications now transfer to commercial wheel production, yielding fatigue life improvements that extend replacement intervals for long-haul operators.
- California Air Resources Board Mandates:CARB's Advanced Clean Trucks rule accelerates zero-emission vehicle deployment where battery payload penalties make lightweight wheels essential for maintaining cargo capacity.
Market Restraints
- Primary Aluminum Price Volatility:LME aluminum pricing swings directly compress forging house margins, with energy-intensive smelting costs in China and Russia creating input cost instability for North American producers.
- Forging Press Capacity Concentration:Large-diameter closed-die forging capacity clusters in Germany, Japan, and the United States, creating supply bottlenecks when demand surges exceed installed equipment utilization.
- Cast Wheel Substitution in Vocational Segments:Construction and refuse applications tolerate higher unsprung mass, allowing lower-cost cast aluminum or steel wheels to capture fleet orders where fuel efficiency carries less weight in total cost of ownership calculations.
Strategic Opportunities
- Mexico Manufacturing Expansion:Nearshoring of Class 4-7 truck assembly creates demand for forged wheels at tariff-advantaged production points serving United States distribution networks.
- Closed-Loop Alloy Recycling:Scrap recovery systems integrated into forging operations can satisfy emerging carbon border adjustment requirements while reducing virgin aluminum dependency.
- Telematics-Integrated Wheel Sensors:Forged wheel hubs incorporating tire pressure and temperature monitoring create service revenue streams beyond commodity wheel sales to fleet maintenance departments.
Industry Challenges
- Forging Die Engineering Talent Scarcity:Specialized CAD/CAM and thermal modeling expertise for large-diameter wheel dies concentrates among retiring specialists, constraining new product development velocity.
- FMVSS 120 Certification Timelines:Federal Motor Vehicle Safety Standard testing protocols require 18-24 month validation cycles for new wheel designs, delaying market entry for upgraded specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Forged Aluminum Alloy Wheels Market |
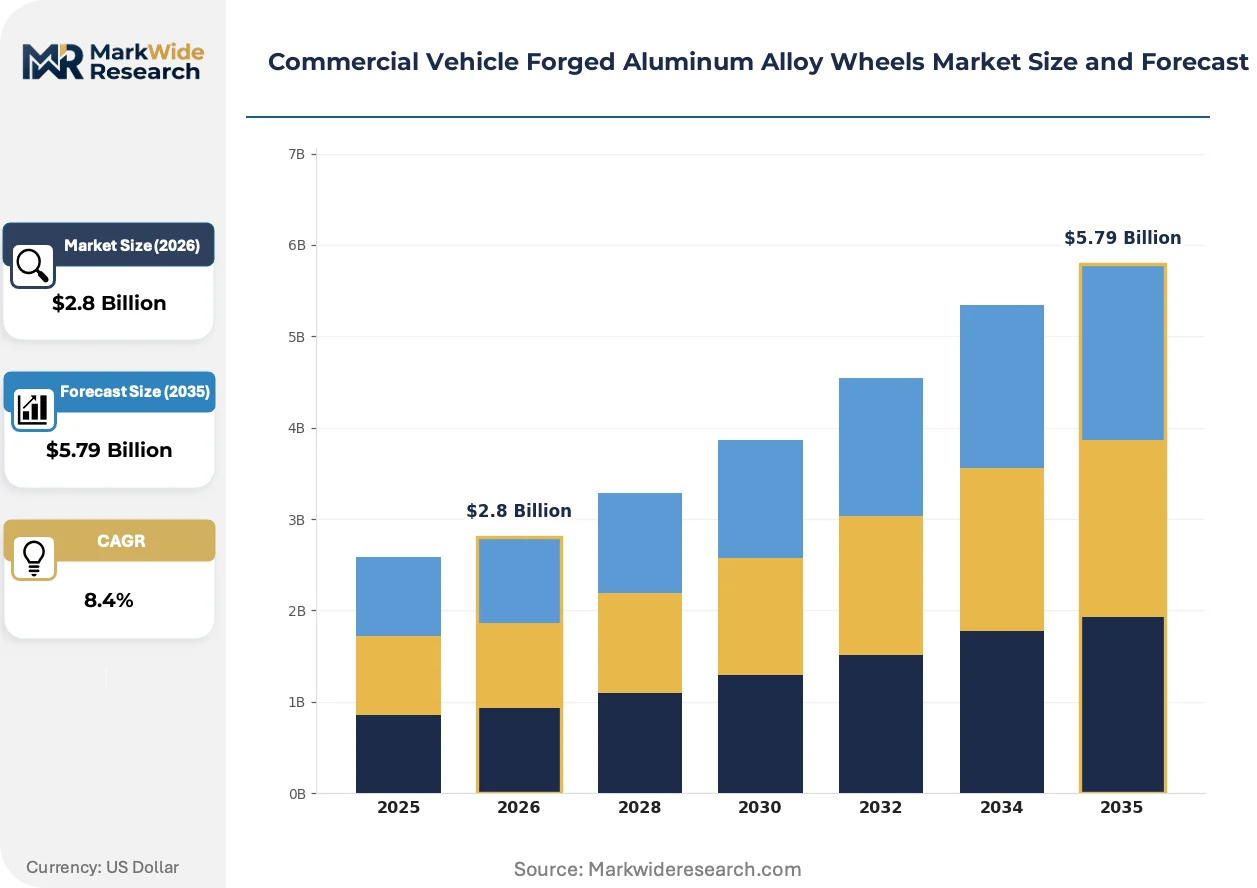
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight Wheels, Heavy-Duty Wheels, High-Performance Wheels, Standard Wheels End User: Fleet Operators, OEMs, Aftermarket Providers, Logistics Companies Manufacturing Stage: Raw Material Processing, Forging, Machining, Finishing Technology: Gravity Casting, Low-Pressure Die Casting, Conventional Forging, Advanced Forging |
| Companies Covered | MAXION Wheels, Lizhong Wheel Group, CITIC Dicastal Co. Ltd, Howmet Aerospace Inc., Topy Industries, Alcoa Wheels, Wanfeng Auto, Superior Industries International Inc., RONAL GROUP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Forged Aluminum Alloy Wheels Market Trends and Innovations
Manufacturing technology and regulatory measurement protocols are compressing development cycles while expanding performance verification requirements. Three developments define the current innovation frontier.
Isothermal forging is converging with real-time thermal monitoring to enable thinner wall sections without sacrificing structural margins. Tier 1 suppliers serving Detroit-based OEMs are adopting these systems for 2027 model year wheel programs. The technology is converging with automated inspection to reduce material overdesign and scrap rates in high-volume production.
EPA's Greenhouse Gas Emissions Model (GEM) compliance simulation now requires wheel mass as an input variable for certifying tractor-trailer combinations. This regulatory integration forces wheel suppliers to provide verified weight documentation traceable to specific forging lots. Long-haul fleet specifications are tightening tolerance bands accordingly, with some operators mandating certificate-of-analysis delivery with each wheel shipment.
Spec-buy behavior among large fleet operators now separates wheel procurement from tire purchasing, reversing decades of bundled supplier relationships. Independent wheel distributors are capturing direct fleet contracts previously held by tire-and-wheel package vendors. This unbundling is most visible in United States less-than-truckload segments where maintenance standardization across multiple terminals requires direct wheel specification control.
Commercial Vehicle Forged Aluminum Alloy Wheels Market Segmentation
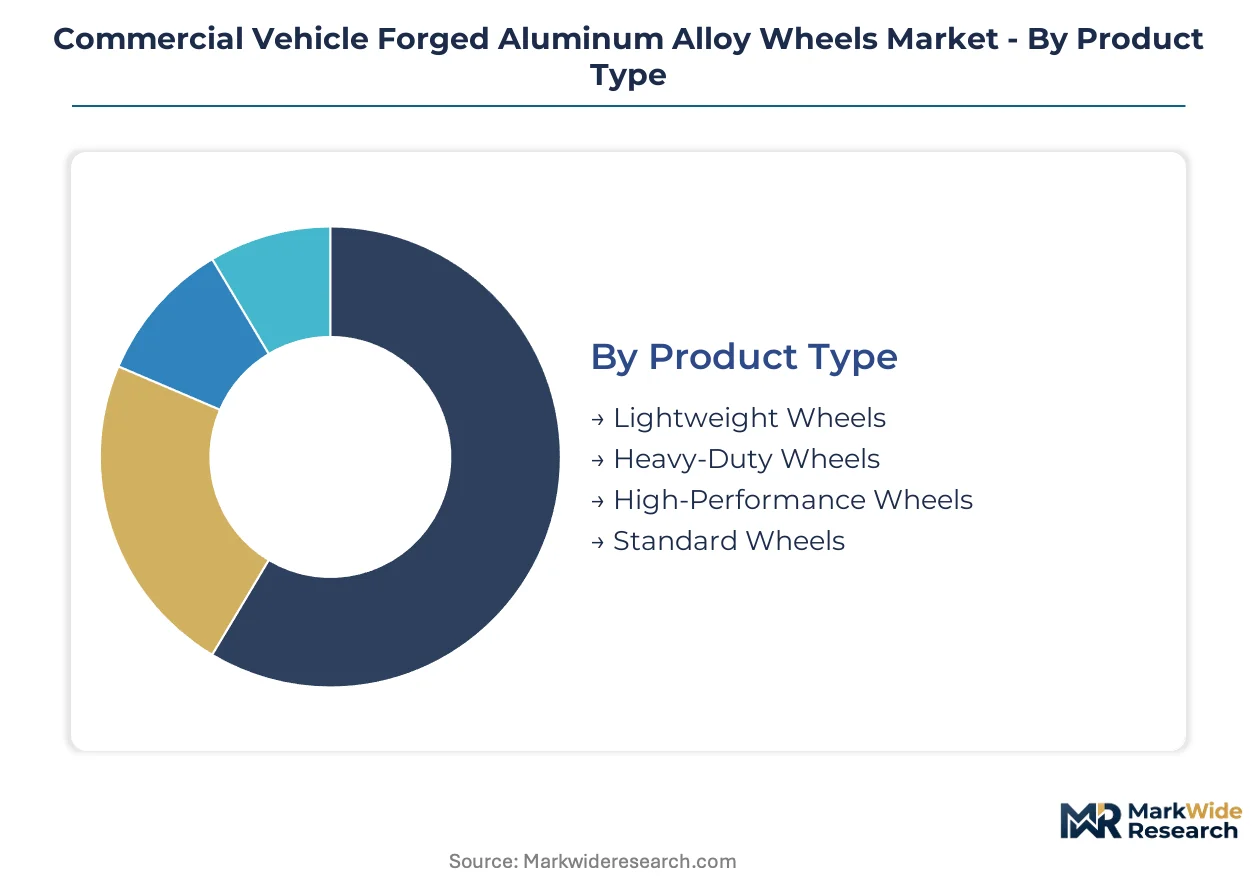
Wheel procurement in commercial vehicles fractures across weight specifications, buyer types, and manufacturing sophistication. Fleet operators and OEMs apply divergent criteria when selecting forged aluminum wheels, creating distinct margin pools and certification requirements within each segment cluster.
Product Type:
Fleet procurement officers prioritize unsprung mass reduction against total cost of ownership benchmarks, while vocational operators accept weight penalties for durability.
- Lightweight Wheels:These wheels utilize 6061-T6 alloy with optimized wall thickness below 12mm to maximize fuel efficiency gains. Long-haul fleets operating Class 8 tractors across interstate corridors specify these wheels to comply with EPA Phase 3 greenhouse gas standards while preserving cargo capacity.
- Heavy-Duty Wheels:Thicker forged sections withstand severe-service loading cycles in refuse, construction, and mining applications. Replacement demand concentrates in United States vocational fleets where duty cycles exceed 100,000 miles annually and downtime costs override fuel economy considerations.
- High-Performance Wheels:Aerospace-grade alloy formulations deliver tensile strength above 350 MPa for extreme load ratings.
- Standard Wheels:Conventional 6061-T6 specifications serve price-sensitive regional delivery operations.
Heavy-Duty Wheels lead volumes today; Lightweight Wheels is gaining share fastest.
End User:
Contract structures and specification control differentiate procurement behavior across buyer categories.
- Fleet Operators:Large less-than-truckload carriers now unbundle wheel procurement from tire purchasing, mandating direct supplier relationships for maintenance standardization. Direct fleet contracts specify certificate-of-analysis documentation traceable to forging lots for EPA GEM compliance verification.
- OEMs:Detroit-based truck manufacturers integrate forged wheels into platform engineering from concept phase, locking in multi-year supply agreements. OEM specifications drive technology adoption as assemblers certify wheel mass inputs for tractor-trailer greenhouse gas modeling.
- Aftermarket Providers:Independent distributors capture replacement cycle demand through inventory positioning at major freight corridors.
- Logistics Companies:Third-party operators prioritize interchangeability across leased equipment pools.
OEMs dominate specification-setting; Fleet Operators is expanding procurement autonomy most rapidly.
Manufacturing Stage:
Value capture concentrates at process steps where capital intensity creates entry barriers.
- Forging:Closed-die forging with 10,000-ton press capacity represents the critical constraint in supply chains. Large-diameter wheel forging clusters in Germany, Japan, and the United States, creating bottlenecks when demand surges exceed installed equipment utilization.
- Machining:CNC finishing operations achieve dimensional tolerances within 0.1mm for hub mounting surfaces. Precision machining capacity near Detroit serves OEM just-in-sequence requirements with 48-hour turnaround windows.
- Raw Material Processing:Virgin aluminum ingot and scrap sorting precede forging operations.
- Finishing:Anodizing and coating applications provide cosmetic and corrosion protection.
Forging commands the highest margin capture; Machining is climbing the fastest as tolerance requirements tighten.
Technology:
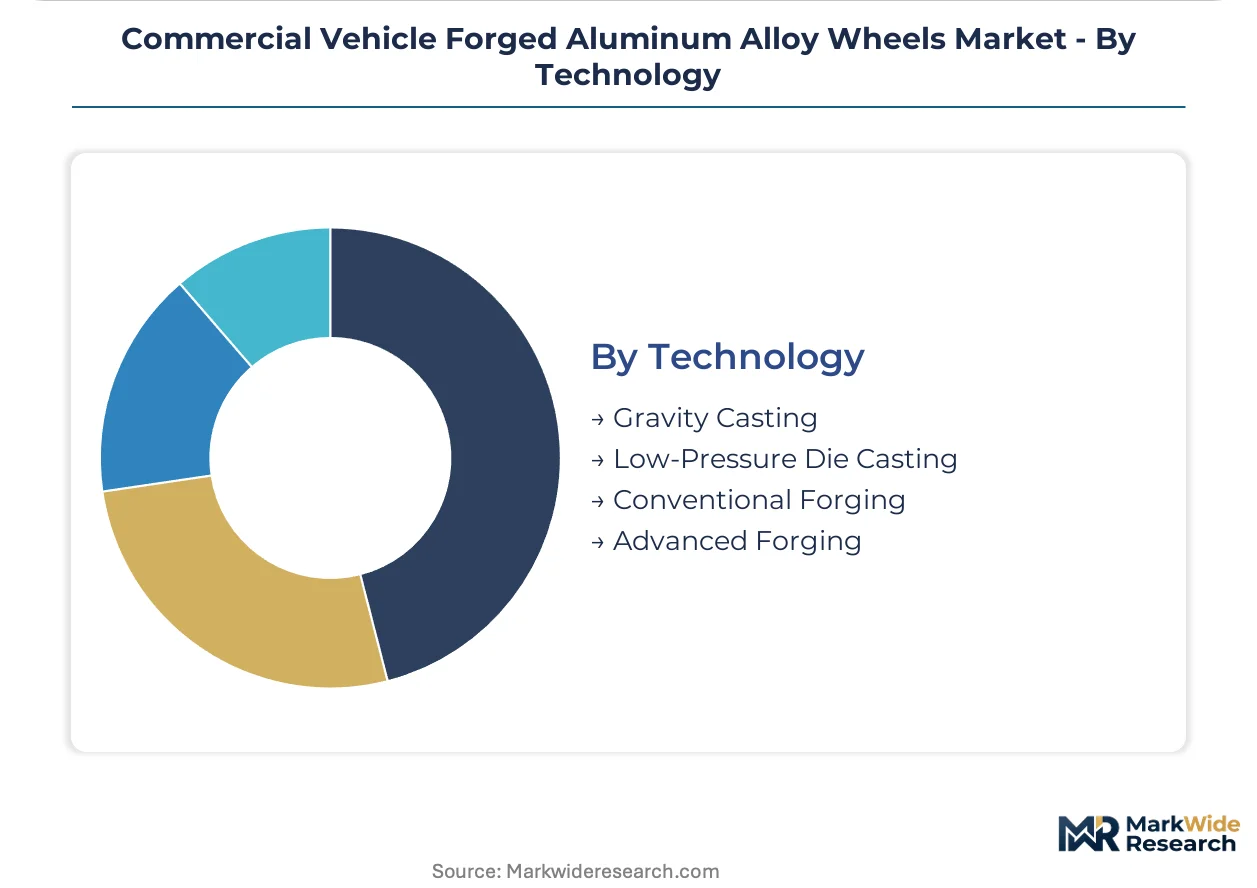
Process selection determines structural integrity, production rate, and capital recovery profiles.
- Advanced Forging:Isothermal forging converges with real-time thermal monitoring to enable thinner wall sections without sacrificing structural margins. Tier 1 suppliers serving United States-based OEMs deploy these systems for upcoming model year wheel programs.
- Conventional Forging:Standard closed-die processes with mechanical presses serve high-volume production of established wheel designs. Conventional forging retains cost advantages for replacement market specifications where development amortization is complete.
- Low-Pressure Die Casting:Near-net-shape casting competes in lighter-duty commercial segments.
- Gravity Casting:Basic casting technology serves price-driven aftermarket applications.
Conventional Forging leads installed capacity; Advanced Forging shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forging die engineers and metallurgical specialists cluster in industrial corridors where heavy-press capacity and OEM engineering offices intersect. Talent density in Germany, the United States, Japan, China, and Mexico shapes where specification-setting occurs and where new wheel programs launch first.
United States
Long-haul freight corridors through Texas, Ohio, and Michigan generate replacement demand exceeding 2 million wheels annually. EPA Phase 3 greenhouse gas standards mandate unsprung mass reductions that OEMs achieve through forged aluminum specifications. Detroit-area machining clusters serve just-in-sequence assembly requirements with 48-hour turnaround windows.
Germany
Commercial vehicle manufacturers in Baden-Württemberg and Bavaria specify forged wheels for export tractors meeting EU CO2 standards for heavy-duty vehicles. KBA certification protocols require fatigue testing documentation that favors established forging houses over new entrants. Isothermal forging equipment concentrates in the Stuttgart industrial region for premium wheel programs.
China
Domestic heavy-truck production in Shandong and Hubei provinces consumes forged wheels for fleet upgrades meeting MIIT fuel consumption limits. GB standards for commercial vehicle wheels mandate impact resistance testing that aligns with forged construction advantages. Yangtze River Delta forging clusters supply both domestic OEMs and export markets.
Japan
Metropolitan Tokyo and Nagoya engineering centers develop lightweight wheel specifications for hybrid and electric commercial platforms. METI carbon neutrality roadmaps pressure fleet operators toward mass reduction technologies. Chubu region forging houses specialize in thin-wall designs for premium export segments.
Mexico
Nearshored Class 4-7 truck assembly in Nuevo León and Mexico City metro areas creates tariff-advantaged demand for forged wheels serving United States distribution. IMMEX program incentives attract wheel forging investments to border states. Querétaro machining clusters finish wheels for just-in-time delivery to Texas and California freight corridors.
Commercial Vehicle Forged Aluminum Alloy Wheels Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier structure. Integrated forging-to-finishing operations command specification-setting influence with Detroit-based OEMs, while specialized machining houses capture aftermarket replacement cycles. Three archetypes dominate: vertically integrated wheel manufacturers with captive forging capacity; precision machining specialists serving multiple forging sources; and aluminum alloy developers transferring aerospace formulations to commercial specifications. Capacity expansion and strategic partnerships constitute the primary competitive vectors as suppliers position for EPA-mandated specification upgrades.
Among vertically integrated manufacturers, MAXION Wheels and Lizhong Wheel Group exemplify scale-driven archetypes with multi-continent production footprints. Howmet Aerospace Inc. occupies a specialization position derived from aerospace-grade alloy expertise. These three anchors illustrate how competitive positioning fragments between volume-scale operators and materials-science specialists, with each archetype capturing distinct margin pools in OEM versus aftermarket channels.
| Leading Market Players |
|---|
| MAXION Wheels |
| Lizhong Wheel Group |
| CITIC Dicastal Co. Ltd |
| Howmet Aerospace Inc. |
| Topy Industries |
| Alcoa Wheels |
| Wanfeng Auto |
| Superior Industries International Inc. |
| RONAL GROUP |
| Others |
Pricing and Supply Chain Analysis
LME aluminum ingot pricing swings transmit directly through forging house cost structures into OEM contract tiers and aftermarket replacement rates, with energy-intensive smelting costs in China and Russia creating input instability that North American producers must hedge through long-term offtake agreements or backward integration into scrap recovery systems.
Pricing Analysis
Bundled tire-and-wheel packages are fragmenting into unbundled wheel procurement as fleet operators seek direct specification control. Three-tier pricing structure across premium forged, standard forged, and cast-aluminum alternatives separates OEM just-in-sequence contracts from aftermarket replacement channels. Pricing pressure stems from primary aluminum volatility and cast wheel substitution in vocational segments where fuel efficiency carries less weight in total cost calculations. Regional delivery fleets exhibit highest price sensitivity; long-haul Class 8 operators prioritize performance over unit cost.
Supply Chain Analysis
Domestic-content requirements under Buy America provisions and EPA certification traceability rules are reshaping sourcing patterns toward North American forging capacity. Large-diameter closed-die forging clusters in Germany, Japan, and the United States anchor supply, with Mexico emerging as tariff-advantaged finishing capacity. Virgin 6061-T6 alloy billet, aerospace-grade scrap streams, and specialized forging dies constitute critical input dependencies. Single-source vulnerability concentrates in 10,000-ton press capacity. Distribution runs through OEM just-in-sequence channels and independent aftermarket distributors serving freight corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as EPA Phase 3 greenhouse gas standards hardwire forged aluminum specifications into Class 8 tractor platforms through regulatory compliance rather than discretionary upgrade cycles.
For Market Incumbents: Lock in multi-year supply agreements with Detroit-based OEMs before 2027 model year platform freezes solidify procurement relationships. Secure captive forging die engineering talent through acquisition or partnership before retiring specialists exit the workforce. Cast wheel substitution in vocational segments and emerging Mexican manufacturing competitors threaten margin pools in replacement channels. For New Entrants and Emerging Players: EPA Phase 3 in the United States opens a window for specification-compliant lightweight wheel suppliers to penetrate direct fleet contracts previously held by bundled tire-and-wheel vendors. Target less-than-truckload carriers with maintenance standardization needs across multiple terminals. Pursue closed-loop alloy recycling capabilities to satisfy emerging carbon border adjustment requirements and differentiate against virgin-aluminum-dependent incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where forging press capacity scarcity meets surging demand from nearshored truck assembly in Mexico. Five-to-ten year viability favors vertically integrated manufacturers with captive 10,000-ton press capacity and established OEM certification relationships. Precision machining specialists serving multiple forging sources represent attractive acquisition targets. Watch EPA enforcement timelines and LME aluminum price trajectories as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Recovery | Closed-loop alloy recycling satisfies carbon border adjustments while reducing virgin aluminum dependency. |
| Forging Die Engineering Talent Acquisition | CAD/CAM and thermal modeling expertise concentrates among retiring specialists, constraining new product velocity. |
| Mexico Manufacturing Footprint Expansion | IMMEX program incentives attract forging investments to border states serving Texas and California freight corridors. |
| Telematics-Integrated Wheel Sensor Development | Forged wheel hubs incorporating tire pressure monitoring create service revenue streams beyond commodity sales. |
| Isothermal Forging Technology Deployment | Real-time thermal monitoring enables thinner wall sections without sacrificing structural margins for EPA compliance. |
Research Methodology
Direct dialogue with fleet procurement officers, OEM platform engineers, forging house operations managers, and aftermarket distribution heads grounded qualitative insights in operational reality. Secondary validation drew from EPA regulatory filings, NHTSA FMVSS 120 certification databases, LME aluminum price series, and commercial vehicle production registries. Bottom-up and top-down triangulation cross-checked volume estimates against installed forging press capacity utilization and replacement cycle modeling.
Bottom-up modeling built from segment-level volume and pricing assumptions across product type, end user, and manufacturing stage dimensions. Top-down constraints applied macroeconomic freight demand indicators and regulatory compliance timelines across the projection horizon. CAGRs derived from curve-fitting historical replacement patterns against EPA-mandated specification upgrade schedules. Forecast inputs incorporated Class 8 tractor build rates, long-haul mileage accumulation curves, and alloy recycling infrastructure development trajectories.
Revisions become necessary when EPA enforcement intensity shifts, LME aluminum price volatility exceeds historical bands, or forging press capacity expansion outpaces demand surges. Forecasts reflect documented assumptions about regulatory compliance timelines and technology adoption rates. A small set of named triggers—CARB Advanced Clean Trucks rule expansion, carbon border adjustment implementation, and isothermal forging equipment deployment velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
GCC Tire Market