
 Zeropressure Tires Market | 2026-2036
Zeropressure Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Zeropressure Tires Market Analytics
Tire lifecycle management subscriptions and predictive maintenance software layers is rebalancing how fleet operators procure zeropressure systems, shifting capital expenditure into operational contracts. Michelin leverages its connected tire services to anchor long-term fleet relationships. Bridgestone Corporation competes through its Mobility Solutions division, which extends digital monitoring across commercial vehicle deployments. Continental AG dominates engineering partnerships with OEMs, sustaining embedded tire intelligence as a standard feature.
Zeropressure tires incorporate reinforced sidewalls, self-supporting structures, or non-pneumatic architectures that maintain operability after pressure loss, typically rated for speeds up to 50 mph over limited distances in run-flat configurations. Their primary purpose is eliminating roadside failure events in passenger transport, military logistics, and commercial freight where downtime carries disproportionate cost. Run-flat tires occupy the largest installed base among product types, though airless tires are attracting R&D concentration for urban last-mile and autonomous shuttle applications. Among end users, commercial vehicles generate the deepest margin pools due to fleet-scale procurement and total-cost-of-ownership contracting, while passenger vehicles provide the broadest volume foundation.
NHTSA's Federal Motor Vehicle Safety Standards govern run-flat performance labeling and minimum mobility specifications in the United States, while the EU Tire Labeling Regulation and REACH compliance on rubber compound chemicals shape product formulation and market access across Europe. These frameworks elevate technical barriers for new entrants and compel incumbents to maintain dual-certification laboratories. Stakeholders must monitor how emerging solid-state polymer formulations interact with evolving recyclability mandates and whether military procurement specifications migrate into civilian commercial standards.
Market Dynamics
Fleet operators are converting capital-heavy tire purchases into subscription-based lifecycle contracts, compressing upfront procurement into recurring operational expenditure while embedding predictive maintenance software directly into zeropressure tire deployments.
Growth Catalysts
- NHTSA run-flat performance standards:Updated Federal Motor Vehicle Safety Standards mandate minimum mobility specifications after pressure loss, compelling commercial fleets to upgrade legacy pneumatic inventories.
- Military logistics procurement:Defense agencies across NATO member states are expanding airless and run-flat tire contracts for armored vehicle and supply convoy applications where roadside immobilization risks mission failure.
- Self-sealing polymer formulations:Advances in elastomer chemistry enable puncture-sealing capabilities without driver intervention, penetrating premium passenger vehicle lines in Germany.
Market Restraints
- Natural rubber price volatility:Input cost swings for hevea brasiliensis latex concentrate margins, particularly for manufacturers dependent on Southeast Asian supply basins.
- REACH chemical compliance:EU restrictions on specific rubber compound additives force reformulation cycles that extend product development timelines by 12-18 months.
- Ride quality trade-offs:Reinforced sidewall architectures in run-flat configurations transmit greater road harshness, limiting consumer acceptance in comfort-oriented vehicle segments.
Strategic Opportunities
- Autonomous shuttle deployments:Urban mobility pilots in Singapore and Dubai specify airless tire architectures for reduced maintenance intervals in 24/7 operational environments.
- Last-mile delivery electrification:E-commerce logistics hubs in the Netherlands are testing non-pneumatic designs for electric van fleets subject to high curb-impact frequencies.
- EU Green Deal circularity mandates:Upcoming recyclability requirements for tire materials create first-mover advantage for solid-state polymer developers with closed-loop feedstock capabilities.
Industry Challenges
- Embedded systems integration:Pressure monitoring sensors and telematics hardware must interface with legacy fleet management platforms lacking standardized data protocols.
- Dual-certification laboratory capacity:Manufacturers maintaining NHTSA and KBA testing facilities face extended queue times that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zeropressure Tires Market |
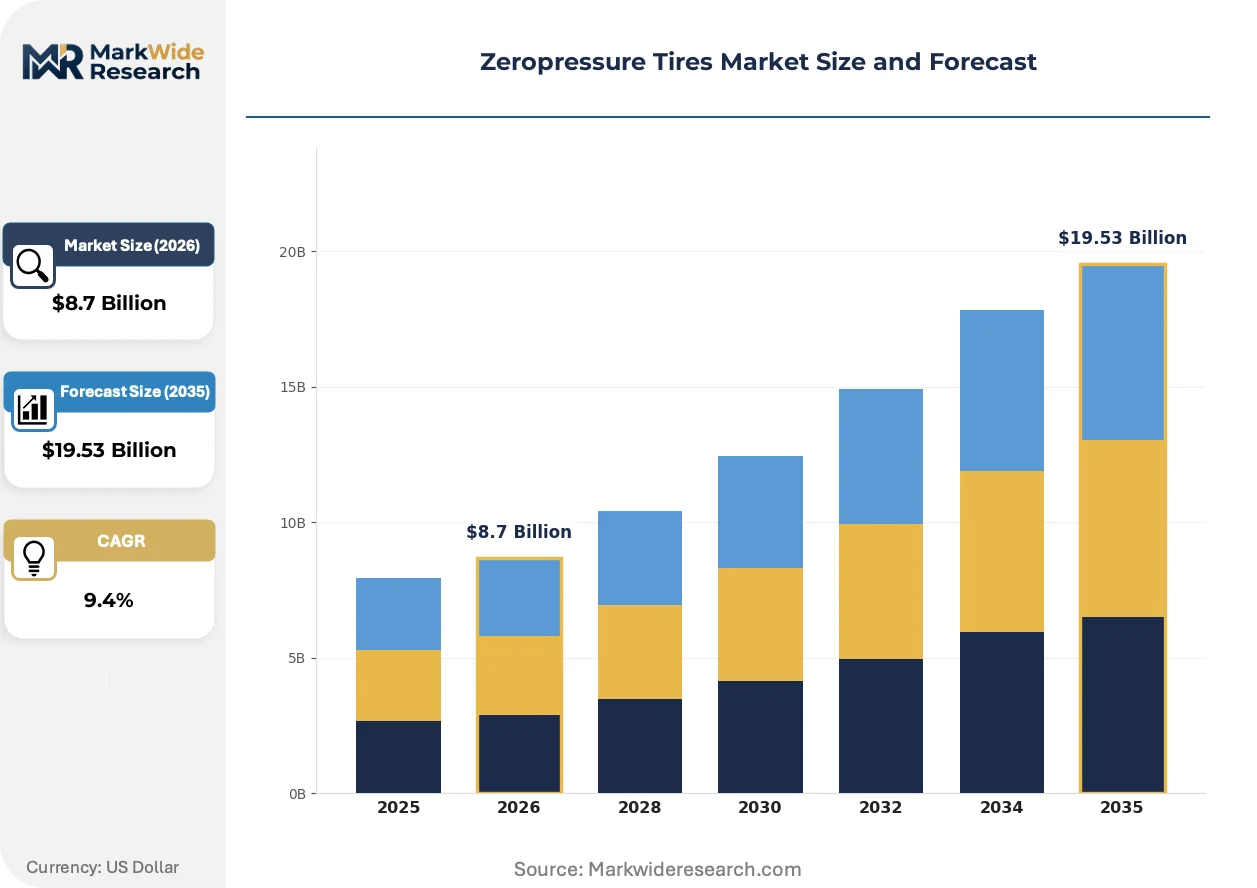
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Sealing Tires, Run-Flat Tires, Airless Tires, Hybrid Tires End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Buses Technology: Pneumatic, Solid, Polymer-Based, Composite Distribution Channel: Online Retail, Offline Retail, Direct Sales, Automotive Dealerships |
| Companies Covered | Michelin, Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, Hankook Tire & Technology, Sumitomo Rubber Industries, Pirelli, The Yokohama Rubber Co., Amerityre Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zeropressure Tires Market Evolving Landscape
Digital tire intelligence is migrating from aftermarket accessories to factory-embedded standard equipment, reshaping how vehicle OEMs specify zeropressure architectures and how fleets extract operational data from rolling stock.
Tread-mounted sensor arrays are automating real-time pressure and temperature telemetry transmission to cloud-based fleet dashboards. Commercial vehicle operators in long-haul freight are deploying these systems most aggressively, with adoption curves compressing from five-year to eighteen-month rollout cycles. This capability is automating preventive maintenance scheduling and eliminating unplanned roadside service events that previously disrupted just-in-time delivery commitments.
REACH authorization procedures for novel rubber processing aids are tightening disclosure requirements for chemical substance volumes and exposure pathways. Compound suppliers must now submit extended safety dossiers before market entry, elevating documentation burdens for reformulated zeropressure tire lines. German and French regulatory authorities are enforcing these provisions most stringently, with KBA and ANSM coordinating cross-border inspection protocols.
Subscription-based tire-as-a-service contracts are displacing traditional unit sales in fleet procurement departments. Logistics operators in the United Kingdom and Benelux markets are contracting total-cost-of-ownership agreements that bundle installation, monitoring, rotation, and end-of-life recycling into per-kilometer pricing. This model transfers residual value risk from fleet balance sheets to tire manufacturers while locking in multi-year supply relationships.
Zeropressure Tires Market Segmentation
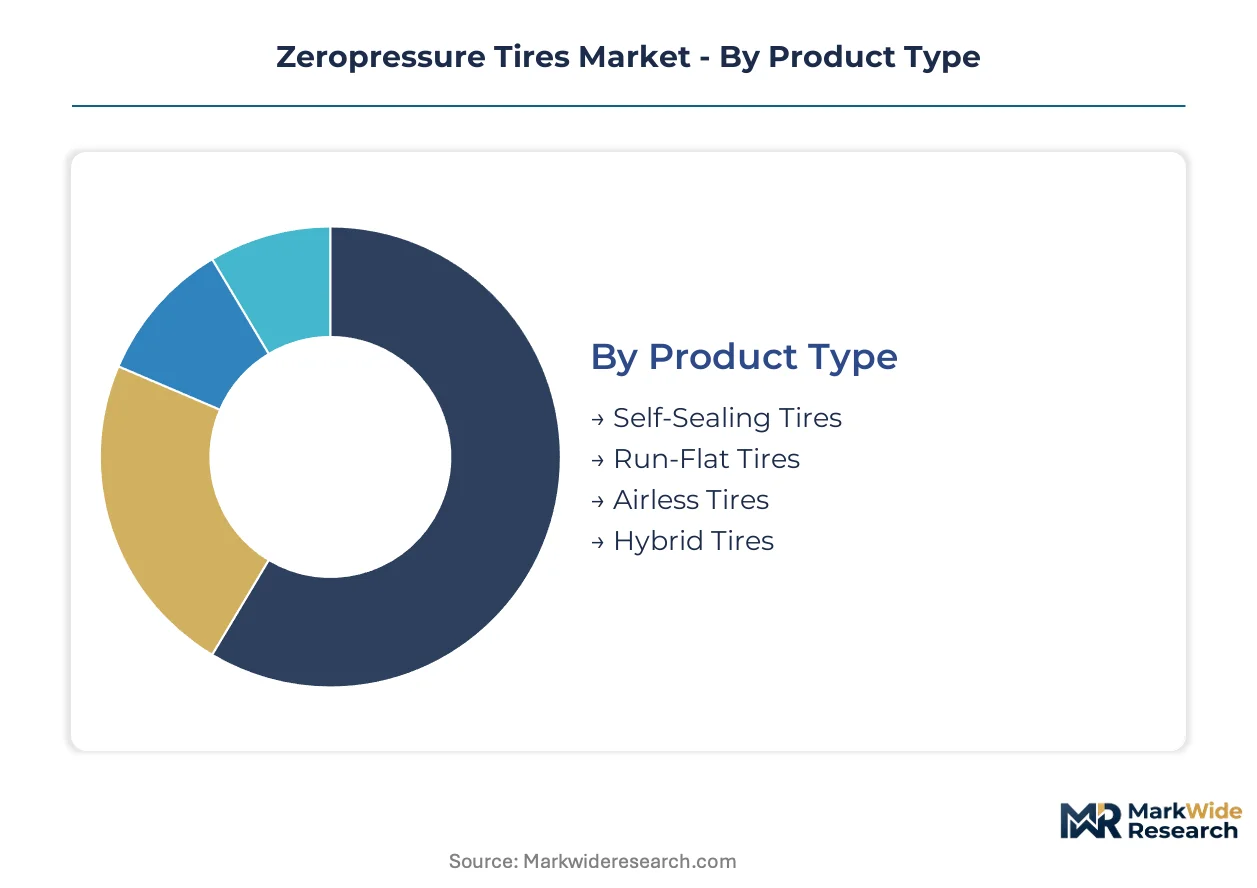
Zeropressure tire architectures vary dramatically in tooling requirements and R&D intensity. Understanding segment-level capital demands reveals why certain manufacturers dominate specific product categories while others concentrate on aftermarket distribution.
Product Type:
Capital intensity peaks with airless architectures requiring entirely new mold designs and polymer science capabilities, while run-flat variants leverage existing pneumatic manufacturing infrastructure.
- Run-Flat Tires:Reinforced sidewall structures maintain vehicle mobility after complete pressure loss, rated typically for 50 miles at reduced speeds. German premium OEMs integrate these as standard fitment across executive sedans, driven by consumer expectations of uninterrupted mobility. Most installed capacity flows through Run-Flat Tires. Expansion is steepest in Airless Tires.
- Airless Tires:Non-pneumatic architectures employing flexible spoke structures or honeycomb matrices eliminate inflation entirely. Singapore and Dubai autonomous shuttle pilots specify these designs for continuous 24/7 operation without maintenance intervals.
- Self-Sealing Tires:Internal polymer liners seal punctures up to 5mm diameter without driver awareness. BMW and Mercedes-Benz deploy these across European passenger lines.
- Hybrid Tires:Combined run-flat and self-sealing capabilities address commercial fleet operators seeking redundant failure protection.
Volume leadership resides with run-flat configurations. Airless designs are gaining share fastest among next-generation mobility platforms.
End User:
Customer procurement patterns separate unit-driven replacement demand from multi-year fleet contracts with embedded telematics requirements.
- Commercial Vehicles:Fleet-scale procurement generates the deepest margin pools through total-cost-of-ownership contracting. Long-haul freight operators in the Benelux region compress adoption cycles from five years to eighteen months for connected tire systems.
- Passenger Vehicles:Premium German OEMs anchor volume foundations with factory-fit specifications across luxury segments. Ride quality trade-offs in reinforced sidewall designs limit penetration in comfort-oriented categories.
- Motorcycles:Two-wheeler applications demand specialized lightweight architectures balancing puncture resistance with unsprung mass constraints.
- Buses:Urban transit authorities specify heavy-duty run-flat configurations for route reliability in high-frequency service corridors.
Commercial vehicle channels command premium pricing power. Passenger vehicle fitments deliver the broadest manufacturing scale.
Technology:
Material science differentiation determines patent positioning and regulatory compliance pathways across formulation categories.
- Polymer-Based:Advanced elastomer formulations enable self-sealing and airless architectures without metallic reinforcement. REACH authorization procedures for novel processing aids extend development timelines for European market entry.
- Pneumatic:Conventional pressurized designs with zeropressure mobility features dominate current installed base and aftermarket replacement cycles.
- Solid:Rubber-filled constructions eliminate air cavity entirely, penetrating industrial and slow-speed applications.
- Composite:Hybrid material structures combining polymer matrices with fiber reinforcement target weight reduction in electric vehicle applications.
Pneumatic technologies retain manufacturing scale advantages. Polymer-based systems are climbing the fastest amid solid-state formulation breakthroughs.
Distribution Channel:
Channel economics separate high-touch specification sales from automated replenishment systems with embedded monitoring.
- Direct Sales:Fleet operators in the United Kingdom contract tire-as-a-service agreements bundling installation, monitoring, and end-of-life recycling into per-kilometer pricing.
- Automotive Dealerships:OEM-authorized networks control premium fitment specifications and warranty-integrated replacement cycles.
- Offline Retail:Independent tire dealers and national chains service aftermarket replacement demand with inventory-heavy operating models.
- Online Retail:E-commerce platforms penetrate price-sensitive replacement segments with direct-to-consumer logistics.
Direct sales channels capture the highest lifetime value per customer. Online retail is expanding most quickly in commoditized replacement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium passenger fitments while the United States dominates military logistics procurement, creating divergent demand profiles across Atlantic markets.
United States
NHTSA's updated Federal Motor Vehicle Safety Standards mandate minimum mobility specifications after pressure loss, compelling commercial fleets to upgrade legacy pneumatic inventories. The Department of Defense is expanding airless and run-flat tire contracts for armored vehicle and supply convoy applications. Michigan-based automotive clusters integrate connected tire intelligence into factory specifications.
Germany
BMW and Mercedes-Benz anchor European volume through factory-fit self-sealing tires across executive sedan lines. KBA enforces REACH authorization procedures for novel rubber processing aids with cross-border inspection protocols coordinated with ANSM. Stuttgart and Munich engineering corridors sustain embedded tire intelligence as standard OEM equipment.
Japan
METI supports solid-state polymer R&D for next-generation airless architectures targeting autonomous shuttle deployments. JIS standards govern performance labeling for run-flat configurations in domestic passenger markets. Nagoya industrial basements concentrate manufacturing infrastructure for reinforced sidewall production.
United Kingdom
Logistics operators in London and Birmingham markets contract tire-as-a-service agreements bundling installation, monitoring, and end-of-life recycling into per-kilometer pricing. The Competition and Markets Authority monitors subscription-based procurement for anti-competitive exclusivity clauses. Midlands distribution hubs test predictive maintenance software integration with legacy fleet management platforms.
Singapore
Urban mobility pilots specify airless tire architectures for 24/7 autonomous shuttle operations without maintenance intervals. The Land Transport Authority coordinates with Dubai on non-pneumatic design validation for tropical climate durability. Jurong manufacturing zones attract polymer science capabilities for honeycomb matrix production.
Zeropressure Tires Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium OEM channels concentrating around integrated tire intelligence providers while aftermarket replacement flows through independent distribution networks. The vendor base organizes into three tiers: multinational compounders with captive R&D facilities, regional fabricators serving fleet procurement departments, and specialty compound suppliers licensing formulations to larger manufacturers. Dominant competitive moves include backward integration into polymer feedstock production and strategic partnerships with autonomous vehicle platform developers.
Within the multinational tier, Michelin, Bridgestone Corporation, and Continental AG occupy positions as archetypal integrated service providers. Michelin exemplifies the connected tire services model through subscription-based fleet relationships. Bridgestone Corporation anchors digital monitoring capabilities across commercial vehicle deployments. Continental AG represents engineering partnership strategies with OEMs for embedded tire intelligence standardization.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone Corporation |
| Continental AG |
| The Goodyear Tire & Rubber Company |
| Hankook Tire & Technology |
| Sumitomo Rubber Industries |
| Pirelli |
| The Yokohama Rubber Co. |
| Amerityre Corporation |
| Others |
Value Network & Pricing Analysis
Fleet procurement departments at NATO defense agencies and German premium OEMs anchor pricing power through multi-year total-cost-of-ownership contracts that compress transactional spot markets into subscription-based per-kilometer arrangements. This buyer concentration shifts margin capture toward manufacturers with captive monitoring software and end-of-life recycling capabilities.
Pricing Analysis
Capacity additions in Thailand and Vietnam are reshaping price floors for natural rubber feedstocks, transmitting cost volatility into compound formulation budgets. Three-tier pricing structure across premium, standard, and economy levels separates Michelin and Continental AG's connected tire services from commodity run-flat replacements. Pricing pressure stems from REACH authorization delays extending European product launches by 12-18 months. Commercial vehicle fleets exhibit lowest price sensitivity due to embedded telematics requirements, while independent aftermarket channels face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian hevea brasiliensis latex concentrate suppliers, where climate disruption and labor availability constrain harvest predictability. Manufacturing draws from Thailand, China, and Germany for mold fabrication, polymer compounding, and embedded sensor assembly. Tariff exposure on Southeast Asian rubber imports into the European Union elevates landed cost uncertainty. Distribution runs through captive OEM supply agreements for factory fitments and independent dealer networks for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as military logistics and autonomous shuttle specifications displace commodity pneumatic alternatives with performance-validated architectures.
For Market Incumbents: Deploy predictive maintenance software layers to lock in fleet subscription renewals before Bridgestone Corporation and Hankook Tire replicate connected tire service portfolios. Consolidate backward integration into solid-state polymer feedstock production to hedge REACH reformulation cycles. Counter airless tire specialists by accelerating KBA certification queue positions for hybrid run-flat architectures. For New Entrants and Emerging Players: Fleet telematics integrators present the most accessible partnership pathway for sensor-embedded tire architectures lacking legacy manufacturing infrastructure. Target autonomous shuttle pilots in Singapore and Dubai where airless specifications remain uncaptured by incumbent supply agreements. Pursue white-label manufacturing contracts with Netherlands-based last-mile electrification hubs testing non-pneumatic van configurations. For Investors and Strategic Acquirers: Tire-as-a-service platform operators are the most active acquirer in this space, consolidating regional fleet management providers to embed per-kilometer pricing capabilities. Five-to-ten year viability hinges on polymer science differentiation beyond commodity rubber compounding. Monitor solid-state formulation patent filings as inflection indicator for material substitution risk in pneumatic-dominant installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive supply of REACH-compliant elastomers insulates Continental AG from authorization delays. |
| Embedded Tire Intelligence Standardization | Factory-fit sensor arrays cement Michelin's multi-year OEM engineering partnerships. |
| Airless Architecture Pilot Deployment | Singapore Land Transport Authority validation positions developers for Dubai expansion. |
| Subscription-Based Lifecycle Contracting | Per-kilometer pricing transfers residual value risk from UK fleet balance sheets. |
| Dual-Certification Laboratory Investment | NHTSA and KBA testing capacity reduces queue times for German premium OEM launches. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and Singapore, with primary inputs from each. Primary interviews with fleet procurement directors, OEM platform engineers, tire compound R&D leads, and military logistics contracting officers combined with secondary validation from NHTSA Federal Motor Vehicle Safety Standards filings, KBA type-approval databases, EU REACH authorization registers, and METI solid-state polymer research disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation cross-validated volume and value estimates.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement pattern, material technology, and distribution channel structure. CAGRs derived from fitted growth curves applied to base-year market sizing. Industry-specific forecast inputs incorporated military procurement pipeline visibility and autonomous shuttle pilot expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state polymer breakthroughs, REACH chemical authorization timelines, and military specification migration into civilian standards. Forecasts reflect documented assumptions about fleet electrification penetration and subscription contracting adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Alloy Wheels Market