
 Global Tire Cord Fabrics Market | 2026-2036
Global Tire Cord Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tire Cord Fabrics Market Foresight
Polymer engineering talent scarcity is bifurcating the competitive landscape between integrated compounders and specialty converters. Kordsa Global leverages captive nylon-6,6 polymerization to secure feedstock continuity for high-tenacity cord operations. Hyosung Corporation anchors its position through backward integration into caprolactam and adipic acid production. Teijin Limited differentiates via aramid fiber expertise transferred from ballistic protection applications into ultra-high-performance tire reinforcement.
Tire cord fabrics are high-strength textile reinforcements engineered from twisted filament yarns, typically polyester, nylon, rayon, or aramid, which are woven or braided and then dip-coated with resorcinol-formaldehyde-latex adhesives to achieve rubber-to-fabric bonding critical for tire structural integrity. Steel cord dominates value capture due to its irreplaceable role in radial truck and bus tire belts where tensile strength exceeds 2,800 MPa. Polyester cord is displacing rayon in passenger car radial ply applications as manufacturing economies and hydrolysis resistance improve. Aramid cord occupies niche premium segments where mass reduction justifies material cost premiums of several multiples over conventional alternatives.
The US NHTSA tire safety standards, the EU REACH regulation on chemical substances in dip-coating formulations, and China's GB standards for radial tire performance collectively shape material substitution patterns and compliance costs across the supply base. EPA oversight of adhesive solvent emissions influences coating line capital expenditure decisions for North American producers. Stakeholders must monitor evolving battery-electric vehicle axle load distributions and torque profiles that will redefine fatigue specifications for next-generation reinforcement architectures.
Market Dynamics
Automotive electrification is fundamentally restructuring tire cord fabric specifications, as battery-electric vehicle powertrains impose asymmetric axle loads and instantaneous torque profiles that conventional reinforcement architectures were never engineered to withstand.
Growth Catalysts
- India's tire production scaling:Domestic capacity expansion to serve local vehicle assembly and export markets is concentrating procurement demand for high-tenacity polyester and nylon-6,6 cord fabrics.
- EU tire labeling regulations:Mandatory disclosure of rolling resistance and wet grip performance is compelling OEMs to specify advanced reinforcement materials that reduce hysteresis losses.
- Lightweighting mandates:China's MIIT fuel economy standards are pushing electric vehicle manufacturers toward aramid and hybrid cord constructions that cut unsprung mass.
Market Restraints
- Caprolactam supply concentration:Nylon-6,6 precursor production clusters in Northeast Asia create feedstock vulnerability for non-integrated cord fabric producers in Europe and North America.
- REACH chemical compliance:ECHA restrictions on resorcinol-formaldehyde-latex adhesive formulations are forcing costly reformulation of dip-coating chemistries without mature substitutes.
- Steel cord substitution ceiling:Radial truck tire belts remain locked into steel reinforcement above 2,800 MPa tensile requirements that polymer fibers cannot satisfy.
Strategic Opportunities
- Brazilian tire localization:ANVISA-aligned domestic manufacturing incentives are opening procurement channels for cord fabric suppliers as tire OEMs regionalize supply chains.
- Aramid-polyester hybrids:Convergence of high-modulus aramid with cost-optimized polyester enables tiered performance architectures for premium electric vehicle platforms.
- Digital coating line retrofits:Solvent recovery and closed-loop adhesive systems qualify for IRA clean manufacturing credits in US-based production facilities.
Industry Challenges
- Polymer engineering talent scarcity:Compound formulation and high-tenacity spinning expertise concentrates at integrated producers, constraining specialty converter expansion.
- Multi-standard certification complexity:Simultaneous compliance with US NHTSA, EU REACH, and China GB testing protocols extends product qualification timelines by 18-24 months.
- Legacy radial tire retooling:Existing weaving and dipping assets require substantial capital redeployment to handle next-generation hybrid yarn constructions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tire Cord Fabrics Market |
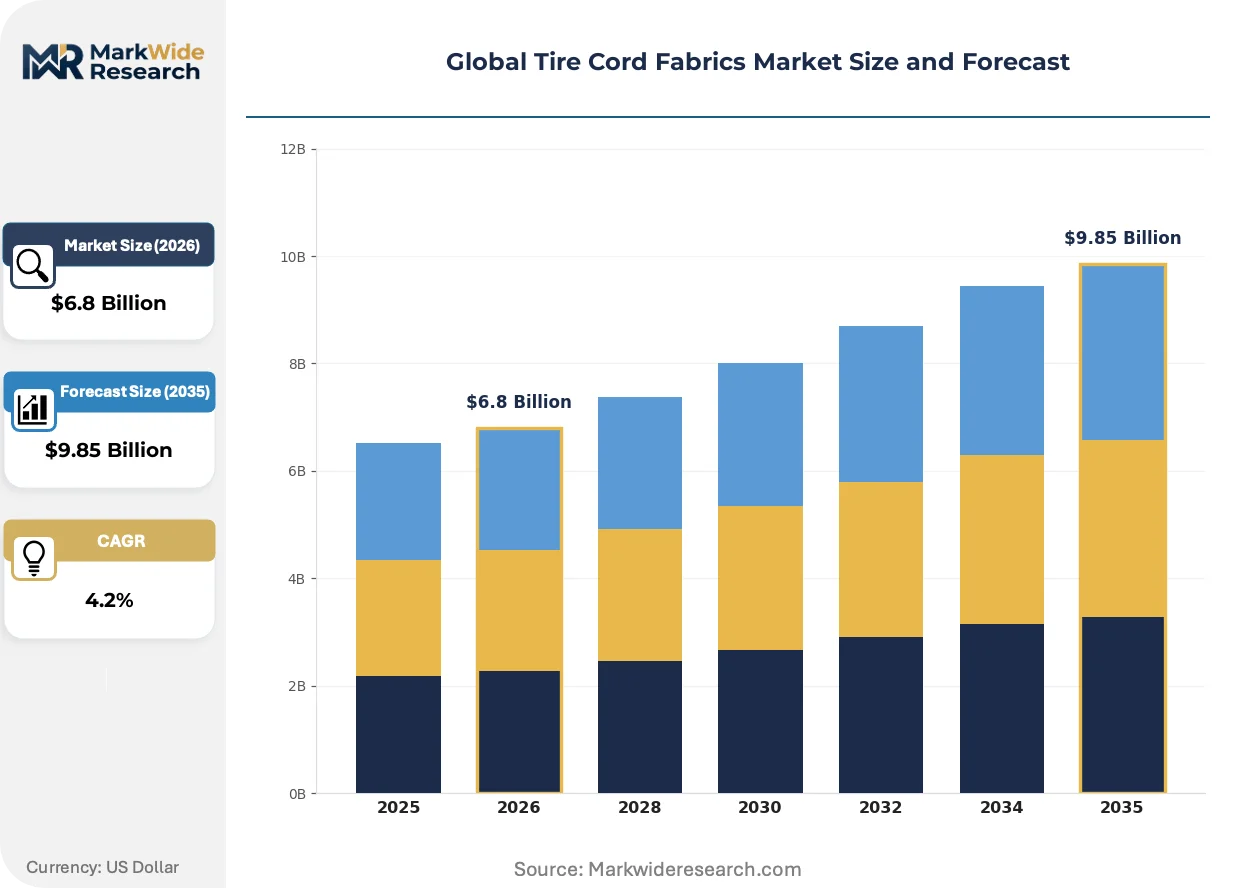
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Cord, Polyester Cord, Rayon Cord, Nylon Cord, Aramid Cord Application: Passenger Vehicle Tires, Commercial Truck Tires, Off-The-Road Tires, Two-Wheeler Tires, Agricultural Tires Technology: Twisting, Braiding, Weaving, Coating, Laminating End User: Original Equipment Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Retreaders |
| Companies Covered | Kordsa Global, Toray Industries, Hyosung Corporation, Kolon Industries, SRF Limited, Teijin Limited, Indorama Ventures Public Company Limited, Century Enka Limited, Bekaert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tire Cord Fabrics Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry restrictions are jointly rewriting tire cord fabric specifications, with performance thresholds now defined by electrification-driven fatigue requirements rather than legacy internal combustion vehicle duty cycles.
Hybrid aramid-polyester cord constructions are displacing conventional nylon-6,6 in premium passenger electric vehicle tires, where mass reduction justifies material cost premiums. Tier 1 suppliers are qualifying these architectures for original equipment fitment on performance electric sedans and crossovers. The shift is compressing addressable volume for standalone nylon cord in the highest-margin tire segments.
REACH Annex XVII restrictions on formaldehyde-releasing substances are forcing adhesive formulators to validate alternative latex crosslinking chemistries. The industrial consequence is a two-year qualification backlog at European dip-coating facilities. Passenger tire producers serving EU markets are absorbing reformulation costs and extending supplier development timelines to maintain CE marking compliance.
Fleet procurement consolidation among logistics operators is compressing tire specification cycles and demanding outcome-based durability guarantees rather than component-level material certifications. Direct sourcing agreements between mega-fleet operators and tire OEMs are disintermediating traditional distributor channels. This pattern is most visible in North American long-haul trucking, where top-ten fleet operators now control a disproportionate share of radial truck tire procurement decisions.
Global Tire Cord Fabrics Market Segmentation
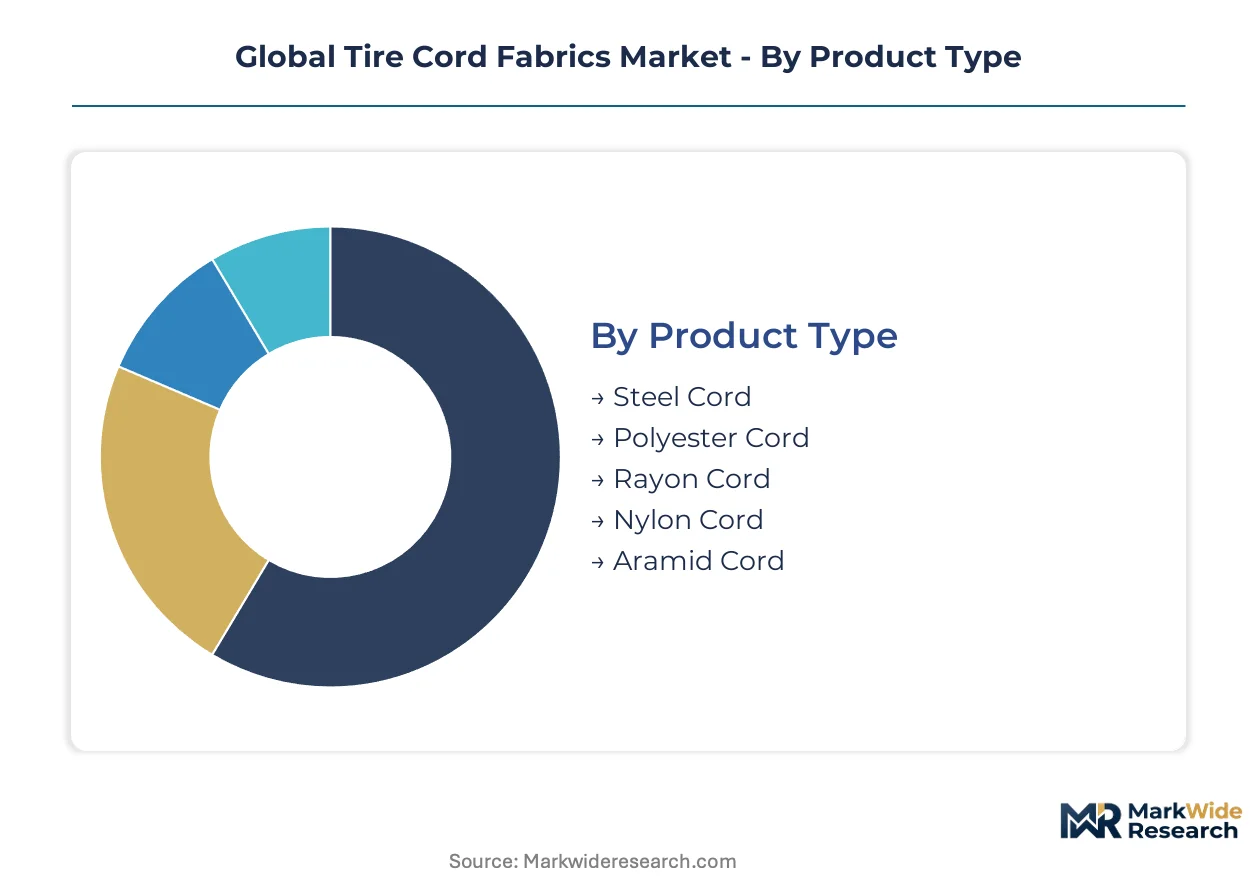
Tire cord fabric segmentation reveals how material specifications diverge across vehicle electrification tiers and duty cycles. Product type and application dimensions together determine qualification barriers and contract tenure for suppliers serving OEM and replacement channels.
Product Type:
Margin pools concentrate in high-tenacity synthetic polymers where compound formulation expertise creates supplier stickiness, while steel cord commands value through irreplaceable performance in heavy-load architectures.
- Steel Cord:Ultra-high-tensile wire filaments exceeding 2,800 MPa dominate radial truck and bus tire belts where polymer alternatives fail. Demand clusters in North American long-haul fleet procurement and Chinese commercial vehicle production, with specifications tightening around fatigue resistance under electric axle loads.
- Polyester Cord:High-modulus polyethylene terephthalate filaments deliver hydrolysis-resistant reinforcement for passenger car radial plies. Indian domestic tire capacity expansion is accelerating procurement of industrial-grade polyester cord as local OEMs regionalize supply chains away from Southeast Asian imports.
- Rayon Cord:Regenerated cellulose filaments retain niche fitment in premium comfort-biased tires where dimensional stability under dynamic loading remains valued.
- Nylon Cord:Polyamide-6 and nylon-6,6 constructions serve bias-ply and select radial applications requiring high elongation at break.
- Aramid Cord:Aromatic polyamide fibers from para-aramid chemistry enable mass reduction in ultra-high-performance electric vehicle tires, justifying material cost premiums through unsprung weight savings.
Steel cord holds installed capacity. Aramid cord is rotating up the share rankings.
Application:
Volume concentration tracks vehicle parc composition, with electrification intensity varying sharply across duty cycles and regional fleet turnover rates.
- Passenger Vehicle Tires:Radial constructions for sedans, crossovers, and SUVs constitute the highest-volume procurement channel. EU tire labeling regulations are pushing OEMs toward low-hysteresis reinforcement materials as rolling resistance disclosure affects consumer purchase decisions.
- Commercial Truck Tires:Heavy-duty radial and bias designs for Class 8 vehicles and regional delivery trucks impose the most severe fatigue specifications. Chinese MIIT fuel economy standards are compressing specification cycles for domestic fleet operators.
- Off-The-Road Tires:Mining and construction equipment tires requiring cut-resistant reinforcement operate on extended replacement cycles with concentrated OEM procurement.
- Two-Wheeler Tires:Motorcycle and scooter applications in India and Southeast Asia drive high-volume, cost-optimized cord specifications with shorter qualification timelines.
- Agricultural Tires:Tractor and harvester tires with reinforced sidewalls serve seasonal demand patterns tied to planting and harvest cycles.
Passenger vehicle tires anchor procurement volume. Commercial truck tires are climbing the fastest on electrification-driven specification upgrades.
Technology:
Process intensity varies by yarn architecture complexity, with multi-stage coating and laminating operations capturing value through adhesion chemistry proprietary to integrated suppliers.
- Twisting:Filament aggregation into plied yarns with controlled twist coefficients determines tensile translation efficiency and fatigue life.
- Braiding:Interlaced yarn architectures for specialized hose and tire components requiring multidirectional load distribution.
- Weaving:Loom-based fabric construction for calendered tire cord sheets with defined warp and weft densities.
- Coating:Resorcinol-formaldehyde-latex dip application achieving rubber-to-fabric bonding, now subject to REACH-driven reformulation costs at European facilities.
- Laminating:Multi-layer composite assembly for hybrid cord constructions combining aramid and polyester performance tiers.
Coating holds process-specific margin concentration. Laminating is gaining share fastest on hybrid material adoption.
End User:
Contract structures diverge sharply between OEM direct procurement with multi-year qualification requirements and aftermarket spot purchasing with compressed lead times.
- Original Equipment Manufacturers:Vehicle assemblers and captive tire subsidiaries specify reinforcement materials through 3-5 year supply agreements with embedded volume commitments. Indian electric vehicle OEMs are expanding technical qualification teams to manage local tire supplier development.
- Tier-1 Suppliers:Dedicated tire manufacturers serving multiple OEM platforms aggregate cord fabric demand across brand portfolios, concentrating procurement leverage.
- Aftermarket Providers:Distributor and retail channels for replacement tires operate on shorter procurement cycles with specification flexibility.
- Retreaders:Tire remanufacturing specialists require cord fabric for tread bonding and casing repair in commercial vehicle applications.
Tier-1 suppliers hold consolidated procurement volume. Aftermarket providers are expanding fastest on fleet vehicle parc growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT fuel economy standards in China anchor the dominant geography, compressing specification cycles for reinforcement materials across Asia-Pacific manufacturing clusters while EU REACH restrictions and US NHTSA safety mandates reshape procurement patterns in Western markets.
China
Domestic electric vehicle assembly expansion drives procurement of high-tenacity nylon-6,6 and hybrid aramid-polyester cord fabrics for premium passenger tire platforms. GB standards for radial tire performance mandate rolling resistance benchmarks that favor advanced reinforcement architectures. Yangtze River Delta manufacturing clusters concentrate dip-coating capacity serving both local OEMs and export-oriented tire producers.
United States
Long-haul fleet operator consolidation concentrates radial truck tire procurement decisions among mega-fleet managers demanding outcome-based durability guarantees. EPA oversight of adhesive solvent emissions influences coating line capital expenditure decisions for domestic producers. Southeast manufacturing corridors host weaving and dipping assets retooling for next-generation hybrid yarn constructions.
Germany
EU tire labeling regulations compelling OEM disclosure of rolling resistance performance reshape material specifications for premium passenger vehicle platforms. ECHA restrictions on resorcinol-formaldehyde-latex adhesive formulations force costly reformulation at European dip-coating facilities. Baden-Württemberg industrial clusters anchor specialty chemical supply for alternative crosslinking chemistry development.
India
Domestic tire production capacity scaling to serve local vehicle assembly and export markets concentrates procurement demand for industrial-grade polyester cord. PLI scheme incentives support technical qualification teams at electric vehicle OEMs managing local tire supplier development. Gujarat and Maharashtra manufacturing belts host expanding weaving operations regionalizing supply chains away from Southeast Asian imports.
Brazil
ANVISA-aligned domestic manufacturing incentives open procurement channels for cord fabric suppliers as tire OEMs regionalize supply chains for Latin American markets. Import substitution policies strengthen local content requirements for commercial vehicle tire production. São Paulo industrial corridors concentrate calendering and tire assembly capacity serving Mercosur distribution networks.
Global Tire Cord Fabrics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure bifurcating between compounders commanding captive polymerization assets and converters dependent on merchant feedstock supply. Three archetypes define competitive positioning: integrated polymer-to-fabric producers securing feedstock continuity, steel cord specialists dominating heavy-load radial applications, and aramid fiber innovators transferring defense-sector expertise into automotive reinforcement. Capacity expansion and backward integration into precursor chemicals represent the dominant competitive moves reshaping supplier hierarchies.
Among integrated synthetic fiber producers, Kordsa Global and Hyosung Corporation exemplify archetypes leveraging captive polymerization assets to secure feedstock continuity for high-tenacity cord operations. Teijin Limited occupies a position within the specialty materials tier, representing transfer of ballistic protection fiber expertise into ultra-high-performance tire reinforcement applications. These three anchors illustrate how polymer engineering capabilities concentrate competitive advantage in a market where qualification timelines and formulation expertise create substantial barriers to specialist converter expansion.
| Leading Market Players |
|---|
| Kordsa Global |
| Toray Industries |
| Hyosung Corporation |
| Kolon Industries |
| SRF Limited |
| Teijin Limited |
| Indorama Ventures Public Company Limited |
| Century Enka Limited |
| Bekaert |
| Others |
Supply & Pricing Matrix
Capacity utilization at integrated nylon-6,6 polymerization facilities in Northeast Asia anchors price floors for high-tenacity cord fabrics, with scale economies at Kordsa Global and Hyosung Corporation compressing margins for non-integrated European and North American converters dependent on merchant caprolactam supply.
Pricing Analysis
Geographic price spreads between Yangtze River Delta manufacturing clusters and European dip-coating facilities reflect REACH-driven reformulation cost absorption. Contract-based long-term offtake dominates OEM procurement, with price differentiation tracking certification grade and volume scale. Cost compression in standard polyester cord intensifies as Indian domestic weaving capacity scales. Fleet procurement consolidation in North American long-haul trucking exhibits lowest price sensitivity; two-wheeler tire producers in Southeast Asia face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of adipic acid and caprolactam prevails among integrated producers, while merchant-dependent converters operate on just-in-time feedstock schedules vulnerable to Northeast Asian supply disruptions. Manufacturing concentrates in China, India, and South Korea. Production draws from petrochemical-derived polymers, steel wire rod, and aramid fiber precursors. Single-source vulnerability clusters around caprolactam production. Distribution runs through Tier-1 tire manufacturers aggregating multi-OEM demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical qualification services and adhesive formulation support are expanding faster than base cord fabric sales, creating recurring-revenue layers as OEMs outsource REACH compliance and hybrid material development to supplier partners.
For Market Incumbents: Shield market position by deepening captive polymerization capacity in India to serve PLI-scheme tire production scaling. Prioritize certification investment for aramid-polyester hybrid architectures before EU tire labeling regulations tighten further. Lock in multi-year supply agreements with emerging Indian electric vehicle OEMs expanding technical qualification teams. For New Entrants and Emerging Players: Differentiate on bio-based adhesive formulations addressing ECHA restrictions on formaldehyde-releasing substances. Target Brazilian tire localization under ANVISA-aligned manufacturing incentives as the most penetrable geography. Pursue direct qualification with retreaders seeking alternative cord suppliers for commercial vehicle casing repair. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated compounders with captive polymerization and in-house dip-coating capabilities. Long-term viability favors suppliers controlling upstream chemical inputs rather than converters exposed to feedstock volatility. Watch battery-electric vehicle axle load specification thresholds as the inflection signal for next-generation fatigue-resistant reinforcement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Secures feedstock continuity for nylon-6,6 cord operations against Northeast Asian supply concentration. |
| REACH-Compliant Adhesive Reformulation | Enables continued EU market access as ECHA restrictions on formaldehyde-releasing substances tighten. |
| Hybrid Cord Laminating Capacity Expansion | Captures premium electric vehicle procurement shifting toward aramid-polyester mass-reduction architectures. |
| Digital Coating Line Retrofit | Qualifies for IRA clean manufacturing credits while reducing solvent emission compliance costs. |
| Indian Technical Qualification Team Buildout | Aligns with PLI-scheme electric vehicle OEMs regionalizing tire supply chains away from imports. |
Research Methodology
The analysis maps steel cord, synthetic polymer cord, and hybrid material sub-sectors, each validated through procurement directors at Tier-1 tire manufacturers, plant managers at dip-coating facilities, and regulatory affairs leads navigating REACH compliance. Primary interviews with OEM platform engineers and aftermarket fleet operators combined with secondary validation from customs trade data, SEC filings of listed fiber producers, MIIT fuel economy standard disclosures, and ECHA restriction updates. Bottom-up capacity assessments and top-down demand modeling were triangulated for consistency.
Outputs were validated against external benchmarks including vehicle production databases and tire industry association capacity surveys across the analysis window. Segmentation dimensions modeled include product type, vehicle application, coating technology, and end-user procurement structure. CAGRs were derived from elasticity-adjusted demand projections incorporating electric vehicle penetration rates and regional fleet turnover patterns. Forecast inputs included GB standard evolution timelines and battery-electric vehicle axle load specification trajectories.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle assembly expansion or abrupt REACH chemical bans would require recalibration. Forecasts reflect assumptions on feedstock price stability and qualification timeline continuity. Revision becomes warranted when caprolactam supply disruption severity or adhesive reformulation cost thresholds cross materiality levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Spun Yarn Paper Cone Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market