
 Tire Yarn Market | 2026-2036
Tire Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Yarn Market Analytics
Modular tire cord bundling is consolidating buyer choice as manufacturers shift from standalone yarn purchases to integrated reinforcement packages combining polyester, nylon, and adhesion-treated cords. Invista leverages its upstream polymer capacity to anchor supply security for major tire makers across North America and Europe. Hyosung sustains cost leadership through captive caprolactam production for its nylon tire yarn lines. Kolon Industries specializes in aramid-based solutions for ultra-high-performance tire segments where heat resistance commands premium positioning.
Tire yarn comprises high-tenacity synthetic or metallic filaments engineered into cord structures that reinforce rubber matrices, typically achieving tensile strengths exceeding 6.0 grams per denier for polyester grades and 9.0 grams per denier for nylon variants, with primary function to maintain dimensional stability under cyclic loading and elevated temperatures during vehicle operation. Polyester dominates volume in passenger tire applications where dimensional stability and fatigue resistance outweigh cost premiums, while aramid captures margin concentration in motorsport and aircraft tire segments where specific strength thresholds justify material expenditure. Steel cord retains structural primacy in heavy-duty truck radial tires where load-bearing requirements exceed synthetic fiber capabilities.
FDA oversight of rubber chemical migration in tire manufacturing environments, EPA emissions standards for fiber production facilities, and REACH substance restrictions on adhesion promoters collectively elevate compliance investment for yarn producers supplying European and North American tire makers. China's GB standards and MIIT industrial guidelines impose parallel technical specifications on domestic tire cord supply chains. Stakeholders must monitor regulatory divergence between jurisdictions as carbon accounting requirements and extended producer responsibility frameworks reshape material qualification protocols and cross-border sourcing decisions.
Market Dynamics
Radial tire expansion in China is compressing global supply chains as domestic manufacturers absorb polyester and nylon yarn capacity that previously served export markets, forcing European and North American tire makers to secure alternative reinforcement sources.
Growth Catalysts
- REACH chemical compliance:Europe's tightening adhesion promoter restrictions are accelerating substitution toward water-based bonding systems that reduce environmental liability for tire cord suppliers.
- Lightweighting mandates:Passenger vehicle OEMs are specifying high-tenacity polyester grades to meet fuel efficiency targets without sacrificing durability thresholds.
- Radialization:China's domestic tire sector is converting bias-ply production lines to radial capacity, multiplying yarn consumption per tire unit.
Market Restraints
- Caprolactam price volatility:Nylon tire yarn production remains exposed to benzene derivative cost swings that compress margin predictability for non-integrated producers.
- Steel cord substitution floor:Heavy-duty truck radial applications maintain synthetic fiber exclusion zones where load-bearing requirements exceed polymer capabilities.
- REACH authorization delays:ECHA substance evaluation timelines for legacy adhesion chemistries are freezing qualification pathways for modified cord treatments.
Strategic Opportunities
- Aramid thermal performance:Motorsport and aircraft tire segments reward heat-resistant reinforcement with premium positioning unattainable by commodity synthetics.
- India radial penetration:Domestic tire manufacturers are expanding radial capacity with yarn specifications aligned to BIS technical standards.
- Modular bundling contracts:Integrated reinforcement packages combining multiple fiber types with adhesion treatment are displacing standalone yarn procurement.
Industry Challenges
- Polymer process engineering talent:High-tenacity spinning expertise concentrates among aging technical workforces with limited knowledge transfer pipelines.
- Multi-jurisdiction carbon accounting:Divergent embodied emissions measurement protocols between EU CBAM and China's dual carbon goals complicate cross-border material qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Yarn Market |
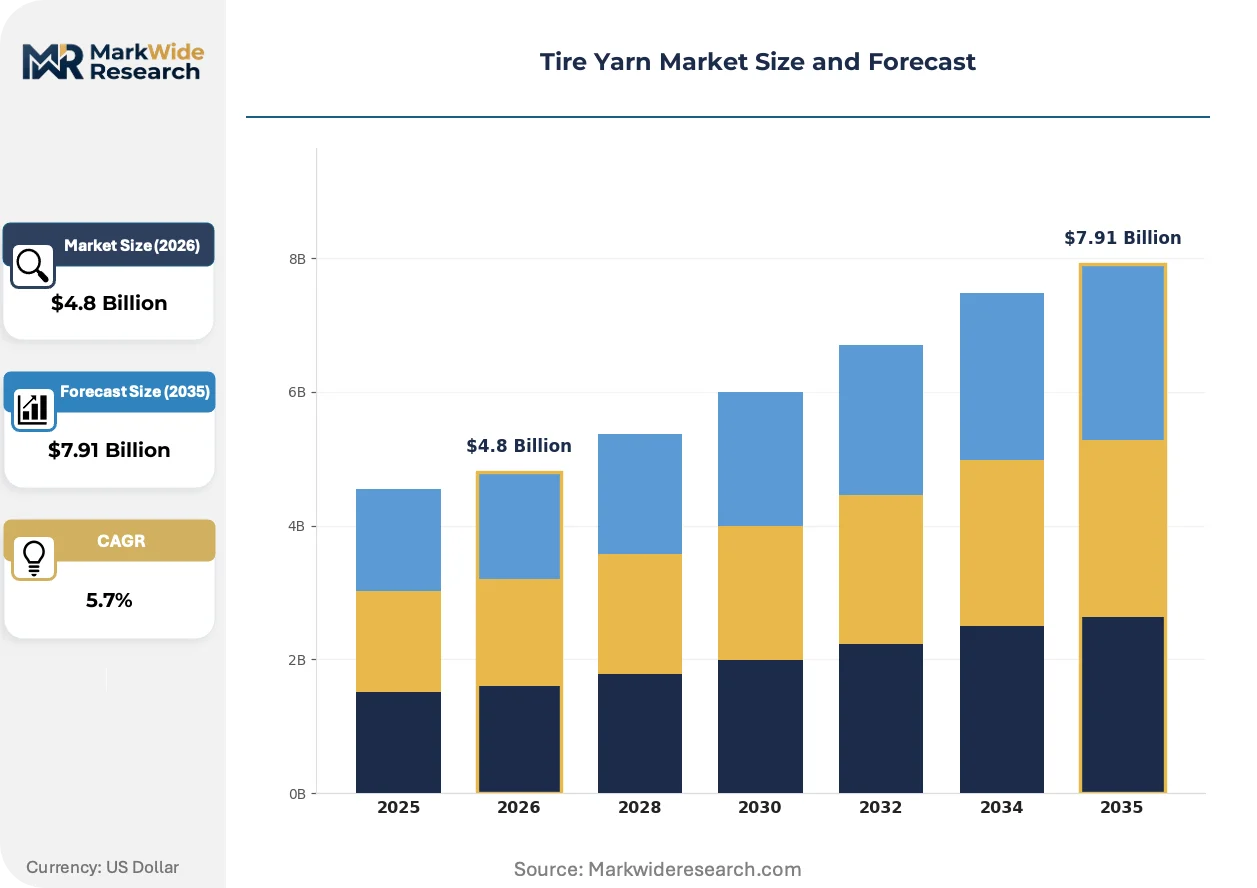
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, Steel, Aramid Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles End User: OEMs, Aftermarket Suppliers, Tire Manufacturers, Distributors Form: Filament, Staple, Textured, Composite |
| Companies Covered | Invista, Hyosung, Toray Industries, Teijin, Kolon Industries, Indorama Ventures, SRF Limited, Kordsa Teknik Tekstil, Asahi Kasei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Yarn Market Evolving Landscape
Reinforcement material science is converging with digital manufacturing controls as tire makers demand lot-level traceability and predictive performance modeling from yarn suppliers.
Hybrid cord architectures are integrating recycled-content polyester with virgin high-tenacity filaments to meet automotive OEM circularity targets without sacrificing fatigue resistance. Tier 1 tire manufacturers in Germany and Japan are qualifying these grades for premium passenger tire lines. The technology is integrating sustainability credentials into supplier selection criteria that previously prioritized cost and availability alone.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in fiber production cooling systems, compelling yarn producers to retrofit facilities with alternative refrigeration chemistries or process heat recovery. Capital expenditure requirements are concentrating among smaller cord treatment specialists lacking balance sheet capacity for equipment replacement. Southeast Asian export-oriented plants face the steepest compliance timeline pressure as they supply European tire makers bound by Scope 3 emissions disclosure.
Fleet operators are consolidating tire procurement through managed service contracts that bundle replacement scheduling with performance guarantees, compressing yarn supplier access to direct specification influence. Commercial vehicle tire makers now negotiate reinforcement requirements with fleet management platforms rather than individual OEMs. This pattern is most pronounced in North American long-haul trucking where tire-as-a-service models capture maintenance decision-making from driver-level discretion.
Tire Yarn Market Segmentation
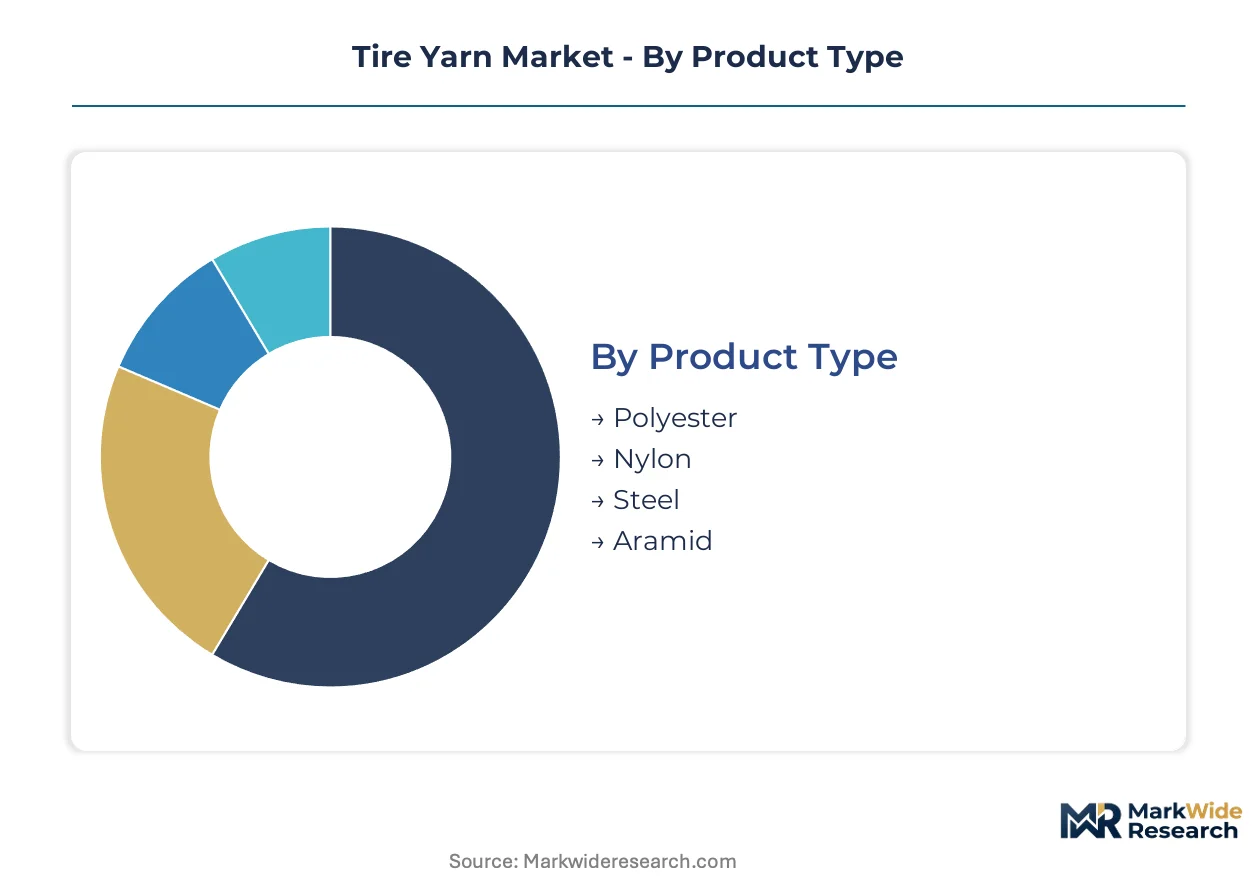
Tire yarn segmentation tracks how reinforcement chemistry, vehicle duty cycles, and supply chain position determine specification intensity and contract value. Material selection cascades through adhesion treatment requirements, thermal performance thresholds, and OEM qualification timelines that lock in multi-year supply relationships.
Product Type:
Customization intensity varies sharply across this category, from commodity-grade polyester with standardized tenacity specifications to aramid grades requiring lot-level thermal performance certification.
- Polyester:High-tenacity filament yarn achieving tensile strengths above 6.0 grams per denier dominates passenger tire carcass and belt applications where dimensional stability under cyclic loading outweighs cost premiums. Demand concentrates with Chinese radial tire manufacturers expanding domestic capacity, absorbing polyester volumes that previously supplied export markets and forcing European and North American tire makers to secure alternative reinforcement sources.
- Nylon:Caprolactam-based high-tenacity grades deliver fatigue resistance and adhesion compatibility for passenger and light truck tire belts, with captive caprolactam production anchoring cost leadership for integrated manufacturers. Specification intensity peaks in markets where REACH adhesion promoter restrictions are accelerating substitution toward water-based bonding systems.
- Steel:Brass-coated wire cord maintains structural primacy in heavy-duty truck radial tires where load-bearing requirements exceed synthetic fiber capabilities.
- Aramid:Heat-resistant para-aramid filaments command premium positioning in motorsport and aircraft tire segments where specific strength thresholds justify material expenditure.
Most installed capacity flows through Polyester. Expansion is steepest in Aramid as thermal performance specifications tighten in ultra-high-performance segments.
Application:
Duty cycle severity and load-bearing requirements segment this category from low-stress passenger applications to extreme-load mining truck deployments.
- Passenger Vehicles:Radial tire architectures specify polyester-dominant reinforcement packages balancing fuel efficiency targets against durability thresholds, with lightweighting mandates from German and Japanese OEMs driving high-tenacity grade adoption. Fleet consolidation through managed service contracts is compressing yarn supplier access to direct specification influence as fleet management platforms capture tire procurement decisions.
- Commercial Vehicles:Regional delivery and urban freight applications combine polyester carcass with nylon belt reinforcement to balance cost against puncture resistance and retreadability.
- Heavy-Duty Trucks:Steel cord retains structural primacy in long-haul and mining applications where load-bearing requirements exceed polymer capabilities.
- Motorcycles:Bias-ply and radial architectures specify nylon-dominant reinforcement for high-speed stability and sidewall flexibility in two-wheeler duty cycles.
Volume concentration sits with Passenger Vehicles. Specification intensity is climbing fastest in Heavy-Duty Trucks as retread economics and fleet uptime guarantees tighten performance thresholds.
End User:
Contract structure and technical integration depth separate this category from spot-market distributors to multi-year OEM qualification partnerships.
- OEMs:Vehicle manufacturers specify reinforcement packages through platform-level supply agreements with tire makers, embedding yarn performance criteria into tire qualification protocols that span development cycles.
- Aftermarket Suppliers:Independent tire distributors and service networks procure replacement tire reinforcement through fragmented spot-market channels with limited specification influence.
- Tire Manufacturers:Tier 1 and Tier 2 tire makers negotiate yarn supply through modular bundling contracts combining multiple fiber types with adhesion treatment, displacing standalone yarn procurement.
- Distributors:Regional and national tire distributors aggregate demand from smaller tire makers and retreaders with limited direct mill relationships.
Contract value concentrates with Tire Manufacturers. Technical integration depth is deepening fastest with OEMs as platform-level supply agreements expand.
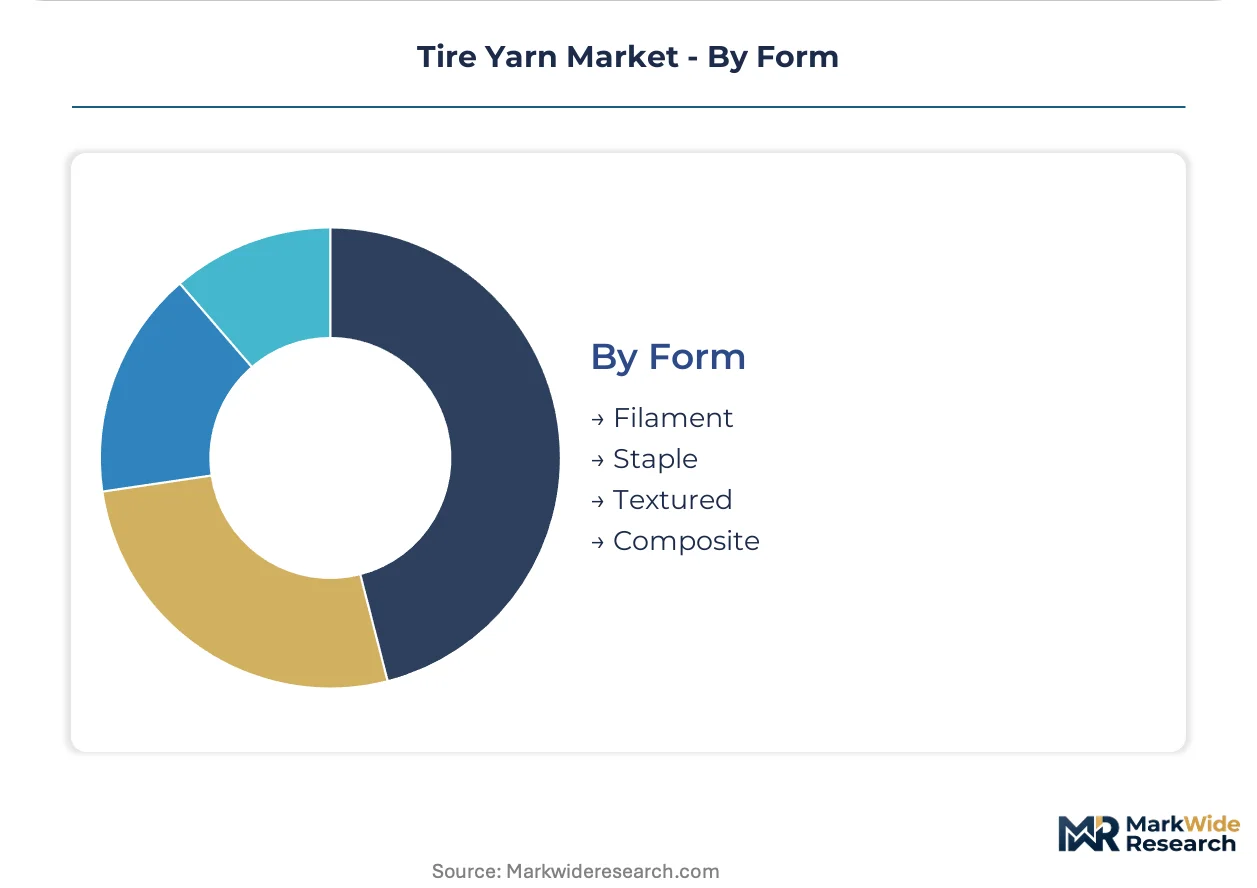
Form:
Processing stage and structural configuration segment this category from raw filament to engineered composite cords ready for rubber calendering.
- Filament:Continuous high-tenacity synthetic filaments serve as feedstock for downstream cord twisting and adhesion treatment operations.
- Staple:Short-cut fiber lengths support non-woven reinforcement applications and specialized tire component manufacturing.
- Textured:Bulked filament yarns enhance rubber penetration and adhesion in specific tire construction zones.
- Composite:Pre-engineered cord structures combining multiple fiber types with integrated adhesion treatment are displacing in-house cord manufacturing at smaller tire plants.
Most processing volume flows through Filament. Value capture is shifting fastest toward Composite as modular bundling contracts expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tire yarn manufacturing traces its industrial origins to German chemical engineering breakthroughs in high-tenacity synthetic fibers during the mid-twentieth century. Early polymer spinning expertise concentrated in the Rhine-Ruhr corridor before dispersing to Asian production centers. Contemporary supply chains reflect this heritage through specialized technical knowledge clusters.
China
Radial tire capacity expansion by domestic manufacturers absorbs polyester and nylon yarn volumes that previously served export markets. MIIT industrial guidelines impose technical specifications on tire cord supply chains that align with GB standards. Shandong Province hosts the densest concentration of tire manufacturing plants, where yarn producers co-locate treatment facilities to reduce logistics costs.
Germany
Automotive OEM lightweighting mandates drive specification intensity for high-tenacity polyester grades in premium passenger tire lines. REACH chemical compliance and the F-Gas Regulation tighten material thresholds for cord treatment processes. The Rhine-Ruhr industrial corridor retains specialized polymer spinning expertise, though producers face capital expenditure pressure for cooling system retrofits.
United States
Long-haul trucking fleet consolidation through tire-as-a-service contracts compresses yarn supplier influence over reinforcement specifications. EPA emissions standards for fiber production facilities elevate compliance investment for domestic cord manufacturers. The Southeast manufacturing belt attracts treatment facility investments due to proximity to tire plants and port access for raw material imports.
India
Domestic tire manufacturers expand radial capacity with yarn specifications aligned to BIS technical standards. CDSCO oversight of chemical migration in manufacturing environments parallels regulatory frameworks in export destination markets. Gujarat and Tamil Nadu industrial corridors concentrate new cord treatment investments serving both domestic OEM supply and aftermarket replacement demand.
Japan
Premium passenger tire makers qualify hybrid cord architectures combining recycled-content polyester with virgin high-tenacity filaments. METI industrial guidelines and JIS standards shape material qualification protocols for domestic supply chains. The Nagoya-Toyota industrial zone maintains close technical integration between yarn suppliers and tire manufacturers for platform-level supply agreements.
Tire Yarn Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specialization and adhesion treatment integration. The market structure consolidates around integrated polymer producers with captive raw material supply and specialized cord treatment specialists serving niche thermal performance segments. Three archetypes dominate: upstream-integrated chemical conglomerates with polymer spinning assets, standalone high-tenacity yarn specialists, and composite cord engineers delivering pre-treated reinforcement packages. Capacity expansion and modular bundling contracts constitute the primary competitive vectors, with producers securing multi-year supply agreements through technical qualification partnerships.
Within the integrated chemical tier, Invista and Hyosung exemplify upstream-anchored positioning through polymer production assets. Kolon Industries occupies the specialized performance tier where heat-resistant reinforcement commands differentiated margins. These three anchors illustrate how competitive positioning stratifies between scale-driven commodity supply and technical-specialty premium capture.
| Leading Market Players |
|---|
| Invista |
| Hyosung |
| Toray Industries |
| Teijin |
| Kolon Industries |
| Indorama Ventures |
| SRF Limited |
| Kordsa Teknik Tekstil |
| Asahi Kasei |
| Others |
Value Network & Pricing Analysis
Caprolactam feedstock costs cascade through nylon tire yarn pricing tiers from integrated producers like Hyosung to non-integrated cord treatment specialists, compressing margins at each handoff while REACH compliance investments widen spreads between European-qualified and standard-grade supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aramid thermal-performance grades from commodity polyester and entry-level nylon specifications. Price differentiation hinges on REACH adhesion certification status and captive caprolactam integration. Cost compression in standard polyester tiers is intensifying because Chinese radial capacity expansion is absorbing regional supply. Fleet procurement platforms exhibit lowest price sensitivity due to performance guarantees, while aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns that feed tire manufacturing clusters. Raw material flows draw from benzene derivative networks, high-tenacity polymer spinning assets, and brass-coated wire drawing facilities. Single-source vulnerability concentrates in European adhesion treatment chemicals facing ECHA authorization delays. Distribution runs through modular bundling contracts that disaggregate standalone yarn procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
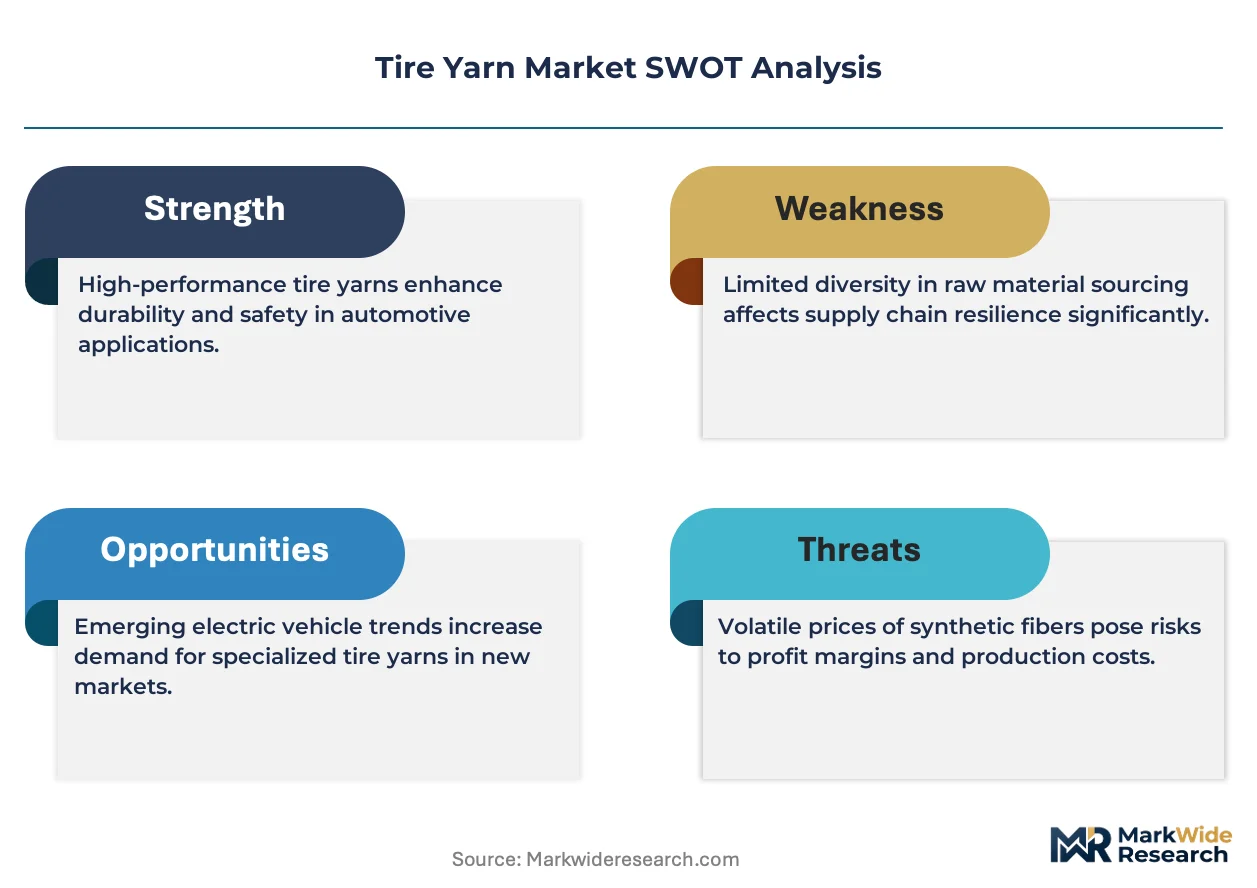
Tire yarn margins expand through two vectors: captive caprolactam supply secures cost-down capture in nylon grades, while aramid thermal-performance positioning commands premium extraction in motorsport and aircraft segments.
For Market Incumbents: Deploy modular bundling contracts to lock in multi-year supply relationships before fleet procurement platforms consolidate specification influence. Anchor cost leadership through backward integration into caprolactam or polymer spinning assets. Counter REACH authorization delays by accelerating water-based adhesion system qualification with European tire makers. For New Entrants and Emerging Players: Tire-as-a-service fleet management platforms represent the most penetrable channel for direct specification access outside incumbent mill relationships. Target India's radial expansion corridor where BIS-aligned yarn specifications are still crystallizing. Pursue composite cord engineering partnerships that displace in-house treatment capacity at smaller tire plants. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone cord treatment specialists lack balance sheet capacity for F-Gas Regulation cooling retrofits. Five-to-ten-year viability favors integrated polymer producers with upstream raw material control and technical qualification depth. Watch ECHA substance evaluation timelines for legacy adhesion chemistries as inflection signals for modified cord treatment market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Captive benzene derivative supply anchors margin predictability against feedstock volatility. |
| Water-Based Adhesion System Qualification | REACH-compliant bonding chemistry opens European tire maker procurement pathways. |
| Modular Bundling Contract Expansion | Integrated reinforcement packages disaggregate standalone yarn spot-market procurement. |
| Aramid Thermal-Performance Certification | Motorsport and aircraft tire segments yield premium positioning unattainable by commodity synthetics. |
| F-Gas Cooling Retrofit Completion | Alternative refrigeration chemistry compliance preserves European supply qualification status. |
Research Methodology
Multiple input streams — procurement directors at tire manufacturers, polymer spinning technical leads, regulatory affairs specialists, and distribution channel managers — were reconciled against customs trade data, MIIT industrial guideline filings, ECHA substance registration databases, and SEC disclosures from listed chemical conglomerates. Bottom-up volume modeling and top-down value triangulation cross-validated segment-level outputs.
Data-stream reconciliation across product type, application duty cycle, end-user contract structure, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves and capacity absorption rates. Forecast inputs incorporated radialization penetration curves and REACH authorization timeline scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to caprolactam price volatility, ECHA evaluation delays, and carbon accounting protocol divergence between jurisdictions. Outputs reflect documented assumptions about radial tire conversion rates and fleet procurement platform consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market