
 Knitted Fabric Market | 2026-2036
Knitted Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Knitted Fabric Market Intelligence
Modular sourcing of knit components is hardening as buyers decouple greige fabric procurement from finishing services. Welspun India Limited leverages its integrated spinning-to-fabric infrastructure to control cotton knit supply chains. Teijin Frontier anchors technical polyester knit development for athletic and industrial applications. Vardhman Textiles Limited dominates India's cotton knit segment through backward integration into yarn production.
Knitted fabric consists of interlocking yarn loops formed by needles, typically measured in grams per square meter and stitch density, engineered for elasticity, breathability, and shape recovery in garments and technical textiles. Jersey knits lead volume consumption across basic apparel categories, while fleece commands premium positioning in cold-weather sportswear and activewear layers. Nylon knit structures are gaining traction in compression garments and technical sportswear where dimensional stability and recovery properties outperform standard polyester constructions.
EPA guidelines on textile effluent discharge constrain wet processing operations in the United States, while REACH and the EU Green Deal restrict hazardous chemical inputs across European supply chains. OEKO-TEX and GOTS certification requirements are reshaping buyer qualification criteria for knitted fabric suppliers seeking access to regulated retail channels. Stakeholders must track evolving chemical compliance thresholds and energy transition mandates to sustain market access across major demand centers.
Market Dynamics
Technical performance requirements from sportswear and medical textile buyers are compressing traditional commodity knit margins while rewarding engineered constructions with verified stretch recovery and moisture management.
Growth Catalysts
- REACH chemical compliance mandates:European retailers now require OEKO-TEX or GOTS certification for knit fabric procurement, filtering out unqualified suppliers and concentrating volume among certified mills.
- Bangladesh ready-made garment export expansion:Dhaka-Chittagong industrial clusters consume knit fabric at scale as global brands relocate basic apparel sourcing from China.
- Seamless knitting technology:Whole-garment production eliminates cutting waste and sewing labor, attracting athletic wear brands seeking construction efficiency.
Market Restraints
- Cotton price volatility:Weather-driven supply fluctuations in Texas and India directly compress margins for unhedged spinners lacking polyester blend flexibility.
- Wet processing concentration in Tamil Nadu and Gujarat:Dyeing and finishing capacity bottlenecks create lead time risk for buyers requiring quick-turn replenishment.
- Mechanical stretch limitations in natural fibers:Cotton and wool knits require elastane blends to match polyester's inherent recovery, adding cost and complicating recycling streams.
Strategic Opportunities
- Vietnam garment manufacturing expansion:Rising FDI in Ho Chi Minh City and Hanoi apparel parks creates demand for regional knit fabric supply currently met by imports.
- EU Green Deal carbon border adjustments:Early investment in renewable-powered knitting and dyeing operations secures preferential access to European retail channels.
- Bio-based elastane integration:Fermentation-derived spandex alternatives paired with recycled polyester knits open premium positioning in sustainability-focused athletic lines.
Industry Challenges
- GOTS and OEKO-TEX certification backlog:Testing laboratory capacity constraints delay supplier qualification timelines, freezing out new entrants during peak demand windows.
- Digital knitting machine technician scarcity:Programming complex stitch architectures for 3D seamless constructions requires specialized CAD skills concentrated in European and Japanese machinery vendors.
- Legacy ERP integration with traceability platforms:Batch-level fiber origin tracking demanded by brands conflicts with decades-old inventory management systems at established mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knitted Fabric Market |
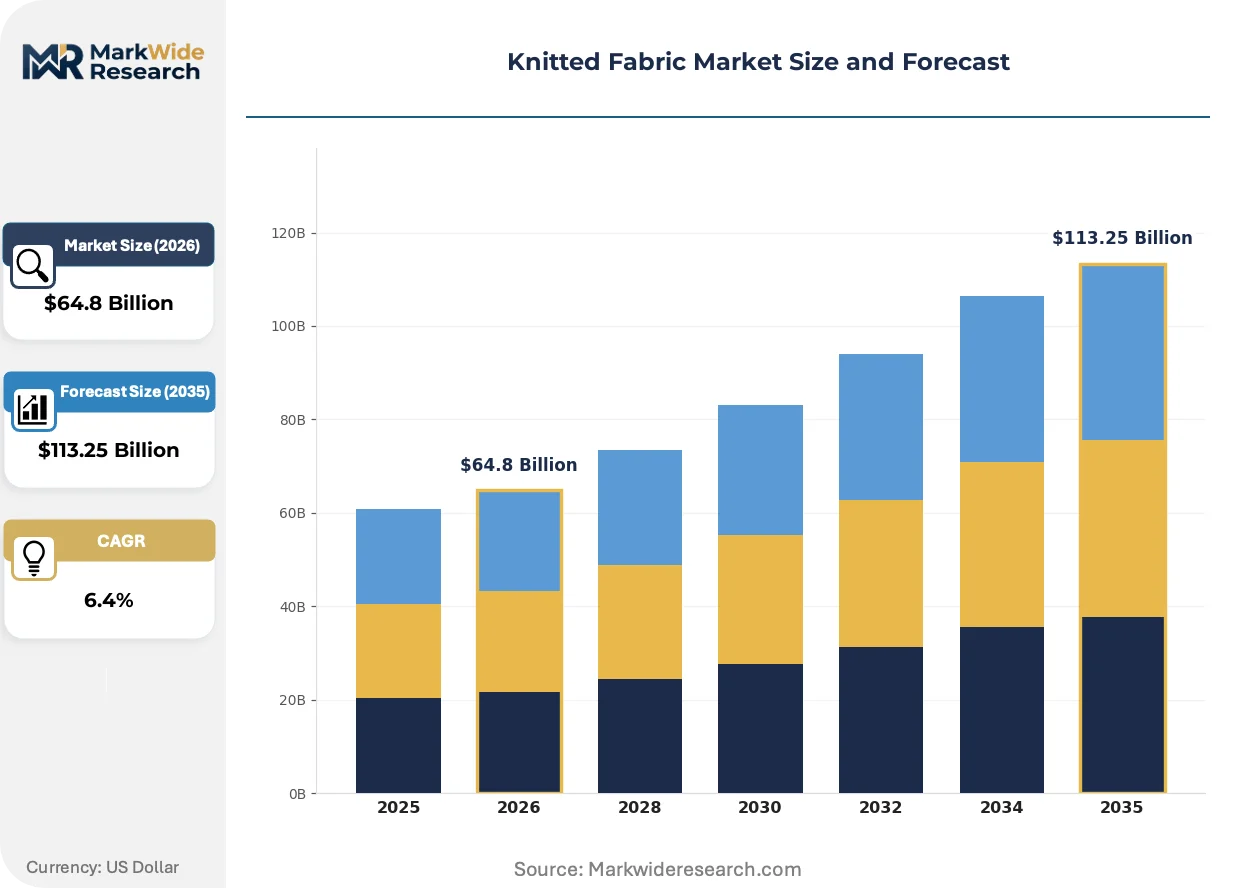
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $113.25 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jersey, Rib, Interlock, Fleece Material: Cotton, Polyester, Nylon, Wool Application: Apparel, Home Textiles, Sportswear, Fashion End User: Manufacturers, Retailers, Wholesalers, Designers |
| Companies Covered | Welspun India Limited, Teijin Frontier, Toray Industries, Nilit Ltd., Koninklijke Ten Cate, Vardhman Textiles Limited, Unifi, Shandong Ruyi Technology Group, Arvind Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knitted Fabric Market Strategic Shifts & Innovations
Digital manufacturing interfaces and polymer science advances are compressing the gap between laboratory formulation and mill-floor production, collapsing development cycles for functional knit constructions.
Recycled polyester filament yarns with verified GRS chain of custody are absorbing share in mid-tier athletic base layers and outerwear linings. Brands including those supplying marathon and trail running segments specify minimum recycled content thresholds. This absorption is compressing virgin polyester knit pricing power and forcing petrochemical-dependent mills to reconfigure polymer sourcing or retreat to commodity segments.
EPA effluent guidelines for textile wet processing are tightening discharge limits for nitrogen and color in North Carolina and California knitting clusters. Mills face capital-intensive biological treatment upgrades or geographic relocation. Smaller finishers in Los Angeles County are consolidating or exiting as compliance costs exceed revenue per pound processed.
Modular sourcing separates greige knit procurement from specialized finishing services, with brands qualifying multiple independent dye houses rather than relying on integrated mills. Bangladeshi garment exporters increasingly buy unfinished fabric from India and commission local or regional finishing. This disaggregation is most visible in Dhaka's export processing zones where lead time flexibility outweighs unit cost minimization.
Knitted Fabric Market Segmentation
Knitted fabric procurement increasingly filters through certification requirements that vary sharply by segment, with OEKO-TEX and GOTS thresholds determining mill qualification for premium channels. Buyers now map segment-specific compliance burdens onto supplier scorecards, concentrating volume among certified producers while excluding uncertified competitors from regulated retail access.
Product Type:
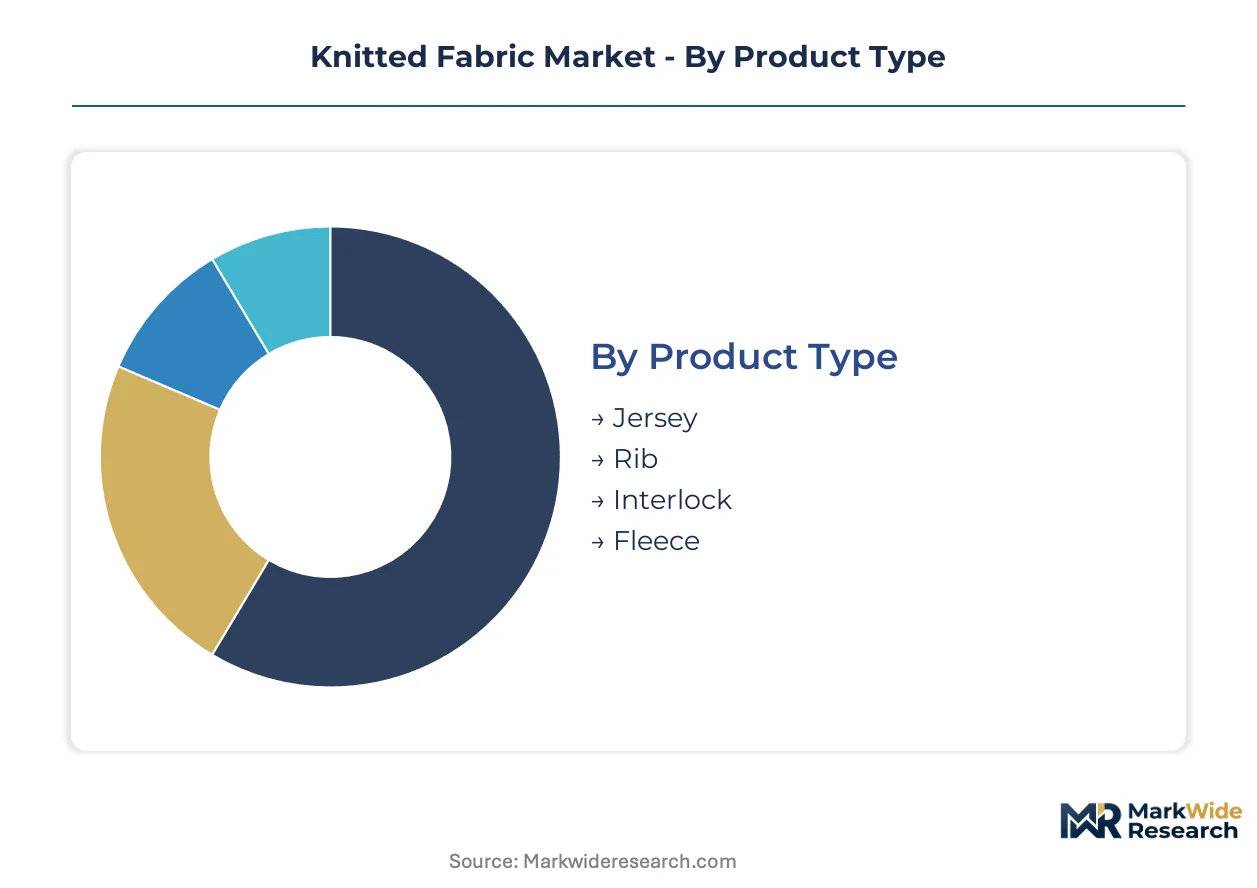
Jersey and fleece carry the heaviest certification loads for European retail entry, while rib and interlock face lighter documentation requirements in Asian domestic channels.
- Jersey:Single-knit construction with distinct face and reverse sides, typically 120-200 GSM for base layer applications. Dhaka-Chittagong garment clusters consume jersey at scale for basic T-shirt production, with REACH-compliant dyeing now mandatory for EU-bound exports.
- Fleece:Brushed or sheared surface creates insulating loft for cold-weather applications. Premium athletic brands in Germany and France specify GRS-certified recycled polyester fleece for outerwear programs, compressing margins for virgin-fiber producers.
- Rib:Vertical wale structure provides stretch recovery for cuffs and collars. Tamil Nadu mills dominate rib production for Indian domestic apparel manufacturers.
- Interlock:Double-knit face construction yields stable, reversible fabric for formal casualwear. Bangladesh garment exporters favor interlock for polo shirt manufacturing.
Jersey sits at the top of the volume ranking, with fleece climbing the fastest.
Material:
Raw material selection determines chemical compliance pathways, with natural fibers triggering pesticide residue testing and synthetics demanding microplastic discharge documentation.
- Cotton:Cellulosic staple fiber requiring ginning, spinning, and knitting preparation. Texas and Gujarat weather volatility compresses unhedged spinner margins, while BCI and GOTS certifications open premium European channels.
- Polyester:Petrochemical-derived filament or staple with inherent stretch recovery. Recycled PET variants with verified GRS chain of custody are displacing virgin polymer in mid-tier athletic base layers.
- Nylon:Polyamide polymer delivering superior abrasion resistance and dimensional stability. Compression garment manufacturers in Italy and Japan specify nylon knit for medical and athletic applications.
- Wool:Protein fiber from sheep fleece requiring scouring and carbonizing before knitting. Merino wool knits command premium positioning in outdoor and base layer categories.
Cotton dominates absolute volume, though recycled polyester is expanding most quickly.
Application:
End-use application dictates performance specification intensity, with sportswear demanding verified stretch recovery and moisture management that commodity apparel segments rarely require.
- Sportswear:Technical performance category requiring engineered constructions with verified wicking and compression properties. Marathon and trail running brands specify minimum recycled content thresholds, forcing polymer reconfiguration at petrochemical-dependent mills.
- Apparel:General garment category spanning basic T-shirts through formal casualwear. Bangladesh ready-made garment export expansion concentrates basic apparel sourcing in Dhaka-Chittagong clusters.
- Home Textiles:Domestic furnishing applications including blankets, throws, and upholstery. Indian mills supply cotton knits for US and European home textile distributors.
- Fashion:Trend-driven seasonal category with shorter lead time requirements. Los Angeles County finishers serve fast-fashion brands with quick-turn dyeing and finishing.
Apparel maintains volume leadership, while sportswear shows the steepest expansion trajectory.
End User:
Buyer type determines procurement sophistication, with integrated manufacturers demanding batch-level traceability that wholesalers rarely specify.
- Manufacturers:Vertically integrated or assembly-oriented producers requiring greige fabric with finishing flexibility. Modular sourcing separates knit procurement from dyeing services, with brands qualifying multiple independent finishers.
- Retailers:Branded channel operators with direct consumer relationships and strict certification mandates. European retailers now require OEKO-TEX or GOTS documentation for knit fabric procurement.
- Wholesalers:Intermediary distributors serving smaller garment producers without direct mill relationships. Indian cotton knit wholesalers supply Bangladeshi garment exporters.
- Designers:Small-batch creative studios requiring quick-turn sampling and flexible minimum order quantities. Digital knitting technology enables whole-garment production for designer-led athletic wear programs.
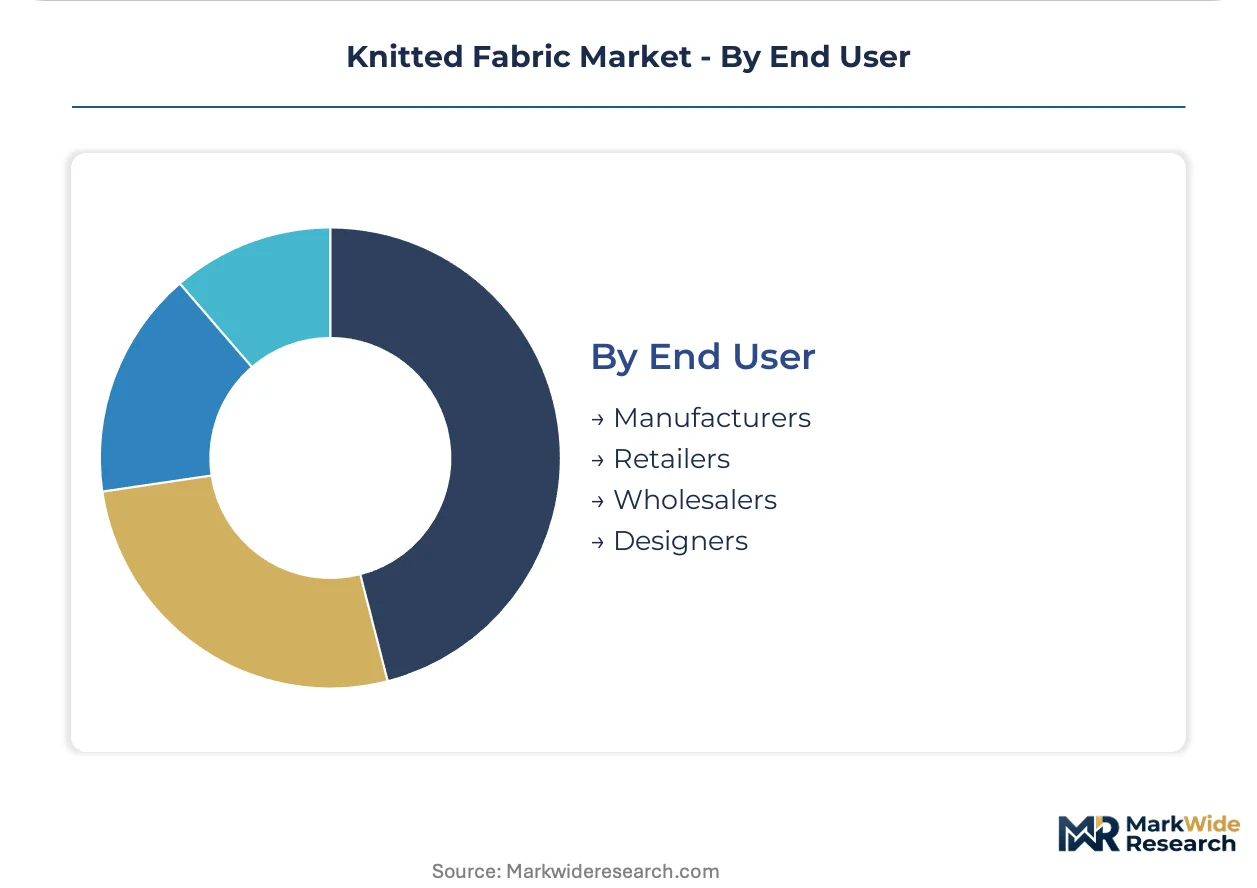
Manufacturers command the largest volume share, with retailers gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Knitted fabric manufacturing originated in the industrial textile centers of England and Germany during the nineteenth century, with mechanical knitting frames scaling wool and cotton production for emerging ready-to-wear markets. Today, production geography reflects a century-long migration toward cotton-growing regions and labor-intensive garment assembly zones.
United States
Technical sportswear brands in Oregon and Colorado drive demand for moisture-wicking polyester knits with verified recycled content. EPA effluent guidelines constrain wet processing in North Carolina's Piedmont Triad, forcing biological treatment upgrades at legacy dye houses. Los Angeles County finishers serve quick-turn fashion clients while consolidating under compliance cost pressure.
Germany
Marathon and outdoor brands in Bavaria specify GRS-certified recycled polyester fleece for premium outerwear programs. REACH chemical compliance mandates filter supplier qualification, concentrating procurement among OEKO-TEX certified mills. The Stuttgart industrial corridor hosts specialized knitting machinery vendors supplying seamless production technology.
China
GB standards evolution tightens chemical safety documentation for textile exports to European and North American retail channels. The Yangtze River Delta knitting cluster around Shaoxing and Ningbo supplies greige fabric to Bangladesh garment exporters. Zhejiang province mills face dual carbon goals pressure to transition dyeing operations toward renewable energy.
India
Tamil Nadu and Gujarat spinning mills supply cotton knit greige to Dhaka garment factories through modular sourcing arrangements. BCI and GOTS certifications open premium European retail channels for certified producers. Coimbatore's knitting cluster dominates rib and interlock production for domestic apparel manufacturers.
Bangladesh
Dhaka-Chittagong export processing zones consume knit fabric at scale as global brands relocate basic apparel sourcing from China. Local garment exporters increasingly commission regional finishing rather than relying on integrated mill supply. Ready-made garment export expansion concentrates knit fabric demand in industrial clusters around Gazipur and Narayanganj.
Knitted Fabric Market Key Industry Players
The competitive structure tilts toward integrated spinners with captive yarn supply and technical specialists commanding premium positioning in performance segments. Market concentration remains moderate, with volume leadership distributed across South Asian cotton knit producers and East Asian synthetic fiber specialists. Three archetypes dominate: backward-integrated cotton spinners, petrochemical-linked polyester filament producers, and seamless knitting technology licensors. Capacity expansion in Vietnam and Bangladesh accompanies strategic partnerships between machinery vendors and regional fabricators.
Among India-based integrated producers, Welspun India Limited and Vardhman Textiles Limited exemplify the backward-integrated archetype controlling cotton supply chains from fiber through fabric. Teijin Frontier anchors technical polyester knit development, representing the synthetic performance tier. These three occupy positions spanning commodity volume and engineered construction segments.
| Leading Market Players |
|---|
| Welspun India Limited |
| Teijin Frontier |
| Toray Industries |
| Nilit Ltd. |
| Koninklijke Ten Cate |
| Vardhman Textiles Limited |
| Unifi |
| Shandong Ruyi Technology Group |
| Arvind Limited |
| Others |
Cost & Logistics Intelligence
Cotton yarn cost volatility in Texas and Gujarat propagates through three distinct pricing tiers before reaching garment exporters in Bangladesh and Vietnam. REACH-compliant dyeing commands premium positioning in European channels while uncertified commodity knits compete on unit cost in Asian domestic markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified technical knits from commodity jersey and unbranded greige fabric. Price differentiation hinges on certification grade and volume scale, with marathon and outdoor brands paying premiums for GRS-verified recycled content. Cost compression in commodity cotton knits is intensifying because weather-driven fiber volatility squeezes unhedged spinner margins. Small Bangladeshi garment exporters exhibit highest price sensitivity, while integrated European sportswear brands prioritize performance specifications over unit cost.
Supply Chain Analysis
Dual-sourcing requirements now mandate that buyers qualify independent finishers in Tamil Nadu, Gujarat, and Vietnam alongside primary greige suppliers in India and China. Raw material supply draws from Texas cotton gins, Zhejiang polyester filament plants, and South Korean nylon polymer facilities. Single-source vulnerability concentrates in Shaoxing dyeing clusters where wet processing bottlenecks create lead time risk. Distribution runs through Dhaka-Chittagong export processing zones for garment assembly, with modular sourcing decoupling fabric procurement from finishing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The knitted fabric market functions as a stable compounder, with technical performance requirements from sportswear brands driving steady value migration toward engineered constructions.
For Market Incumbents: Extend certification coverage into bio-based elastane and fermentation-derived spandex alternatives to preempt sustainability-focused athletic lines. Deepen backward integration into captive yarn production in Gujarat and Tamil Nadu to defend margin position against cotton price volatility. Prioritize seamless knitting machinery partnerships with European and Japanese vendors to lock in construction efficiency advantages. For New Entrants and Emerging Players: Direct-to-garment-exporter digital platforms offer the most penetrable route into Bangladesh's ready-made garment clusters, where modular sourcing creates entry points for specialized finishers. Target Vietnam's Ho Chi Minh City and Hanoi apparel parks with quick-turn rib and interlock supply, as rising FDI outstrips regional knit fabric capacity. Lead with OEKO-TEX pre-certification to bypass testing laboratory backlogs that freeze out competitors during peak demand windows. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale integrated cotton spinners because certification backlogs and ERP traceability requirements favor consolidated platforms with compliance infrastructure already deployed. The 5-10 year viability window rewards archetypes with backward integration into yarn and forward relationships with Dhaka garment exporters. Watch for inflection when EU Green Deal carbon border adjustments trigger preferential channel access for renewable-powered mills.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yarn Production | Gujarat and Tamil Nadu spinners secure cotton supply chains against weather-driven volatility. |
| Seamless Knitting Technology Licensing | Whole-garment production eliminates cutting waste for marathon and trail running brands. |
| GRS-Certified Recycled Polyester Scale-Up | Verified chain of custody opens premium Bavarian and Colorado sportswear channels. |
| Modular Sourcing Partnership Expansion | Independent dye house qualification in Vietnam reduces lead time risk for quick-turn replenishment. |
| Bio-Based Elastane R&D Investment | Fermentation-derived spandex alternatives pair with recycled knits for sustainability positioning. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with spinning mill executives, garment exporter procurement leads, dye house operations managers, and sportswear brand sustainability directors with secondary validation. Trade data from Bangladesh Export Processing Bureau, India Cotton Association crop reports, Zhejiang textile customs records, and OEKO-TEX certification registries anchored volume estimates. Bottom-up mill capacity assessments and top-down apparel production forecasts were triangulated against import-export flows.
Comparable historical periods across the analysis window anchored growth trajectory assumptions for the projection horizon. Segmentation modeling incorporated product type, material chemistry, end-use application intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion pipelines. Forecast inputs included cotton futures volatility patterns, REACH chemical threshold evolution, and seamless knitting machinery deployment rates.
Cotton weather shocks, REACH compliance timeline acceleration, and Bangladesh garment export quota shifts are the dominant revision risks to the outlook. Forecasts reflect documented assumptions about fiber substitution elasticity and certification adoption curves. Deviation in EU Green Deal implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market