
 Indonesia Textile Manufacturing Market | 2026-2036
Indonesia Textile Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Textile Manufacturing Market Foresight
Market Context with Strategic Players
Skilled loom operators and dye technicians is redrawing competitive boundaries across Java's textile belt. PT. Sri Rejeki Isman Tbk (Sritex) leverages vertical integration from yarn spinning to finished fabric, sustaining cost advantages in uniform and workwear contracts. PT. Pan Brothers Tbk anchors export volume through long-term supply agreements with international apparel brands, while PT. Indorama Synthetics Tbk dominates polyester fiber production with captive petrochemical feedstock.
Technical Definition and Structural Segments
Indonesia textile manufacturing encompasses the mechanical and chemical transformation of natural and synthetic fibers into woven, knitted, non-woven, and technical textile products through spinning, weaving, dyeing, and finishing processes, with finished goods serving apparel, home furnishing, industrial, and automotive end-uses. Woven fabrics occupy the largest production share due to established shuttle and rapier loom infrastructure, while technical textiles represent the fastest-expanding margin pool driven by geotextile and filtration demand from infrastructure projects. Cotton and polyester together structure the material base, though polyester gains share as domestic PTA-MEG capacity expands under petrochemical co-location strategies.
Regulatory Frame and Forward-Looking Close
BIS standards govern import-competing product quality, while the Ministry of Industry's Making Indonesia 4.0 policy channels tax incentives toward digital weaving and automated dyeing upgrades, and the national textile association API enforces voluntary sustainability protocols for export market access. Compliance with these layered requirements shapes capital allocation toward certified facilities and excludes smaller unregistered dye houses from premium buyer qualification lists. Stakeholders must weigh workforce retraining costs against automation subsidies when selecting facility upgrade sequencing.
Market Dynamics
Automation subsidies under Making Indonesia 4.0 are compressing the wage advantage that historically anchored Java's weaving clusters, forcing mills to choose between workforce retraining or facility consolidation.
Growth Catalysts
- Export qualification protocols:API sustainability certification opens access to EU and US apparel brand supplier lists, redirecting investment toward wastewater treatment and chemical management systems.
- Polyester feedstock co-location:Captive PTA-MEG capacity at Merak and Cilegon reduces import dependency for synthetic fiber producers.
- Technical textile infrastructure:Geotextile demand from Trans-Java toll road and new capital city projects absorbs high-tenacity woven output.
Market Restraints
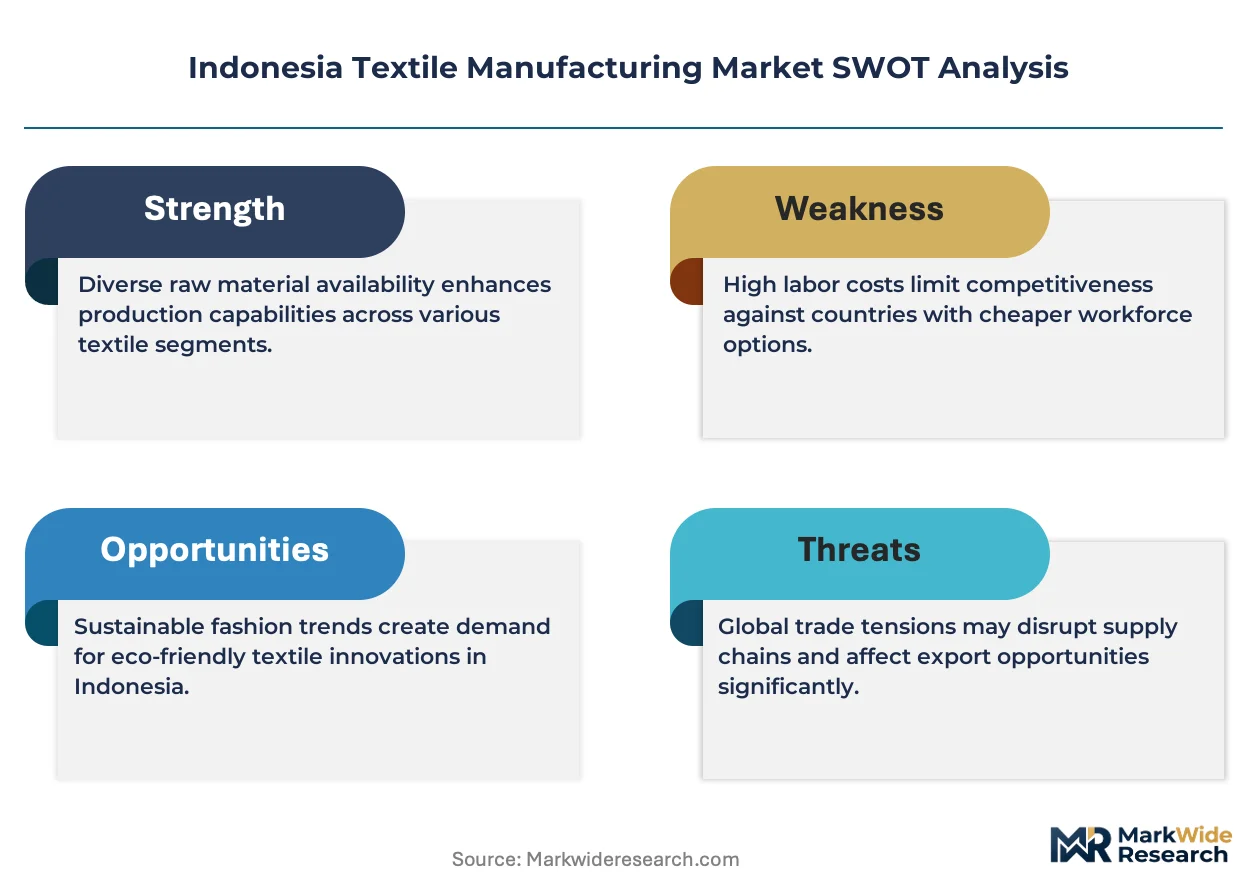
- Cotton import concentration:Raw cotton arrives through Tanjung Priok and Surabaya ports, exposing spinners to container cost volatility and rupiah-dollar exchange pressure.
- Small-batch dye house fragmentation:Unregistered wet processing units in Bandung and Solo operate below BIS effluent thresholds, creating price competition that erodes compliant facility margins.
- Power cost structure:Industrial electricity tariffs from PLN exceed Vietnamese and Bangladeshi benchmarks, compressing energy-intensive weaving operations.
Strategic Opportunities
- Eastern Indonesia expansion:Makassar and Sulawesi offer lower labor costs and underutilized port capacity for export-oriented garment sewing.
- Automotive textile integration:Seat fabric and airbag substrate specifications from domestic vehicle assembly plants create technical textile pull.
- Digital weaving incentive stack:Ministry of Industry tax holidays for rapier-to-jacquard upgrades accelerate pattern-change capability.
Industry Challenges
- Jacquard programming skill scarcity:Automated loom operation requires CAD pattern design competency that vocational institutes have not scaled to match installation rates.
- Zero Discharge certification timeline:ZDHC compliance for European brand supplier qualification demands 18-24 month chemical inventory overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Textile Manufacturing Market |
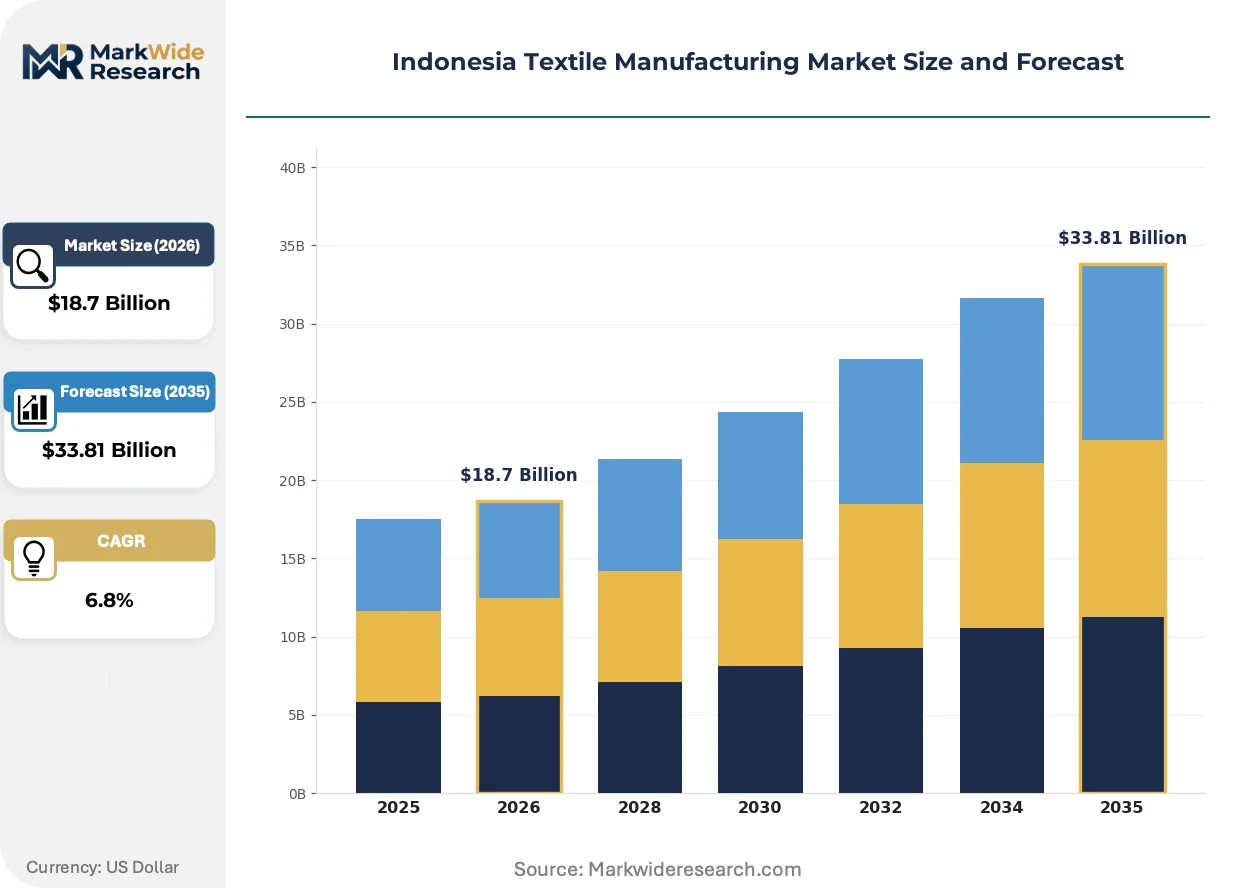
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Knitted Fabrics, Non-Woven Fabrics, Technical Textiles End User: Apparel, Home Textiles, Industrial, Automotive Components Material: Cotton, Polyester, Nylon, Wool Manufacturing Process: Spinning, Weaving, Dyeing, Finishing |
| Companies Covered | PT. Pan Brothers Tbk, PT. Danantara Textiles, PT. Sri Rejeki Isman Tbk (Sritex), PT. Indo Acfic Tbk, PT. Poly Prima Indonesia Tbk, PT. Indorama Synthetics Tbk, PT. Gajah Tunggal Tbk, PT. Tifico Fiber Indonesia Tbk, PT. Asia Pacific Fibers Tbk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Textile Manufacturing Market Shifts & Advancements
Digitalization of production workflows and chemical management is compressing batch turnaround times while raising the capital threshold for market participation.
Waterless dyeing systems using supercritical CO2 are miniaturizing from pilot scale to production modules. Denim and knitwear exporters in Bandung are installing 50-100 kg capacity units to bypass wastewater treatment bottlenecks. This technology is miniaturizing the minimum viable scale for compliant wet processing, allowing smaller mills to retain brand supplier status without central effluent facility investment.
Making Indonesia 4.0 tax incentives now cover automated fabric inspection and AI-driven loom monitoring. The Ministry of Industry requires domestic machinery sourcing quotas for subsidy eligibility, steering procurement toward local integrators. Warp knitting and technical weaving segments are responding fastest due to higher value-per-meter and faster payback on quality control automation.
Brand supplier qualification is consolidating procurement volumes among certified tier-one mills. International apparel labels are reducing their Indonesian vendor base from 15-20 suppliers to 5-7 strategic partners with full vertical coverage. This concentration is most visible in Surabaya, where uniform and workwear contracts now flow exclusively to facilities with in-house spinning, weaving, and cut-make-trim capability.
Indonesia Textile Manufacturing Market Segmentation
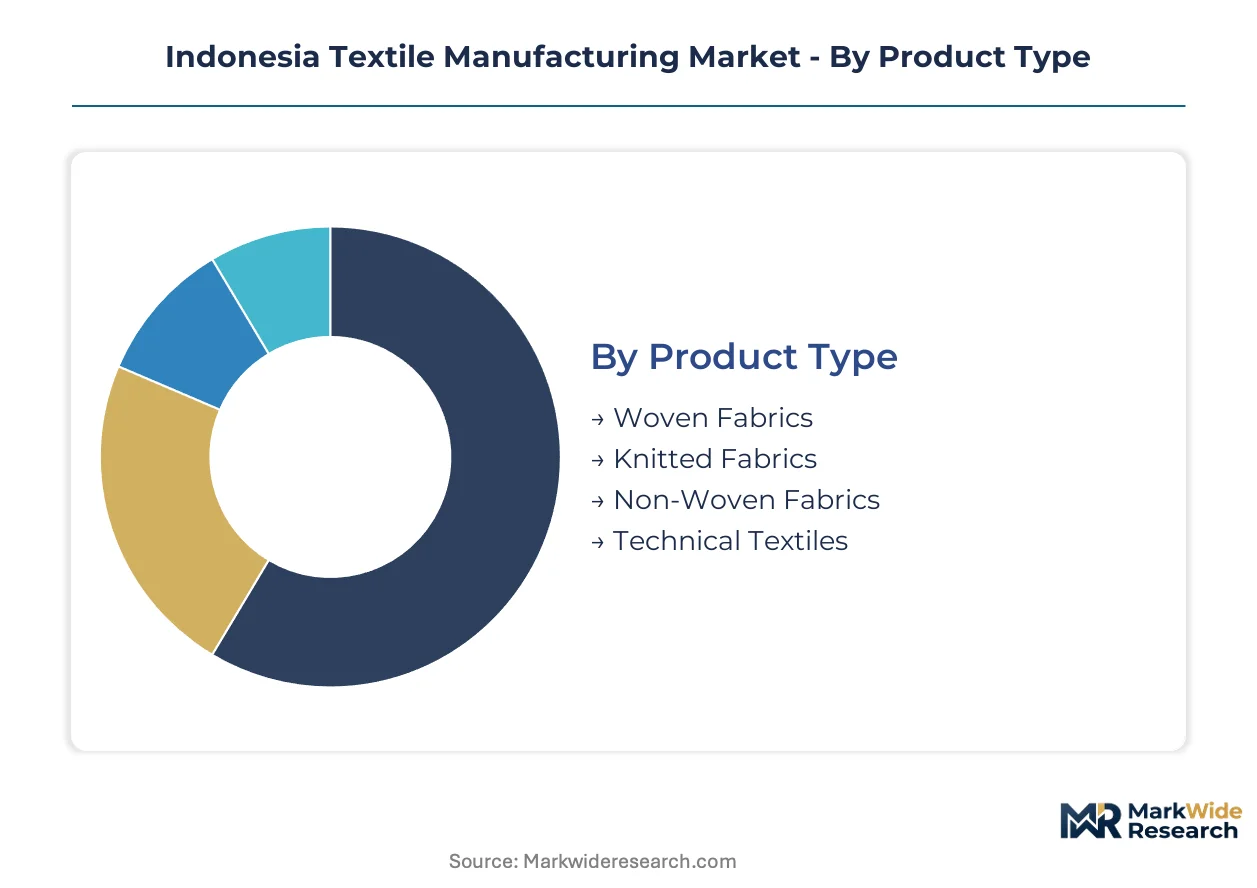
Segmentation in Indonesia's textile manufacturing reveals how production capabilities align with distinct demand channels. Understanding these divisions exposes where automation investments and certification requirements create divergent margin structures across the value chain.
Product Type:
Domestic consumption absorbs woven and knitted output for apparel and home textiles, while technical textiles serve export-led infrastructure and automotive contracts.
- Woven Fabrics:Shuttle and rapier loom infrastructure across Java produces uniform cloth, denim, and shirting materials. Bandung and Surabaya clusters supply domestic garment cutters and Southeast Asian export markets under long-term supply agreements.
- Technical Textiles:High-tenacity woven geotextiles and filtration media absorb capacity from upgraded jacquard installations. Trans-Java toll road expansion and new capital city projects in East Kalimantan pull output from Surabaya-based producers with API sustainability certification.
- Knitted Fabrics:Circular and flatbed knitting serves t-shirt and activewear producers in Greater Jakarta and Bali garment zones.
- Non-Woven Fabrics:Spunbond and needle-punch lines produce hygiene and filtration substrates for domestic medical and packaging end-uses.
Woven fabrics hold the largest share; momentum sits with technical textiles as infrastructure spending accelerates.
End User:
Cost tier stratification separates commodity apparel from premium technical applications requiring ZDHC compliance and automotive specification adherence.
- Apparel:Cut-make-trim contractors in Greater Jakarta and Central Java consume the majority of domestic woven and knitted output. International brand supplier qualification demands are consolidating procurement volumes among five to seven vertically integrated mills with in-house finishing capability.
- Automotive Components:Seat fabric, headliner substrates, and airbag textiles must meet OEM specification protocols from domestic vehicle assembly plants. Technical weaving investments in Karawang and Bekasi target just-in-time delivery requirements.
- Home Textiles:Bedding and curtain fabrics serve domestic retail chains and hospitality refurbishment cycles.
- Industrial:Conveyor belting, filtration, and protective equipment textiles supply mining and palm oil processing operations.
Apparel commands volume leadership; automotive components are climbing the fastest as domestic vehicle assembly expands.
Material:
Supply concentration patterns differentiate between import-dependent natural fibers and petrochemical-integrated synthetics.
- Polyester:Captive PTA-MEG production at Merak and Cilegon petrochemical complexes secures feedstock for Indorama Synthetics and integrated spinners. Synthetic fiber gains share as domestic polymer capacity expands under co-location strategies.
- Cotton:Raw lint arrives through Tanjung Priok and Surabaya ports, exposing spinners to container cost volatility and rupiah-dollar exchange pressure. Quality variation across origins complicates consistent yarn spinning.
- Nylon:Industrial filament and carpet fiber applications rely on imported caprolactam and polymer chip.
- Wool:Limited domestic demand restricts processing to specialty worsted spinning for uniform and suiting applications.
Polyester holds the largest share; technical nylon applications are gaining share fastest in automotive and industrial segments.
Manufacturing Process:
Automation maturity varies sharply across process stages, with dyeing and finishing presenting the highest compliance barriers to entry.
- Dyeing:Wet processing capacity concentrates in Bandung and Solo, where BIS effluent standards and ZDHC chemical management requirements exclude unregistered small-batch operators. Waterless supercritical CO2 systems are miniaturizing to 50-100 kg production modules.
- Weaving:Rapier-to-jacquard upgrades under Making Indonesia 4.0 tax incentives accelerate pattern-change capability. Ministry of Industry domestic machinery sourcing quotas steer procurement toward local integrators.
- Spinning:Ring and open-end rotor lines process cotton and polyester staple into yarn for captive weaving and merchant sales.
- Finishing:Calendering, coating, and functional treatment lines complete fabric specification for brand supplier qualification.
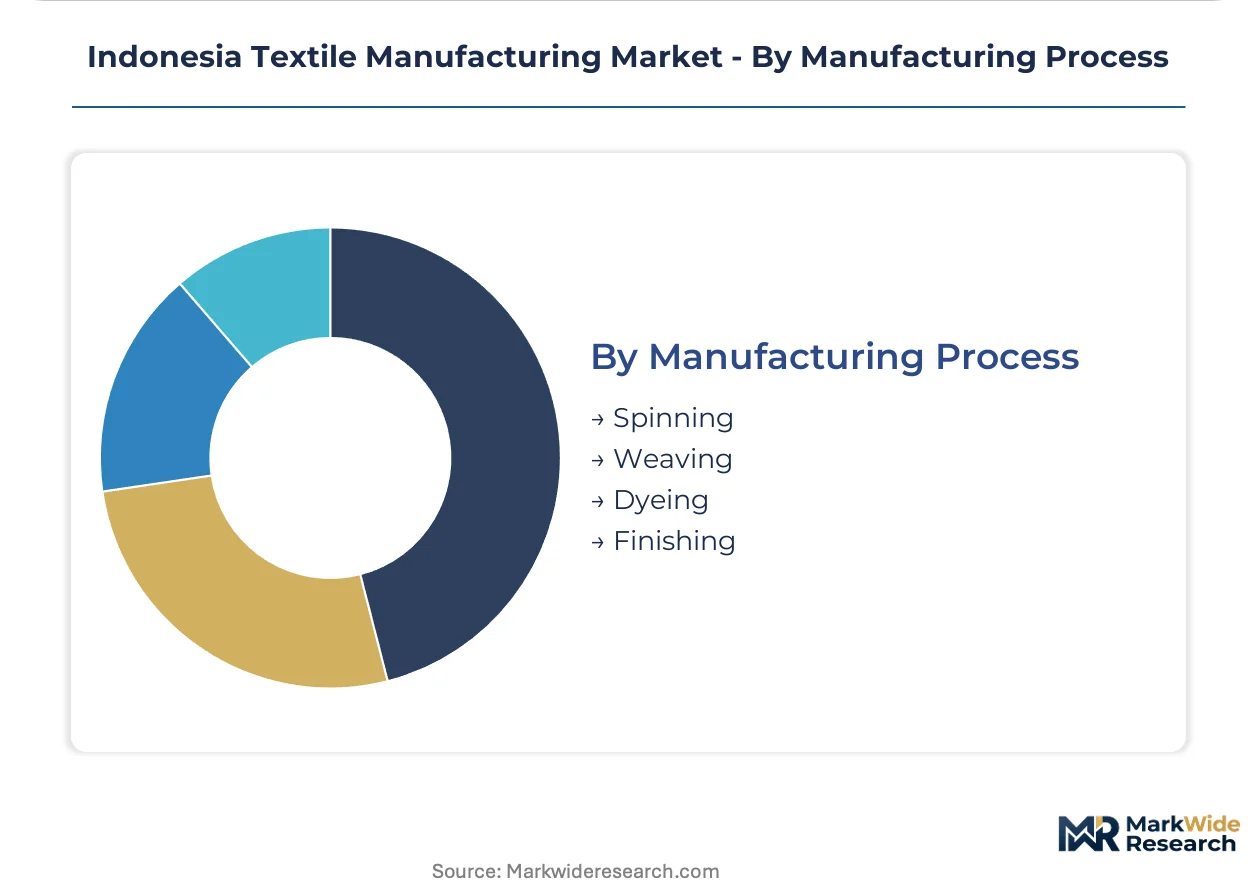
Weaving holds the largest installed capacity base; dyeing presents the steepest expansion trajectory as compliance investments reshape competitive access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java absorbs the majority of Indonesia's textile output for domestic apparel consumption, while export-oriented technical textile production concentrates in corridors serving infrastructure and automotive end-uses.
West Java
Bandung hosts the densest weaving and dyeing cluster, with rapier loom infrastructure supplying uniform cloth and denim to domestic garment cutters. BIS certification requirements under the Ministry of Industry's Making Indonesia 4.0 roadmap are accelerating automation investments in wet processing facilities. Waterless supercritical CO2 dyeing systems are miniaturizing to production modules, allowing compliant mills to retain brand supplier status.
East Java
Surabaya anchors high-tenacity woven output for geotextile contracts from Trans-Java toll road expansion. API sustainability certification opens access to EU and US apparel brand supplier lists, consolidating procurement volumes among vertically integrated facilities with in-house spinning, weaving, and finishing capability. Uniform and workwear contracts now flow exclusively to certified tier-one mills.
Greater Jakarta
Karawang and Bekasi target automotive textile integration, with technical weaving investments addressing just-in-time delivery requirements for seat fabric and airbag substrate specifications. Domestic vehicle assembly plants create pull for OEM-compliant textile producers. Industrial electricity tariffs from PLN exceed regional benchmarks, compressing energy-intensive operations.
Banten
Merak and Cilegon petrochemical complexes host captive PTA-MEG production that secures feedstock for polyester fiber spinners. Indorama Synthetics leverages this co-location strategy to reduce import dependency. Synthetic fiber gains share as domestic polymer capacity expands, displacing cotton-dependent operations exposed to rupiah-dollar exchange pressure.
Central Java
Solo's small-batch dye house concentration operates below BIS effluent thresholds, creating price competition that erodes compliant facility margins. Unregistered wet processing units face exclusion from premium buyer qualification lists as ZDHC compliance timelines tighten. Workforce retraining costs weigh against automation subsidies when mills select upgrade sequencing.
Indonesia Textile Manufacturing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical coverage determining access to international brand supplier lists. The upper tier commands uniform and workwear contracts through captive spinning-to-finishing capability, while mid-scale weavers compete on batch flexibility for domestic garment cutters. Two archetypes dominate: petrochemical-integrated fiber producers with captive feedstock, and vertically integrated apparel textile suppliers with full process coverage. Competitive moves center on automation subsidy capture under Making Indonesia 4.0 and API sustainability certification for export qualification.
Among Indonesia-based textile manufacturers, PT. Sri Rejeki Isman Tbk (Sritex), PT. Pan Brothers Tbk, and PT. Indorama Synthetics Tbk occupy positions across the vertical integration spectrum. Sritex exemplifies the fully integrated archetype with spanning capability from yarn spinning through finished fabric. Pan Brothers anchors export volume positioning through long-term supply framework agreements. Indorama Synthetics represents the petrochemical-integrated fiber producer model with captive upstream feedstock control. These three companies illustrate how backward integration and sustainability certification are separating qualified tier-one suppliers from fragmented downstream competitors.
| Leading Market Players |
|---|
| PT. Pan Brothers Tbk |
| PT. Danantara Textiles |
| PT. Sri Rejeki Isman Tbk (Sritex) |
| PT. Indo Acfic Tbk |
| PT. Poly Prima Indonesia Tbk |
| PT. Indorama Synthetics Tbk |
| PT. Gajah Tunggal Tbk |
| PT. Tifico Fiber Indonesia Tbk |
| PT. Asia Pacific Fibers Tbk |
| Others |
Supply & Pricing Matrix
Captive PTA-MEG capacity at Merak and Cilegon petrochemical complexes generates scale economies that compress synthetic fiber price floors while simultaneously concentrating supply leverage among integrated polyester producers. This concentration reshapes procurement dynamics across Java's weaving belt, where spinners lacking backward integration face margin compression from both feedstock volatility and electricity tariff premiums.
Pricing Analysis
Long-term offtake agreements between Surabaya-based mills and Trans-Java infrastructure contractors anchor pricing stability in technical textiles, while spot-market cotton yarn trades expose smaller Bandung weavers to rupiah-dollar exchange pressure. Price differentiation rests on API sustainability certification and ZDHC compliance tier, with certified facilities commanding premium positioning for EU and US brand supplier lists. Pricing pressure stems from unregistered dye house fragmentation in Solo, where below-threshold effluent operations undercut compliant facility margins. Domestic garment cutters exhibit highest price sensitivity, whereas automotive OEMs prioritize specification adherence over unit cost.
Supply Chain Analysis
Container availability fluctuations at Tanjung Priok and Surabaya ports elevate inbound logistics costs for raw cotton arriving from the United States, Brazil, and Australia. Indonesia's spinning sector draws from these three origins for lint supply, with quality variation complicating consistent yarn production. Supply chain risk centers on single-source vulnerability for caprolactam and polymer chip imports feeding nylon filament lines. Distribution runs through vertically integrated mills with in-house finishing capability, as brand supplier qualification requirements consolidate procurement volumes among certified tier-one facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's textile manufacturing sector is navigating a cyclical recovery shaped by infrastructure spending acceleration, with Trans-Java toll road expansion and new capital city projects absorbing high-tenacity woven output.
For Market Incumbents: Shield margin position by accelerating waterless supercritical CO2 dyeing module deployment to bypass wastewater treatment bottlenecks and retain brand supplier status. Consolidate weaving capacity through rapier-to-jacquard upgrades under Making Indonesia 4.0 tax incentives, capturing automation subsidies before domestic machinery sourcing quotas tighten. Workforce retraining costs represent the critical lever against facility consolidation decisions. For New Entrants and Emerging Players: Technical textile specification gaps in automotive airbag substrates and seat fabric present white-space targets, as domestic vehicle assembly plants demand just-in-time delivery capabilities that incumbent commodity weavers under-serve. Makassar and Sulawesi offer underpenetrated geography for export-oriented garment sewing operations, leveraging lower labor costs and underutilized port capacity. Go-to-market positioning should emphasize ZDHC compliance from inception to bypass the 18-24 month chemical inventory overhaul timeline blocking incumbent qualification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors petrochemical-integrated fiber producers with captive PTA-MEG feedstock control, as domestic polymer capacity expansion displaces import-dependent cotton spinners. Long-term viability across the projection horizon rests on backward integration depth and API certification portfolio breadth. Acquisition target archetype: vertically integrated mills with in-house spinning, weaving, and finishing capability in Surabaya or Bandung clusters. Signal to watch: Ministry of Industry automation subsidy disbursement velocity as inflection indicator for competitive repositioning pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstock | Merak and Cilegon petrochemical co-location secures polyester supply against rupiah volatility. |
| ZDHC Compliance Certification | Chemical management overhaul opens EU and US apparel brand supplier qualification pathways. |
| Waterless Dyeing Module Deployment | Supercritical CO2 systems bypass BIS effluent thresholds and central treatment facility dependency. |
| Jacquard Loom Automation Upgrade | Making Indonesia 4.0 tax incentives accelerate pattern-change capability for technical textile contracts. |
| Eastern Indonesia Manufacturing Expansion | Makassar and Sulawesi port capacity supports export-oriented garment sewing cost repositioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary research phases, including loom operators and dye technicians in Bandung and Surabaya clusters, procurement managers at international apparel brands, plant engineers at petrochemical-integrated fiber facilities, and API sustainability certification auditors. Secondary validation drew from BIS standards documentation, Ministry of Industry Making Indonesia 4.0 policy filings, PLN industrial electricity tariff schedules, and customs trade data for cotton and synthetic fiber imports. Bottom-up capacity utilization estimates triangulated against top-down infrastructure project demand forecasts.
Across the analysis window, volume and value projections model woven versus technical textile segmentation alongside material type splits between polyester and cotton, manufacturing process automation maturity tiers, and end-use channel differentiation between apparel and automotive components. CAGRs derive from facility-level capacity expansion announcements, subsidy disbursement trajectories, and brand supplier qualification timeline assumptions. Forecast inputs incorporate petrochemical feedstock capacity buildout at Merak and Cilegon, plus Trans-Java toll road construction phase commitments.
Underlying assumptions cover sustained infrastructure spending execution, stable rupiah-dollar exchange bands, and BIS effluent enforcement consistency, with deviation risk concentrated in PLN tariff adjustment magnitude and ZDHC compliance timeline acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Sailcloth Market