
 Upholstery Fabric Market | 2026-2036
Upholstery Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Upholstery Fabric Market Analytics
European textile mills is restructuring capacity toward performance-driven synthetics as energy costs reshape continental manufacturing economics. Milliken & Company leverages polymer science expertise to dominate commercial-grade solution-dyed acrylics. Glen Raven anchors North American supply through vertical control of fiber-to-finish Sunbrella production. Kravet competes in the design-trade channel with deep archival pattern libraries and rapid custom capabilities.
Upholstery fabric denotes woven, knitted, or non-woven textile materials engineered for furniture covering applications, typically specified by abrasion resistance (Wyzenbeek or Martindale cycles), tensile strength, and flammability compliance ratings. These materials must withstand mechanical wear while meeting aesthetic and safety requirements across residential, commercial, and transportation seating. Polyester leads material-type volume through cost-scalability and stain-resistance engineering, though leather commands premium margin pools in luxury automotive and executive hospitality segments. The hospitality end-user category is expanding fastest as hotel renovation pipelines reactivate across resort and urban select-service formats.
REACH in Europe, California TB 117-2013 in the United States, and China's GB 20286 national standard collectively govern flammability, chemical content, and labeling requirements that determine market access for upholstery textiles. Compliance costs favor scaled producers with dedicated testing laboratories and regulatory affairs teams. Stakeholders must monitor evolving state-level chemical disclosure mandates and bio-based content thresholds that will reshape raw-material sourcing decisions and supplier qualification protocols.
Market Dynamics
REACH chemical restrictions on flame retardants are forcing European mills to reformulate synthetic fiber compositions, compressing product development cycles while elevating compliance costs for smaller producers. This regulatory pressure is reshaping competitive positioning toward polymer science capabilities and captive testing infrastructure.
Growth Catalysts
- Hospitality renovation pipelines:Hotel operators in Dubai and Singapore are accelerating upholstery refresh cycles as occupancy rates normalize post-pandemic, pulling demand for commercial-grade solution-dyed acrylics through contract channels.
- REACH halogen-free mandates:The EU's chemical restrictions are redirecting R&D investment toward phosphorus-based and intumescent flame-retardant systems that maintain abrasion ratings without halogen content.
- Contract furniture manufacturing concentration:India's Moradabad and Jodhpur industrial belts are scaling woven polyester and leather processing capacity to serve North American and European furniture OEMs seeking cost-competitive sourcing.
Market Restraints
- Petrochemical feedstock volatility:Polyester staple fiber and solution-dyed acrylic yarn pricing tracks crude oil derivatives, compressing margin stability for mills without long-term polymer supply agreements.
- Testing laboratory concentration:Wyzenbeek and Martindale abrasion certification capacity clusters in Germany and the United States, creating bottlenecks for Asian mills seeking European market access.
- Leather substitution pressure:Advanced polyurethane microfiber and silicone-coated fabrics are capturing price-sensitive segments in automotive and mass-market hospitality seating.
Strategic Opportunities
- Bio-based content thresholds:The EU Green Deal's emerging mandates for recycled and renewable feedstock percentages create first-mover advantage for mills with bio-polyester or agricultural waste fiber programs.
- Direct-to-designer digital platforms:Custom pattern visualization and rapid sampling tools are disintermediating traditional distributor channels for high-end residential and boutique hospitality projects.
- Transportation seating expansion:Rail and aviation interior refurbishment cycles are extending beyond traditional automotive applications, requiring specialized flame-retardant knit constructions.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with expertise in halogen-free flame-retardant systems and solution-dyeing processes command premium compensation, constraining mid-tier mill expansion.
- Multi-jurisdiction certification complexity:Simultaneous compliance with REACH, California TB 117-2013, and China's GB 20286 requires dedicated regulatory affairs teams that smaller producers cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Upholstery Fabric Market |
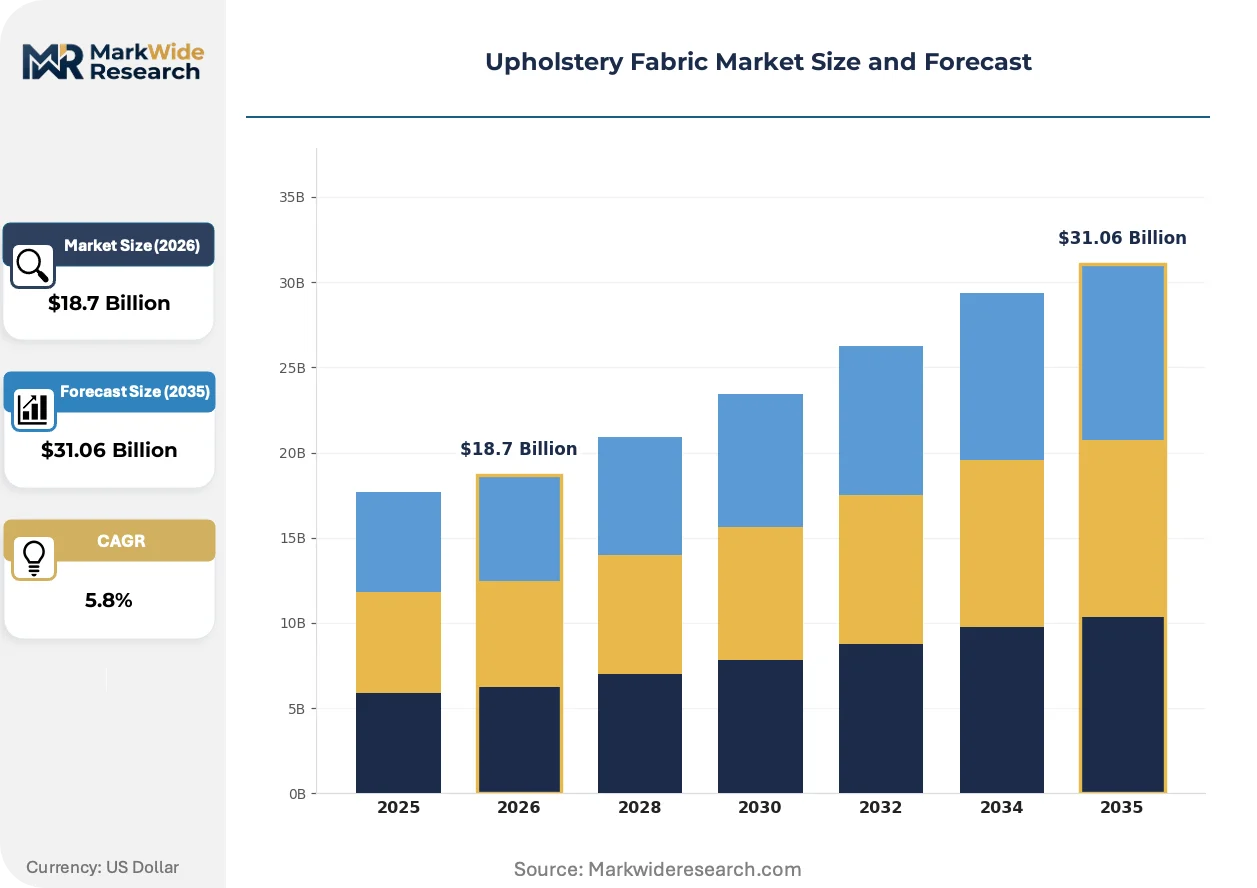
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Polyester, Cotton, Nylon End User: Residential, Commercial, Automotive, Hospitality Pattern Type: Solid, Striped, Floral, Geometric Durability Grade: Heavy Duty, Medium Duty, Light Duty, Upholstery Grade |
| Companies Covered | Fabricut, Milliken & Company, Absecon Mills, Kravet, Sunbrella, CF Strow, Glen Raven, Donghia, Designtex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Upholstery Fabric Market Evolving Landscape
Digital design-to-manufacture workflows and sustainable chemistry are converging to compress development timelines while elevating performance specifications across residential and contract segments. These forces are redistributing competitive advantage toward vertically integrated producers with in-house polymer and pattern capabilities.
Solution-dyed acrylic fiber technology is integrating nanoscale UV stabilizers and soil-release chemistries directly into polymer extrusion, eliminating post-weave finishing steps. Hospitality procurement teams in resort and cruise segments are specifying these constructions for exterior and high-traffic interior applications. This integration is compressing supplier qualification timelines while raising minimum volume thresholds for mill-direct relationships.
ECHA's expanding SVHC candidate list is accelerating substitution of antimony trioxide and brominated flame retardants in European-sourced upholstery. Mills with dedicated REACH compliance laboratories are capturing specification share from competitors reliant on third-party testing. Contract furniture manufacturers serving German and French markets are now requiring full material disclosure documentation upstream to finished fabric.
Hotel ownership groups are consolidating upholstery specification authority at corporate level, displacing property-level purchasing autonomy. Design-build firms and procurement consortiums are capturing volume previously fragmented across individual franchise operators. This concentration is most visible in North American select-service and extended-stay formats where brand standards mandate uniform textile specifications across portfolios exceeding ten thousand rooms.
Upholstery Fabric Market Segmentation
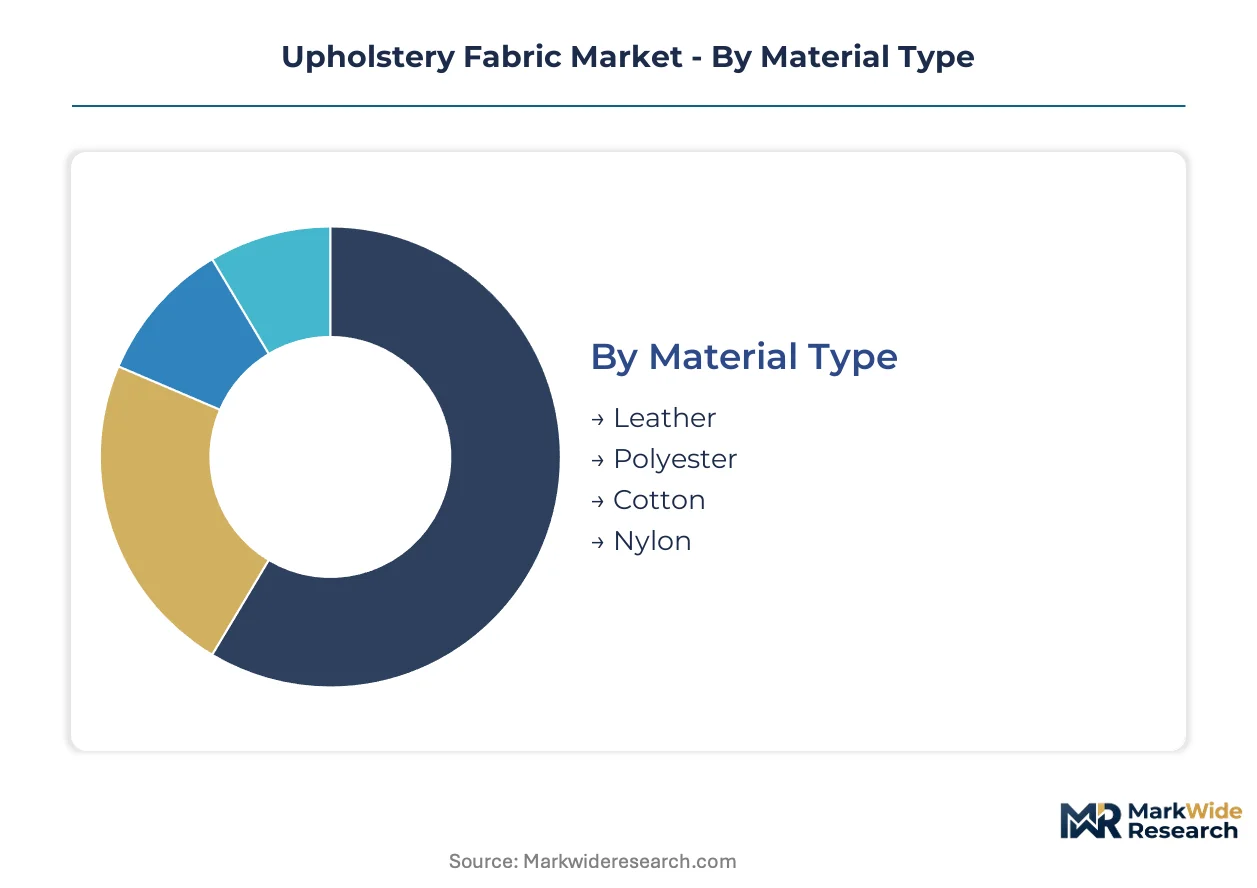
Segmentation in upholstery fabrics tracks how procurement authority, performance specifications, and aesthetic requirements diverge across buyer categories. Material chemistry and end-use durability standards create distinct supply chains with incompatible testing protocols and margin structures.
Material Type:
Cost tier and performance engineering drive specification decisions across residential, contract, and transportation seating applications.
- Polyester:Solution-dyed staple fiber dominates volume through abrasion resistance above 50,000 Wyzenbeek cycles and stain-repellent surface engineering. Hotel procurement teams in Dubai and Singapore specify polyester for high-traffic guest room upholstery where refresh cycles compress to 18-24 months.
- Leather:Full-grain and corrected-grain hides command premium positioning in executive aviation seating and luxury automotive interiors. REACH chemical restrictions on chromium tanning are redirecting European tanneries toward vegetable and synthetic tanning agents that maintain flame-retardant compliance.
- Cotton:Natural fiber constructions serve residential and boutique hospitality segments prioritizing hand-feel and breathability over commercial durability ratings.
- Nylon:High-tenacity filament yarns deliver superior tensile strength for transportation seating and heavy-duty contract applications requiring 100,000+ abrasion cycles.
Polyester leads on scale; leather leads on momentum as bio-based alternatives and regulatory pressure reshape premium segment sourcing.
End User:
Application environment determines flammability certification requirements, pattern complexity, and volume procurement structures.
- Hospitality:Hotel ownership groups are consolidating specification authority at corporate headquarters, mandating uniform textiles across portfolios exceeding ten thousand rooms. Solution-dyed acrylics with integrated nanoscale UV stabilizers dominate resort and cruise exterior applications.
- Commercial:Office furniture OEMs specify heavy-duty polyester and nylon constructions for 24/7 seating in call centers and healthcare waiting areas. California TB 117-2013 compliance is non-negotiable for North American contract access.
- Residential:Design-trade channels emphasize rapid custom sampling and archival pattern libraries for high-end upholstery projects. Digital visualization tools are compressing traditional distributor relationships.
- Automotive:Tier 1 seating suppliers require specialized flame-retardant knit constructions meeting OEM-specific fogging and emissions standards.
Hospitality claims the steepest expansion trajectory; commercial maintains the deepest procurement concentration.
Pattern Type:
Aesthetic differentiation and production economics separate stock programs from custom development pipelines.
- Solid:Plain-weave and twill constructions in solution-dyed yarns minimize inventory risk for hospitality and commercial stock programs. Digital color matching enables rapid replenishment without minimum order constraints.
- Geometric:Jacquard and dobby-woven patterns serve mid-market hospitality and corporate interiors where brand identity requires consistent visual language across property portfolios.
- Striped:Classic linear patterns concentrate in residential traditional and coastal aesthetic segments with predictable repeat-demand profiles.
- Floral:Archival and custom botanical prints compete in design-trade residential channels where pattern exclusivity commands margin premiums.
Solids dominate volume throughput; geometrics gain share fastest as brand-standard consolidation accelerates.
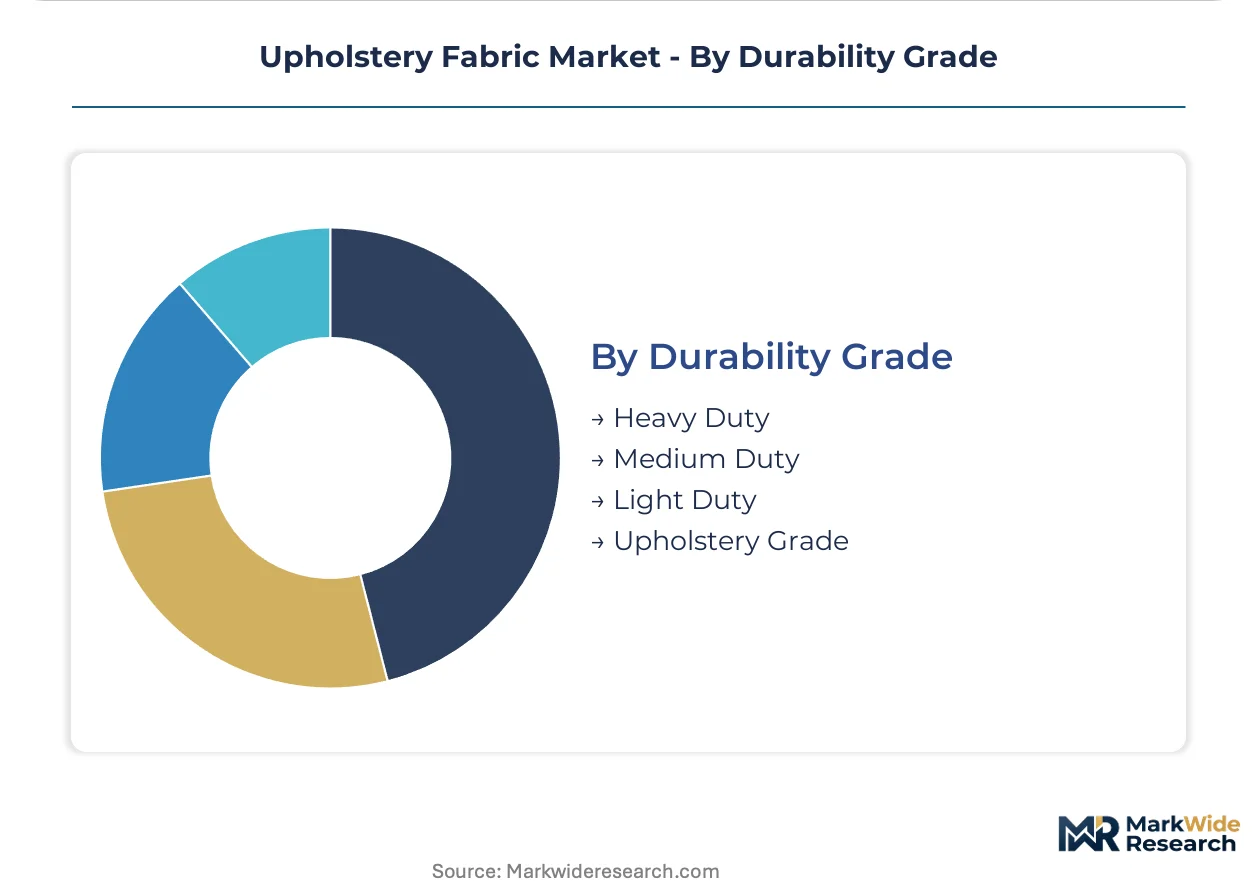
Durability Grade:
Wyzenbeek and Martindale abrasion testing thresholds determine market access and pricing stratification across buyer segments.
- Heavy Duty:Exceeding 50,000 Wyzenbeek cycles, these constructions target transportation, healthcare, and 24/7 commercial seating. Certification bottlenecks at German and US testing laboratories constrain Asian mill market access.
- Medium Duty:15,000-50,000 cycle ratings serve standard hospitality guest rooms and residential family seating where replacement cycles balance durability with cost.
- Light Duty:Below 15,000 cycles, these fabrics occupy decorative accent and occasional-use residential segments with minimal performance engineering.
- Upholstery Grade:A catch-all classification spanning unrated decorative constructions to entry-level performance fabrics without standardized testing documentation.
Heavy duty commands the tightest supply; medium duty captures the broadest specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing upholstery fabric production toward jurisdictions with lower compliance-cost burdens. Mills in India and Southeast Asia capture contract furniture sourcing previously anchored in European manufacturing belts.
Germany
REACH enforcement through ECHA drives halogen-free reformulation investments among Rhine-Ruhr textile mills. The country's national chemical regulator maintains Europe's strictest SVHC documentation requirements. Stuttgart and Munich industrial zones concentrate solution-dyed acrylic R&D capacity for automotive seating applications.
United States
California TB 117-2013 compliance mandates shape procurement specifications for hospitality and commercial furniture OEMs. The EPA oversees chemical disclosure frameworks affecting flame-retardant content labeling. North Carolina and Georgia manufacturing corridors host captive fiber-to-finish operations serving domestic contract channels.
India
BIS certification requirements for textile flammability are tightening as export-oriented mills target European and North American markets. The country's national standards body is harmonizing test protocols with ISO benchmarks. Moradabad and Jodhpur industrial belts scale woven polyester and leather processing capacity for international furniture OEMs.
China
GB 20286 national standards govern upholstery flammability classifications for domestic and export-bound production. MIIT oversees industrial policy directing textile capacity toward higher-value technical fabrics. Zhejiang and Jiangsu province manufacturing clusters dominate global polyester staple fiber output.
United Arab Emirates
Dubai hospitality operators are accelerating upholstery refresh cycles as hotel occupancy normalizes post-pandemic. MOHAP regulates product safety standards for imported textile furnishings. Jebel Ali industrial zone hosts regional distribution hubs serving Gulf Cooperation Council contract furniture markets.
Upholstery Fabric Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based material platforms and direct-to-designer digital channels. The vendor base stratifies across polymer science specialists, vertically integrated fiber-to-finish operators, and design-trade pattern houses. Three archetypes dominate: multinational chemical conglomerates with captive textile divisions, mid-tier mills with regional certification expertise, and boutique studios with archival design libraries. Competitive moves concentrate on backward integration into polymer supply and geographic expansion into India's contract manufacturing belt.
Among North American solution-dyed acrylic specialists, Milliken & Company and Glen Raven exemplify the polymer-science-driven archetype through captive fiber production and in-house testing infrastructure. Kravet occupies a position within the design-trade channel, anchoring the pattern-library and rapid-custom-sampling segment. These three entities represent distinct competitive vectors: technical performance engineering, vertical supply control, and aesthetic differentiation through archival depth.
| Leading Market Players |
|---|
| Fabricut |
| Milliken & Company |
| Absecon Mills |
| Kravet |
| Sunbrella |
| CF Strow |
| Glen Raven |
| Donghia |
| Designtex |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's emerging bio-based content thresholds gate qualified supply and premium-tier pricing access for upholstery mills, favoring producers with verified renewable feedstock programs while compressing margin structures for conventional synthetic specialists. REACH compliance costs and halogen-free reformulation investments stratify pricing power toward scaled polymer science operators with captive testing infrastructure.
Pricing Analysis
Distributor margin layers in contract furniture channels absorb 15-25 points before mill-direct relationships. Three-tier pricing structure across premium, standard, and economy levels separates solution-dyed acrylics with integrated UV stabilizers from commodity polyester weaves and entry-level decorative constructions. Cost compression in standard-grade polyester is intensifying because Indian and Chinese mills compete on volume for North American hospitality procurement. Boutique hospitality and executive aviation seating demonstrate least price sensitivity; mass-market residential channels through big-box retailers show highest elasticity.
Supply Chain Analysis
Polymer science chemist scarcity in Germany and the United States constrains European mill expansion despite strong order books. Raw material flows draw from Zhejiang and Jiangsu province polyester staple fiber clusters, Saudi petrochemical derivatives for solution-dyed acrylic polymers, and Italian tanneries for full-grain aviation leather. Single-source vulnerability concentrates in German and US testing laboratories certifying Wyzenbeek and Martindale abrasion ratings. Distribution runs through Jebel Ali regional hubs serving Gulf hospitality projects, North Carolina corridor captive operations for domestic contract channels, and direct mill relationships with consolidated hotel ownership groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The upholstery fabric market reads as a late-cycle quality story as hotel ownership groups consolidate specification authority and mandate premium durability ratings across ten-thousand-plus room portfolios. This demand-shift toward heavy-duty certified constructions rewards mills with polymer science depth and regulatory compliance infrastructure.
For Market Incumbents: Extend halogen-free flame-retardant formulation capabilities through dedicated REACH compliance laboratories that capture specification share from third-party-dependent competitors. Expand captive fiber production in North Carolina and Georgia corridors to defend margin position against Indian cost-competitive sourcing. Backward integration into polymer extrusion insulates against petrochemical feedstock volatility while accelerating solution-dyed acrylic development cycles. For New Entrants and Emerging Players: Launch via direct-to-designer digital platforms that disintermediate traditional distributor channels for high-end residential and boutique hospitality projects. Target bio-based polyester programs serving EU Green Deal procurement mandates as the most penetrable white-space segment. White-label manufacturing partnerships with Moradabad and Jodhpur industrial belt weavers provide cost-competitive entry without capital-intensive mill construction. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier mills with regional certification expertise but limited polymer science depth. Long-term viability over the next decade hinges on REACH compliance infrastructure and bio-based feedstock programs rather than scale alone. Watch for ECHA SVHC candidate list expansions as the inflection signal that accelerates consolidation toward halogen-free specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Captive fiber production insulates Milliken and Glen Raven from petrochemical volatility. |
| REACH Compliance Laboratory Investment | In-house SVHC testing accelerates European market access for reformulated synthetic constructions. |
| Direct-to-Designer Digital Platform Launch | Kravet's visualization tools compress sampling timelines and disintermediate distributor markups. |
| Bio-Based Polyester Program Development | EU Green Deal thresholds create first-mover advantage for agricultural waste fiber specialists. |
| Indian Manufacturing Belt Partnership | Moradabad and Jodhpur weavers offer cost-competitive capacity for North American hospitality OEMs. |
Research Methodology
Multiple input streams — primary interviews with polymer science directors, hospitality procurement leads, and contract furniture OEM sourcing managers; secondary validation through ECHA SVHC candidate list updates, BIS certification harmonization notices, and customs trade data — were reconciled to construct market estimates. Bottom-up mill capacity assessments and top-down end-use demand modeling triangulated volume figures across material type, durability grade, and end-user segments.
Historical capacity utilization and price realization data cross-referenced against panel input from fiber producers and textile mills anchored the analytical framework. Segmentation dimensions modeled include material chemistry, pattern complexity, durability certification tier, and geographic procurement cluster. CAGRs derived from production volume trajectories, renovation pipeline reactivation timelines, and regulatory compliance cost absorption rates across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH restriction expansions or petrochemical price spikes. Material deviation in ECHA SVHC candidate list additions, bio-based mandate acceleration, or hospitality occupancy recovery trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Wool Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Knitted Fabric Market