
 Canada Refrigerated Vehicles Market | 2026-2036
Canada Refrigerated Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Refrigerated Vehicles Market Insights
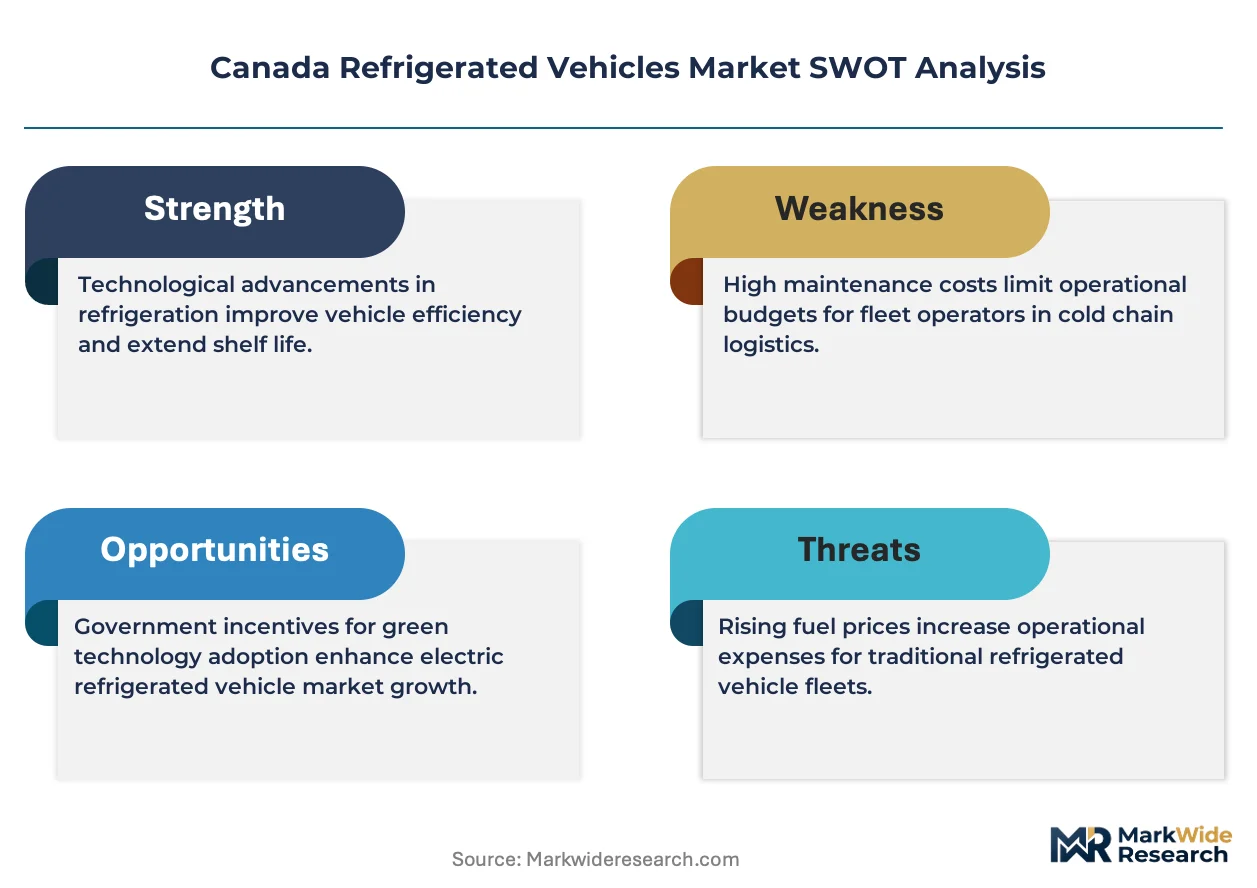
Electric auxiliary power units and telematics-enabled temperature monitoring is rewriting cold chain reliability standards for Canadian fleet operators. Thermo King Corporation leverages its nationwide service network to sustain aftermarket revenue streams across provincial temperature zones. Carrier Transicold anchors the premium reefer segment through deep R&D investment in low-GWP refrigerant architectures. Manac Inc. competes on manufacturing scale, dominating domestic trailer production with Quebec-based fabrication facilities optimized for northern climate specifications.
Refrigerated vehicles are insulated transport assets engineered to maintain cargo temperatures between minus 25 degrees Celsius and plus 20 degrees Celsius through integrated mechanical refrigeration or passive thermal mass systems, purpose-built for preserving perishable goods across extended haul cycles. The light duty truck category leads unit volume in last-mile grocery and meal-kit delivery, while heavy duty trucks command the dominant share of total fleet capital expenditure due to extended duty cycles and multi-temperature zone configurations. Trailer-mounted reefers represent the fastest-growing technology segment as food processors and pharmaceutical distributors seek flexible capacity without dedicated tractor commitments.
Health Canada enforces stringent cold chain validation protocols under its Good Distribution Practice guidelines, compelling fleet operators to invest in redundant temperature logging and real-time alert systems. Transport Canada mandates CMVSS safety standards for refrigeration unit mounting and fuel system isolation, shaping OEM design priorities and aftermarket modification constraints. The Canadian Environmental Protection Act phases down hydrofluorocarbon refrigerants, forcing reefer manufacturers to qualify alternative chemistries under accelerated timelines. Stakeholders must weigh total cost of ownership against compliance readiness as refrigerant transition deadlines and provincial zero-emission vehicle mandates converge on fleet procurement decisions.
Market Dynamics
Electric auxiliary power units are collapsing total cost of ownership calculations for urban fleet operators across Ontario and Quebec, while Health Canada's tightening Good Distribution Practice enforcement is accelerating capital redeployment toward redundant cold chain validation systems.
Growth Catalysts
- Health Canada GDP enforcement:Biologics distributors are expanding refrigerated fleet orders to meet temperature validation requirements for insulin, vaccines, and gene therapies.
- Ontario Golden Horseshoe concentration:Food processors in the Toronto distribution hub are driving trailer-mounted reefer demand for flexible capacity without dedicated tractor commitments.
- Electric refrigeration integration:Zero-emission vehicle mandates in British Columbia and Quebec are pulling battery-electric auxiliary units into last-mile grocery and meal-kit delivery fleets.
Market Restraints
- Low-GWP refrigerant qualification costs:The Canadian Environmental Protection Act phase-down of hydrofluorocarbons is forcing manufacturers to accelerate alternative chemistry testing timelines.
- Quebec-based fabrication concentration:Domestic trailer production clusters in a single province, creating geographic supply vulnerability for western Canadian operators.
- Multi-zone configuration complexity:Heavy-duty trucks requiring simultaneous minus 25 and plus 20 Celsius zones face extended engineering cycles and certification delays.
Strategic Opportunities
- Prairie provincial expansion:Saskatchewan and Manitoba grain processors represent underpenetrated demand for temperature-controlled hopper-bottom trailers.
- Telematics-enabled temperature monitoring:Real-time alert systems are opening subscription revenue streams for fleet technology providers.
- Atlantic Canada seafood export corridors:Nova Scotia and New Brunswick lobster and aquaculture processors need expanded cold chain capacity for Asian market access.
Industry Challenges
- Refrigeration technician scarcity:Diesel-to-electric unit conversion requires retraining across Carrier Transicold and Thermo King service networks.
- CMVSS fuel system isolation compliance:Transport Canada safety standards for refrigeration unit mounting are extending OEM design cycles.
- Legacy fleet retrofit complexity:Existing diesel-powered reefers face integration friction with telematics overlay systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Refrigerated Vehicles Market |
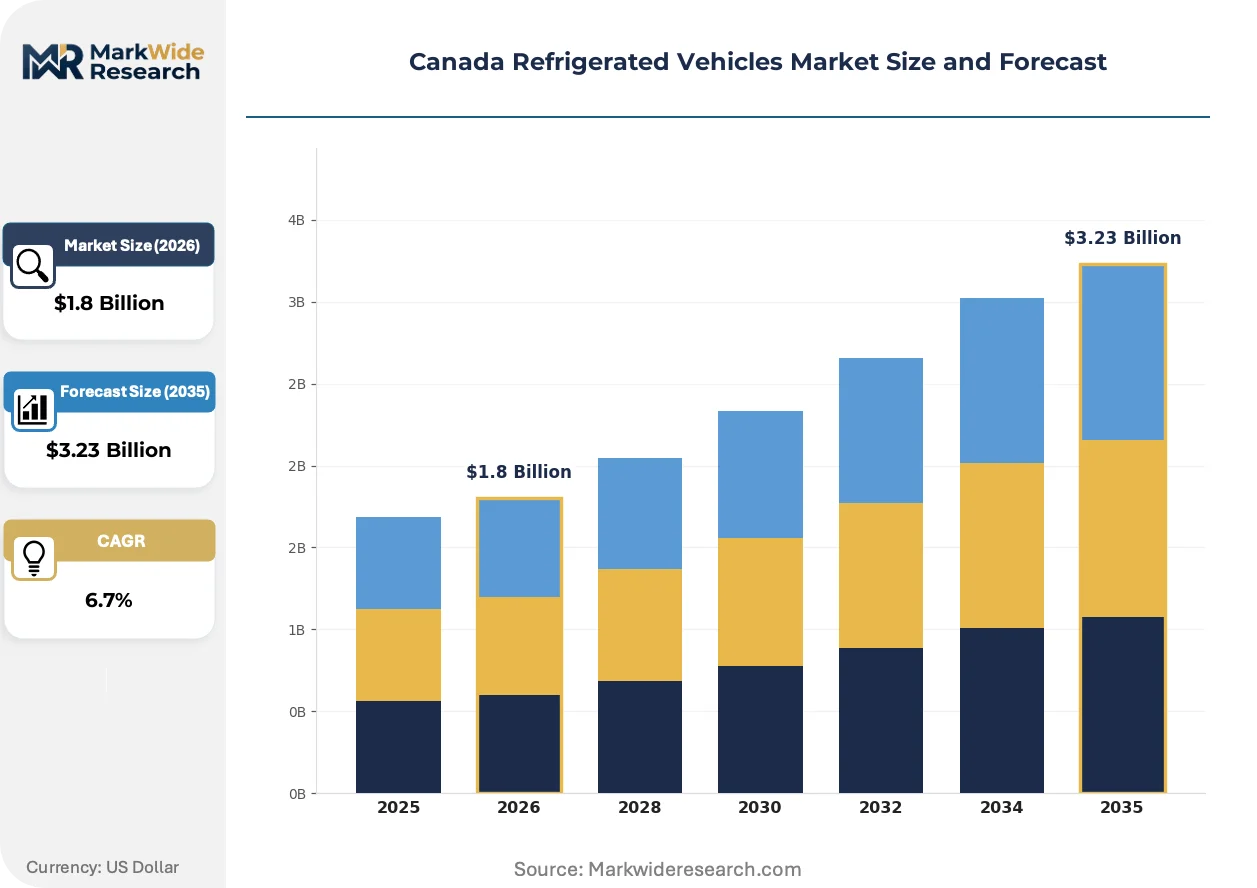
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty Trucks, Heavy Duty Trucks, Vans, Trailers Technology: Reefers, Insulated Containers, Active Cooling, Passive Cooling End User: Food & Beverage, Pharmaceuticals, E-Commerce, Logistics Providers Application: Cold Chain Transportation, Food Distribution, Vaccine Transportation, Dairy Delivery |
| Companies Covered | Manac Inc., Thermo King Corporation, Carrier Transicold, Utility Trailer Manufacturing Company, Wabash National Corporation, Great Dane, Schmitz Cargobull AG, Hyundai Translead, Brown Industries, LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Refrigerated Vehicles Market Trends and Innovations
Battery-electric auxiliary power units are rewriting operational economics for Canadian cold chain operators. Three distinct forces are compressing technology adoption timelines and reshaping fleet procurement patterns across provincial regulatory environments.
Electric refrigeration units are collapsing the operating cost advantage of diesel-powered systems in urban delivery corridors. Loblaws and Sobeys last-mile fleets are piloting battery-electric auxiliary units for Toronto and Vancouver grocery routes. The technology is collapsing the five-year total cost of ownership gap that previously favored conventional diesel reefers.
The Canadian Environmental Protection Act refrigerant phase-down is forcing accelerated low-GWP chemistry qualification. Hydrofluorocarbon reduction mandates are compressing manufacturer R&D timelines for CO2 and propane-based systems. Trailer manufacturers serving Health Canada-regulated pharmaceutical distributors face the steepest compliance deadlines.
Meal-kit subscription services are fragmenting traditional wholesale procurement patterns. HelloFresh and Goodfood direct-to-consumer operations are bypassing foodservice distributors and contracting dedicated light-duty refrigerated capacity. British Columbia's Lower Mainland exhibits the most pronounced channel disintermediation, with meal-kit fleets now representing a distinct buyer segment from conventional grocery logistics.
Canada Refrigerated Vehicles Market Segmentation
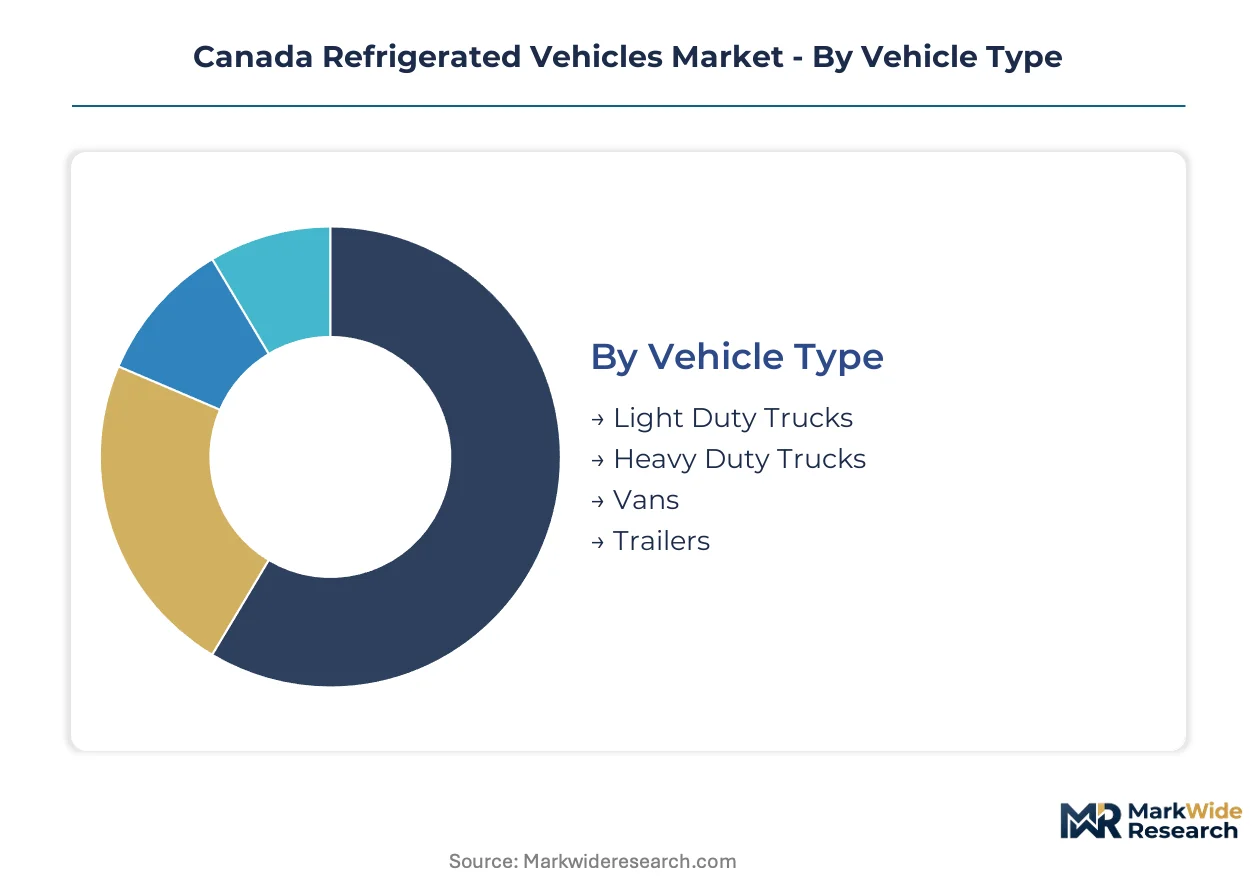
Segmentation in Canada's refrigerated vehicle market reveals how fleet procurement priorities diverge across duty cycles, cargo sensitivity, and regulatory exposure. Each dimension captures distinct capital allocation patterns among Ontario food distributors, Quebec pharmaceutical operators, and British Columbia zero-emission adopters.
Vehicle Type:
Cost tier stratification separates urban last-mile operations from long-haul capital commitments across Canadian fleet portfolios.
- Light Duty Trucks:These chassis carry integrated refrigeration units rated for 1-3 ton payloads, optimized for Toronto and Vancouver grocery route density. Meal-kit distributors like HelloFresh and Goodfood are concentrating orders here as direct-to-consumer channels bypass traditional foodservice networks.
- Heavy Duty Trucks:Multi-temperature zone configurations spanning minus 25 to plus 20 Celsius command premium capital expenditure through extended duty cycles. Ontario Golden Horseshoe food processors deploy these for flexible capacity without dedicated tractor commitments.
- Vans:Compact urban delivery units serve pharmacy and specialty food segments with reduced payload requirements.
- Trailers:Trailer-mounted reefers are climbing the fastest as pharmaceutical distributors seek modular capacity under Health Canada GDP enforcement.
Heavy duty trucks hold installed capacity. Trailers are rotating up the share rankings.
Technology:
Application requirements dictate thermal management architecture selection across cargo sensitivity and haul duration.
- Reefers:Mechanical vapor-compression systems maintain precise temperature control through integrated diesel or electric power units. British Columbia and Quebec zero-emission mandates are pulling battery-electric auxiliary units into pilot fleets.
- Insulated Containers:Passive thermal mass systems rely on pre-conditioned coolants for short-haul pharmaceutical and vaccine movements. Health Canada's tightening GDP validation requirements are accelerating redundant cold chain investment here.
- Active Cooling:Thermoelectric or compressor-driven units for mid-range temperature stability in variable ambient conditions.
- Passive Cooling:Insulated panels with gel packs for frozen food last-mile delivery in urban corridors.
Reefers dominate capital deployment. Insulated containers are gaining share fastest in pharmaceutical validation.
End User:
Customer type segmentation exposes divergent procurement sophistication between regulated biologics handlers and price-sensitive retail distributors.
- Food & Beverage:Loblaws and Sobeys national networks drive volume through Ontario distribution hubs, with meal-kit fragmentation creating new dedicated fleet demand.
- Pharmaceuticals:Biologics distributors face the steepest compliance deadlines under Health Canada GDP enforcement for insulin, vaccines, and gene therapies.
- E-Commerce:Direct-to-consumer cold chain requirements are emerging as a distinct buyer segment from conventional wholesale logistics.
- Logistics Providers:Third-party cold chain operators serving multiple end-use verticals with flexible asset deployment.
Food and beverage holds installed base. Pharmaceuticals is climbing fastest on regulatory tailwinds.
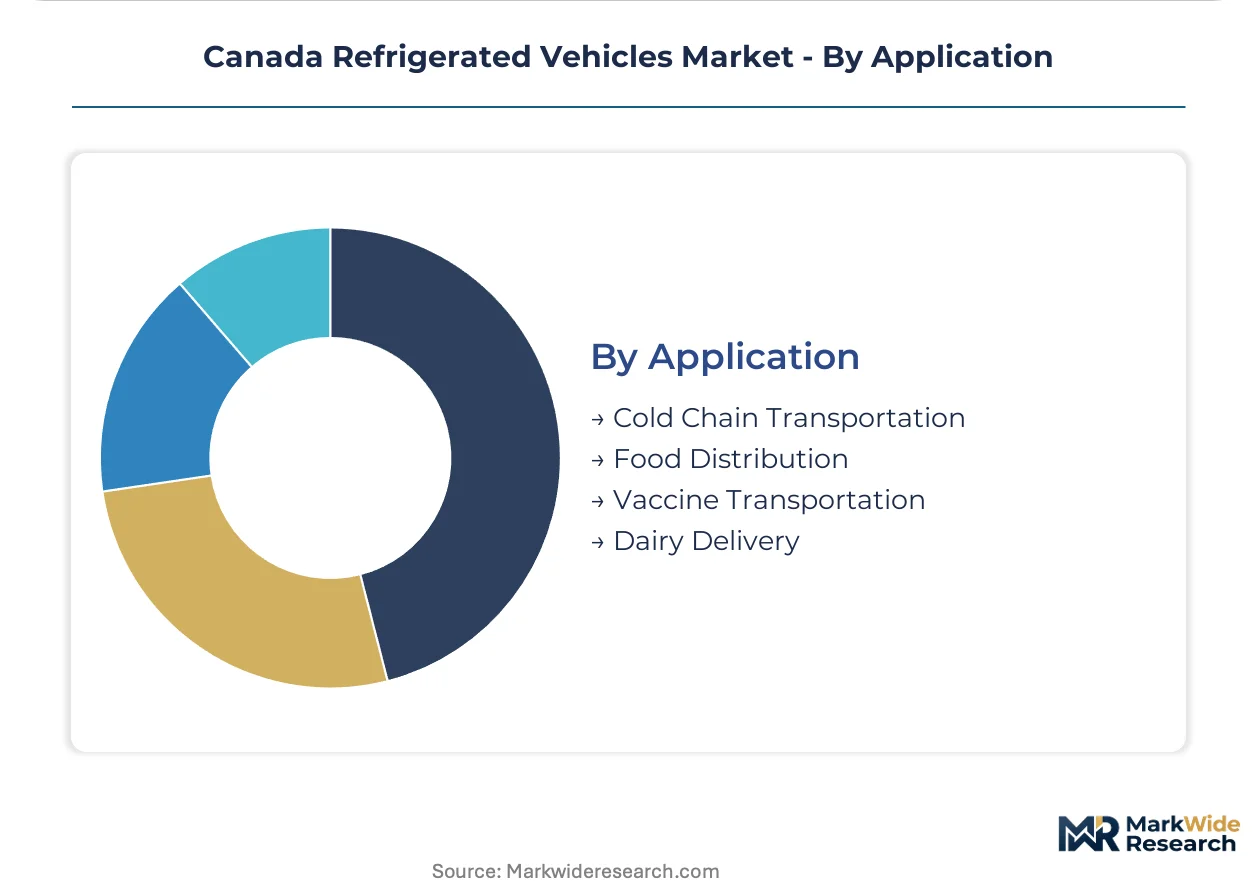
Application:
Volume concentration maps directly onto Canada's provincial economic geography and export corridor infrastructure.
- Cold Chain Transportation:Integrated temperature-controlled logistics spanning production through retail, anchored in Quebec and Ontario manufacturing clusters.
- Food Distribution:Wholesale and retail grocery networks concentrate demand in the Golden Horseshoe surrounding Toronto.
- Vaccine Transportation:Health Canada GDP-mandated validation protocols drive redundant temperature logging and real-time alert system investment.
- Dairy Delivery:Fluid milk and specialty cheese distribution maintains consistent refrigerated demand across provincial supply management systems.
Food distribution holds capacity concentration. Vaccine transportation is expanding most quickly on regulatory enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian seafood exports to Asian markets traverse refrigerated corridors through Vancouver and Halifax, while cross-border agricultural trade with the United States funnels through Ontario and Quebec distribution hubs.
Ontario
The Golden Horseshoe surrounding Toronto concentrates food processing and pharmaceutical distribution demand. Health Canada GDP enforcement tightens cold chain validation requirements for insulin and vaccine shipments. Mississauga and Brampton logistics parks host expanding trailer-mounted reefer fleets serving Loblaws and Sobeys national networks.
Quebec
Domestic trailer manufacturing clusters here with fabrication facilities optimized for northern climate specifications. The Canadian Environmental Protection Act refrigerant phase-down accelerates low-GWP chemistry testing timelines for CO2 and propane-based systems. Montreal pharmaceutical distributors face steep compliance deadlines for biologics cold chain infrastructure.
British Columbia
Provincial zero-emission vehicle mandates pull battery-electric auxiliary units into last-mile grocery and meal-kit delivery fleets. Vancouver's Lower Mainland exhibits pronounced channel disintermediation as HelloFresh and Goodfood contract dedicated light-duty refrigerated capacity. Port Metro Vancouver anchors seafood export corridors to Asian markets.
Alberta
Energy sector logistics and agricultural processing drive heavy-duty multi-temperature zone truck demand. Calgary and Edmonton distribution hubs serve prairie grain processors with extended duty cycle configurations. The province's regulatory environment lags coastal zero-emission mandates, preserving diesel reefer operating cost advantages.
Atlantic Canada
Nova Scotia and New Brunswick lobster and aquaculture processors need expanded cold chain capacity for Asian market access. Halifax port infrastructure upgrades support temperature-controlled seafood export growth. Regional fleet operators face technician scarcity for diesel-to-electric unit conversion across Carrier Transicold and Thermo King service networks.
Canada Refrigerated Vehicles Market Competitive Landscape
On the supply side, the industry is tiered between integrated refrigeration system providers, domestic trailer fabricators, and international chassis specialists. Three strategic archetypes dominate: technology licensors with nationwide service networks, scale-driven manufacturers with provincial production concentration, and import-dependent distributors serving western markets. Competitive moves center on refrigerant transition readiness and electric auxiliary unit pilot deployments.
Among domestic fabricators, Manac Inc. anchors Quebec-based manufacturing scale. Thermo King Corporation and Carrier Transicold occupy positions as integrated refrigeration technology providers with established aftermarket service infrastructure. These three represent the core competitive tension between provincial production advantages and nationwide cold chain reliability standards.
| Leading Market Players |
|---|
| Manac Inc. |
| Thermo King Corporation |
| Carrier Transicold |
| Utility Trailer Manufacturing Company |
| Wabash National Corporation |
| Great Dane |
| Schmitz Cargobull AG |
| Hyundai Translead |
| Brown Industries, LLC |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Quebec-based trailer fabrication is compressing supplier pricing power while forcing western Canadian operators to absorb elevated logistics premiums. Utilization rates at Manac Inc.'s domestic facilities directly shape tiered pricing postures across heavy-duty and light-duty reefer segments.
Pricing Analysis
Current-generation diesel refrigeration units, prior-generation hydrofluorocarbon systems, and next-generation battery-electric auxiliary units occupy distinct pricing tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under Health Canada GDP guidelines and geographic delivery cost differentials. Cost compression in electric auxiliary segments is intensifying because of provincial zero-emission vehicle mandate acceleration. Food and beverage distributors exhibit highest price sensitivity due to thin grocery margins, while pharmaceutical biologics handlers accept premium pricing for redundant cold chain validation systems.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk calculations for chassis and refrigeration component sourcing. Manufacturing concentration rests on Quebec for domestic trailer fabrication, the United States for heavy-duty chassis platforms, and Germany for precision refrigeration compressors. Steel, aluminum, and low-GWP refrigerant chemistries constitute critical input dependencies. Single-source vulnerability concentrates in electric auxiliary power unit battery cell supply. Distribution runs through Ontario Golden Horseshoe logistics parks serving Loblaws and Sobeys national networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric refrigeration unit adoption is compressing technology transition timelines across Canadian fleet procurement. Health Canada's refrigerant phase-down enforcement under the Canadian Environmental Protection Act creates a regulatory inflection that rewards early compliance investment.
For Market Incumbents: Build service network density as the defensive moat. Carrier Transicold and Thermo King Corporation should expand technician training infrastructure for diesel-to-electric conversion across provincial temperature zones. Secure backward integration into low-GWP refrigerant distribution channels to defend margin position against chemistry qualification cost spikes. Channel control through exclusive aftermarket parts agreements locks out independent service providers. For New Entrants and Emerging Players: Pursue Saskatchewan and Manitoba grain processor segments where temperature-controlled hopper-bottom trailer penetration remains underdeveloped. Atlantic Canada seafood export corridors offer white-space expansion as Nova Scotia lobster processors seek Asian market access. A telematics-enabled temperature monitoring subscription model bypasses capital-intensive manufacturing barriers while capturing recurring revenue from Health Canada GDP compliance requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because cold chain validation requirements are structurally tightening across pharmaceutical and food safety regimes. Acquisition targets should display electric auxiliary unit integration capabilities and established Health Canada certification relationships. The signal to watch is provincial zero-emission vehicle mandate acceleration in British Columbia and Quebec as fleet electrification inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Auxiliary Unit Integration | Battery-electric refrigeration collapses total cost of ownership for Loblaws and Sobeys urban delivery fleets. |
| Low-GWP Refrigerant Qualification | CO2 and propane-based systems secure Health Canada compliance ahead of Canadian Environmental Protection Act deadlines. |
| Telematics Platform Deployment | Real-time temperature monitoring opens subscription revenue streams from pharmaceutical GDP validation requirements. |
| Quebec Manufacturing Footprint Expansion | Manac Inc. scale advantages in northern climate specifications anchor domestic trailer supply security. |
| Prairie Provincial Distribution Buildout | Saskatchewan and Manitoba grain processors represent underpenetrated demand for flexible refrigerated capacity. |
Research Methodology
Desk research of Transport Canada regulatory filings, Health Canada GDP guidance documents, and provincial zero-emission vehicle mandate records preceded structured interviews with fleet operations managers, refrigeration unit procurement directors, cold chain compliance officers, and aftermarket service network heads. Primary fieldwork combined with secondary validation through Canadian Environmental Protection Act enforcement timelines and OEM refrigeration system specification databases. Bottom-up unit shipment modeling and top-down fleet capital expenditure triangulation anchored market sizing.
Assumptions held fixed include Health Canada GDP enforcement intensity and provincial zero-emission vehicle mandate adoption schedules, while electric auxiliary unit cost curves and low-GWP refrigerant availability were varied across sensitivity scenarios. Vehicle type, technology architecture, end-use vertical, and application segmentation dimensions structured the analytical framework across the projection horizon. CAGRs derived from fleet replacement cycle analysis and regulatory compliance deadline clustering. Refrigeration technician training capacity and battery cell supply constraints fed industry-specific forecast inputs.
Sensitivities concentrate around electric auxiliary unit total cost of ownership crossover timing and Health Canada GDP audit enforcement intensity. Forecasts reflect assumptions about provincial regulatory harmonization and refrigerant chemistry qualification success rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Iraq Trailer Market
Commercial Vehicles
Robotic Haul Trucks Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Van Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Peru Commercial Vehicle Market