
 Metal Replacement Market | 2026-2036
Metal Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Replacement Market Intelligence
Asset-light manufacturing models, enabled by contract production partnerships, is reconfiguring the competitive landscape for high-performance polymers. This shift allows focused specialists to compete against vertically integrated giants like BASF SE, which leverages its vast chemical production scale. Solvay SA differentiates through its focus on specialty polymers for demanding aerospace and automotive applications. SABIC sustains its market position through extensive R&D in advanced thermoplastics and a broad portfolio.
Metal replacement involves substituting traditional metals like steel and aluminum with materials such as engineering plastics, composites, and high-performance ceramics. These materials offer benefits including significant weight reduction, corrosion resistance, and greater design flexibility, often achieved through processes like injection molding. High-performance plastics and composites are displacing conventional alloys in numerous uses. The automotive and aerospace applications command premium pricing due to stringent performance and safety requirements.
Market access and material specifications are governed by a complex web of international and national standards. Regulations such as the European Union's REACH framework, vehicle safety protocols from the US NHTSA, and China's GB standards for materials directly influence product development. Material suppliers must continuously innovate to meet evolving environmental regulations and end-user demands for higher performance and sustainability.
Market Dynamics
The push for circularity, codified in regulations like the EU Green Deal, is the central force shaping the market. This compels a systemic shift from linear metal-based supply chains toward recoverable and reusable high-performance polymer and composite solutions.
Growth Catalysts
- Automotive Lightweighting:Stringent emissions standards, particularly in Europe and China, compel automakers to use engineering plastics and composites to reduce vehicle weight and improve fuel or battery efficiency.
- Aerospace Modernization:The demand for next-generation aircraft with higher fuel efficiency and lower maintenance costs drives the adoption of carbon fiber composites in primary structures like fuselages and wings.
- Process Innovation:Advances in injection molding and automated fiber placement technologies are lowering the cost and increasing the speed of producing complex polymer parts, making them more competitive against machined metals.
Market Restraints
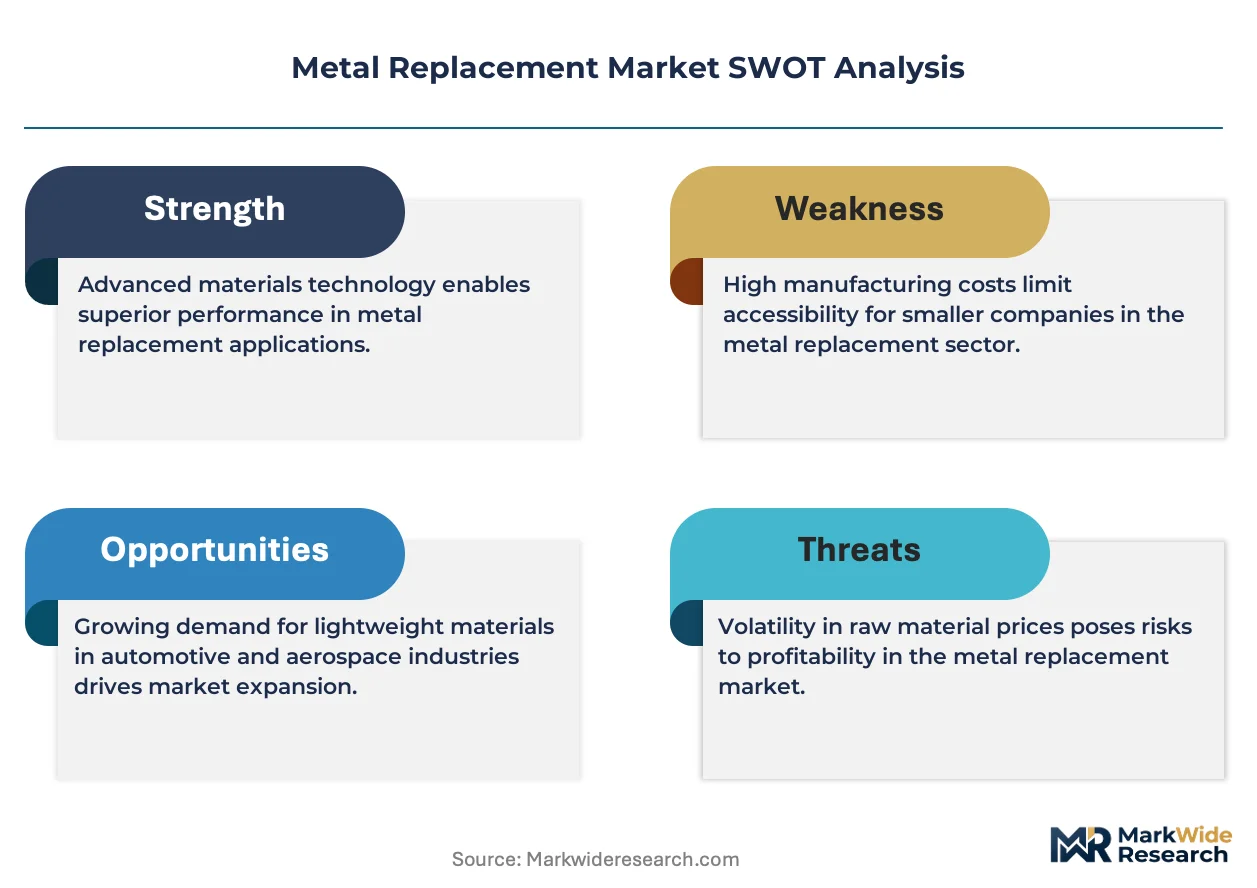
- Material Cost Premium:The high initial cost of high-performance polymers, such as PEEK and carbon fiber composites, remains a primary barrier to entry compared to conventional aluminum and steel alloys.
- Thermal Performance Limits:Many engineering plastics cannot withstand the extreme temperatures found in internal combustion engine components or certain industrial processes, limiting their application scope.
- Recycling Complexity:The absence of mature, large-scale recycling infrastructure for thermoset composites and multi-material plastic components hinders sustainability goals and complicates end-of-life vehicle directives.
Strategic Opportunities
- Medical Device Components:Biocompatible and sterilizable polymers present a significant opportunity to replace stainless steel in single-use surgical instruments, implantables, and diagnostic equipment casings.
- Hydrogen Economy Infrastructure:The build-out of hydrogen production and distribution requires corrosion-resistant composite materials for high-pressure storage tanks, piping, and fuel cell components.
- Construction and Infrastructure:Fiber-reinforced polymer (FRP) rebar and structural profiles offer a corrosion-proof alternative to steel in bridges, marine structures, and buildings in harsh environments.
Industry Challenges
- Specialized Design Skills:A persistent talent shortage of engineers with expertise in composite mechanics and polymer part design slows adoption and increases reliance on specialized consulting firms.
- Lengthy Qualification Cycles:Securing material certifications from bodies like the FAA for aerospace or the NHTSA for automotive applications involves extensive, multi-year testing protocols that delay market entry for new materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Replacement Market |
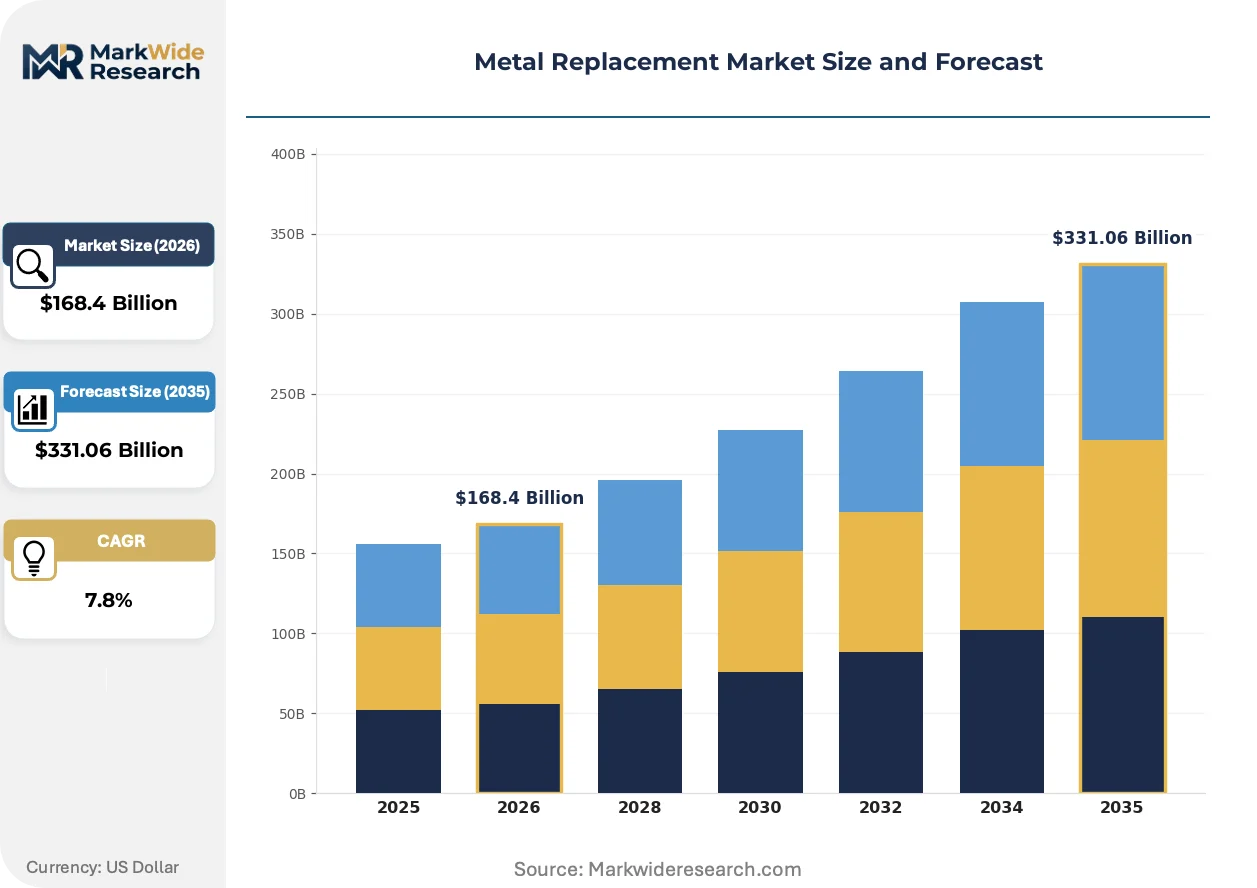
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $331.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloys, Composites, Plastics, Ceramics Application: Aerospace, Automotive, Construction, Consumer Electronics End User: Manufacturers, OEMs, Suppliers, Contractors Technology: Additive Manufacturing, Injection Molding, Casting, Machining |
| Companies Covered | BASF SE, Celanese Corporation, DuPont, Toray Industries Inc., Solvay SA, SABIC, SGL Group, Owens Corning Corporation, Covestro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Replacement Market Strategic Shifts & Innovations
Innovation in the metal replacement market is driven by the convergence of material science and digital manufacturing. This synthesis enables the creation of lighter, stronger, and more complex components that fulfill stringent sustainability and performance mandates across key industries.
Multi-material injection molding allows for the integration of different polymers into a single, functional part. Automotive and consumer electronics manufacturers are rapidly adopting this technique to consolidate assemblies and reduce weight. The market's production logic is migrating from assembling discrete metal and plastic pieces to creating unified, multi-functional composite components in one process step.
Regulatory frameworks like the European Union's REACH directive are forcing a significant reformulation of polymer compounds. The directive restricts or bans certain chemicals and plasticizers, compelling material suppliers to invest heavily in developing compliant, high-performance alternatives. This directly affects supply chains for automotive interiors and medical devices destined for the EU market.
A notable demand-side shift involves OEMs forming direct co-development partnerships with material science companies, bypassing traditional tiered supply structures. This collaborative model gives polymer specialists early-stage influence on component design, ensuring material properties align with performance goals from inception. The practice is most advanced within the electric vehicle and aerospace sectors.
Metal Replacement Market Segmentation
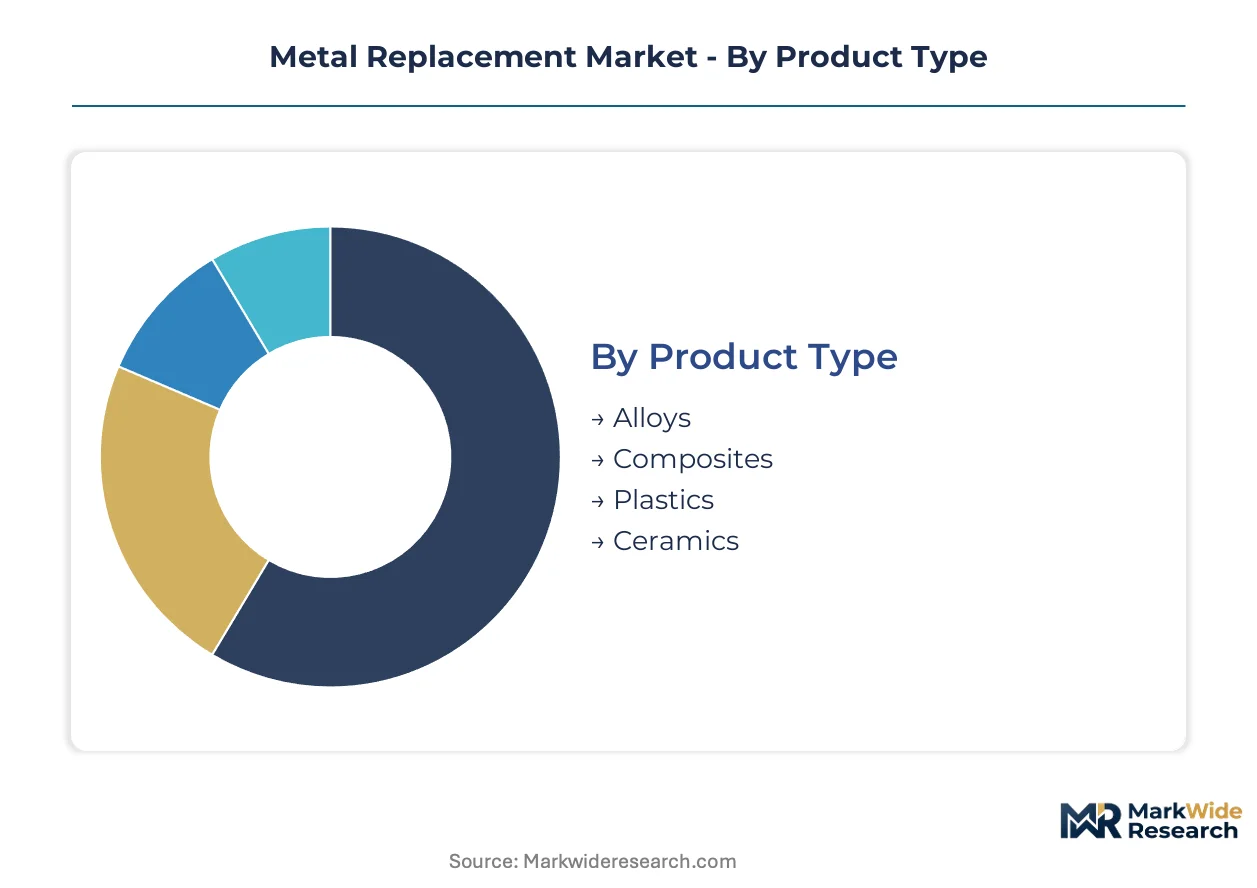
The metal replacement market's segmentation highlights the diverse material science and engineering solutions displacing traditional metals. Understanding these segments is crucial for identifying specific growth vectors and technological shifts driving material innovation and adoption across key industrial applications.
Product Type:
The product type segmentation reveals a spectrum from mature metallic alloys to rapidly emerging advanced composites, each with distinct performance characteristics.
- Composites:These materials, often carbon or glass fiber reinforced polymers, offer superior strength-to-weight ratios and design flexibility for structural components. Demand concentrates in aerospace and high-performance automotive applications, driven by stringent lightweighting and safety mandates.
- Plastics:Engineering plastics like PEEK, PA, and PC provide corrosion resistance and ease of processing through injection molding for various applications. Automotive interiors and consumer electronics represent significant demand centers, seeking cost-effective weight reduction and aesthetic flexibility.
- Alloys:Specialized lightweight alloys, such as advanced aluminum or magnesium variants, offer enhanced performance over conventional metals in specific, high-stress applications.
- Ceramics:High-performance ceramics deliver extreme temperature resistance and hardness for niche applications, often in engine components or industrial wear parts.
Alloys retains volume leadership; Composites holds the steepest expansion curve.
Application:
The application landscape for metal replacement materials is defined by varying performance demands and regulatory pressures across industries.
- Automotive:This sector utilizes metal replacement for vehicle lightweighting, primarily in powertrain components, body panels, and interior structures to meet emissions standards. Europe and China drive extensive adoption, compelled by strict CO2 reduction targets and EV range optimization.
- Aerospace:High-performance composites and specialized alloys replace metals in aircraft fuselages, wings, and interior fittings to enhance fuel efficiency and reduce maintenance cycles. The US and European aviation markets lead in material qualification, driven by FAA and EASA safety protocols.
- Construction:Metal replacement materials provide corrosion-resistant and lighter alternatives for structural elements, rebar, and cladding in infrastructure projects.
- Consumer Electronics:Lightweight plastics and composites reduce device weight and enable complex designs for smartphones, laptops, and other portable electronics.
Automotive applications consistently generate the largest material volumes, while aerospace applications command premium pricing for specialized solutions.
End User:
End-user dynamics for metal replacement materials are shaped by procurement strategies and integration levels within the supply chain.
- OEMs:Original Equipment Manufacturers directly integrate metal replacement components into their final products, dictating material specifications and performance requirements. Automotive and aerospace OEMs in Germany and Japan often co-develop materials with suppliers, ensuring tailored solutions.
- Manufacturers:These entities produce components or sub-assemblies using metal replacement materials, serving various industries as part of a tiered supply structure. Specialized plastic molders and composite fabricators in China and the US represent a significant portion of this segment.
- Suppliers:Material suppliers provide raw or semi-finished metal replacement materials to manufacturers and OEMs, focusing on material science innovation and regulatory compliance.
- Contractors:Construction and infrastructure contractors utilize metal replacement products in their projects, valuing ease of installation and long-term durability.
OEMs exert substantial influence over material selection, while Suppliers play a critical role in delivering specialized component solutions.
Technology:
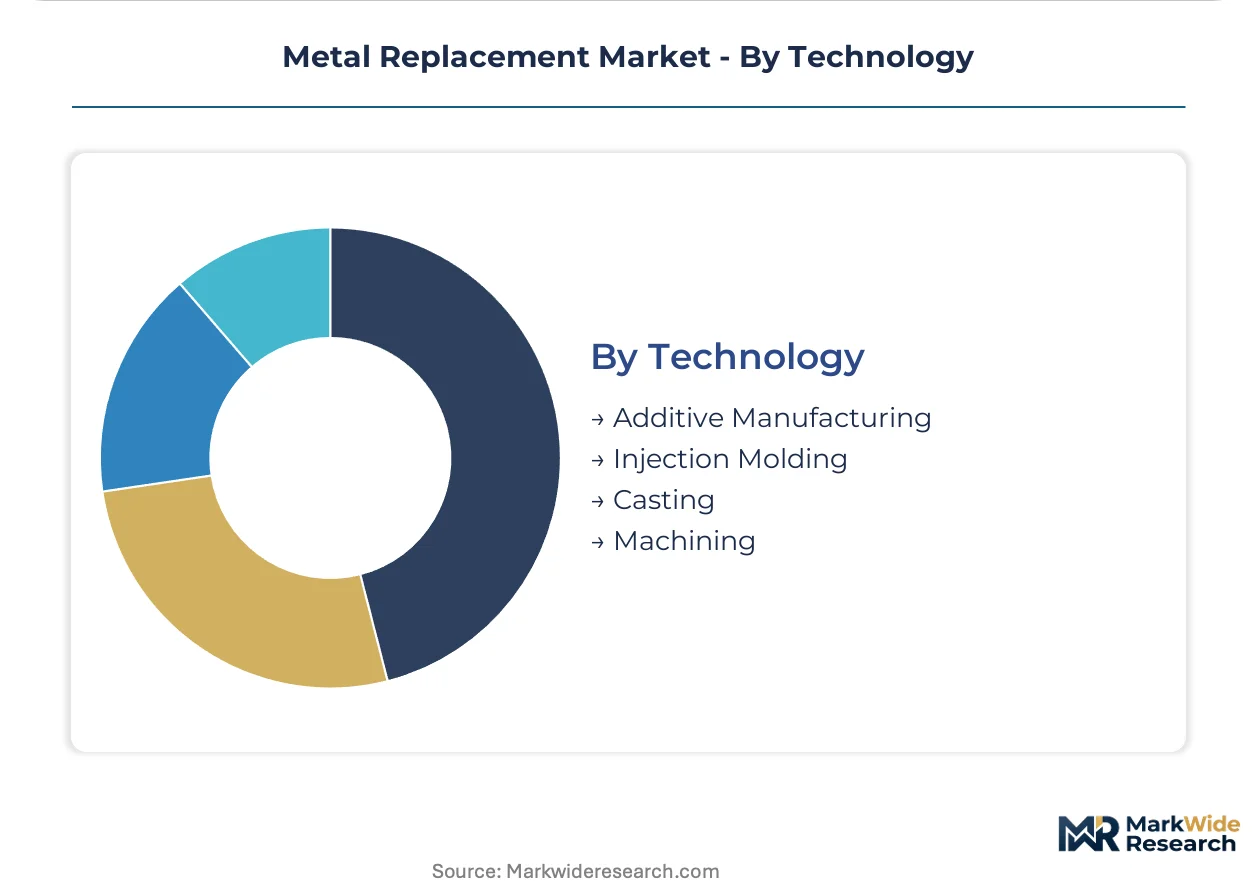
Technological advancements in processing methods are continuously expanding the feasibility and cost-effectiveness of metal replacement solutions.
- Injection Molding:This high-volume manufacturing process forms complex plastic and composite parts by injecting molten material into a mold cavity, offering design freedom and cost efficiency. Automotive interior components and consumer electronics casings frequently leverage this technology for rapid production.
- Additive Manufacturing:Also known as 3D printing, this technology builds parts layer by layer from digital models, enabling intricate geometries and rapid prototyping with advanced polymers and composites. Aerospace and medical device sectors in the US and Europe utilize this for custom, low-volume, high-performance parts.
- Casting:Specialized casting techniques are adapted for certain lightweight alloys and advanced ceramic matrix composites, offering precise part formation.
- Machining:Precision machining processes are employed for finishing complex metal replacement components, particularly for high-tolerance aerospace and medical applications.
Injection Molding sustains its dominance in volume production, whereas Additive Manufacturing shows the most rapid expansion in specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global metal replacement market exhibits a complex interplay of material supply and end-use demand across continents. Export-oriented manufacturing hubs often drive material innovation, while large domestic markets dictate application volumes. This dynamic balance influences regional investment in advanced material production and processing capabilities.
China
China's robust electric vehicle production and expanding aerospace sector drive significant demand for metal replacement materials. The nation's GB standards for materials and stringent dual carbon goals compel extensive adoption of lightweight composites. Manufacturing clusters in the Yangtze River Delta actively integrate advanced plastics into new energy vehicles and aviation components.
United States
Aerospace modernization initiatives and a growing medical device sector propel material replacement demand in the United States. FAA safety protocols and US NHTSA vehicle regulations mandate rigorous testing for high-performance polymers. The Pacific Northwest, particularly around Seattle, remains a hub for composite integration in aircraft structures.
Germany
Germany's advanced automotive industry and precision engineering sectors are prime adopters of metal replacement solutions. The EU Green Deal and REACH framework push for circularity and compliant high-performance materials. Clusters in Baden-Württemberg and Bavaria focus on integrating engineering plastics into vehicle platforms and specialized industrial equipment.
Japan
Japanese automakers and consumer electronics manufacturers increasingly leverage lightweight polymers for performance and design flexibility. JIS standards for materials ensure quality, while METI industrial policies support advanced material research. The Chubu region, centered around Nagoya, remains a critical area for automotive material innovation and production.
India
India's rapidly expanding automotive sector and ambitious infrastructure projects create significant opportunities for metal replacement. BIS standards for materials and the PLI scheme encourage domestic manufacturing of advanced composites. Automotive hubs like Pune in Maharashtra are increasingly exploring polymer-based solutions for vehicle parts.
Metal Replacement Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, diversified chemical producers and specialized material science companies. Vertically integrated giants leverage extensive chemical production scale to offer broad portfolios. Focused specialists often compete through contract production partnerships, enabling agility and niche market penetration. Strategic partnerships and targeted M&A activities represent dominant competitive moves, allowing companies to expand application expertise and geographic reach.
Within the landscape of diversified chemical producers, Germany-based BASF SE exemplifies a vertically integrated approach, leveraging its vast chemical production scale across numerous end-use markets. Belgium-headquartered Solvay SA occupies a position as a specialist in high-performance polymers, particularly for demanding aerospace and automotive applications where stringent performance is critical. Saudi Arabia's SABIC, with its extensive R&D in advanced thermoplastics, represents another global player sustaining market presence through a broad material portfolio and continuous innovation.
| Leading Market Players |
|---|
| BASF SE |
| Celanese Corporation |
| DuPont |
| Toray Industries Inc. |
| Solvay SA |
| SABIC |
| SGL Group |
| Owens Corning Corporation |
| Covestro |
| Others |
Cost & Logistics Intelligence
Underutilized production capacity for specialized polymers in certain regions drives both supplier consolidation and strategic pricing adjustments. This dynamic influences material availability and cost structures for end-use industries.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for critical metal replacement materials. Price differentiation stems from the stringent certification level required by regulators like the FAA or US NHTSA, alongside the specific customization level for complex parts. Upward pricing pressure arises from the fluctuating costs of specialized raw materials, such as carbon fiber precursors and high-performance polymer feedstocks. Aerospace and automotive OEMs exhibit lower price sensitivity for safety-critical components, while consumer electronics manufacturers remain highly sensitive to material costs.
Supply Chain Analysis
Single-source vulnerability for specialized precursors and advanced polymer resins represents a significant structural risk for the metal replacement supply chain. Geographic supply concentration draws heavily from manufacturing hubs in China for EV components, Germany for engineering plastics, and the United States for aerospace composites. Raw material dependencies center on high-performance polymer resins, carbon fiber, and glass fiber. Distribution for these materials primarily runs through direct sales channels to large OEMs and specialized distributors serving smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal replacement market offers fragmentation opportunities as specific demand-side shifts, such as the hydrogen economy build-out, create distinct material niches.
For Market Incumbents: Pre-empt competitive threats by investing in advanced recycling infrastructure for multi-material composites. Strategic partnerships with major automotive and aerospace OEMs ensure early material specification influence against emerging bio-based polymers. Capacity addition in key manufacturing regions, coupled with continuous R&D in sustainable alternatives, strengthens market position. Certification investment, particularly for new material grades, provides a defensible lever against regulatory shifts like the EU Green Deal.
For New Entrants and Emerging Players: Pursue white-space opportunities within medical device components, leveraging biocompatible and sterilizable polymers. The build-out of hydrogen economy infrastructure offers another target, requiring corrosion-resistant composite solutions for storage and transport. Niche industrial applications demanding specific material properties represent a penetrable segment. Rapid prototyping and customization services provide a compelling go-to-market angle for specialized material solutions.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized material science companies possessing proprietary processing technologies or unique intellectual property in advanced polymers. The market exhibits strong long-term viability over the next 5-10 years, driven by persistent lightweighting and sustainability mandates. Progress in large-scale composite recycling technologies serves as a critical signal to watch for inflection in market dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture for Advanced Composites | A joint venture accelerates development of next-generation materials for aerospace applications. |
| Capacity Expansion in Engineering Plastics | Increased capacity supports growing demand from automotive lightweighting initiatives in Europe. |
| Green Manufacturing Transition | Adopting sustainable production processes aligns with circular economy principles and EU REACH regulations. |
| Long-term Supply Agreement with OEMs | Securing long-term contracts stabilizes revenue and provides material specification influence with major vehicle manufacturers. |
| Product Launch: Bio-based Polymer Series | Introducing new bio-based materials addresses sustainability mandates and expands market reach in consumer electronics. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association publications, regulatory documents, and relevant academic research. This approach integrated insights from material science R&D directors, automotive OEM procurement managers, aerospace design engineers, and composite fabricators. Bottom-up and top-down triangulation validated data points across various market segments.
Forecast inputs considered historical trends, technological adoption rates, and the impact of evolving regulatory frameworks across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, technology, and regional automotive production volumes. CAGRs were derived from a weighted average of segment-specific growth trajectories, reflecting anticipated market shifts. Key industry-specific forecast inputs included vehicle lightweighting targets and aerospace build rates.
Sensitivities concentrate around raw material price volatility, shifts in global trade policies, and unforeseen technological breakthroughs that could revise forecasts. Forecasts reflect current market conditions and anticipated regulatory trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Medium Entropy Alloys Market