
 Global CIS Insulin Market | 2026-2036
Global CIS Insulin Market Size, Share, and Industry Trends Forecast 2026-2036
Global CIS Insulin Market Analysis
European API manufacturers is pivoting toward high-purity recombinant insulin production to serve contract manufacturing demand. F. Hoffmann-La Roche Ltd leverages its diagnostic-insulin ecosystem to anchor chronic disease management workflows. Medtronic competes through closed-loop algorithm integration with its pump portfolio. Ypsomed specializes in pen needle miniaturization, occupying a defensible niche in precision delivery devices.
CIS insulin denotes chemically synthesized or recombinant human insulin analogs engineered for specific pharmacokinetic profiles, typically produced via Escherichia coli or Saccharomyces cerevisiae expression systems with ≥98% purity and defined zinc hexamer crystal formulations for subcutaneous depot release. Long-acting insulin dominates value pools due to patent-protected analog premiums and weekly dosing development pipelines, while insulin pumps represent the fastest-expanding delivery mode as patch pump miniaturization reduces patient burden. Rapid-acting insulin maintains maturity in pre-meal correction segments, with margin compression from biosimilar entry offset by volume expansion in emerging markets.
The FDA enforces Current Good Manufacturing Practice for active pharmaceutical ingredients and finished dosage forms, while the EMA's biosimilar guidance mandates extensive immunogenicity profiling that extends development timelines. India's CDSCO aligns with ICH Q5E comparability protocols for insulin analog approvals, creating harmonized but stringent regulatory convergence. Stakeholders must monitor WHO prequalification expansion for insulin access programs and calibrate manufacturing scale decisions against evolving pharmacopeial monograph revisions.
Market Dynamics
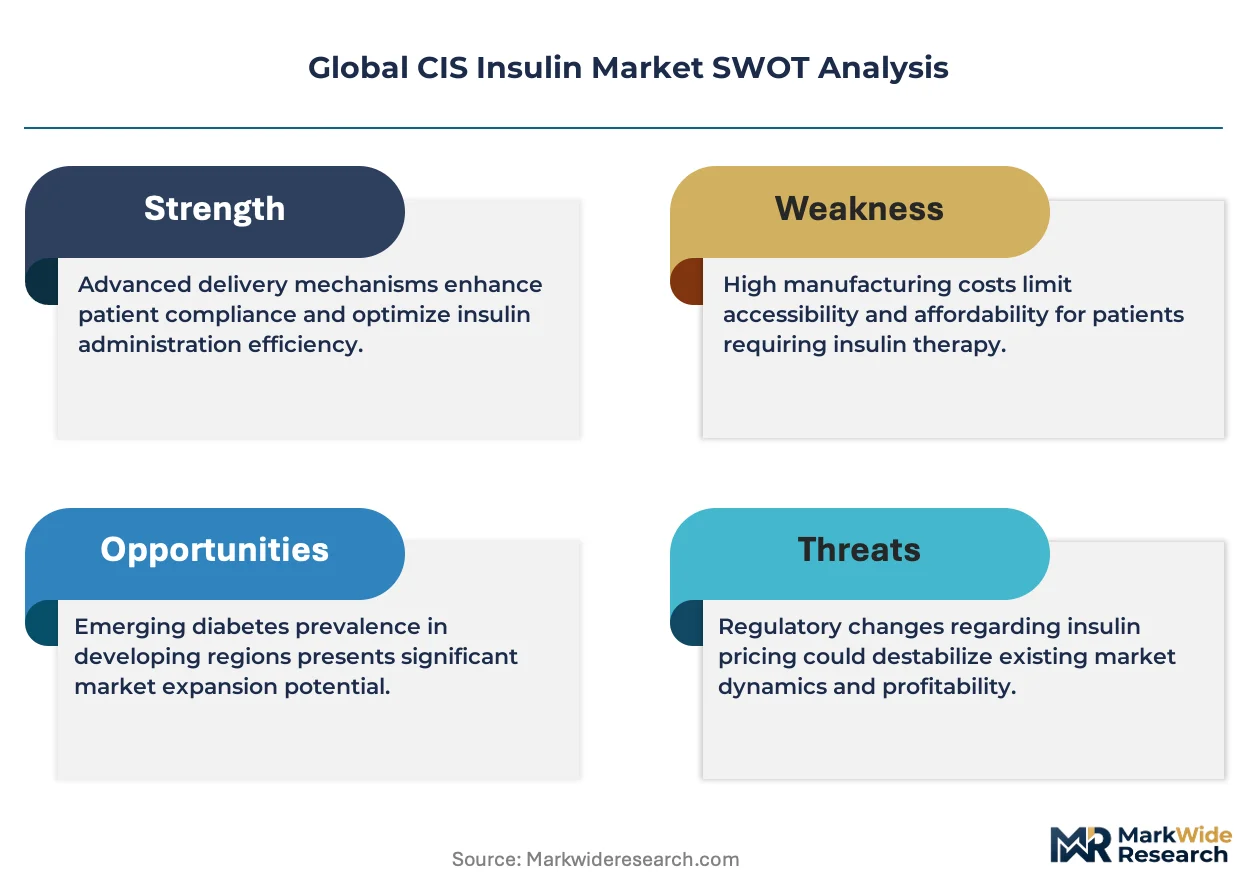
The FDA's evolving biosimilar approval pathway is compressing development timelines for insulin analogs while simultaneously intensifying immunogenicity documentation requirements, forcing manufacturers to recalibrate clinical trial investments against abbreviated pathway savings.
Growth Catalysts
- Home Care Self-Administration:Patients managing type 1 and type 2 diabetes are shifting from clinic-based injections to pen devices and patch pumps, expanding addressable volume for precision delivery formats.
- EMA Biosimilar Guidance Harmonization:Extensive immunogenicity profiling mandates are creating regulatory clarity that accelerates European market entry for second-wave biosimilar developers.
- CDSCO-ICH Q5E Alignment:India's adoption of comparability protocols for insulin analog approvals is unlocking manufacturing scale for export-oriented recombinant production facilities.
Market Restraints
- Active Pharmaceutical Input Concentration:Recombinant insulin production depends on concentrated E. coli and Saccharomyces cerevisiae strain supply from specialized European fermentation houses.
- Cold Chain Infrastructure Gaps:Temperature-controlled distribution requirements for ≥98% purity insulin formulations limit reach into tropical and rural markets lacking validated storage networks.
- GLP-1 Receptor Agonist Substitution:Semaglutide and tirzepatide therapies are capturing oral and injectable diabetes management share among newly diagnosed patients.
Strategic Opportunities
- Brazil ANVISA Accelerated Pathway:South America's largest diabetes population remains underpenetrated by analog insulin relative to human insulin, creating biosimilar substitution potential.
- Closed-Loop Algorithm Convergence:Integration of continuous glucose monitors with automated insulin delivery systems is opening premium hardware-software bundled service models.
- WHO Prequalification Expansion:The agency's insulin access program prequalification is enabling tender participation for manufacturers serving low-income country procurement pools.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:High-purity recombinant insulin manufacturing requires specialized fermentation and downstream purification expertise that outpaces current training pipeline output.
- Legacy Pump System Integration:New rapid-acting analog formulations must demonstrate compatibility with installed Medtronic, Tandem, and Ypsomed pump reservoirs and occlusion detection algorithms.
- Pharmacopeial Monograph Revision Lag:United States Pharmacopeia and European Pharmacopoeia updates to zinc hexamer crystal specifications create batch release uncertainty during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CIS Insulin Market |
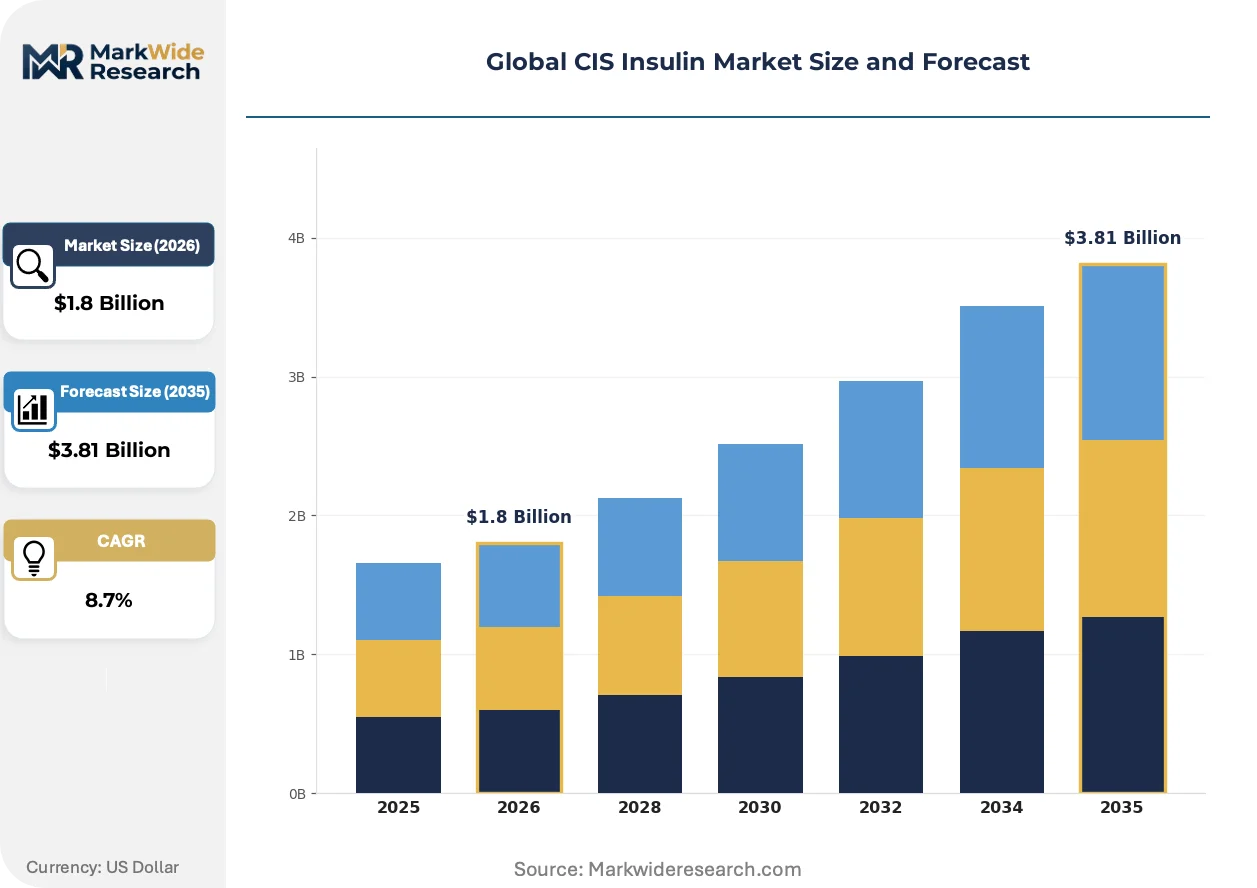
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Premixed Insulin, Intermediate-Acting Insulin Delivery Mode: Insulin Pens, Insulin Syringes, Insulin Pumps, Inhalable Insulin End User: Hospitals, Diabetes Clinics, Home Care, Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes |
| Companies Covered | F. Hoffmann-La Roche Ltd, CeQur Simplicity, Medtronic, B. Braun SE, BD, Insulet Corporation, Ypsomed, ZEALAND PHARMA, Tandem Diabetes Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CIS Insulin Market Emerging Trajectories
Bioprocess automation and algorithm-driven delivery systems are restructuring how insulin is manufactured, regulated, and administered. Three developments are compressing legacy operating models while opening new value capture mechanisms.
Single-use bioreactor systems are decentralizing recombinant insulin production from centralized stainless-steel facilities to modular, deployable manufacturing units. Contract manufacturers in Switzerland and Singapore are adopting these systems to reduce cross-contamination risk and accelerate batch turnaround. This technology is decentralizing geographic production concentration that has historically anchored supply in Western European fermentation clusters.
The EU's Medical Device Regulation (MDR) is reclassifying insulin pumps and automated delivery systems into higher-risk categories requiring notified body intervention and clinical evidence renewal. Manufacturers must now maintain post-market surveillance systems that track real-world algorithm performance across diverse patient glycemic profiles. Patch pump miniaturization developers are responding by front-loading clinical validation to secure CE marking ahead of 2027 certificate expiration waves.
Pharmacy benefit managers and national tender authorities are consolidating procurement decisions around total cost-of-care metrics rather than per-vial pricing. United States integrated delivery networks are negotiating multi-year insulin supply contracts that bundle rapid-acting, long-acting, and delivery device categories under single-source agreements. This behavioral shift is most visible in Medicare Advantage plan formularies, where preferred product positioning now requires demonstrated hypoglycemia reduction in real-world evidence datasets.
Global CIS Insulin Market Segmentation
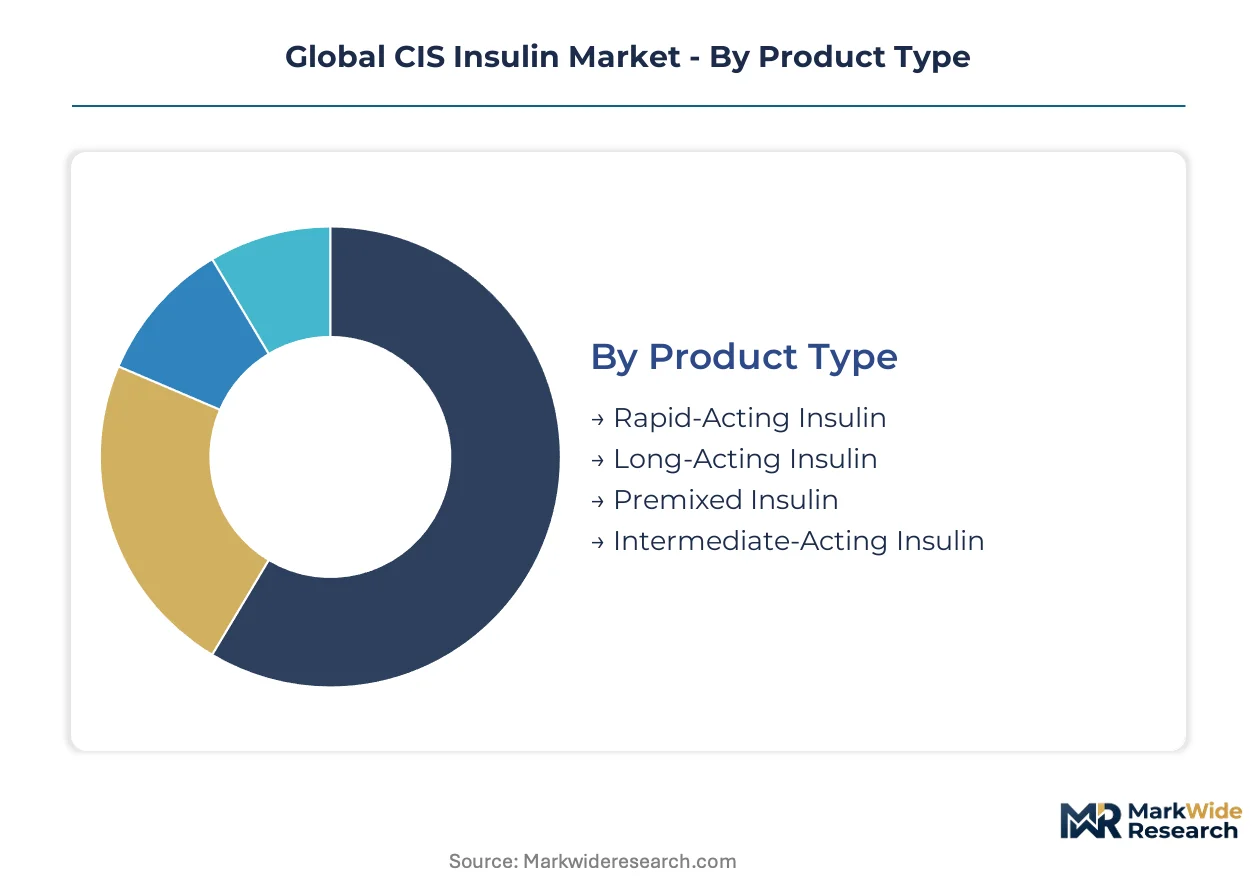
Insulin market segmentation reveals distinct upgrade cycles across pharmacokinetic profiles, delivery technologies, and care settings. Patient migration patterns between segments determine manufacturer R&D prioritization and pricing architecture.
Product Type:
Replacement cycles accelerate as patients shift from human insulin toward analog formulations with flatter glucose curves and reduced hypoglycemia risk.
- Long-Acting Insulin:Basal analogs engineered for 24-hour glucose suppression with minimal peak activity command premium positioning in the United States and Germany. Patent-protected formulations like insulin glargine and degludec sustain value pools despite biosimilar erosion in European tenders.
- Rapid-Acting Insulin:Prandial correction analogs with 15-minute onset profiles dominate pre-meal dosing protocols in Japan and the United Kingdom. Volume expansion in Brazil and India offsets margin compression from lispro and aspart biosimilar entry.
- Premixed Insulin:Fixed-ratio basal-bolus combinations retain stronghold in China's tier-2 cities where physician preference favors simplified regimens.
- Intermediate-Acting Insulin:NPH formulations persist in WHO procurement programs and cash-constrained markets lacking cold chain reliability for analog storage.
Volume placements concentrate in long-acting analogs; the faster expansion belongs to rapid-acting biosimilars.
Delivery Mode:
Cost stratification separates precision delivery hardware from commodity injection formats, with reimbursement tiering determining access patterns.
- Insulin Pumps:Patch pump miniaturization and closed-loop algorithm integration are restructuring diabetes management in Sweden and the Netherlands. Tandem and Medtronic systems command hardware-software bundled contracts with United States integrated delivery networks.
- Insulin Pens:Disposable and reusable pen devices balance convenience against per-unit cost in France and Italy where pharmacy benefit managers negotiate tender pricing.
- Insulin Syringes:Vial-and-syringe administration persists in India's government procurement channels and rural clinics with limited device reimbursement.
- Inhalable Insulin:Pulmonary delivery systems occupy niche positioning for needle-averse patients in Saudi Arabia's private healthcare sector.
Insulin pens capture the highest prescription volumes; pump adoption is climbing the fastest among type 1 diabetes populations.
End User:
Patient self-management capabilities determine site-of-care distribution, with reimbursement infrastructure shaping migration between institutional and ambulatory settings.
- Home Care:Self-administration via pen devices and personal pumps dominates United States and United Kingdom volume as diabetes educators certify patient injection competency.
- Hospitals:Inpatient glycemic control protocols in Germany and Australia require intravenous insulin infusion capabilities and pharmacy-compounded correction doses.
- Diabetes Clinics:Specialist-led titration programs in Canada's provincial health systems manage complex patients transitioning to pump therapy.
- Pharmacies:Community dispensing with pharmacist counseling anchors access in Spain and Mexico where primary care physician density is limited.
Home care channels absorb the majority of analog prescriptions; diabetes clinics are gaining share fastest among pump-naive patient conversions.
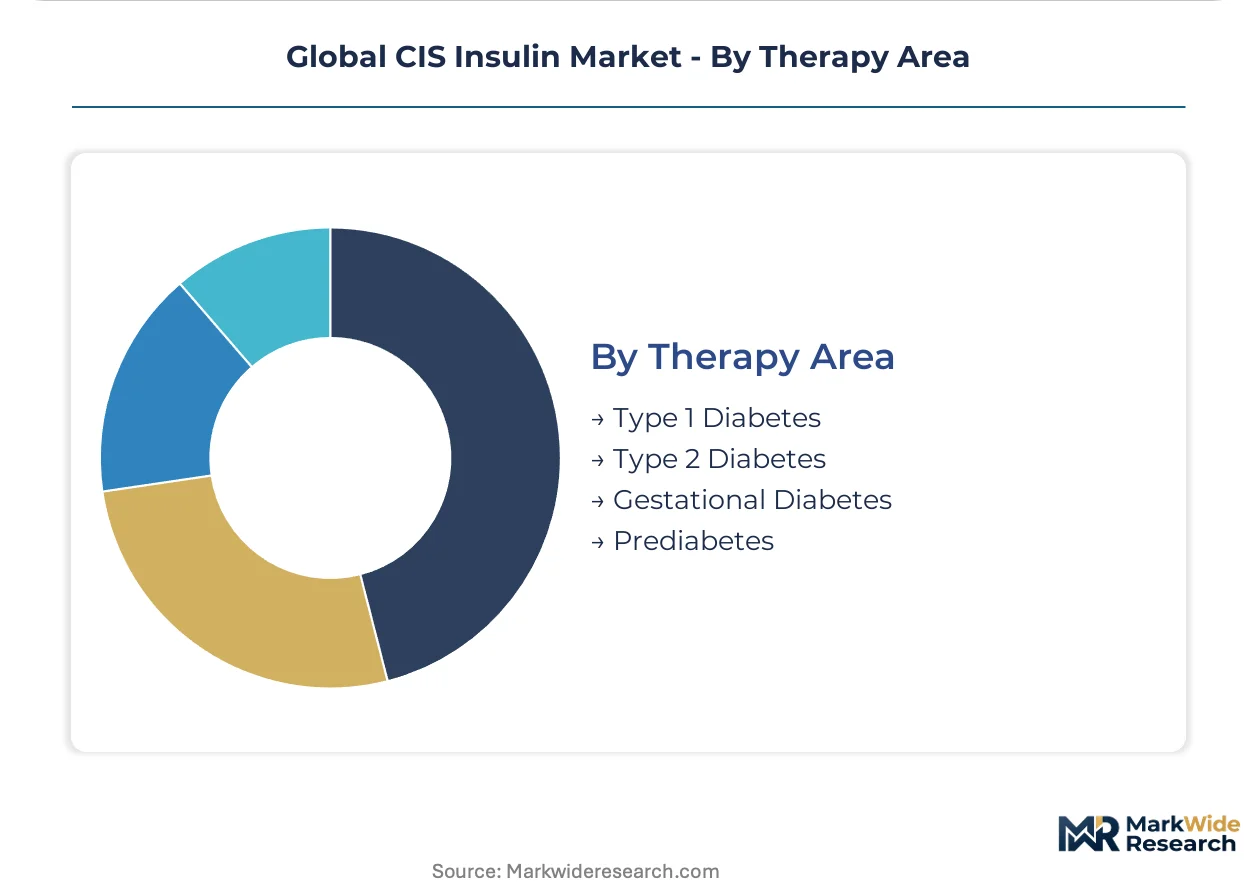
Therapy Area:
Disease severity and progression stage dictate insulin initiation timing, with earlier intervention expanding addressable populations.
- Type 2 Diabetes:Progressive beta-cell failure drives basal insulin addition after oral agent exhaustion in the United States, China, and Brazil. GLP-1 agonist co-prescription is delaying but not eliminating insulin dependency.
- Type 1 Diabetes:Absolute insulin deficiency mandates lifelong exogenous replacement from diagnosis, with pump penetration highest in Nordic countries and lowest in Eastern European markets.
- Gestational Diabetes:Pregnancy-specific glycemic targets require human insulin preference over unstudied analogs in India's tertiary maternity centers.
- Prediabetes:Pharmacologic intervention remains off-label in most jurisdictions, though metformin-intolerant subpopulations in Japan receive basal insulin trials.
Type 2 diabetes generates the largest prescription volumes; type 1 diabetes shows the steepest per-patient value capture through device bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant insulin fermentation capacity clusters in Basel, Switzerland, and Hillerød, Denmark, anchoring European supply chains for high-purity active pharmaceutical ingredients. These facilities feed formulation plants across multiple continents, with distribution networks extending into patient self-administration markets.
United States
Type 1 and type 2 diabetes prevalence drives basal analog consumption through Medicare Advantage formularies. FDA biosimilar pathway refinements compress approval timelines for insulin glargine and lispro alternatives. Indianapolis and Cambridge, Massachusetts, host integrated delivery network contracting headquarters where pharmacy benefit managers negotiate bundled device-drug agreements.
Germany
Statutory health insurance reimbursement tiers favor long-acting analogs with demonstrated hypoglycemia reduction profiles. EMA immunogenicity documentation requirements create regulatory clarity that accelerates second-wave biosimilar market entry. Frankfurt and Munich anchor diabetes clinic networks managing complex pump-naive patient conversions to automated delivery systems.
India
Government procurement channels maintain NPH human insulin volumes for tier-2 and tier-3 cities lacking cold chain infrastructure for analog storage. CDSCO alignment with ICH Q5E comparability protocols streamlines recombinant insulin analog approvals for export-oriented manufacturers. Hyderabad and Ahmedabad fermentation clusters supply high-purity active pharmaceutical ingredients to formulation facilities serving Southeast Asian tender markets.
Brazil
ANVISA accelerated approval pathways enable biosimilar substitution from human insulin toward glargine and degludec analogs among newly diagnosed type 2 diabetes patients. SUS public procurement pools concentrate demand in São Paulo and Rio de Janeiro metropolitan diabetes clinics. Patch pump miniaturization trials are expanding in private healthcare networks serving needle-averse patient segments.
Japan
PMDA post-approval surveillance requirements for novel insulin formulations extend real-world evidence collection periods beyond European benchmarks. Metformin-intolerant prediabetes subpopulations receive off-label basal insulin trials in Tokyo and Osaka tertiary centers. Yokohama bioprocess engineering clusters specialize in single-use bioreactor systems for modular recombinant protein production.
Global CIS Insulin Market Vendor Landscape
Global majors compete with regional champions across device-drug integration depth, with market structure consolidating around three strategic tiers. Integrated pharmaceutical-diagnostic ecosystems anchor premium positioning through chronic disease management workflow capture. Specialized delivery device manufacturers occupy defensible niches in precision injection technologies. Pure-play insulin analog developers compete on biosimilar cost positioning and manufacturing scale. Dominant competitive moves include algorithm licensing partnerships between pump manufacturers and continuous glucose monitor developers, plus backward integration into recombinant fermentation capacity by formulation specialists.
Within the integrated ecosystem tier, F. Hoffmann-La Roche Ltd exemplifies diagnostic-insulin convergence strategies, while Medtronic anchors automated delivery system hardware-software bundling. Among specialized device manufacturers, Ypsomed occupies a position in pen needle miniaturization and precision delivery formats. These three entities represent distinct competitive archetypes: diagnostic-platform integrators, closed-loop algorithm developers, and precision hardware specialists.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| CeQur Simplicity |
| Medtronic |
| B. Braun SE |
| BD |
| Insulet Corporation |
| Ypsomed |
| ZEALAND PHARMA |
| Tandem Diabetes Care |
| Others |
Supply Flow & Price Mechanics
High-purity recombinant insulin production costs cascade from specialized E. coli and Saccharomyces cerevisiae strain procurement through European fermentation houses into three-tier pricing structures across premium, standard, and economy levels. Cold chain logistics expenditures for temperature-controlled distribution amplify geographic price stratification between United States Medicare Advantage formularies and India's government procurement channels.
Pricing Analysis
Warranty and service bundling separates pump manufacturers offering algorithm update subscriptions from unbundled pen device suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery technology sophistication, with closed-loop systems commanding hardware-software bundled premiums. Cost compression in rapid-acting biosimilars intensifies because of ANVISA accelerated pathway entry, while pharmacy benefit managers in United States integrated delivery networks exhibit highest price sensitivity through total cost-of-care negotiations.
Supply Chain Analysis
Reverse logistics for insulin pump refurbishment and reservoir recycling flows from patient returns through authorized service centers into remanufacturing facilities. Supply concentrates in Switzerland, Denmark, and India, drawing from recombinant protein expression systems, zinc hexamer crystal formulations, and single-use bioreactor components. Single-source vulnerability in specialized yeast strain supply from Basel fermentation clusters threatens batch continuity. Distribution runs through validated cold chain networks anchored by regional formulation plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into recombinant fermentation capacity anchors competitive positioning as manufacturers race to capture upstream margin pools and secure strain supply continuity against bioprocess engineering talent scarcity.
For Market Incumbents: To counter GLP-1 receptor agonist substitution in newly diagnosed type 2 diabetes, incumbents should deepen closed-loop algorithm integration with continuous glucose monitor partners and expand manufacturing scale in Hyderabad fermentation clusters serving Southeast Asian tender markets. For New Entrants and Emerging Players: The price-point gap between patent-protected long-acting analog premiums and NPH human insulin economy tiers offers entry space for biosimilar developers targeting Brazil's ANVISA accelerated pathway and India's CDSCO-aligned export manufacturing. For Investors and Strategic Acquirers: FDA biosimilar pathway refinement completion is the leading indicator that abbreviated approval timelines will compress development risk-return profiles. Viability over the coming decade rests on identifying modular single-use bioreactor specialists with demonstrated EMA immunogenicity documentation capabilities. Monitor WHO prequalification expansion announcements for tender access inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captures upstream margin pools and secures E. coli strain supply continuity against European concentration. |
| Closed-Loop Algorithm Licensing Partnership | Enables Medtronic and Tandem hardware-software bundling with continuous glucose monitor data streams. |
| WHO Prequalification Pathway Completion | Unlocks low-income country tender participation for manufacturers serving procurement pools. |
| Single-Use Bioreactor Modular Deployment | Reduces cross-contamination risk and accelerates batch turnaround for contract manufacturers in Singapore. |
| EMA MDR Clinical Evidence Renewal | Satisfies notified body intervention requirements for insulin pump reclassification ahead of certificate expirations. |
Methodological Framework
Document review covered FDA biosimilar pathway guidance documents, EMA immunogenicity profiling requirements, and CDSCO-ICH Q5E alignment protocols, complemented by interviews with bioprocess engineering directors, regulatory affairs leads at insulin analog developers, pharmacy benefit manager formulary directors, and hospital procurement managers. Secondary validation drew from ClinicalTrials.gov entries, WHO prequalification databases, and United States Pharmacopeia monograph revisions. Bottom-up patient volume modeling and top-down value pool estimation provided triangulation checks.
Projections across the analysis window reflect segment-level modeling by pharmacokinetic profile, delivery technology, and care setting, with CAGRs derived from patient migration patterns between human insulin and analog formulations. Inputs included diabetes prevalence trajectories, reimbursement tier evolution, and cold chain infrastructure expansion rates in tropical markets.
Inputs from EMA post-market surveillance systems and ANVISA approval databases were available through the study window; gaps in real-world hypoglycemia reduction evidence introduce uncertainty bands around formulary positioning assumptions. Practitioners should monitor GLP-1 agonist co-prescription rates and WHO prequalification expansion triggers for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Global Flu Vaccine Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market