
 Fenbendazole Market | 2026-2036
Fenbendazole Market Size, Share, and Industry Trends Forecast 2026-2036
Fenbendazole Market Insights
Companion animal clinics are rotating toward fenbendazole protocols for canine and feline parasitic management, pulling demand from traditional livestock channels. Zoetis LLC leverages its veterinary distribution network to sustain branded parasiticide positioning across multiple species. Boehringer Ingelheim International GmbH anchors its portfolio through R&D intensity in anthelmintic formulations. Merck & Co., Inc. competes on manufacturing scale for bulk active pharmaceutical ingredient supply to generic compounders.
Fenbendazole is a benzimidazole anthelmintic compound with broad-spectrum activity against nematodes, formulated as granules, tablets, powder, or injectable suspensions with varying particle sizes and dissolution profiles for species-specific bioavailability. Its primary commercial purpose centers on gastrointestinal parasite control in food-producing animals and companion species, with powder formulations dominating volume sales to agricultural integrators while tablet and granule formats command premium positioning in companion animal and research institution channels. Injectable delivery modes capture specialized veterinary clinic demand despite higher per-dose costs. Oral formulations remain the mature baseline across all end user segments, with mixed formulations representing the fastest-growing innovation area as manufacturers blend fenbendazole with other antiparasitic actives to address resistance patterns.
FDA Center for Veterinary Medicine oversees fenbendazole approval pathways and residue tolerance limits in the United States, while EMA veterinary product standards govern European market access and withdrawal period labeling. Brazil's national agricultural regulator enforces export-certification requirements that shape product formulation choices for beef and dairy operations. Stakeholders must monitor evolving resistance surveillance data and regulatory pressure on anthelmintic stewardship to align portfolio investments with shifting veterinary practice standards.
Market Dynamics
Parasitic resistance to legacy anthelmintics is forcing livestock producers toward fenbendazole rotation protocols, while regulatory tightening on residue monitoring reshapes formulation and withdrawal period requirements across veterinary supply chains.
Growth Catalysts
- EMA Veterinary Product Standards:Harmonized withdrawal period labeling across European member states reduces regulatory friction for cross-border veterinary pharmaceutical trade, accelerating product registration timelines for manufacturers.
- Brazilian Beef Export Certification:ANVISA enforcement of residue limits for international markets drives adoption of fenbendazole protocols with documented pharmacokinetic profiles in cattle operations supplying EU and Middle Eastern buyers.
- Companion Animal Channel Expansion:Small-animal veterinary clinics are incorporating fenbendazole into canine and feline wellness programs, diversifying demand beyond traditional agricultural end-uses.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Bulk fenbendazole API production concentrates among a limited set of chemical manufacturers in India and China, creating supply vulnerability for downstream formulators.
- Generic Price Compression:Patent-expired status of fenbendazole enables commoditized powder formulations that erode margin structures for branded veterinary pharmaceutical portfolios.
- Antiparasitic Stewardship Mandates:FDA Center for Veterinary Medicine guidance documents on judicious anthelmintic use impose documentation burdens that lengthen sales cycles for veterinary distributors.
Strategic Opportunities
- Mixed Formulation Development:Combination products blending fenbendazole with novel antiparasitic actives address emerging resistance patterns and command premium positioning in large-animal veterinary channels.
- Injectable Suspension Segment:Specialized veterinary clinics in North American metropolitan markets demonstrate willingness to absorb higher per-dose costs for parenteral delivery systems with improved bioavailability profiles.
- Research Institution Procurement:Academic and government laboratory demand for pharmaceutical-grade fenbendazole in oncology and cell biology research creates non-agricultural revenue streams with stable pricing.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Veterinary pharmaceutical manufacturers face competition for skilled personnel capable of optimizing particle size distribution and dissolution profiles for species-specific bioavailability.
- Multi-Jurisdiction Registration Complexity:Divergent residue tolerance limits between FDA, EMA, and ANVISA require parallel regulatory dossier preparation, extending time-to-market for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fenbendazole Market |
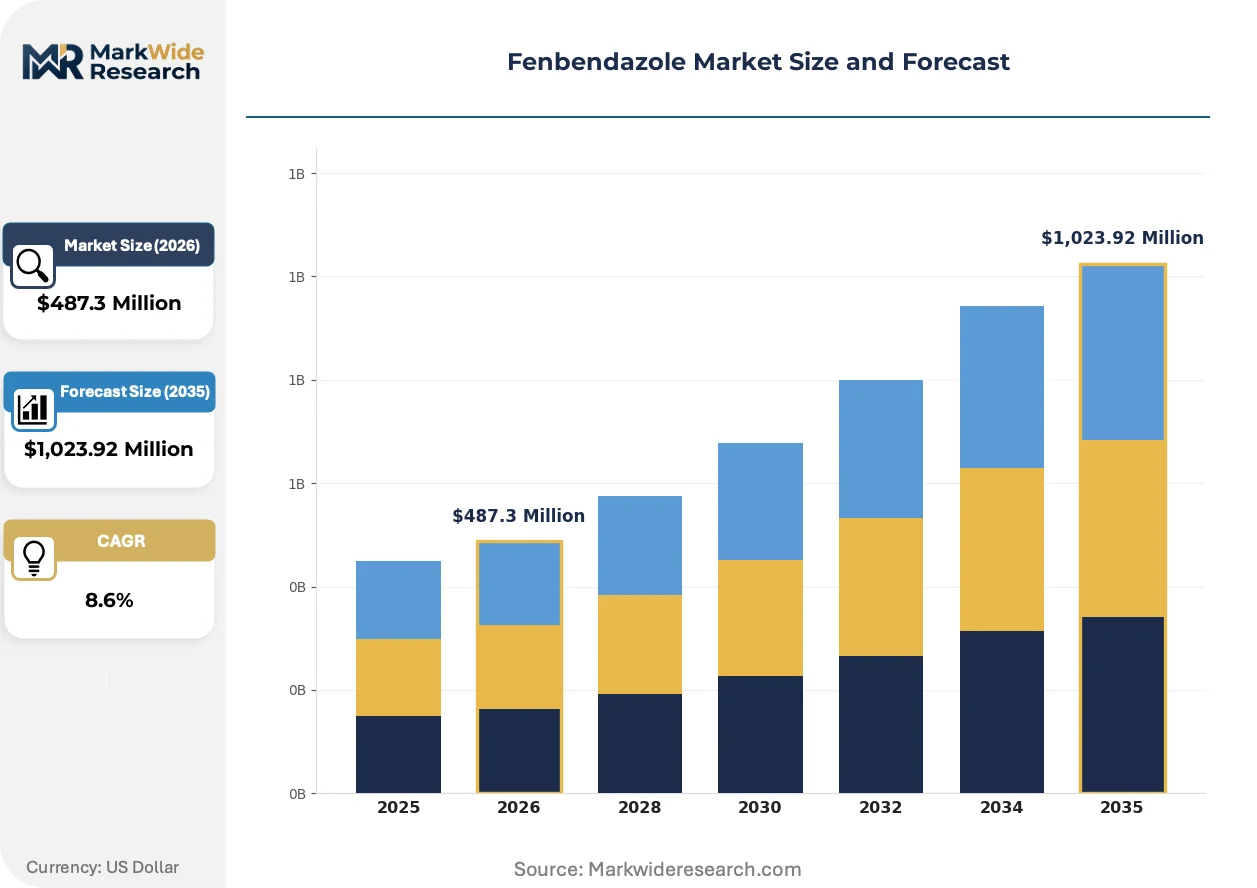
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Tablets, Powder, Injectable Application: Veterinary Medicine, Agricultural Use, Livestock Treatment, Companion Animals End User: Farmers, Veterinarians, Pet Owners, Research Institutions Delivery Mode: Oral, Parenteral, Topical, Mixed Formulations |
| Companies Covered | Zoetis LLC, Elanco Animal Health Incorporated, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Ceva Santé Animale S.A., Vetoquinol S.A., Virbac S.A., Dechra Pharmaceuticals PLC, Shaanxi Hanjiang Pharmaceutical Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fenbendazole Market Trends and Innovations
Fenbendazole product architectures are diversifying rapidly as manufacturers respond to resistance surveillance data and shifting channel economics across agricultural and companion animal segments.
Nano-milling and micronization technologies for particle size reduction are fragmenting competitive positioning in oral formulation segments. Veterinary pharmaceutical manufacturers adopting sub-10-micron particle engineering capture differential bioavailability advantages in ruminant applications. This technical capability is fragmenting procurement decisions, with large-scale cattle integrators now specifying dissolution profile parameters in supply agreements rather than accepting standard-grade powder.
EMA's revised guidelines on environmental risk assessment for veterinary medicinal products impose expanded aquatic toxicity testing requirements on fenbendazole registrants. Manufacturers must now submit sediment organism study data for products with predicted environmental concentrations above threshold limits. Cattle and swine formulation specialists in Germany and the Netherlands are restructuring R&D budgets to accommodate extended ecotoxicology timelines.
Direct purchasing relationships between agricultural integrators and API suppliers are compressing traditional veterinary distribution margins. Large beef and dairy operations in the United States are negotiating volume contracts for fenbendazole powder that bypass branded pharmaceutical intermediaries. This channel restructuring concentrates price leverage among buyers with sufficient scale to justify dedicated quality assurance and logistics functions.
Fenbendazole Market Segmentation
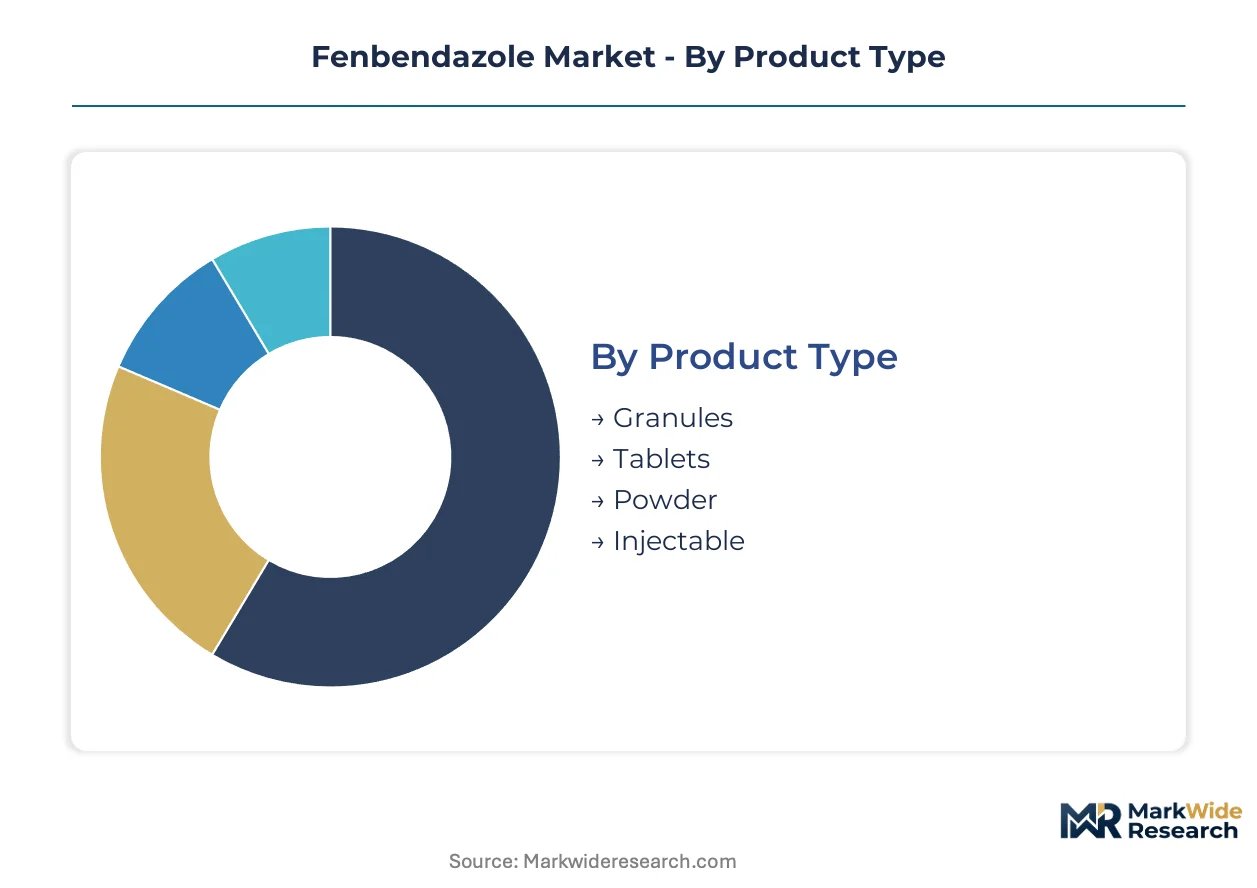
Fenbendazole market segmentation reveals divergent margin structures across formulation types and delivery channels. Agricultural integrators prioritize cost-efficient bulk powder procurement, while companion animal clinics absorb premium pricing for precision-dosed formats. Understanding these segment economics guides portfolio allocation for veterinary pharmaceutical manufacturers.
Product Type:
Margin pools concentrate in specialized formats where bioavailability engineering commands pricing power, while commodity powder segments compete on manufacturing scale.
- Granules:Intermediate particle size distribution enables flexible dosing across species weights. Demand clusters in companion animal clinics serving mixed-breed canine populations, where ease of administration drives protocol adherence.
- Tablets:Precision-compressed formulations with defined dissolution profiles support regulatory documentation for residue-sensitive export markets. Veterinary distributors in metropolitan North American markets capture premium positioning through tablet-based wellness programs.
- Powder:Bulk active formulations dominate volume procurement by cattle feedlot operators and swine integrators seeking cost-efficient herd-level parasitic control.
- Injectable:Parenteral suspensions with extended-release characteristics address compliance challenges in large ruminant operations where oral administration proves labor-intensive.
The dominant share belongs to Powder, while Injectable is closing the gap fastest.
Application:
Volume concentration varies sharply between production agriculture and clinical veterinary channels, with regulatory intensity shaping profitability across each.
- Veterinary Medicine:Clinical protocols emphasizing evidence-based parasite management drive formulation standardization. Small-animal practices in the United States incorporate fenbendazole into routine wellness screening.
- Agricultural Use:Herd-level prophylaxis programs in Brazilian beef operations require documented withdrawal compliance for EU export certification. ANVISA residue monitoring shapes product selection criteria.
- Livestock Treatment:Therapeutic interventions in dairy cattle target gastrointestinal nematode burdens affecting feed conversion efficiency. Large-scale operations specify pharmacokinetic profile documentation.
- Companion Animals:Canine and feline parasitic management protocols expand fenbendazole utilization beyond traditional agricultural endpoints. Urban veterinary clinics absorb higher per-dose costs for palatable formulations.
Agricultural Use holds the largest volume position, though Companion Animals demonstrates the steepest expansion trajectory.
End User:
Procurement sophistication diverges dramatically between institutional buyers and individual consumers, fragmenting pricing architecture.
- Farmers:Production-scale operators negotiate direct API supply agreements, compressing traditional distribution margins. Feedlot enterprises in the United States maintain captive quality assurance functions.
- Veterinarians:Clinical practitioners prioritize formulation reliability and regulatory documentation over unit cost considerations. Metropolitan practice groups consolidate purchasing through group procurement organizations.
- Pet Owners:Retail-accessible formats with palatability enhancements support compliance in home-administered protocols. E-commerce channels displace traditional veterinary pharmacy relationships.
- Research Institutions:Academic and government laboratories require pharmaceutical-grade material with batch certification for oncology and cell biology applications. Pricing stability characterizes this non-agricultural demand segment.
Farmers command the dominant procurement volume, yet Research Institutions deliver the most stable margin profile.
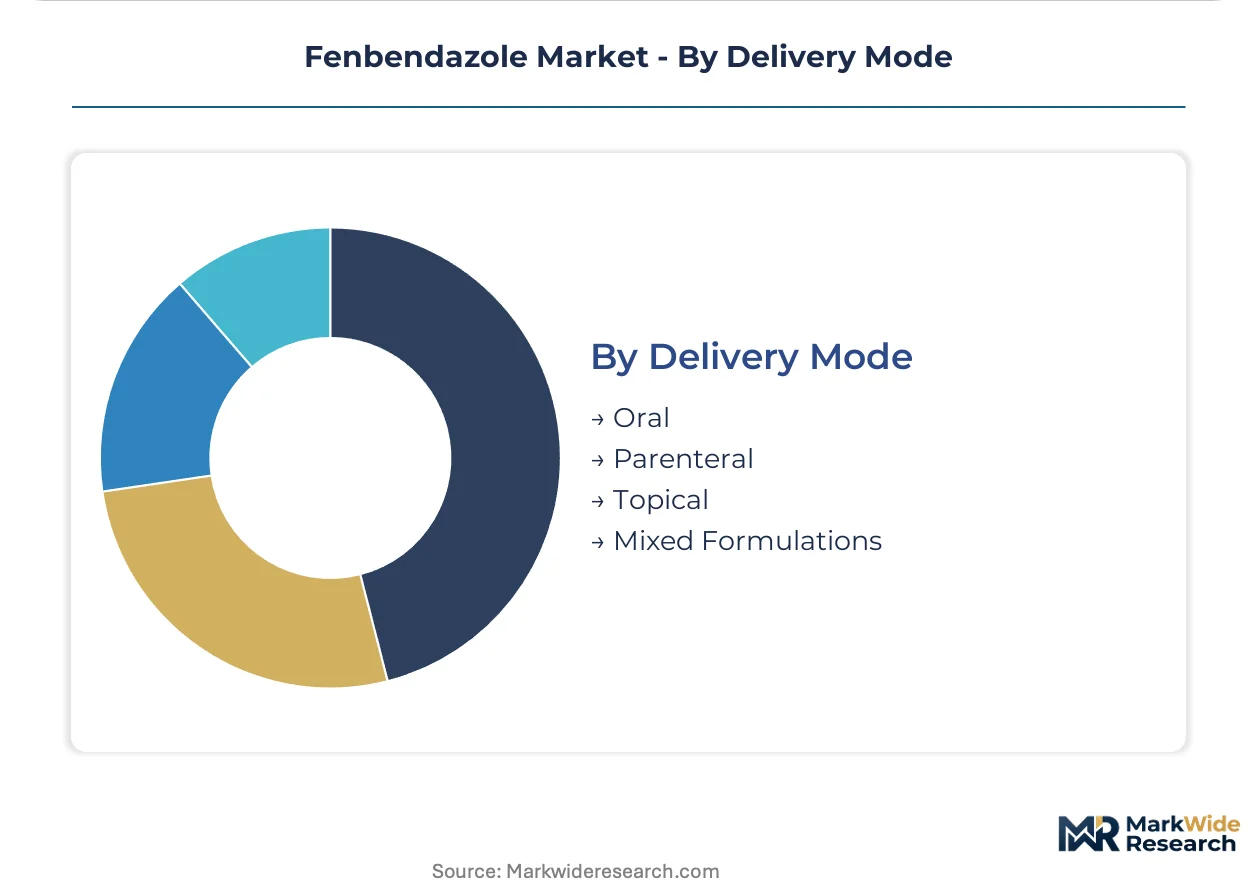
Delivery Mode:
Technical complexity in formulation engineering creates tiered competitive positioning across administration routes.
- Oral:Mature baseline administration route with established bioavailability profiles across species. Granule and tablet formats dominate companion animal and production livestock applications.
- Parenteral:Injectable suspensions with optimized particle size distribution enable extended-release characteristics. Specialized veterinary clinics absorb premium pricing for improved compliance in large-animal settings.
- Topical:Transdermal absorption formulations address administration challenges in fractious animals. Limited commercial penetration constrains segment scale.
- Mixed Formulations:Combination products blending fenbendazole with complementary antiparasitic actives address emerging resistance patterns. Manufacturers capture premium positioning through multi-mechanism efficacy claims.
Oral maintains the foundational share, though Mixed Formulations gains share most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos in São Paulo state anchors Brazilian fenbendazole distribution networks, channeling pharmaceutical-grade formulations from domestic manufacturers into cattle feedlot operations serving Middle Eastern and European export markets. This maritime infrastructure underwrites Brazil's position as the primary volume aggregator for Latin American parasiticide demand.
United States
Large-scale cattle feedlot operators in Texas and Kansas negotiate direct API procurement contracts, bypassing traditional veterinary distribution channels. FDA Center for Veterinary Medicine residue tolerance enforcement shapes formulation selection criteria for export-bound beef. Metropolitan veterinary clinic networks in Chicago and Denver absorb premium pricing for companion animal tablet formats.
Brazil
Beef export certification requirements from ANVISA drive adoption of documented pharmacokinetic protocols in São Paulo and Mato Grosso cattle operations. Parasitic resistance surveillance programs in the Cerrado biome accelerate rotation toward fenbendazole-based deworming schedules. Domestic pharmaceutical manufacturers in Osasco cluster supply regional integrators with cost-efficient powder formulations.
Germany
EMA veterinary product standards harmonize withdrawal period labeling across Bavarian and Lower Saxony dairy operations supplying EU-wide distribution networks. Environmental risk assessment guidelines impose expanded aquatic toxicity testing on registrants in the Rhine-Ruhr pharmaceutical manufacturing belt. Specialized veterinary clinics in Munich demonstrate demand for precision-dosed granule formats.
China
Bulk active pharmaceutical ingredient production concentrates in Zhejiang and Jiangsu province chemical manufacturing zones, supplying downstream formulators across Asia-Pacific markets. NMPA veterinary drug registration pathways shape export-oriented formulation development. Shanghai-based trading houses coordinate powder shipments to Southeast Asian livestock integrators.
India
CDSCO regulatory frameworks govern fenbendazole manufacturing licensure for domestic veterinary and research institution channels. Pharmaceutical API specialists in Hyderabad and Ahmedabad supply generic compounders with intermediate-grade material. Maharashtra-based cattle cooperatives incorporate fenbendazole into documented herd health programs for dairy export compliance.
Fenbendazole Market Competitive Landscape
Concentration sits with diversified veterinary pharmaceutical conglomerates that leverage cross-species distribution networks and manufacturing scale. The competitive structure fragments between branded formulation specialists and commodity powder suppliers, with regulatory documentation capabilities serving as the primary differentiation mechanism. Three archetypes dominate: integrated animal health conglomerates with multi-species portfolios, regional API manufacturers supplying generic compounders, and specialized research-grade suppliers serving academic laboratories. Dominant competitive moves include portfolio diversification into combination antiparasitic formulations and backward integration into captive API production.
Among US-based animal health conglomerates, Zoetis LLC and Merck & Co., Inc. occupy positions spanning both livestock and companion animal channels. German GmbH-structured Boehringer Ingelheim International GmbH exemplifies the R&D-intensive archetype with anthelmintic formulation depth. French S.A.-incorporated entities including Ceva Santé Animale S.A. and Vetoquinol S.A. represent European specialists with concentrated veterinary pharmaceutical focus. Chinese Co., Ltd.-structured Shaanxi Hanjiang Pharmaceutical Group Co., Ltd. anchors the API supply tier for regional formulators.
| Leading Market Players |
|---|
| Zoetis LLC |
| Elanco Animal Health Incorporated |
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Ceva Santé Animale S.A. |
| Vetoquinol S.A. |
| Virbac S.A. |
| Dechra Pharmaceuticals PLC |
| Shaanxi Hanjiang Pharmaceutical Group Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Indian and Chinese API manufacturing clusters shapes both supply concentration and price floors for downstream formulators. Large-scale agricultural integrators leverage volume procurement to compress margins on commodity powder grades, while companion animal clinics absorb premium pricing for precision-dosed tablet and injectable formats.
Pricing Analysis
Volume-discount tiering structures stratify fenbendazole procurement across three distinct buyer archetypes. Agricultural integrators purchasing multi-ton powder lots command economy-tier pricing, while metropolitan veterinary clinics absorb standard-tier rates for granule formats, and research institutions pay premium-tier rates for pharmaceutical-grade certification. Price differentiation hinges on batch certification documentation and dissolution profile precision. Pricing pressure stems from generic commoditization of powder formulations as patent-expired status enables unlimited API sourcing. Feedlot operators demonstrate highest price sensitivity, whereas academic laboratories exhibit lowest sensitivity due to grant-funded procurement protocols.
Supply Chain Analysis
Inbound logistics costs from Zhejiang and Jiangsu province chemical zones to Brazilian port facilities fluctuate with container availability on Asia-South America trade lanes. API production concentrates in China and India, with downstream formulation clustering in Brazil, Germany, and the United States. Raw material dependencies include benzimidazole intermediates, specialized solvents, and micronization equipment. Single-source vulnerability characterizes sub-10-micron particle engineering capability. Distribution runs through veterinary pharmaceutical wholesalers in North American metropolitan markets and direct API contracts for large-scale agricultural integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fenbendazole market expansion is accelerating as parasitic resistance surveillance data forces protocol rotation across livestock operations, with regulatory tightening on residue documentation creating competitive moats for manufacturers with multi-jurisdiction registration capabilities.
For Market Incumbents: Consolidate formulation expertise in particle size engineering and dissolution profile optimization to defend against generic powder commoditization. Expand captive API production through backward integration into Indian and Chinese chemical manufacturing zones. Resistance surveillance mandates from FDA Center for Veterinary Medicine and EMA veterinary product standards intensify documentation burdens that favor incumbents with established regulatory dossier capabilities. For New Entrants and Emerging Players: ANVISA fast-track certification for Brazilian beef export operations offers entry pathway into documented pharmacokinetic protocol supply. Target research institution channels with pharmaceutical-grade batch certification, where pricing stability and lower competitive intensity offset smaller addressable volume. Pursue direct purchasing relationships with Maharashtra cattle cooperatives and São Paulo feedlot operators to bypass entrenched veterinary distribution networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized veterinary clinics with protocol-driven companion animal wellness programs, suggesting durable cash flow profiles in metropolitan North American markets. Acquisition focus should center on micronization technology specialists with sub-10-micron particle engineering patents and established EMA environmental risk assessment dossiers. Signal to monitor: ANVISA enforcement intensity for EU and Middle Eastern export certification, which would accelerate demand for documented pharmacokinetic formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive supply of benzimidazole intermediates from Zhejiang manufacturing zones insulates margin compression from generic powder competition. |
| Mixed Formulation Development | Combination products with novel antiparasitic actives command premium positioning in large-animal veterinary channels addressing resistance patterns. |
| EMA Environmental Risk Assessment Dossier Expansion | Aquatic toxicity testing compliance enables continued registration access across Bavarian and Lower Saxony dairy operations. |
| Direct Procurement Contract Negotiation | Volume agreements with Texas and Kansas feedlot operators displace traditional veterinary distribution intermediaries. |
| Research Institution Channel Establishment | Pharmaceutical-grade batch certification for oncology and cell biology applications diversifies revenue beyond agricultural cyclicality. |
Research Methodology
A standing panel of veterinary pharmaceutical executives, regulatory affairs specialists at FDA Center for Veterinary Medicine, feedlot procurement directors, companion animal clinic practice managers, and research institution laboratory supply coordinators provided ongoing calibration throughout data collection. Primary interview findings were cross-validated against secondary sources including FDA veterinary drug approval databases, EMA veterinary product registration records, ANVISA export certification filings, and customs trade data for fenbendazole API shipments. Bottom-up volume estimates from formulation-level procurement patterns were reconciled with top-down market sizing derived from veterinary pharmaceutical manufacturer revenue disclosures.
Consistency checks against external benchmarks validated projection outputs across the modeling period. The analytical framework segmented demand by formulation type, application endpoint, end-user procurement sophistication, and delivery mode technical complexity. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and resistance surveillance data trends. Forecast inputs incorporated parasitic resistance pattern evolution, withdrawal period enforcement intensity, and channel restructuring toward direct agricultural integrator purchasing.
Decision-makers should treat outputs as directional under assumptions of continued EMA-FDA-ANVISA regulatory convergence and stable API supply from Indian and Chinese manufacturing zones; material deviation in either dimension would warrant model refresh. Specific risk factors include abrupt trade restriction imposition on pharmaceutical intermediates, accelerated anthelmintic stewardship mandate expansion, or novel resistance mechanism emergence rendering benzimidazole protocols obsolete. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Prokaryotic Recombinant Protein Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Chemotherapy Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Biobetters Market