
 Olaparib API Market | 2026-2036
Olaparib API Market Size, Share, and Industry Trends Forecast 2026-2036
Olaparib API Market Analytics
The EU Green Deal's pharmaceutical sustainability requirements is shifting procurement criteria toward greener API synthesis routes. AstraZeneca leverages its originator expertise to sustain captive supply advantages for olaparib API. MSN Laboratories anchors its position through cost-competitive generic API production at scale. Dr. Reddy's Laboratories differentiates via integrated oncology API manufacturing across multiple dosage platforms.
Olaparib API is the active pharmaceutical ingredient of a poly(ADP-ribose) polymerase inhibitor, synthesized through multi-step organic chemistry involving chiral resolution and crystallization to achieve pharmaceutical-grade purity exceeding 99.5%, formulated primarily for targeted cancer therapy against BRCA-mutated tumors. Capsules dominate current volume consumption due to established oral oncology protocols, while injections capture expanding share in hospital-based administration settings. Research applications represent the fastest-growing segment as academic and commercial investigators explore combination therapy protocols beyond approved indications.
FDA oncology drug review standards and EMA's MDR framework govern olaparib API purity specifications, bioequivalence requirements, and post-market surveillance obligations that directly shape manufacturer compliance investments and market access timelines. China's NMPA recently aligned its oncology API approval pathways with ICH guidelines, reducing regulatory friction for domestic producers seeking export certification. Stakeholders must monitor evolving pharmacopoeial harmonization between USP, EP, and ChP standards as divergence in impurity thresholds could fragment quality specifications and complicate multi-region supply strategies.
Market Dynamics
The olaparib API market is being fundamentally restructured by the FDA's accelerated approval pathways for oncology drugs, which compress development timelines and intensify competition among PARP inhibitor manufacturers seeking first-mover advantages in BRCA-mutated cancer indications.
Growth Catalysts
- EMA PRIME Designation:The European Medicines Agency's priority medicines scheme fast-tracks olaparib combination therapies, reducing regulatory review periods and accelerating patient access to novel formulations.
- China's NMPA Alignment:China's National Medical Products Administration harmonized oncology API approval pathways with ICH guidelines, enabling domestic producers to secure export certification with reduced regulatory friction.
- Hospital-Based Injection Protocols:Oncology centers are expanding intravenous administration of olaparib for patients unable to tolerate oral capsules, creating new demand for sterile API grades.
Market Restraints
- Chiral Resolution Input Costs:The multi-step synthesis requiring enantiomerically pure intermediates exposes manufacturers to volatile pricing for specialized catalysts and resolving agents.
- Captive Supply Concentration:AstraZeneca's retained manufacturing expertise and patent-protected process knowledge limits accessible volume for independent generic API producers.
- EU Green Deal Compliance:Pharmaceutical sustainability mandates are forcing costly retooling of solvent-intensive crystallization steps to meet carbon intensity thresholds.
Strategic Opportunities
- Combination Therapy Research:Academic and commercial investigators are exploring olaparib paired with immunotherapy agents, expanding addressable API demand beyond approved monotherapy indications.
- India's CDSCO Export Pathway:India's streamlined certification for oncology APIs positions domestic manufacturers to capture share in price-sensitive emerging markets.
- Continuous Flow Chemistry:Adoption of microreactor technology for hazardous nitration steps promises yield improvements and reduced environmental compliance burdens.
Industry Challenges
- Pharmacopoeial Harmonization Gaps:Divergent impurity thresholds between USP, EP, and ChP standards complicate multi-region supply strategies and force redundant quality testing.
- Specialized Synthetic Chemist Shortage:The complex chiral chemistry expertise required for olaparib production outpaces available talent pools in traditional API manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olaparib API Market |
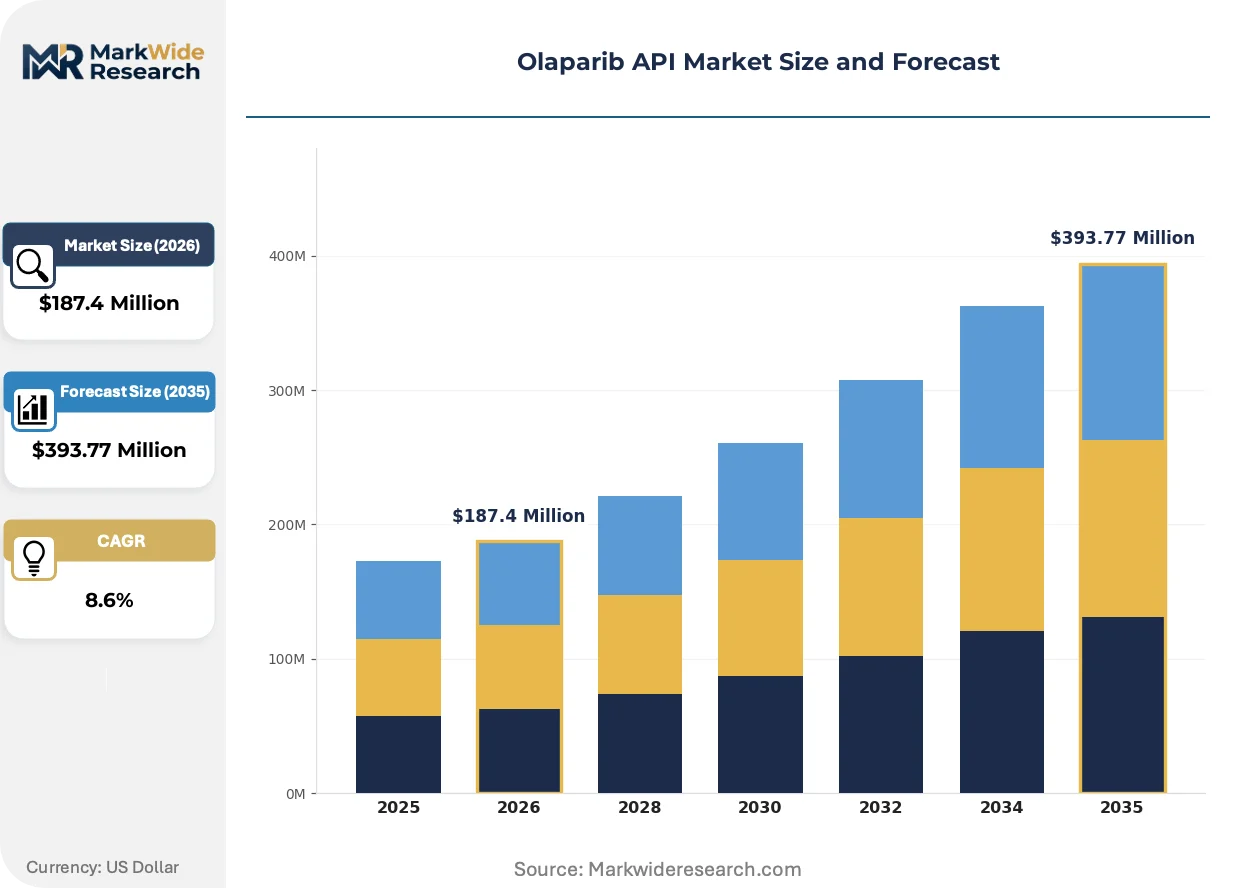
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Injections, Oral Suspensions Application: Cancer Treatment, Research, Clinical Trials, Companion Diagnostics Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Clinics, Research Laboratories, Pharmaceutical Companies |
| Companies Covered | AstraZeneca, Pfizer, Novartis AG, MSN Laboratories, Alembic Pharmaceuticals, ALP Pharm Beijing, Dr. Reddy's Laboratories, Sun Pharmaceutical Industries, ScinoPham Taiwan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olaparib API Market Evolving Landscape
Manufacturing technology and regulatory frameworks are converging to reshape how olaparib API is produced, certified, and procured across oncology supply chains.
Continuous manufacturing technology is absorbing process development investment from leading API producers seeking to replace batch crystallization with real-time quality-controlled production. Mid-scale manufacturers in India and China are piloting these systems to reduce solvent waste and accelerate batch release timelines. The shift is compressing capital recovery periods while raising barriers for producers dependent on legacy batch infrastructure.
REACH authorization requirements for carcinogenic intermediates used in olaparib synthesis are forcing European manufacturers to substitute legacy reagents with greener alternatives or relocate certain steps to non-EU jurisdictions. The regulatory pressure is fragmenting supply chain geography as companies optimize for compliance cost versus logistics efficiency. Generic API specialists are responding by consolidating precursor production in India under centralized environmental permits.
Hospital procurement consortia in the United States are consolidating olaparib API purchasing through centralized oncology pharmacy networks, displacing fragmented distributor relationships with direct manufacturer contracting. This concentration is compressing price negotiation cycles and favoring suppliers with integrated formulation capabilities. The pattern is most pronounced in academic medical centers managing high-volume BRCA testing programs.
Olaparib API Market Segmentation
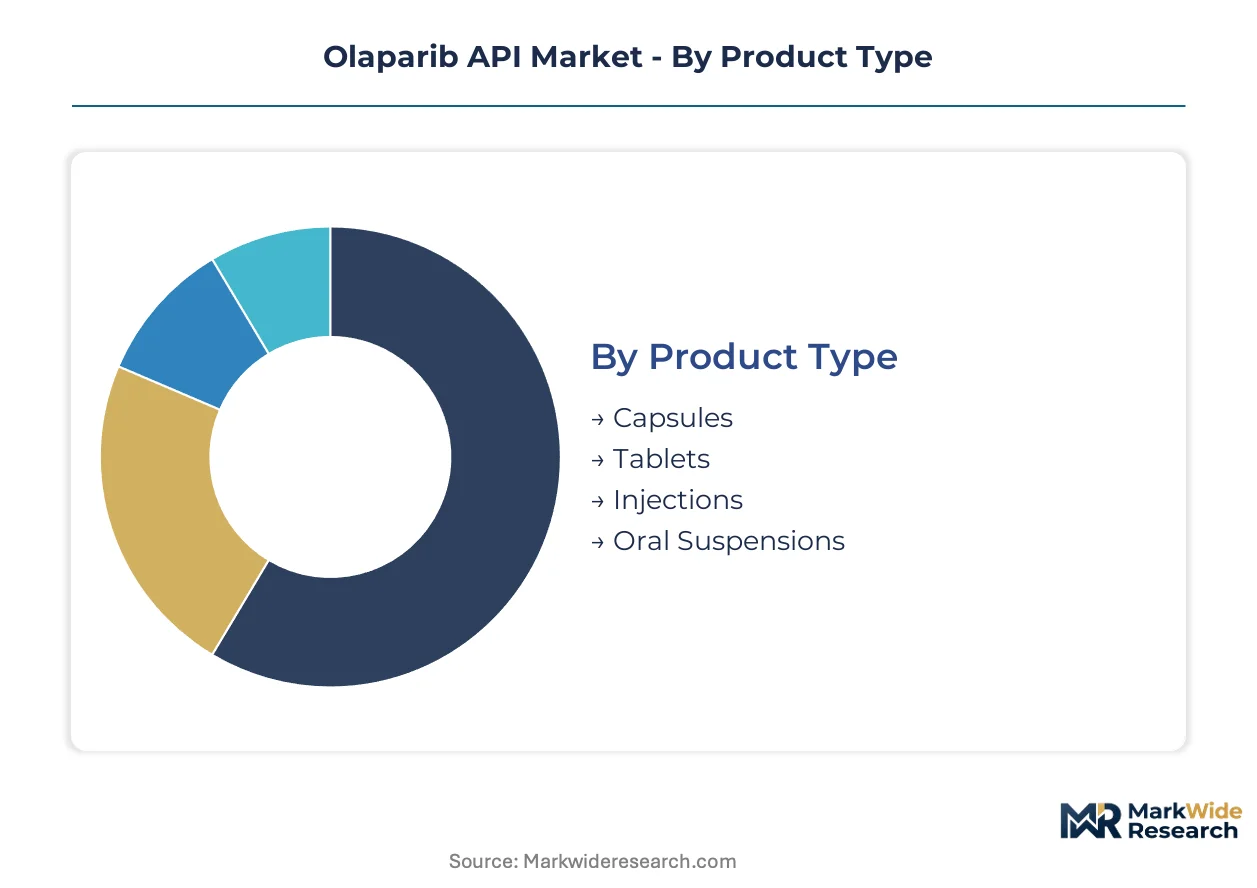
Olaparib API procurement patterns diverge sharply across formulation types and delivery settings. Pharmaceutical manufacturers align synthesis investments with the specific purity grades and stability profiles demanded by each segment's end-use environment.
Product Type:
Capital intensity escalates from oral solid dosage forms to sterile injectable grades, driven by aseptic manufacturing infrastructure and specialized containment requirements.
- Capsules:Hard gelatin shells containing olaparib API with standard oral bioavailability profiles dominate outpatient oncology dispensing. Demand concentrates in the United States where oral PARP inhibitor protocols for BRCA-mutated breast cancer have achieved broad payer coverage, though capsule stability under variable humidity conditions constrains distribution to tropical markets without cold-chain investment.
- Injections:Sterile lyophilized or solution formulations requiring endotoxin-controlled synthesis and aseptic filling command premium API grades. Hospital-based administration in China and Germany is expanding fastest as oncology centers prioritize adherence assurance for patients with gastrointestinal intolerance to oral therapy.
- Tablets:Film-coated compressed dosage forms offer alternative oral delivery with modified release potential. European formulation specialists favor tablets for fixed-dose combination trials with immunotherapy agents.
- Oral Suspensions:Liquid formulations enabling dose titration for pediatric or geriatric populations with swallowing difficulties. Compounding pharmacies in Japan drive niche demand for this format.
Most installed capacity flows through Capsules. Expansion is steepest in Injections.
Application:
Margin profiles diverge between commercial therapeutic manufacturing and investigational supply, with research-grade API commanding price premiums for documentation flexibility.
- Cancer Treatment:Commercial-scale API production for approved indications in ovarian, breast, pancreatic, and prostate malignancies. FDA-approved manufacturing sites in the United States and EMA-certified facilities in Ireland anchor supply for this segment, with volume procurement tied to risk-sharing agreements between AstraZeneca and national health technology assessment bodies.
- Research:Non-GMP and GMP-grade API for academic and commercial investigator-initiated studies exploring olaparib combinations beyond labeled indications. Contract research organizations in Boston and Shanghai represent the fastest-expanding demand pool as combination protocols with checkpoint inhibitors proliferate.
- Clinical Trials:Phase-appropriate API supply with regulatory filing support for sponsor companies developing biosimilar or next-generation PARP inhibitors. Indian CDSCO-registered manufacturers capture share in this segment through cost-competitive IMPD-ready documentation packages.
- Companion Diagnostics:Reference standard API for BRCA testing assay calibration and analytical validation. Diagnostic platform companies in California and Switzerland source highly characterized lots with comprehensive impurity profiling.
Revenue concentration sits with Cancer Treatment. Research is expanding most quickly.
Delivery Mode:
Route-specific formulation requirements fragment API specification standards, with parenteral grades demanding more stringent particulate and bioburden controls.
- Oral:Standard pharmaceutical-grade API with standard dissolution characteristics for gastrointestinal absorption. This delivery mode absorbs the majority of olaparib API volume through capsule and tablet formulations.
- Intravenous:Sterile API with sub-visible particulate compliance and endotoxin limits suitable for direct vascular administration. German hospital pharmacy networks are standardizing IV olaparib preparation protocols.
- Subcutaneous:API formulated for depot injection or continuous infusion devices. Preclinical development programs in Massachusetts explore subcutaneous delivery for patient convenience advantages.
- Intramuscular:API with modified release characteristics for sustained absorption from muscle tissue. This route remains experimental with limited commercial API demand.
Oral delivery retains the largest installed base. Intravenous routes show the steepest capacity expansion.
End User:
Procurement scale and quality documentation requirements vary systematically across institutional buyer categories, shaping supplier qualification strategies.
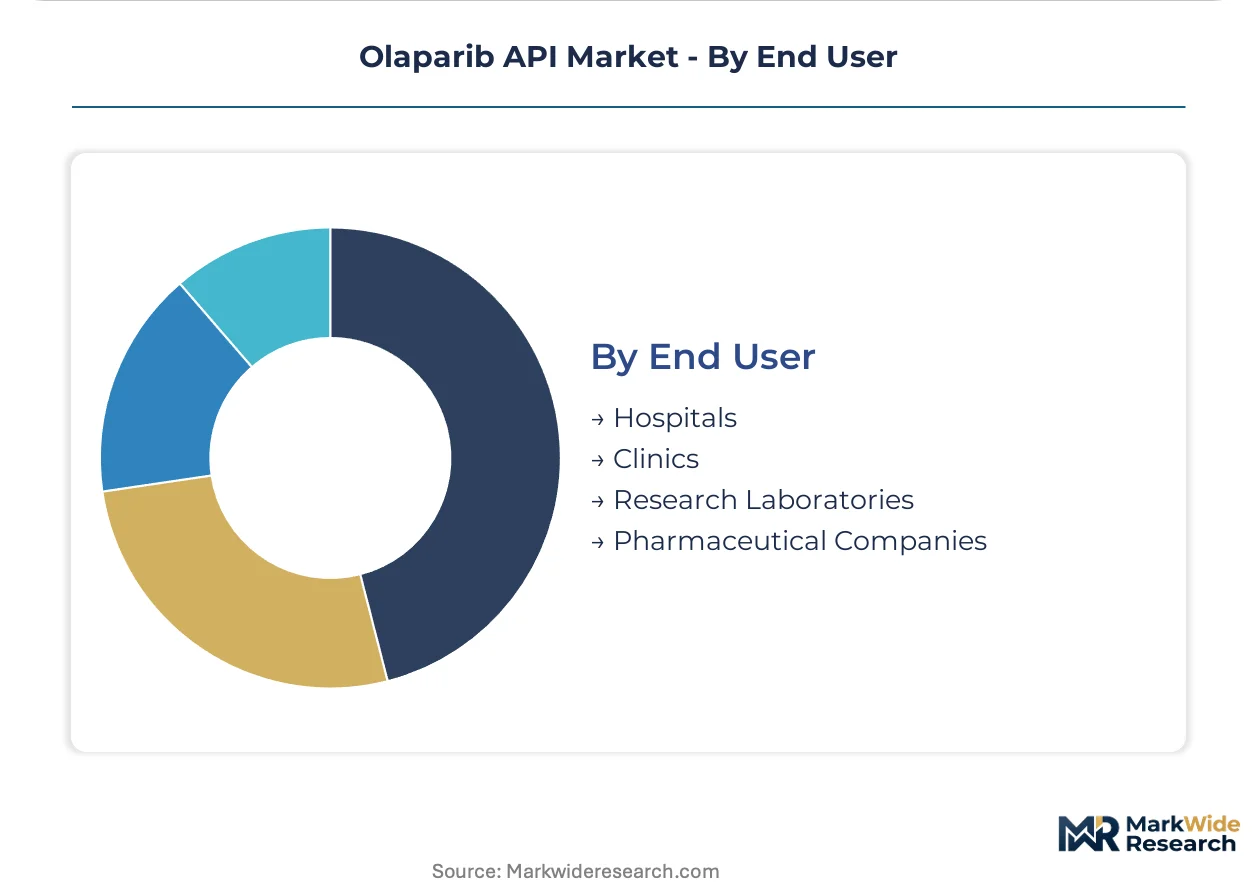
- Hospitals:Integrated health systems with centralized oncology pharmacy operations purchasing API for in-house compounding or contracted manufacturing. US academic medical centers with high-volume BRCA testing programs are consolidating procurement through group purchasing organizations.
- Pharmaceutical Companies:Finished dosage form manufacturers sourcing API for commercial production or generic development. AstraZeneca's captive supply dominance limits accessible volume for independent generic producers seeking to enter the market.
- Research Laboratories:Academic and government institutions with small-lot, high-documentation requirements. National cancer institutes in France and Japan maintain qualified supplier lists for investigator-initiated trials.
- Clinics:Community oncology practices and specialized cancer centers with limited in-house manufacturing capabilities. These settings typically procure finished dosage forms rather than API directly.
Pharmaceutical Companies command the deepest supplier relationships. Hospitals are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The olaparib API industry traces its commercial roots to AstraZeneca's original development and manufacturing scale-up in the United Kingdom and Sweden during the early 2010s, establishing the process chemistry foundations that now diffuse to global production centers.
United States
FDA accelerated approval pathways compress oncology drug development timelines, driving API procurement from domestic manufacturers serving commercial formulation sites. Hospital procurement consortia in academic medical centers with high-volume BRCA testing programs consolidate purchasing through centralized oncology pharmacy networks. Greater Boston hosts contract research organizations expanding investigator-initiated combination therapy studies.
China
NMPA alignment with ICH guidelines reduces regulatory friction for domestic producers seeking export certification, while hospital-based injection protocols expand fastest in oncology centers prioritizing adherence assurance. The Yangtze River Delta concentration of API manufacturers scales continuous flow chemistry pilots for hazardous synthesis steps. Shanghai-based CROs represent the fastest-expanding demand pool for research-grade material.
Germany
EMA PRIME designation fast-tracks olaparib combination therapies through centralized regulatory review, with German hospital pharmacy networks standardizing intravenous preparation protocols. REACH authorization requirements for carcinogenic intermediates force substitution of legacy reagents with greener alternatives. The Rhine-Ruhr industrial corridor concentrates formulation specialists favoring tablet formats for fixed-dose combination trials.
India
CDSCO streamlined certification for oncology APIs positions domestic manufacturers to capture share in price-sensitive emerging markets, with cost-competitive generic API production scaling at Hyderabad and Ahmedabad manufacturing clusters. The country's specialized synthetic chemist shortage for complex chiral chemistry outpaces available talent pools. Maharashtra-based producers consolidate precursor production under centralized environmental permits.
Switzerland
Swissmedic maintains stringent pharmacopoeial standards that shape multi-region quality specifications, with diagnostic platform companies in Basel and Zurich sourcing highly characterized reference standard API for BRCA testing assay calibration. The country's pharmaceutical sustainability mandates anticipate EU Green Deal compliance requirements. Geneva-based academic institutions maintain qualified supplier lists for investigator-initiated trials.
Olaparib API Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory documentation sophistication and captive supply security. The market structure reflects concentrated originator expertise alongside fragmented generic API competition. Three archetypes dominate: integrated pharmaceutical conglomerates retaining process knowledge, specialized oncology API manufacturers scaling cost-competitive production, and regional contract manufacturers serving emerging market formulation needs. Competitive moves center on continuous manufacturing technology licensing and backward integration into hazardous intermediate production.
Within the originator-tier, AstraZeneca exemplifies captive supply advantages through retained manufacturing expertise and patent-protected process knowledge. Among Indian-based specialists, MSN Laboratories and Dr. Reddy's Laboratories occupy positions representing cost-competitive generic API production at scale and integrated oncology API manufacturing across multiple dosage platforms respectively. ALP Pharm Beijing anchors the China-based manufacturer archetype serving domestic formulation demand and export certification pathways.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer |
| Novartis AG |
| MSN Laboratories |
| Alembic Pharmaceuticals |
| ALP Pharm Beijing |
| Dr. Reddy's Laboratories |
| Sun Pharmaceutical Industries |
| ScinoPham Taiwan |
| Others |
Value Network & Pricing Analysis
Originator-captive supply bifurcation from open-market generic API creates divergent margin architectures across the olaparib landscape. AstraZeneca's retained process knowledge commands premium pricing for regulatory-grade material, while Indian and Chinese manufacturers compete on cost-competitive volumes for emerging market formulation. This tiered structure concentrates high-margin supply in FDA- and EMA-certified facilities, with price-sensitive procurement flowing through CDSCO-registered channels serving price-constrained buyers.
Pricing Analysis
Three-tier pricing structure across originator-premium, certified-generic, and emerging-market grades governs olaparib API transactions. Price differentiation rests on regulatory certification tier—FDA-approved sites versus EMA-certified versus CDSCO-registered—and captive supply security versus open-market availability. Cost compression in the generic tier intensifies as Hyderabad and Ahmedabad manufacturers scale chiral resolution capacity. Hospital procurement consortia in the United States exhibit lowest price sensitivity due to risk-sharing agreements, while emerging market formulation specialists demonstrate highest elasticity.
Supply Chain Analysis
Specialized synthetic chemist scarcity in Maharashtra and Gujarat constrains chiral chemistry capacity expansion for Indian manufacturers. API production concentrates in India, China, and the United Kingdom, with intermediate synthesis drawing from Yangtze River Delta chemical clusters and Rhine-Ruhr industrial corridors. Supply chain risk centers on REACH authorization requirements for carcinogenic intermediates, forcing reagent substitution or step relocation. Distribution runs through pharmaceutical company direct procurement for captive supply, with open-market volumes flowing via distributor networks to generic formulation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Olaparib API margin expansion hinges on continuous manufacturing adoption compressing solvent-intensive crystallization costs, while research-grade API premiums widen as combination therapy protocols proliferate.
For Market Incumbents: Deploy continuous flow chemistry licensing to defend yield advantages against batch-legacy competitors. Secure backward integration into hazardous nitration intermediates to isolate supply from REACH-driven reagent substitution disruptions. Consolidate hospital procurement consortia relationships through integrated formulation capabilities, countering distributor disintermediation threats from US academic medical center networks. For New Entrants and Emerging Players: Enter via research-grade API supply for Boston and Shanghai contract research organizations, where documentation flexibility commands price premiums and regulatory barriers remain lowest. Target clinical trial material production for Indian CDSCO-registered manufacturers seeking IMPD-ready packages, leveraging streamlined certification pathways. Position through cost-competitive generic API for price-sensitive emerging markets, differentiating via centralized environmental permits for precursor synthesis. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale manufacturers piloting microreactor technology for hazardous synthesis steps. Long-term viability favors producers bridging originator-tier regulatory sophistication with generic-tier cost structures. Monitor pharmacopoeial harmonization progress between USP, EP, and ChP standards as inflection signal—divergence would fragment quality specifications and reward multi-certification investments, while convergence would compress margins toward commodity dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Microreactor adoption by Indian manufacturers reduces solvent waste and accelerates batch release timelines. |
| Regulatory Certification Investment | EMA PRIME designation pursuit compresses review periods for olaparib combination therapy sponsors. |
| Backward Integration into Intermediates | Precursor production consolidation under centralized Indian environmental permits isolates REACH compliance costs. |
| Research-Grade API Capacity Expansion | Non-GMP and GMP-grade supply for Boston CROs captures fastest-expanding demand pool in combination protocols. |
| Hospital Procurement Direct Contracting | Academic medical center network relationships displace fragmented distributor channels for high-volume BRCA programs. |
Research Methodology
Bottom-up oncology formulation modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors across the United States, Germany, China, and India were validated against secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Triangulation between demand-side prescription volume analysis and supply-side manufacturing capacity assessments ensures cross-verified market sizing.
Historical trendline analysis of PARP inhibitor adoption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include dosage form, delivery mode, application type, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year market estimates, with inputs from oncology protocol expansion rates, BRCA testing program scaling, and combination therapy trial proliferation shaping trajectory assumptions.
The model holds under stable regulatory harmonization and continuous manufacturing adoption curves; deviation in pharmacopoeial standard divergence or REACH enforcement intensity would shift supply chain geography and margin distributions. Forecasts reflect documented assumptions regarding hospital procurement consolidation and research-grade API demand elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Recombinant Human Interferon Protein Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
North America Vaccines Market
Biopharmaceuticals
Purified Protein Derivative Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market