
 H1N1 Vaccines Market | 2026-2036
H1N1 Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
H1N1 Vaccines Market Intelligence
Hospital procurement of H1N1 vaccines is decoupling from seasonal influenza contracting, with large health systems now negotiating standalone pandemic stockpile agreements. Sanofi leverages its established egg-based manufacturing infrastructure to serve cost-sensitive public tenders across multiple continents. GlaxoSmithKline sustains competitive positioning through proprietary adjuvant technology that enables dose-sparing formulations. Moderna anchors its presence with mRNA platform flexibility that allows rapid strain adaptation without process revalidation.
H1N1 vaccines are sterile biological preparations containing inactivated or attenuated influenza A/California/2009 (H1N1) virus antigens, formulated to elicit hemagglutination-inhibiting antibodies at titers of 1:40 or greater in healthy adults. These products function as prophylactic immunological agents designed to prevent infection, reduce severity of breakthrough illness, and limit community transmission during seasonal epidemics and pandemic waves. Inactivated vaccine formulations dominate current revenue pools due to established cold-chain logistics and broad regulatory acceptance, while adjuvanted variants command premium positioning in elderly populations where immunogenicity enhancement justifies higher reimbursement. Intranasal delivery routes represent the fastest-expanding administration segment, driven by needle-free acceptance in pediatric populations and simplified mass-vaccination logistics.
The US FDA, the European EMA, and India's CDSCO enforce divergent potency labeling and stability requirements that shape regional product portfolios and barrier-to-entry calculus for multinational suppliers. WHO prequalification standards further condition access to low-income country procurement through UNICEF and Gavi channels. Stakeholders must monitor strain selection committee decisions and manufacturing technology transitions as dual pressures from pandemic readiness mandates and platform innovation reshape competitive requirements.
Market Dynamics
Cell-based manufacturing technology is displacing egg-based production methods across developed markets, compressing production timelines from six months to twelve weeks and enabling faster strain-matching responses during pandemic waves.
Growth Catalysts
- Pandemic Preparedness Budgets:National stockpile mandates in the United States, India, and Brazil are expanding procurement volumes beyond seasonal influenza baselines.
- EMA Dose-Sparing Guidelines:Adjuvant-enabled formulations now qualify for expanded elderly indications, opening reimbursement pathways in European markets.
- WHO Prequalification:Standardized potency benchmarks accelerate market entry for manufacturers targeting UNICEF and Gavi procurement channels in low-income countries.
Market Restraints
- Egg-Based Supply Concentration:Legacy production infrastructure in specific supplier networks creates vulnerability during avian influenza outbreaks affecting embryonated egg supply chains.
- Cold-Chain Infrastructure Gaps:Ultra-low temperature requirements for mRNA formulations limit distribution reach in regions lacking specialized logistics networks.
- Strain Selection Timing:WHO committee decisions finalized in February create manufacturing lock-in six months before Northern Hemisphere peak demand, risking antigenic mismatch.
Strategic Opportunities
- Pediatric Intranasal Delivery:Needle-free administration formats address compliance barriers in school-based immunization programs across India and Brazil.
- CDSCO Fast-Track Pathways:India's streamlined biosimilar approval framework enables accelerated market entry for platform-adapted vaccines during variant emergence.
- Digital Immunization Registries:Integration with national health IT systems creates demand for serialized dose tracking and real-time coverage monitoring capabilities.
Industry Challenges
- Fill-Finish Capacity Bottlenecks:Sterile manufacturing suites capable of handling high-containment biologicals remain scarce, extending lead times for commercial-scale batches.
- Cross-Platform Workforce Training:Technical personnel proficient in both egg-based and cell-based production methods command premium compensation, constraining operational flexibility.
- Stability Testing Protocol Divergence:FDA, EMA, and CDSCO impose non-harmonized real-time release criteria, forcing parallel validation studies that extend registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | H1N1 Vaccines Market |
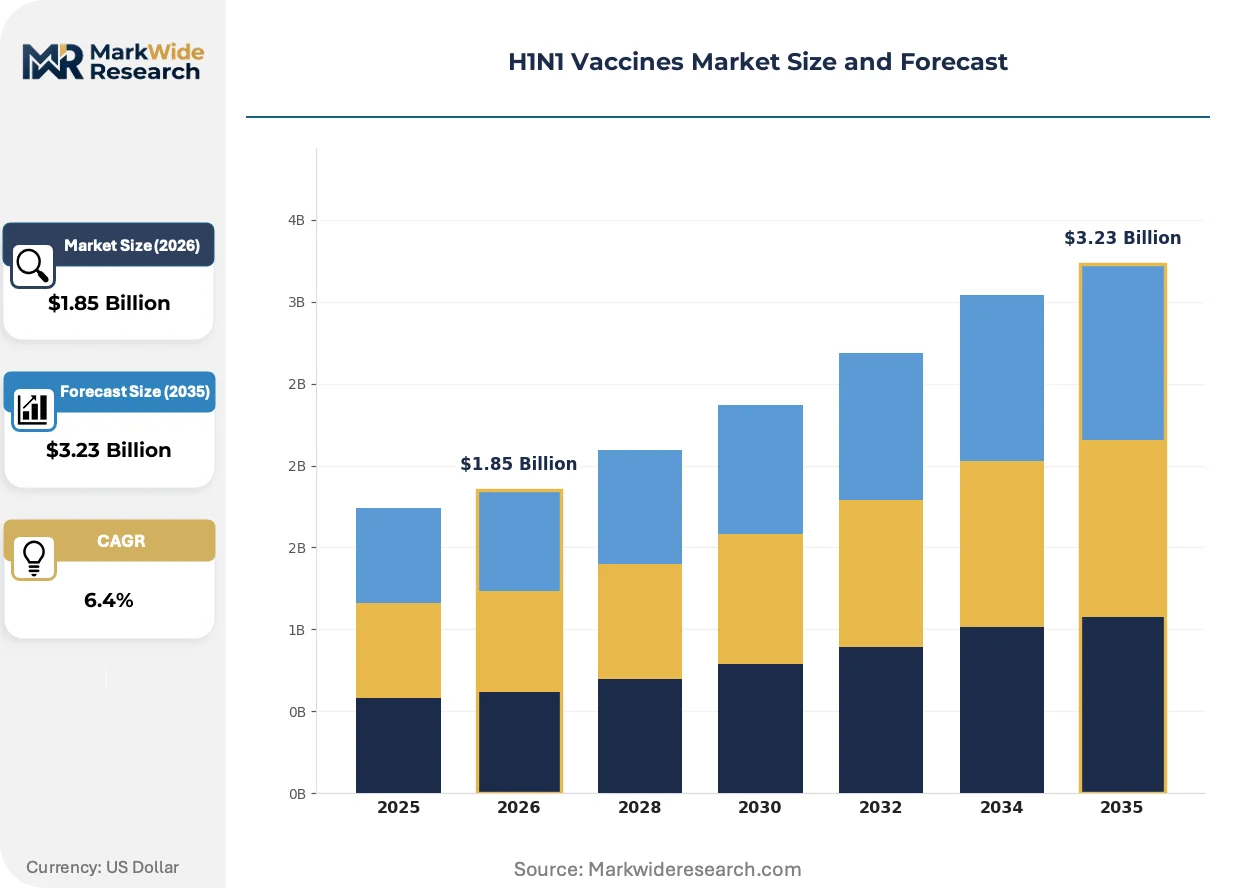
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccine, Live Attenuated Vaccine, Adjuvanted Vaccine, Quadrivalent Vaccine Administration Route: Intramuscular, Intranasal, Subcutaneous, Oral End User: Healthcare Providers, Clinics, Hospitals, Pharmacies Age Group: Infants, Children, Adults, Elderly |
| Companies Covered | Sanofi, GlaxoSmithKline, AstraZeneca, Pfizer, CSL Limited, Seqirus, Moderna, Serum Institute of India, Bharat Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
H1N1 Vaccines Market Strategic Shifts & Innovations
mRNA platform flexibility is actively compressing the strain adaptation cycle, enabling manufacturers to respond to antigenic drift without full process revalidation. This technological pivot is redrawing competitive requirements across pandemic preparedness contracting.
Recombinant hemagglutinin protein technology is rewriting manufacturing economics by eliminating egg-dependent supply constraints. Large health systems in the United States are adopting these formulations for standalone stockpile agreements separate from seasonal contracting. The structural consequence is a bifurcation between rapid-response mRNA capacity and cost-optimized recombinant supply for baseline coverage.
EMA's updated Module 3 requirements for cell-based manufacturing are accelerating facility upgrade investments across European production sites. These guidelines mandate enhanced process analytical technology integration for real-time potency verification. Adjuvanted formulations targeting elderly populations face the steepest compliance burden, driving consolidation among suppliers with established quality management systems.
Hospital procurement teams are consolidating pandemic vaccine contracting under centralized pharmacy and therapeutics committees. Large integrated delivery networks in the United States are replacing standalone seasonal agreements with multi-year preparedness frameworks that bundle H1N1, H3N2, and B-strain coverage. This concentration is most visible in systems operating across multiple states, where standardization reduces formulary complexity and leverages volume-based pricing mechanisms.
H1N1 Vaccines Market Segmentation
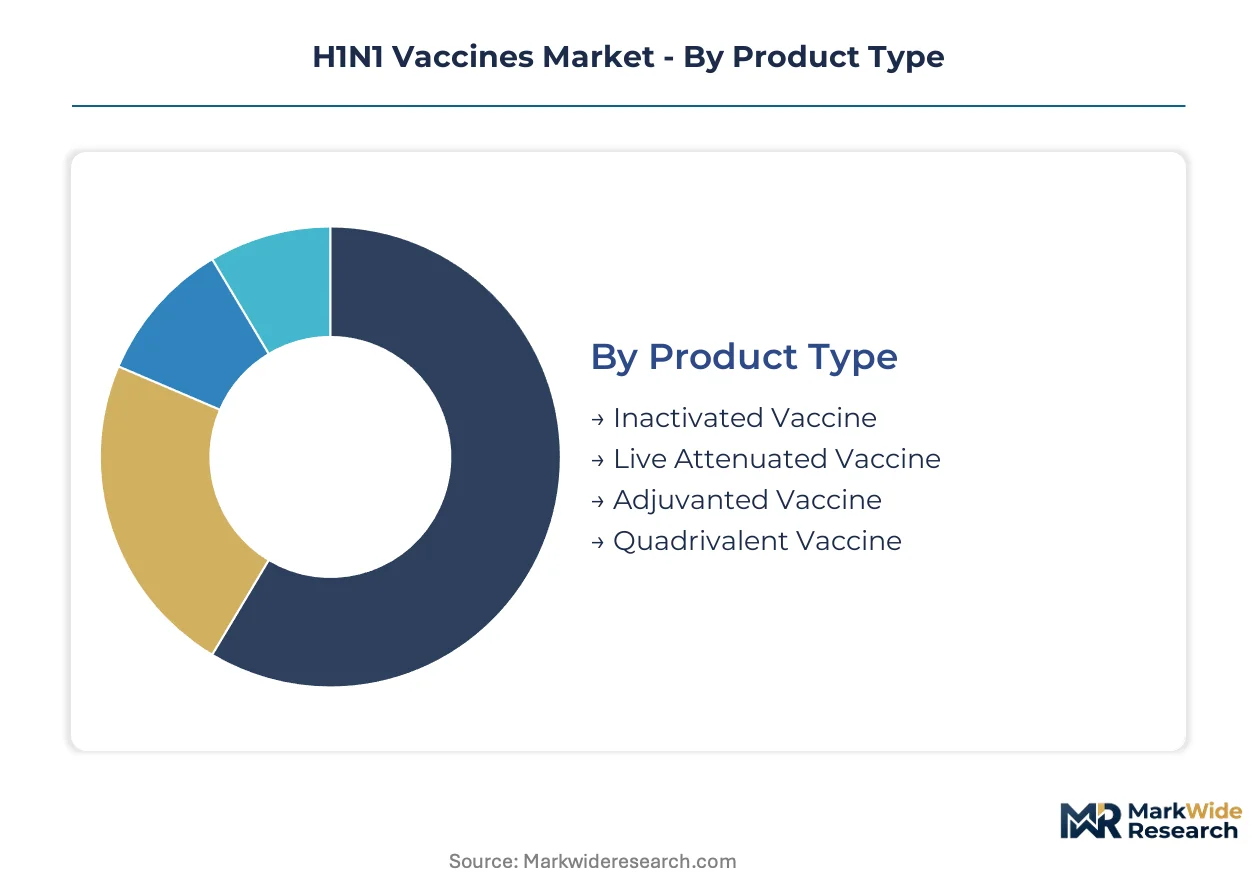
H1N1 vaccine procurement decisions hinge on immunogenicity profiles matched to population risk tiers and distribution infrastructure capacity. Manufacturers configure product portfolios across four intersecting dimensions that determine reimbursement pathways, cold-chain requirements, and regulatory submission strategies.
Product Type:
Procurement officers weigh manufacturing reliability against dose-sparing economics when selecting formulation platforms for national stockpiles.
- Inactivated Vaccine:Virions chemically treated to destroy replication capacity while preserving hemagglutinin and neuraminidase surface antigens. Demand concentrates in United States hospital systems requiring established cold-chain compatibility and broad pediatric-to-elderly labeling.
- Adjuvanted Vaccine:Formulations incorporating oil-in-water emulsions or saponin-based immunostimulants to amplify antigen presentation. European markets under EMA dose-sparing guidelines drive procurement, with elderly populations justifying premium reimbursement through enhanced seroprotection rates.
- Live Attenuated Vaccine:Temperature-sensitive viral strains with restricted replication competence delivered via intranasal routes. Brazil's school-based immunization programs favor this format for mass pediatric administration.
- Quadrivalent Vaccine:Multivalent preparations incorporating H1N1 alongside H3N2 and B-strain antigens. India's national immunization schedules prioritize this category for streamlined logistics and reduced clinic visit burdens.
Volume sits with Inactivated formulations; growth tilts toward Adjuvanted variants as aging demographics expand across developed markets.
Administration Route:
Delivery modality selection reflects mass-vaccination throughput targets and needle-phobia mitigation priorities in school and workplace settings.
- Intramuscular:Standard deltoid or vastus lateralis injection delivering 0.5mL doses into skeletal muscle tissue. United States health systems maintain this as default for adult populations in pandemic stockpile agreements.
- Intranasal:Mist delivery of attenuated viral particles to nasal mucosa eliciting mucosal IgA and systemic IgG responses. India's urban school districts and Brazil's municipal health departments are expanding procurement for pediatric compliance advantages.
- Subcutaneous:Dermal adipose layer injection requiring smaller-gauge needles and reduced technical skill. Pharmacies in United States retail settings favor this route for streamlined staffing models.
- Oral:Enteric-coated formulations in early commercialization with thermostability advantages eliminating cold-chain dependence. Limited current procurement focuses on military and remote deployment scenarios.
Intramuscular administration captures current procurement volumes; Intranasal delivery is climbing the fastest as needle-free acceptance spreads through pediatric immunization programs.
End User:
Channel selection determines packaging configurations, minimum order quantities, and serialization requirements for supply chain traceability.
- Hospitals:Integrated delivery networks negotiating multi-year pandemic preparedness frameworks with centralized pharmacy committees. United States systems bundle H1N1 coverage with seasonal influenza contracting across multi-state operations.
- Clinics:Outpatient facilities serving Medicaid and uninsured populations requiring single-dose vial formats to minimize wastage. India's urban primary health centers represent concentrated demand for this channel.
- Healthcare Providers:Physician practices and community health centers with limited cold-chain infrastructure favoring adjuvanted formulations with extended stability windows.
- Pharmacies:Retail chains with refrigerated storage capacity expanding into immunization services under pharmacist scope-of-practice expansions in United States and Brazilian markets.
Hospital procurement dominates contract value; pharmacy channel expansion is gaining share fastest as retail healthcare access models proliferate.
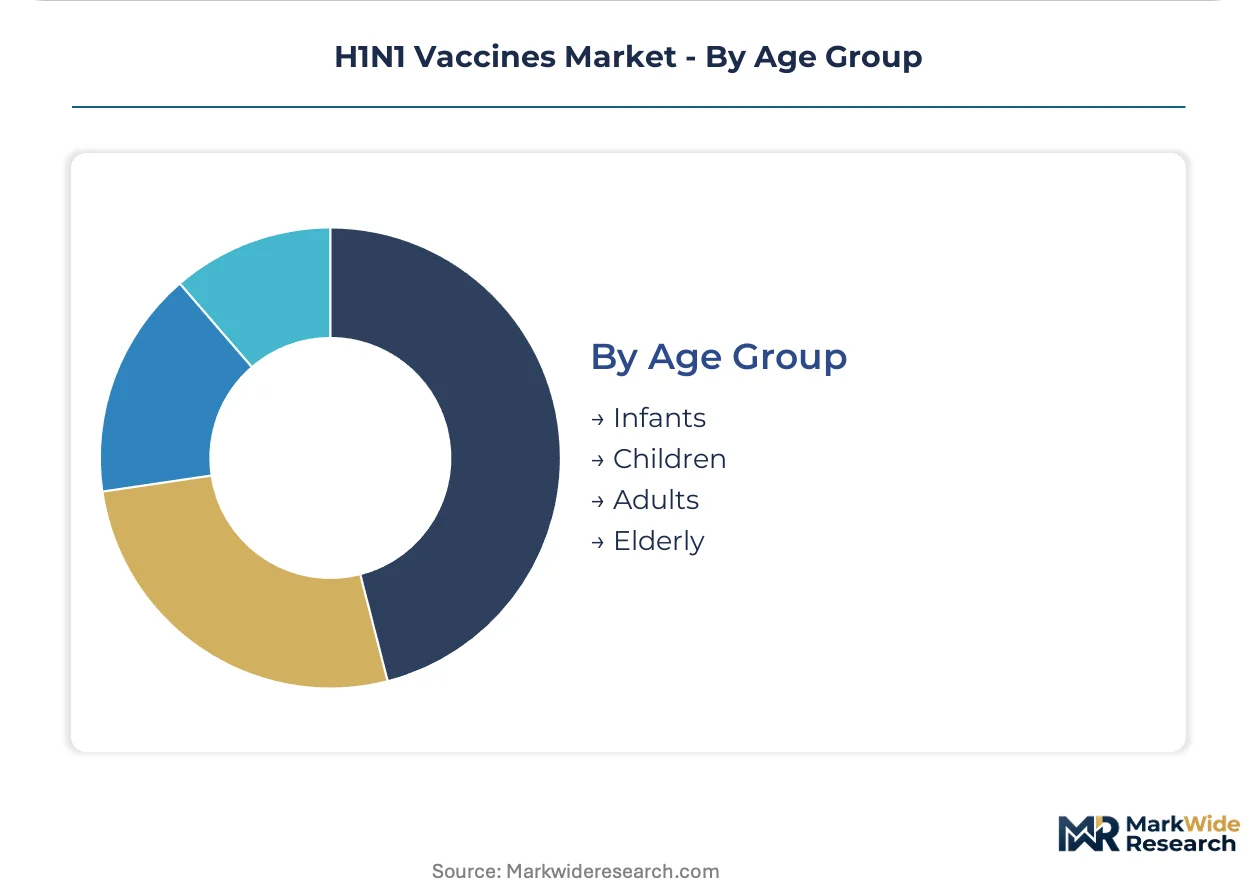
Age Group:
Regulatory labeling and dosing schedules segment manufacturing output across distinct immunogenicity and safety profiles.
- Elderly:Adults aged 65 and above with immunosenescence requiring adjuvanted or high-dose formulations. EMA guidelines and United States ACIP recommendations drive premium-priced procurement for this cohort.
- Adults:Working-age population aged 18-64 forming baseline coverage targets for employer-sponsored and national health programs. Standard-dose inactivated vaccines serve this segment across United States, India, and Brazil.
- Children:Pediatric populations aged 6 months to 17 years requiring age-stratified dosing and thimerosal-free presentations. School-based programs in India and Brazil concentrate demand for this segment.
- Infants:Birth to 6 months with maternal antibody interference and limited approved formulations. NICU and maternal-child health programs represent specialized procurement with stringent safety documentation requirements.
Adult populations anchor manufacturing volume; Elderly segment shows steepest expansion trajectory as demographic aging intensifies across developed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration for H1N1 vaccines clusters in three national markets where pandemic preparedness budgets command standalone stockpiling mandates. Hospital systems and government immunization programs in the United States, India, and Brazil generate the dominant share of contract value.
United States
FDA stockpiling directives require integrated delivery networks to maintain six-month pandemic vaccine reserves independent of seasonal influenza contracts. The Biomedical Advanced Research and Development Authority channels procurement through multi-year preparedness frameworks. Manufacturing concentration in the Research Triangle Park corridor of North Carolina supports rapid fill-finish capacity for mRNA and cell-based formulations.
India
CDSCO fast-track pathways for platform-adapted vaccines accelerate regulatory timelines during variant emergence events. The Universal Immunization Programme expands H1N1 coverage through school-based delivery in urban districts. Production clusters in Pune and Hyderabad host fill-finish operations serving UNICEF and domestic procurement channels simultaneously.
Brazil
ANVISA streamlined approval for intranasal formulations aligns with municipal health department preferences for mass pediatric administration. The National Immunization Program prioritizes needle-free delivery in school settings to improve compliance rates. São Paulo's Butantan Institute anchors regional manufacturing capacity for live attenuated vaccine production.
United Kingdom
EMA dose-sparing guidelines for adjuvanted formulations open premium reimbursement pathways in elderly populations through the National Health Service. The UK Health Security Agency coordinates pandemic stockpile rotation with seasonal procurement cycles. Liverpool's vaccine manufacturing cluster specializes in high-containment biological production for European distribution networks.
Germany
Paul-Ehrlich-Institut potency standards enforce stringent stability requirements that shape product portfolio decisions for suppliers accessing German hospital systems. Federal pandemic preparedness budgets fund standalone H1N1 reserves separate from quadrivalent seasonal contracts. Bavaria's biopharmaceutical corridor hosts cell-based manufacturing investments driven by EMA Module 3 compliance mandates.
H1N1 Vaccines Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue mRNA platform flexibility and recombinant protein alternatives. The supplier base organizes around three archetypes: legacy egg-based manufacturers with cost-optimized public tender positioning, cell-based specialists leveraging shortened production timelines, and platform-agnostic innovators deploying rapid strain adaptation capabilities. Competitive moves concentrate on manufacturing technology transitions and pandemic stockpile contract consolidation.
Within the platform-innovation tier, Moderna exemplifies mRNA adaptability for rapid strain matching without process revalidation. Sanofi and GlaxoSmithKline anchor established supply positions through differentiated manufacturing infrastructures and proprietary formulation technologies. These three entities represent the structural spectrum from rapid-response capacity to cost-optimized baseline coverage.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline |
| AstraZeneca |
| Pfizer |
| CSL Limited |
| Seqirus |
| Moderna |
| Serum Institute of India |
| Bharat Biotech |
| Others |
Cost & Logistics Intelligence
Government procurement programs in the United States, India, and Brazil command pricing power through multi-year pandemic stockpile frameworks that compress margins for suppliers lacking manufacturing scale. This buyer concentration rewards established producers with WHO prequalification status and FDA or EMA licensure, while forcing price-sensitive competitors toward cost-optimized egg-based production.
Pricing Analysis
Volume concentrates in standard-dose inactivated vaccines serving United States hospital systems at contract rates, while margins accrue to adjuvanted formulations qualifying for EMA dose-sparing guidelines in European elderly populations. Price differentiation separates premium mRNA platforms with rapid strain adaptation from standard cell-based supply and economy egg-based tenders. Pricing pressure stems from CDSCO fast-track pathways enabling Indian biosimilar entrants to undercut legacy suppliers in UNICEF channels. Government immunization programs exhibit highest price sensitivity; integrated delivery networks with multi-year frameworks show lowest sensitivity due to standardization premiums.
Supply Chain Analysis
WHO prequalification and FDA licensure requirements gate supplier participation, concentrating fill-finish capacity in the United States, India, and Germany. Manufacturing draws from embryonated eggs, MDCK cell lines, and synthetic mRNA as core inputs, with supply chain risk anchored in single-source vulnerability for high-containment biological suites. Distribution runs through government stockpile depots and hospital pharmacy committees in developed markets, with UNICEF and Gavi channels serving low-income procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Module 3 compliance mandates and FDA potency standards create cost-of-entry barriers that protect incumbent positions while filtering out undercapitalized challengers. The report frames strategic positioning around regulatory moats and manufacturing technology transitions.
For Market Incumbents: Acquire cell-based manufacturing assets and mRNA platform capabilities to defend against rapid-strain-adaptation entrants. Consolidate fill-finish capacity in Research Triangle Park and Bavaria biopharmaceutical corridors. Lock multi-year pandemic preparedness contracts with United States integrated delivery networks before CDSCO fast-track pathways mature. For New Entrants and Emerging Players: Begin with intranasal delivery formats for India's urban school districts and Brazil's municipal health departments, where needle-free compliance advantages offset brand disadvantages. Target pediatric populations underserved by legacy intramuscular suppliers. Pursue WHO prequalification as the essential go-to-market credential for UNICEF and Gavi procurement channels. For Investors and Strategic Acquirers: The window for entry favors platform-agnostic innovators with demonstrated strain adaptation speed over legacy egg-dependent manufacturers. Long-term viability hinges on cell-based and mRNA manufacturing footprints that compress production timelines. Watch EMA dose-sparing guideline expansions as the signal indicating premium pricing power shifts toward adjuvanted formulation specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Technology Transition | Cell-based platforms displace egg-based methods, shortening strain-matching cycles from six months to twelve weeks. |
| Regulatory Approval Pathway | WHO prequalification unlocks UNICEF and Gavi procurement channels in low-income country markets. |
| Long-term Supply Agreement | Multi-year pandemic stockpile frameworks with United States integrated delivery networks secure volume commitments. |
| Product Format Diversification | Intranasal delivery development captures pediatric compliance advantages in India and Brazil school programs. |
| Geographic Manufacturing Footprint | Fill-finish investments in Pune and Hyderabad serve simultaneous domestic Indian and export UNICEF demand. |
Research Approach
Independent corroboration across regulatory affairs directors, hospital pharmacy procurement managers, and government immunization program officers underwrites the qualitative findings in this study. Primary fieldwork combined with secondary validation from FDA filings, EMA Module 3 submissions, WHO prequalification databases, and national stockpile procurement records establishes demand-side and supply-side triangulation. Bottom-up volume estimates from manufacturing capacity disclosures and top-down cross-checks against pandemic preparedness budget appropriations converge on segment-level outputs.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models administration route, age-group risk tier, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from manufacturing capacity expansion schedules, strain selection committee calendars, and procurement contract renewal patterns. Forecast inputs incorporate fill-finish bottlenecks and workforce training constraints specific to high-containment biological production.
Underlying measurement precision varies by segment; inactivated vaccine volumes in United States hospital systems carry tighter precision than emerging oral formulation estimates. Forecasts reflect documented assumptions about EMA guideline stability and CDSCO pathway continuity. A model refresh is warranted upon material change in WHO strain selection timing or avian influenza outbreak severity affecting egg supply chains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Amphotericin B Market