
 Ewing Sarcoma Drugs Market | 2026-2036
Ewing Sarcoma Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Ewing Sarcoma Drugs Market Analysis
Next-generation kinase inhibitor precision is redrawing competitive boundaries in Ewing sarcoma therapeutics. Pfizer leverages its established oncology infrastructure to sustain clinical development momentum across targeted therapy portfolios. Jazz Pharmaceuticals anchors its position through specialized rare disease commercialization capabilities and regulatory navigation expertise.
Ewing sarcoma drugs comprise pharmaceutical agents designed to treat malignant small round blue cell tumors arising from EWSR1 gene translocations, primarily administered as multi-agent chemotherapy regimens with vincristine, doxorubicin, and cyclophosphamide alternating with ifosfamide and etoposide. These therapeutics function to induce remission in bone and soft tissue malignancies predominantly affecting children and young adults. Chemotherapy retains the largest patient volume footprint, while targeted therapy segments show the fastest development velocity as kinase inhibitors address the EWS-FLI1 fusion oncogene. Intravenous administration dominates hospital-based delivery, though oral formulations are gaining traction in maintenance settings where patient convenience drives protocol design.
The FDA's Rare Pediatric Disease Priority Review Voucher program and EMA's Paediatric Investigation Plans create dual regulatory incentives that compress development timelines and expand market access for novel agents. Both frameworks mandate specific trial populations and endpoints that directly shape clinical program architecture and labeling outcomes. Stakeholders must monitor evolving biomarker qualification standards and companion diagnostic requirements that will determine which fusion-targeted therapies achieve reimbursable positioning.
Market Dynamics
FDA's Rare Pediatric Disease Priority Review Voucher program is compressing commercialization timelines and redirecting R&D investment toward fusion-targeted therapies, fundamentally restructuring how developers prioritize Ewing sarcoma pipelines against other oncology indications.
Growth Catalysts
- Orphan Drug Incentives:The FDA's seven-year market exclusivity provisions and tax credits for clinical trial costs reduce financial risk for developers pursuing small-population indications.
- Biomarker-Qualified Endpoints:EMA's qualification of circulating tumor DNA metrics as surrogate endpoints accelerates regulatory pathways for novel kinase inhibitors.
- Pediatric Oncology Network Consolidation:Children's Oncology Group trial enrollment density in the United States concentrates patient access and streamlines Phase II recruitment.
Market Restraints
- Fusion Protein Structural Complexity:The intrinsically disordered nature of EWS-FLI1 transcription factor prevents conventional small-molecule binding, forcing developers toward expensive protein-degradation approaches.
- Platinum Supply Concentration:South African and Russian mining dominance for platinum-group metals creates pricing volatility for carboplatin-based combination regimens.
- Single-Payer Reimbursement Compression:NHS England's Cancer Drugs Fund cost-effectiveness thresholds restrict access to premium-priced targeted therapies outside clinical trials.
Strategic Opportunities
- Maintenance Therapy Oral Formulations:Post-remission oral kinase inhibitor protocols address unmet need for reduced hospitalization burden in adolescent and young adult populations.
- Companion Diagnostic Co-Development:FDA's in vitro diagnostic parallel review pathway enables simultaneous approval of fusion-detection assays and matched therapeutics.
- Academic-Industry Alliance Models:St. Jude Children's Research Hospital's open-science data sharing platforms reduce duplicative preclinical investment and accelerate target validation.
Industry Challenges
- Pediatric Trial Design Expertise Scarcity:Limited pool of investigators with dual competency in sarcoma biology and age-appropriate endpoint selection constrains site activation.
- Long-Term Toxicity Surveillance Infrastructure:Survivorship program reimbursement gaps complicate mandatory decades-long cardiotoxicity and secondary malignancy monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ewing Sarcoma Drugs Market |
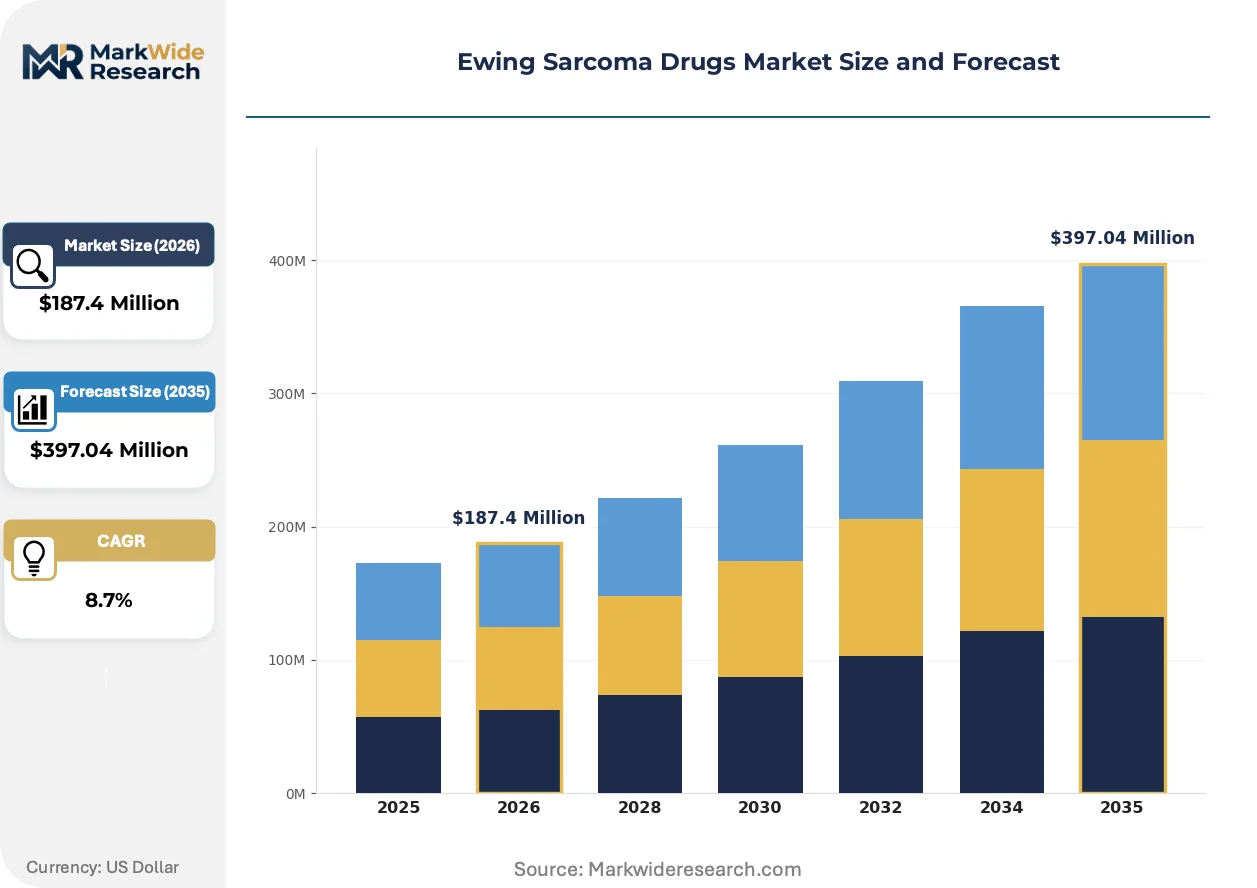
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Chemotherapy, Targeted Therapy, Radiation Therapy, Immunotherapy Drug Class: Alkylating Agents, Antimetabolites, Antibodies, Kinase Inhibitors Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Oncology Clinics, Research Institutions, Homecare |
| Companies Covered | Amgen, Jazz Pharmaceuticals, Salarius Pharmaceuticals, Inhibrx, Pfizer, Novartis, Merck, Bristol-Myers Squibb, Actuate Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ewing Sarcoma Drugs Market Emerging Trajectories
Next-generation therapeutic modalities are displacing cytotoxic chemotherapy dominance through mechanistically distinct approaches targeting the EWS-FLI1 oncogenic driver directly rather than its downstream proliferative consequences.
Proteolysis-targeting chimera (PROTAC) technology is miniaturizing the druggable space for previously intractable transcription factor targets. Pediatric oncology consortiums in the United States and Germany are prioritizing these candidates for early-phase trials. The approach is compressing traditional target validation timelines by leveraging existing E3 ligase biology from approved oncology agents.
EMA's Paediatric Investigation Plan enforcement mandates now require adult-approval sponsors to submit pediatric study designs before market authorization. This regulatory architecture is forcing parallel rather than sequential development tracks. Sarcoma-specific PIP waivers remain rare, compelling investment in age-appropriate formulation development.
Hospital procurement consolidation through group purchasing organizations is centralizing formulary decision-making for high-cost oncology agents. Academic medical centers in the United States are negotiating outcomes-based contracts with manufacturers for novel Ewing sarcoma therapies. This restructuring concentrates pricing leverage among three dominant GPOs serving the majority of pediatric oncology beds.
Ewing Sarcoma Drugs Market Segmentation
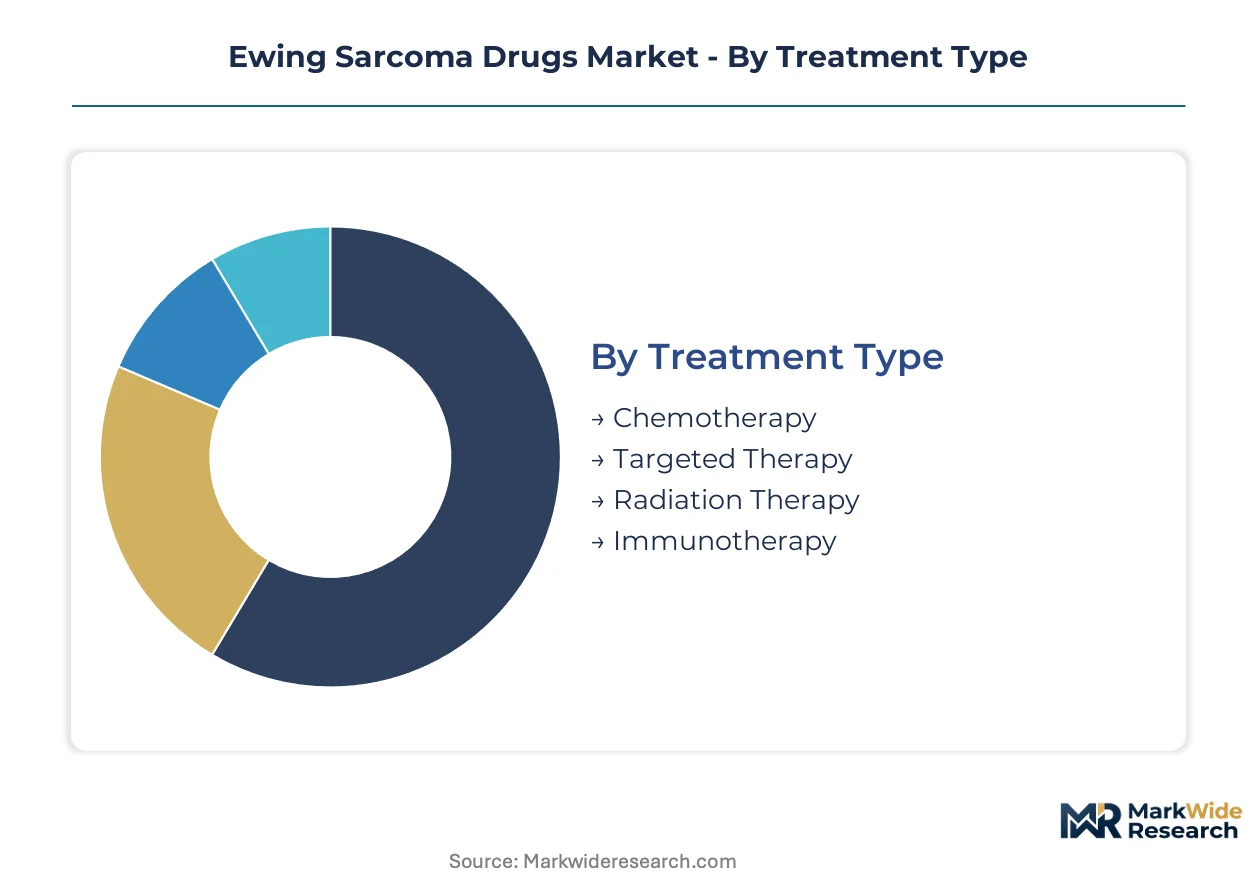
Ewing sarcoma therapeutics fragment across treatment modalities, molecular targets, delivery mechanisms, and care settings. Each segmentation axis reveals distinct competitive dynamics, reimbursement pathways, and patient access patterns that shape commercial strategy.
Treatment Type:
Domestic demand concentrates in chemotherapy and radiation protocols administered through Children's Oncology Group-affiliated centers, while targeted therapy and immunotherapy development draws transnational investment from European and Japanese sponsors seeking FDA Rare Pediatric Disease Priority Review Vouchers.
- Chemotherapy:Multi-agent regimens combining vincristine, doxorubicin, cyclophosphamide, ifosfamide, and etoposide remain the backbone of frontline induction and consolidation therapy. Demand clusters at St. Jude Children's Research Hospital, Memorial Sloan Kettering, and Dana-Farber Cancer Institute where protocol standardization enables outcomes benchmarking.
- Targeted Therapy:Kinase inhibitors and protein-degradation approaches address the EWS-FLI1 fusion oncogene directly rather than downstream proliferative signals. Clinical trial density in the United States and Germany is accelerating regulatory timelines for these mechanistically distinct modalities.
- Radiation Therapy:External beam and proton beam protocols target residual disease following neoadjuvant chemotherapy. Adoption concentrates at proton centers in Boston, Houston, and Jacksonville where capital intensity creates geographic access disparities.
- Immunotherapy:Checkpoint inhibitors and chimeric antigen receptor constructs remain investigational with limited efficacy signals in fusion-driven sarcomas. Academic consortiums in the United States and Netherlands are exploring combination strategies to overcome immune-evasive tumor microenvironments.
Chemotherapy holds the largest share; momentum sits with targeted therapy.
Drug Class:
Cost tier stratification separates mature cytotoxic generics from premium-priced biologics and small-molecule precision agents, with reimbursement complexity escalating across the value spectrum.
- Alkylating Agents:Cyclophosphamide and ifosfamide function through DNA cross-linking to induce apoptosis in rapidly dividing malignant cells. Volume concentrates in hospital-based infusion centers where group purchasing organization contracting compresses margin for generic manufacturers.
- Kinase Inhibitors:Small-molecule agents targeting CDK4/6, IGF-1R, and PARP pathways are expanding the druggable space for fusion-driven malignancies. Development pipelines at Pfizer, Eli Lilly, and AstraZeneca prioritize pediatric-specific formulations to satisfy EMA Paediatric Investigation Plan mandates.
- Antimetabolites:Methotrexate and gemcitabine disrupt nucleic acid synthesis through folate antagonism and nucleoside analog incorporation. These agents anchor salvage regimens for relapsed disease across European and North American cooperative groups.
- Antibodies:Dinutuximab and investigational bispecific constructs leverage immune-mediated cytotoxicity against GD2 and other surface antigens. Manufacturing complexity and cold-chain requirements limit distribution to tertiary pediatric oncology centers.
Alkylating agents dominate volume; kinase inhibitors are climbing the fastest.
Administration Route:
Patient convenience and care setting economics are shifting development investment toward oral and subcutaneous alternatives to prolonged intravenous hospitalization.
- Intravenous:Continuous infusion protocols for anthracyclines and alkylating agents require central venous access and inpatient monitoring. This route anchors induction therapy where toxicity surveillance demands clinical infrastructure.
- Oral:Maintenance-phase kinase inhibitors and hormonal agents enable outpatient disease control with reduced hospitalization burden. Formulation development at Jazz Pharmaceuticals and Novartis targets adolescent adherence through palatable dosing schedules.
- Subcutaneous:Interferon and investigational antibody fragments offer intermediate bioavailability with reduced infusion chair time. Adoption in German and Austrian outpatient oncology networks demonstrates feasibility for selected maintenance protocols.
- Intramuscular:Limited application for supportive care agents including antiemetics and hematopoietic growth factors. This route remains marginal in sarcoma-specific protocols.
Intravenous commands current utilization; oral formulations show steepest expansion trajectory.
End User:
Customer type segmentation reveals divergent procurement authority, with consolidated hospital systems exercising pricing leverage against fragmented research and homecare channels.
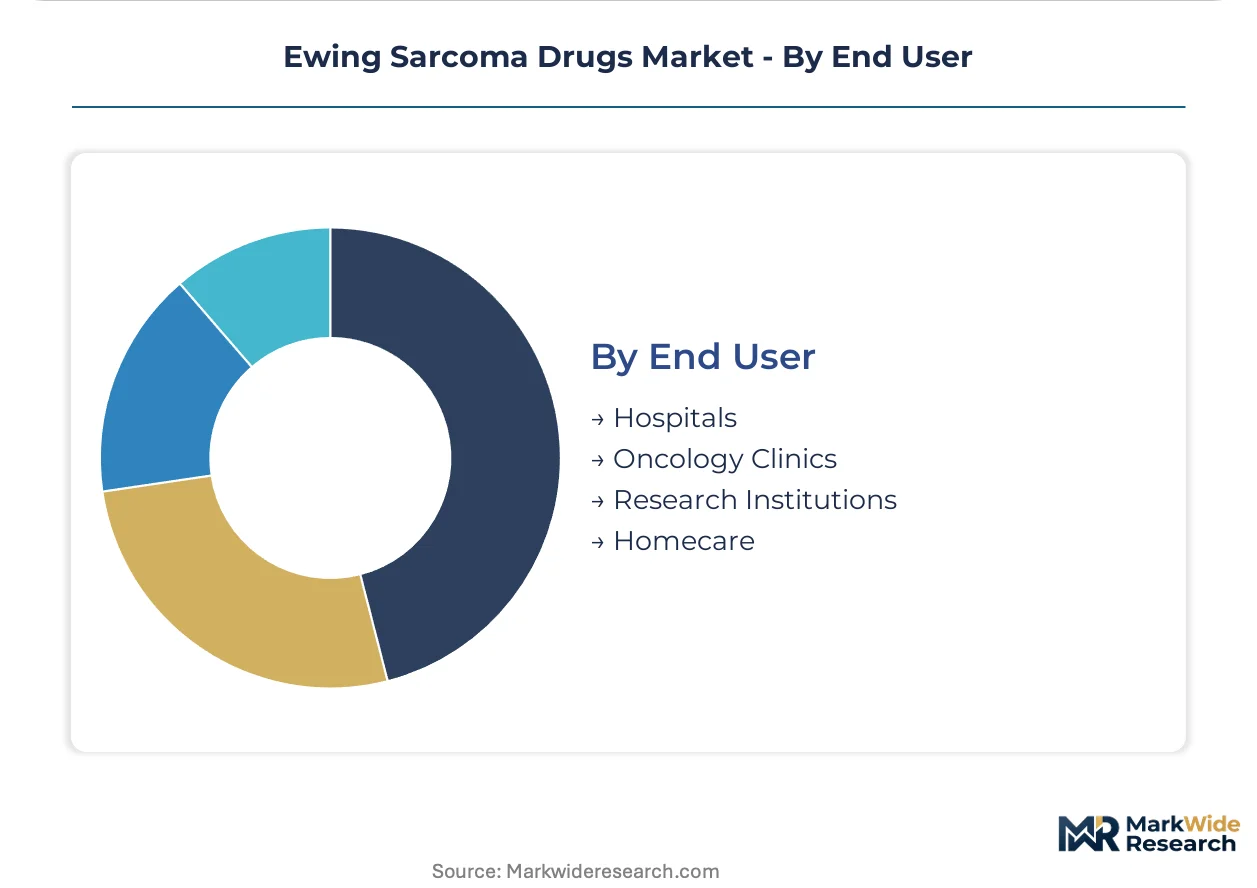
- Hospitals:Academic medical centers and children's hospitals administer complex multi-agent chemotherapy requiring intensive supportive care. Three dominant group purchasing organizations in the United States—Vizient, Premier, and HealthTrust—centralize formulary negotiations for high-cost oncology agents.
- Oncology Clinics:Community-based infusion centers handle selected maintenance and surveillance protocols. These settings prioritize oral agents and abbreviated infusion schedules to maximize throughput.
- Research Institutions:St. Jude Children's Research Hospital, National Cancer Institute-designated centers, and European reference networks conduct early-phase trials. Their procurement operates outside standard commercial contracting through investigator-initiated study mechanisms.
- Homecare:Oral maintenance therapy and subcutaneous growth factor administration shift selected care episodes to residential settings. Reimbursement complexity and nursing visit authorization constrain expansion.
Hospitals retain the largest share; momentum concentrates in oncology clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net therapeutic export flows from the United States and Germany exceed import dependence for Ewing sarcoma agents, while emerging markets in Asia-Pacific and Latin America rely on cross-border procurement for pediatric oncology infrastructure.
United States
FDA Rare Pediatric Disease Priority Review Vouchers concentrate development investment at St. Jude Children's Research Hospital and Memorial Sloan Kettering Cancer Center. The seven-year orphan drug exclusivity provisions anchor commercialization timelines for fusion-targeted therapies. Philadelphia and Houston pediatric oncology clusters drive Phase II trial density through Children's Oncology Group-affiliated sites.
Germany
EMA Paediatric Investigation Plan enforcement mandates parallel adult-pediatric development tracks for kinase inhibitors. The country's reference pricing system for hospital pharmaceuticals creates reimbursement predictability for novel agents. Heidelberg and Berlin sarcoma reference networks coordinate European trial enrollment through the Cooperative Weichteilsarkom Studiengruppe.
United Kingdom
NHS England's Cancer Drugs Fund cost-effectiveness thresholds restrict premium-priced targeted therapy access outside clinical trials. The National Institute for Health and Care Excellence maintains technology appraisal pathways specific to rare pediatric malignancies. London and Manchester pediatric oncology centers concentrate proton beam capacity for residual disease protocols.
Japan
PMDA's sakigake designation system accelerates regulatory review for pediatric oncology innovations addressing unmet need. Domestic pharmaceutical manufacturers prioritize oral formulation development for maintenance-phase protocols. Tokyo and Osaka academic medical centers anchor Asia-Pacific trial expansion for EWS-FLI1-directed therapeutics.
India
CDSCO's pediatric drug development guidelines align with WHO prequalification standards for generic chemotherapy manufacturing. Domestic production of vincristine and cyclophosphamide reduces import dependence for multi-agent regimens. Mumbai and Hyderabad oncology centers participate in international cooperative group trials through bilateral research agreements.
Ewing Sarcoma Drugs Market Vendor Landscape
Listed leaders compete with private specialists across regulatory navigation capabilities and rare disease commercialization infrastructure. Market structure tilts toward consolidated development pipelines where large-cap oncology portfolios absorb smaller fusion-targeted programs through strategic licensing. Three archetypes dominate: established biopharmaceutical conglomerates with pediatric oncology divisions, rare disease specialists with regulatory voucher expertise, and clinical-stage biotechnology firms with protein-degradation platforms. Competitive moves center on portfolio diversification into transcription-factor-directed modalities and geographic expansion through European reference network partnerships.
Within the rare disease specialist tier, Jazz Pharmaceuticals and Salarius Pharmaceuticals exemplify archetypes leveraging regulatory incentive structures. Pfizer anchors the established biopharmaceutical segment with oncology infrastructure spanning targeted therapy development. These entities occupy positions shaped by FDA voucher program dynamics and EMA pediatric mandate compliance requirements rather than conventional therapeutic area scale.
| Leading Market Players |
|---|
| Amgen |
| Jazz Pharmaceuticals |
| Salarius Pharmaceuticals |
| Inhibrx |
| Pfizer |
| Novartis |
| Merck |
| Bristol-Myers Squibb |
| Actuate Therapeutics |
| Others |
Supply Flow & Price Mechanics
Platinum-group metal refining capacity utilization in South African mining operations anchors cost floors for carboplatin-based combination regimens, concentrating pricing leverage among three dominant group purchasing organizations serving United States pediatric oncology centers while compressing margins for generic alkylating agent manufacturers.
Pricing Analysis
Hospital procurement managers anchor contract negotiations through Vizient, Premier, and HealthTrust, extracting volume-based rebates for multi-agent chemotherapy protocols. Three-tier pricing structure across originator biologics, authorized generics, and commodity cytotoxics reflects FDA orphan drug exclusivity premiums versus GPO-negotiated standard-of-care discounts. Cost compression in alkylating agent tiers intensifies because Indian and Chinese API manufacturers expanded vincristine and cyclophosphamide production capacity. Community oncology clinics exhibit highest price sensitivity due to fixed reimbursement rates, while academic medical centers with research mission subsidies tolerate premium targeted therapy pricing.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes periodically disrupt cold-chain distribution for temperature-sensitive antibody constructs requiring liquid nitrogen preservation. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland for cytotoxic backbone agents, while fill-finish operations for biologics cluster in Germany, Ireland, and Singapore. Platinum-group metal sourcing rests on South African and Russian mining concentration, exposing carboplatin supply to geopolitical volatility and export restriction risk. Distribution runs through specialty pharmaceutical wholesalers with pediatric oncology dedicated logistics networks, bypassing generalist hospital distribution channels for high-value targeted therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fusion-targeted therapy development demands rare pediatric oncology trial design expertise that exceeds current investigator pool capacity, creating persistent bottlenecks for site activation and protocol amendment execution across Children's Oncology Group-affiliated centers.
For Market Incumbents: Consolidate clinical development infrastructure through exclusive site access agreements with St. Jude Children's Research Hospital and Memorial Sloan Kettering, locking out competitor trial enrollment. Acquire protein-degradation platform capabilities through licensing rather than de novo R&D to compress target validation timelines against emerging biotechnology entrants. For New Entrants and Emerging Players: FDA Rare Pediatric Disease Priority Review Voucher fast-track eligibility enables abbreviated regulatory pathways for first-in-class EWS-FLI1-directed agents, opening white-space in maintenance-phase oral kinase inhibitor segments where adherence-driven protocol design creates differentiation. Target German and Austrian outpatient oncology networks for subcutaneous formulation pilot programs, leveraging existing reimbursement familiarity with interferon maintenance protocols. For Investors and Strategic Acquirers: Clinical-stage biotechnology firms with transcription-factor-directed PROTAC platforms represent the priority acquisition archetype, capturing mechanistic differentiation unavailable to established kinase inhibitor portfolios. Long-term viability hinges on biomarker-qualified surrogate endpoint acceptance by FDA and EMA, with circulating tumor DNA assay regulatory validation serving as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA parallel review pathway accelerates simultaneous fusion-detection assay and therapeutic approval timelines. |
| Academic Alliance Structuring | St. Jude open-science data sharing reduces duplicative preclinical investment for target validation programs. |
| Oral Formulation Development | EMA Paediatric Investigation Plan compliance mandates age-appropriate dosing schedules for adolescent adherence. |
| Protein-Degradation Platform Licensing | PROTAC technology miniaturizes druggable space for intrinsically disordered EWS-FLI1 transcription factor targets. |
| European Reference Network Partnership | Cooperative Weichteilsarkom Studiengruppe coordination streamlines Phase II recruitment across German and Austrian sites. |
Methodological Framework
Cross-validation between primary interviews with pediatric oncologists, regulatory affairs specialists, hospital formulary directors, and GPO contracting managers anchors the qualitative findings, supplemented by secondary validation against FDA orphan drug designations, EMA Paediatric Investigation Plan submissions, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation reconcile segmentation outputs across treatment modality, drug class, and administration route dimensions.
Sensitivity analysis frameworks test forecast robustness against regulatory timeline acceleration scenarios and platinum supply disruption events. The analytical approach segments by treatment type, molecular target class, delivery mechanism, and care setting across the projection horizon, with CAGRs derived from epidemiological incidence projections and therapy penetration curves. Forecast inputs incorporate Children's Oncology Group trial enrollment velocity, EMA PIP waiver frequency trends, and biomarker qualification pathway progression.
Underlying assumptions cover sustained orphan drug incentive program continuity and stable platinum-group metal supply chain configuration, with deviation risk concentrated in NHS England reimbursement restriction expansion and single-payer cost-effectiveness threshold compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Global Akabane Vaccines Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Insulin API Market