
 Macrolide Drugs Market | 2026-2036
Macrolide Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Macrolide Drugs Market Outlook
Project finance for active pharmaceutical ingredient facilities is fragmenting competitive access across the macrolide supply chain. Pfizer Inc. leverages captive fermentation capacity to sustain cost leadership in azithromycin bulk production. Teva Pharmaceutical Industries Ltd. anchors its position through backward integration into key intermediate synthesis. Sun Pharmaceutical Industries Ltd. competes on geographic reach across emerging markets with established regulatory dossiers.
Macrolide drugs are a class of bacteriostatic antibiotics characterized by a large lactone ring structure of 14 to 16 atoms, typically produced through bacterial fermentation or semi-synthetic modification, with protein synthesis inhibition as their primary mechanism of action against gram-positive and atypical pathogens. Their commercial purpose centers on treating respiratory, skin, and soft tissue infections where beta-lactam alternatives prove ineffective or contraindicated. The azithromycin segment dominates prescription volumes due to its favorable pharmacokinetic profile and shorter dosing regimens. Respiratory infection applications generate the deepest margin pools, particularly in hospital formulary contracts, while oral suspensions for pediatric homecare represent the fastest-expanding formulation channel.
The FDA governs macrolide approval through ANDA and NDA pathways, while the EMA's centralized procedure shapes access across European Union member states, and India's CDSCO aligns with ICH guidelines for export-oriented manufacturing inspections. These frameworks elevate barrier costs for new entrants and reinforce quality differentiation among established producers. Stakeholders must monitor regulatory divergence between FDA bioequivalence standards and emerging WHO prequalification requirements for procurement eligibility.
Market Dynamics
Hospital formulary consolidation in the United States is compressing supplier margins while simultaneously locking in volume commitments for azithromycin and clarithromycin procurement. This buyer-side concentration is forcing fermentation-based producers to reconfigure their capacity allocation models around multi-year tender structures rather than spot-market sales.
Growth Catalysts
- Respiratory Protocol Standardization:United States hospital systems are embedding macrolides into empiric pneumonia treatment pathways, creating predictable demand baselines for azithromycin injectables.
- FDA ANDA Streamlining:The abbreviated new drug application review pathway for generic macrolides is compressing approval timelines and accelerating competitive entry for fermentation-derived products.
- Indian Manufacturing Cluster Expansion:Bulk fermentation capacity around Ahmedabad and Hyderabad is scaling to capture export demand from WHO prequalification programs.
Market Restraints
- Fermentation Input Volatility:Corn steep liquor and soybean meal prices fluctuate with agricultural commodity cycles, squeezing margin predictability for bulk macrolide producers.
- Single-Source Intermediate Risk:Key macrolide precursors concentrate in Chinese chemical synthesis clusters, creating supply vulnerability for Indian and European formulators.
- Antimicrobial Stewardship Mandates:CDC and NHS England prescribing restrictions are narrowing eligible patient populations for empirical macrolide therapy in outpatient settings.
Strategic Opportunities
- Pediatric Oral Suspension Formulations:Homecare administration of azithromycin suspensions for community-acquired infections represents an underdeveloped margin pool in Southeast Asian markets.
- CDSCO Export Certification Alignment:India's convergence with ICH Q7 guidelines is opening prequalified supplier status for African and Latin American procurement tenders.
- Continuous Fermentation Technology:Adoption of perfusion bioreactor systems by European API manufacturers is digitizing process control and reducing batch-to-batch variability in erythromycin yields.
Industry Challenges
- Specialized Fermentation Talent Scarcity:Industrial microbiologists with Streptomyces strain optimization expertise command premium compensation, constraining capacity expansion timelines for mid-tier producers.
- Multi-Jurisdiction Dossier Maintenance:Simultaneous FDA, EMA, and WHO prequalification compliance requires dedicated regulatory affairs teams, elevating fixed costs for generic entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macrolide Drugs Market |
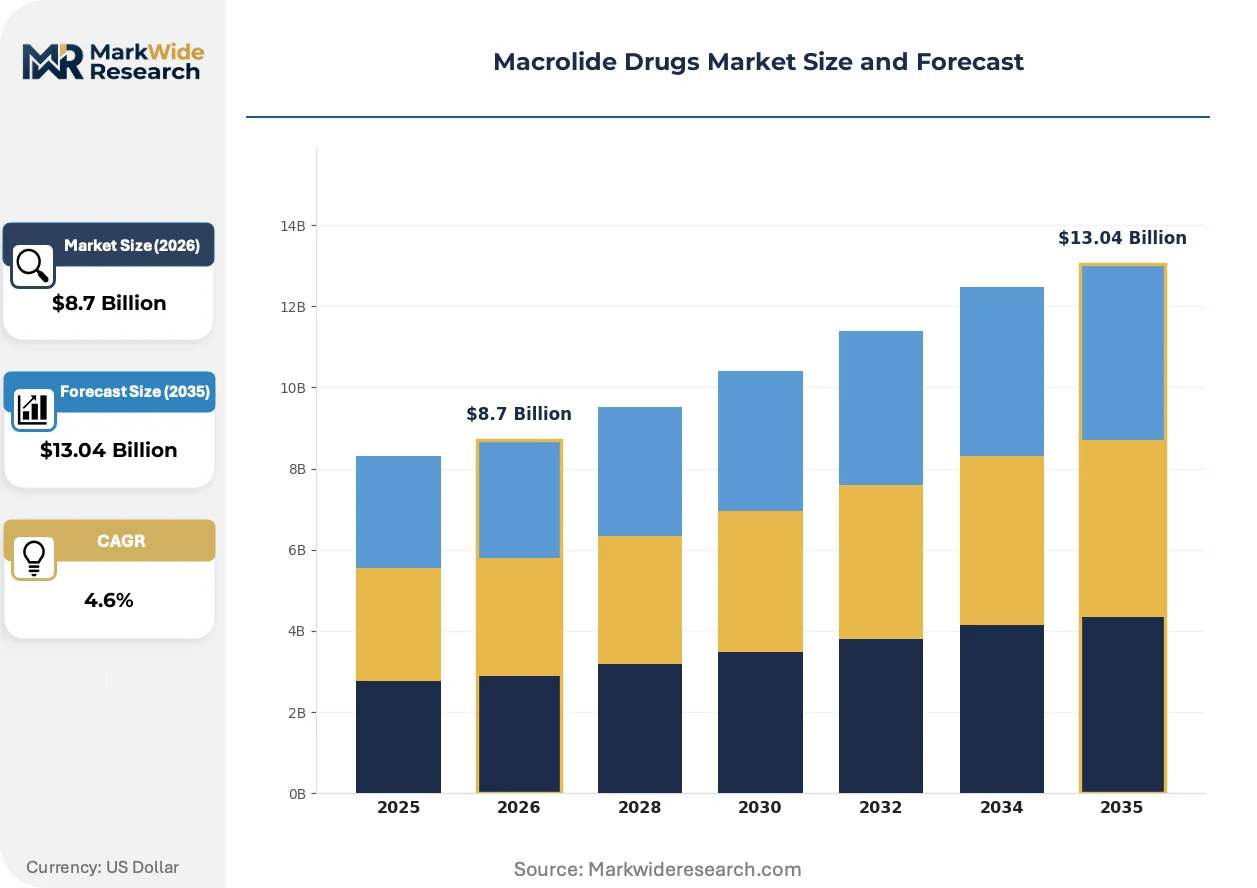
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erythromycin, Azithromycin, Clarithromycin, Roxithromycin Application: Respiratory Infections, Skin Infections, Gastrointestinal Infections, Sexually Transmitted Diseases End User: Hospitals, Clinics, Homecare Settings, Pharmacies Formulation Type: Tablets, Capsules, Injectable, Oral Suspensions |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Alkem Laboratories Ltd., Zydus Lifesciences Ltd., Lupin Limited, AbbVie Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macrolide Drugs Market Strategic Shifts
Process analytical technology is penetrating macrolide fermentation operations, replacing offline quality testing with real-time biomarker monitoring. This instrumentation shift is compressing batch release timelines and enabling parametric release protocols for high-volume azithromycin production.
Digital twin modeling of bioreactor performance is digitizing scale-up protocols for new macrolide strains. Contract fermentation facilities in Ireland and Singapore are deploying these simulations to reduce technology transfer failures between pilot and commercial volumes. The structural consequence is a compression of development timelines for semi-synthetic macrolide derivatives.
EMA's revised environmental risk assessment guidelines for antibiotic manufacturing are mandating tighter effluent controls at European fermentation sites. Bulk producers must now demonstrate minimum inhibitory concentration degradation in wastewater streams before receiving manufacturing authorizations. German and Dutch API facilities are responding by installing advanced oxidation process units to pretreat fermentation broth discharge.
Hospital purchasing cooperatives in the United States are consolidating macrolide procurement under single-source contracts with price-volume escalation clauses. This buyer aggregation is displacing traditional distributor-mediated sales and forcing manufacturers to maintain dedicated account management teams for GPO negotiation. The shift is most visible in the 340B drug pricing program, where covered entities negotiate directly with azithromycin suppliers.
Macrolide Drugs Market Segmentation
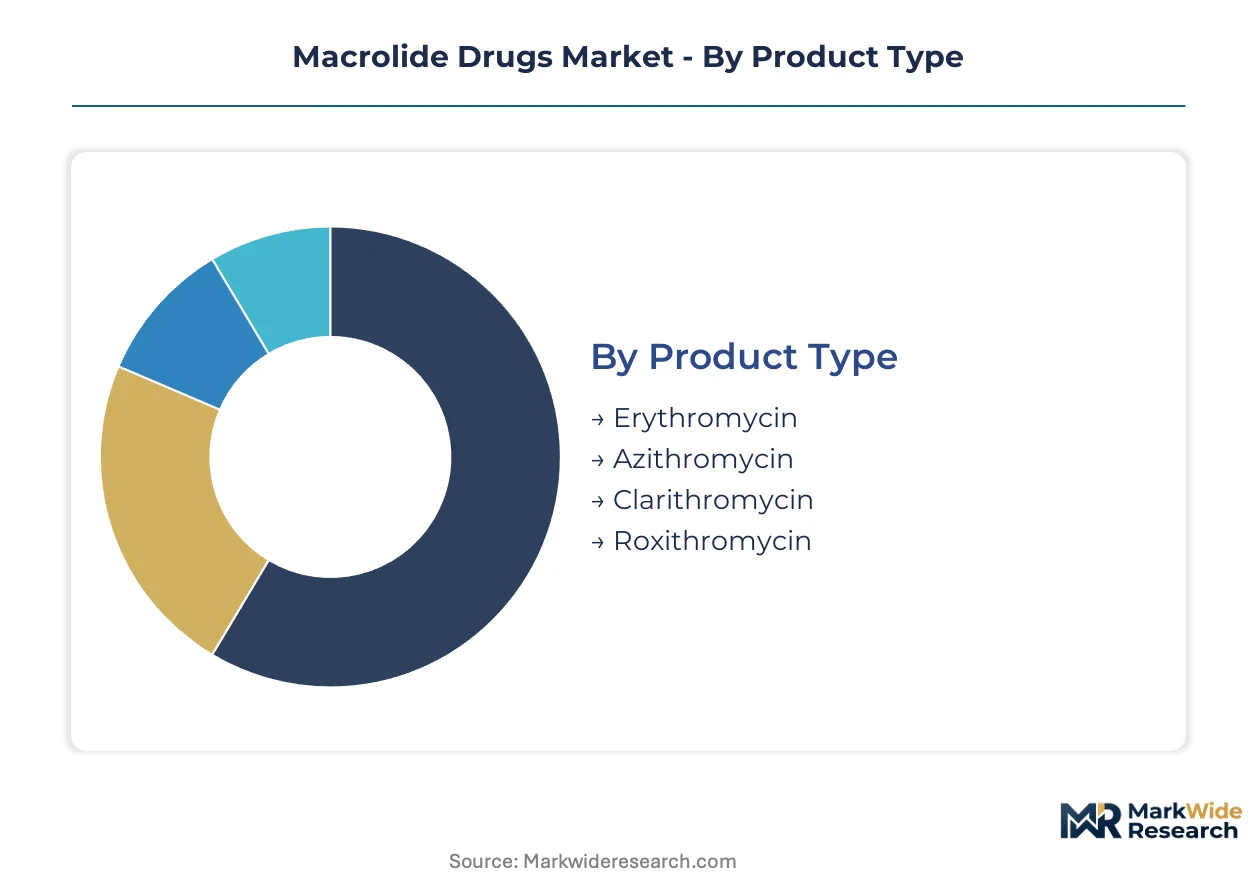
Macrolide market segmentation reveals how formulation chemistry, clinical setting, and patient population intersect to determine procurement patterns. Manufacturers configure fermentation capacity and regulatory dossiers around these divides to capture margin pools across hospital formulary and retail pharmacy channels.
Product Type:
The use-case spectrum spans empiric respiratory therapy to targeted atypical coverage, with pharmacokinetic half-life and drug interaction profiles driving prescriber selection.
- Azithromycin:A 15-membered azalide with extended tissue penetration and once-daily dosing. Hospital procurement in the United States concentrates in injectable forms for pneumonia protocols, while India's CDSCO export certifications target African tender programs for oral tablets.
- Clarithromycin:A 14-membered macrolide with superior Helicobacter pylori eradication rates. European hospital formularies in Germany and France favor this agent for combination triple therapy, constrained by CYP3A4 interaction warnings that narrow eligible patient populations.
- Erythromycin:The original fermentation-derived macrolide with established generic manufacturing infrastructure across Indian clusters.
- Roxithromycin:A semi-synthetic derivative with improved gastric tolerance profiles, concentrated in East Asian prescription markets.
The dominant share belongs to azithromycin, while clarithromycin is closing the gap fastest in European gastrointestinal applications.
Application:
Cost tier stratification separates acute hospital-managed infections from chronic or ambulatory conditions with reimbursement implications.
- Respiratory Infections:Community-acquired pneumonia and atypical bronchitis represent the deepest margin pool. United States hospital systems embed macrolides into sepsis bundle protocols, creating multi-year volume commitments that lock in supplier relationships through GPO structures.
- Skin Infections:Cellulitis and soft tissue abscesses drive outpatient prescription volumes where generic substitution rates exceed 90%. Teva Pharmaceutical Industries Ltd. anchors retail pharmacy distribution through backward integration into key intermediate synthesis.
- Gastrointestinal Infections:H. pylori eradication regimens in European outpatient settings.
- Sexually Transmitted Diseases:Chlamydia and gonorrhea combination therapy protocols in public health clinics.
Respiratory applications command premium hospital pricing, while skin infection volumes expand most quickly in emerging market retail channels.
End User:
Customer type determines whether procurement flows through centralized tender processes or fragmented retail reimbursement.
- Hospitals:Formulary consolidation under 340B drug pricing program entities and purchasing cooperatives. Account management teams negotiate directly with covered entities, displacing traditional distributor relationships for azithromycin injectables.
- Homecare Settings:Pediatric oral suspension administration for community-acquired infections. Southeast Asian markets show underpenetrated demand for home-based antibiotic delivery models.
- Clinics:Outpatient infusion centers and urgent care facilities with limited formulary autonomy.
- Pharmacies:Retail dispensing subject to generic substitution laws and antimicrobial stewardship counseling requirements.
Hospitals retain the largest procurement value, though homecare settings are climbing the fastest as pediatric formulations penetrate Asian markets.
Formulation Type:
Supply concentration in fermentation-based bulk production shapes which dosage forms achieve cost competitiveness.
- Oral Suspensions:Powder-for-reconstitution formats dominate pediatric prescribing. Pfizer Inc. leverages captive fermentation capacity to sustain cost leadership in azithromycin suspension supply, targeting WHO prequalification for African procurement eligibility.
- Tablets:Film-coated immediate-release formats for adult outpatient therapy. Indian generic manufacturers around Ahmedabad and Hyderabad scale tableting capacity to capture CDSCO export certification alignment with ICH Q7 guidelines.
- Capsules:Gelatin-shell formulations with limited differentiation in saturated generic markets.
- Injectable:Lyophilized vials for hospital infusion with sterility testing requirements that elevate barrier costs for new entrants.
Tablets hold the dominant prescription volume position, while oral suspensions are gaining share fastest in pediatric homecare expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows define regional positioning in macrolide drugs, with fermentation capacity clustering in supply-side economies and hospital procurement concentrating in demand-side markets. The United States runs a structural deficit in bulk active pharmaceutical ingredients, sourcing azithromycin intermediates from Indian and Chinese suppliers. European formulators maintain selective self-sufficiency in erythromycin derivatives while importing clarithromycin for gastrointestinal protocols.
United States
Hospital purchasing cooperatives under the 340B drug pricing program embed azithromycin into empiric pneumonia pathways, creating predictable volume baselines for injectable formulations. FDA's streamlined ANDA review pathway compresses approval timelines for generic entrants, reshaping competitive access. Pfizer Inc. maintains captive fermentation capacity for domestic azithromycin bulk production, anchoring supply security for hospital formulary contracts.
Germany
EMA's centralized procedure shapes clarithromycin access for Helicobacter pylori eradication regimens across German hospital formularies. Revised environmental risk assessment guidelines mandate advanced oxidation process units for fermentation effluent pretreatment at API facilities in North Rhine-Westphalia. Bavarian contract manufacturers deploy digital twin bioreactor modeling to reduce technology transfer failures for semi-synthetic macrolide derivatives.
India
CDSCO export certification alignment with ICH Q7 guidelines opens prequalified supplier status for African and Latin American procurement tenders. Bulk fermentation capacity scales around Ahmedabad and Hyderabad to capture WHO prequalification program demand. Sun Pharmaceutical Industries Ltd. leverages established regulatory dossiers to compete on geographic reach across emerging markets.
China
Single-source intermediate concentration in chemical synthesis clusters creates supply vulnerability for Indian and European formulators dependent on imported macrolide precursors. NMPA manufacturing inspections align with ICH standards for export-oriented production. Yangtze River Delta fermentation facilities face pressure from EMA environmental guidelines as European customers demand supply chain transparency.
Brazil
ANVISA regulatory frameworks shape import dependency for macrolide formulations in public health clinics treating sexually transmitted diseases. Ministry of Health procurement tenders favor WHO-prequalified suppliers, channeling demand toward Indian and Chinese exporters. São Paulo-based distributors mediate hospital access while antimicrobial stewardship programs narrow outpatient prescribing eligibility.
Macrolide Drugs Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fermentation and intermediate synthesis. The vendor base stratifies around captive fermentation capacity, backward-integrated intermediate production, and geographic reach through regulatory dossiers. Three archetypes dominate: bulk API producers with strain optimization expertise, formulators with hospital GPO relationships, and generic entrants leveraging FDA ANDA streamlining. Competitive moves center on multi-year tender capture and continuous fermentation technology adoption.
Within the fermentation-anchored tier, Pfizer Inc. and Teva Pharmaceutical Industries Ltd. occupy positions reflecting scale advantages in bulk production and intermediate synthesis control. Sun Pharmaceutical Industries Ltd. exemplifies the geographic reach archetype through CDSCO-aligned export certification. Among Indian generic specialists, Alkem Laboratories Ltd., Zydus Lifesciences Ltd., and Lupin Limited represent the competitive entry vector accelerating through streamlined regulatory pathways.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Alkem Laboratories Ltd. |
| Zydus Lifesciences Ltd. |
| Lupin Limited |
| AbbVie Inc. |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Chinese chemical synthesis clusters for erythromycin A precursors concentrate upstream supply, anchoring margin pools in Indian formulator networks and European hospital GPO contracts. This concentration forces downstream buyers into long-term offtake agreements to secure fermentation input predictability against agricultural commodity cycles.
Pricing Analysis
Hospital GPO buyers anchor contract-based long-term offtake pricing for azithromycin injectables, with premium-mid-economy pricing differentiation driven by FDA bioequivalence tier and sterility certification grade. Cost compression in oral generic tablets is intensifying because Indian manufacturers scale tableting capacity for WHO prequalification tenders. Retail pharmacy chains exhibit highest price sensitivity, while hospital systems with 340B pricing access show lowest.
Supply Chain Analysis
Contract fermentation facilities in Ireland and Singapore hold perfusion bioreactor capacity for semi-synthetic macrolide derivatives. Bulk API production draws from India, China, and Germany, with corn steep liquor and soybean meal as critical fermentation feeds. Single-source intermediate vulnerability in Chinese chemical synthesis clusters creates supply chain risk. Distribution runs through hospital purchasing cooperatives and WHO prequalification procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial microbiologists with Streptomyces strain optimization expertise are scarce, constraining capacity expansion timelines for mid-tier fermentation producers and elevating compensation premiums for qualified talent.
For Market Incumbents: Harden captive fermentation capacity through backward integration into key intermediate synthesis, defending against emerging Indian generic entrants leveraging FDA ANDA streamlining. Invest in continuous fermentation technology adoption to compress batch-to-batch variability and sustain cost leadership in azithromycin bulk production. For New Entrants and Emerging Players: Establish a beachhead in pediatric oral suspension formulations for Southeast Asian homecare markets, where demand penetration remains underdeveloped. Target WHO prequalification status as the go-to-market angle, using CDSCO-aligned export certifications to unlock African and Latin American procurement tenders. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian generic manufacturers possessing established regulatory dossiers but limited fermentation strain optimization capabilities. Five-to-ten year viability hinges on regulatory divergence between FDA bioequivalence standards and emerging WHO requirements. Monitor antimicrobial stewardship mandate expansion as the inflection indicator for volume risk in outpatient prescribing.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Technology Adoption | Perfusion bioreactor systems digitize process control and reduce erythromycin yield variability for European API manufacturers. |
| Backward Integration into Intermediate Synthesis | Teva Pharmaceutical Industries Ltd. anchors retail pharmacy distribution through in-house production of key macrolide precursors. |
| WHO Prequalification Certification Alignment | India's CDSCO convergence with ICH Q7 guidelines opens prequalified supplier status for African procurement tenders. |
| Pediatric Formulation Portfolio Expansion | Pfizer Inc. targets WHO prequalification for azithromycin oral suspension supply to capture African procurement eligibility. |
| Hospital GPO Direct Contracting | 340B covered entities negotiate directly with azithromycin suppliers, displacing traditional distributor-mediated sales channels. |
Study Parameters
A spread of perspectives from fermentation operations directors, regulatory affairs leads at Indian API manufacturers, hospital formulary directors in United States GPOs, and WHO prequalification program officers converged on the working assumptions. These primary insights combined with FDA ANDA filings, EMA centralized procedure submissions, CDSCO manufacturing inspection records, and customs trade data for erythromycin intermediates. Bottom-up capacity modeling and top-down prescription volume analysis provided triangulation.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation by macrolide type, formulation chemistry, clinical setting, and regional regulatory cluster. CAGRs were derived from modeling fermentation capacity expansion against hospital procurement volume commitments. Forecast inputs included antimicrobial stewardship policy trajectory and agricultural commodity price cycles for fermentation feeds.
Stress conditions across corn steep liquor price volatility, Chinese intermediate export restrictions, and CDC prescribing guideline tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and strain optimization yield improvements. Quarterly review of WHO prequalification approval cadence and hospital GPO contract renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Targeted Protein Degradation Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
North America Generic Oncology Drug Market