
 Laband Syndrome Therapeutics Market | 2026-2036
Laband Syndrome Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Laband Syndrome Therapeutics Market Foresight
Multi-source clinical trial partnerships is recalibrating how developers secure patient cohorts for Laband Syndrome studies. Pfizer Inc. leverages its global site network to access dispersed pediatric populations across continents. BioMarin Pharmaceutical anchors its development strategy in rare genetic disease expertise built through prior enzyme replacement programs. Eli Lilly and Company competes by extending its immunology infrastructure into ultra-orphan indications with overlapping mechanistic pathways.
Laband Syndrome therapeutics target the progressive gingival fibromatosis and skeletal anomalies characteristic of this rare hereditary connective tissue disorder, with treatment protocols requiring specialized multidisciplinary coordination between dental surgeons, geneticists, and orthopedic specialists. Small molecules currently occupy the largest commercial footprint due to established manufacturing scalability and oral bioavailability advantages. Gene therapy represents the fastest-expanding development category, though margin pools remain concentrated in biologics where production complexity creates durable pricing power for incumbent suppliers.
FDA orphan drug designation and EMA priority medicines pathways shape competitive timelines by granting market exclusivity provisions and protocol assistance for qualifying sponsors. The EU AI Act introduces emerging compliance requirements for algorithmic patient stratification tools used in rare disease recruitment. Stakeholders must monitor how evolving FDA guidance on gene editing manufacturing controls intersects with EMA advanced therapy medicinal products standards to determine optimal regulatory filing sequences.
Market Dynamics
Gene therapy manufacturing scale-up is compressing development timelines for Laband Syndrome therapeutics while fragmenting competitive advantage between platform technology owners and specialty biologics contractors. This structural shift is redistributing value capture upstream toward viral vector suppliers and downstream toward integrated rare disease centers.
Growth Catalysts
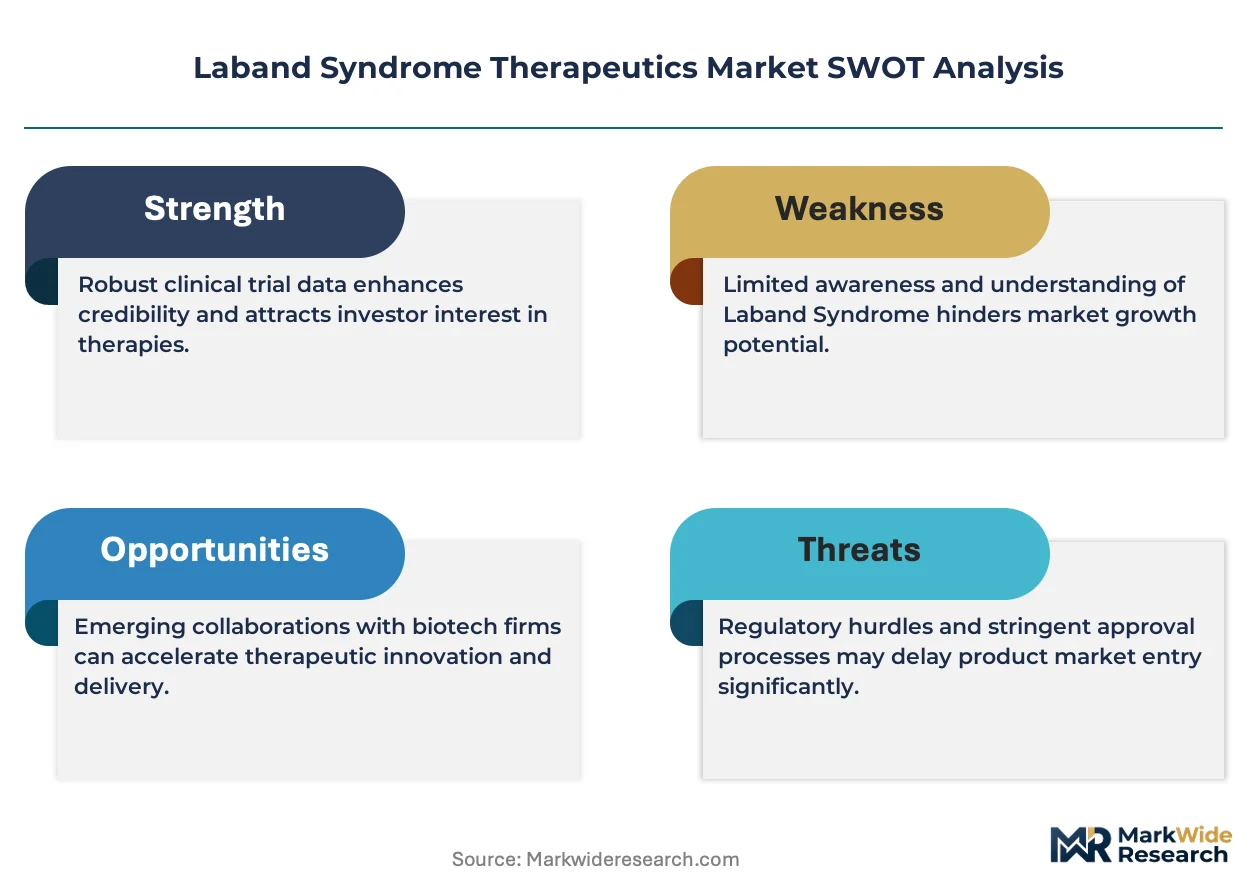
- FDA Orphan Drug Incentives:Tax credits for clinical research and seven-year market exclusivity provisions accelerate sponsor commitment to ultra-orphan indications with limited precedent.
- Enzyme Replacement Expertise:Prior success in lysosomal storage disorders has built manufacturing infrastructure transferable to Laband Syndrome protein-based interventions.
- German Pediatric Genetic Networks:Dense clustering of specialized clinics in Munich and Heidelberg enables rapid patient identification and longitudinal outcome tracking.
Market Restraints
- Plasmid DNA Supply Bottlenecks:Contract manufacturers in North America and Europe face eighteen-month queue times for GMP-grade starting material.
- EMA Advanced Therapy Complexity:Divergent CMC requirements between member states create regulatory friction for centralized gene therapy approvals.
- Orthopedic-Dental Care Coordination Gaps:Absence of standardized referral protocols between specialties delays treatment initiation and complicates reimbursement.
Strategic Opportunities
- AI-Driven Patient Stratification:Machine learning tools applied to German and US electronic health records accelerate identification of undiagnosed pediatric cases.
- Subcutaneous Delivery Formulations:Shift from intravenous to injectable routes reduces treatment burden and expands addressable caregiver populations.
- EU AI Act Compliance Services:Algorithmic transparency requirements create advisory revenue streams for developers of recruitment automation platforms.
Industry Challenges
- Viral Vector Manufacturing Talent Scarcity:Limited pools of process engineers with GMP gene therapy experience constrain capacity expansion at contract development organizations.
- Cross-Border Sample Logistics:Temperature-controlled transport of gingival biopsies between national reference laboratories introduces integrity risks and customs delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laband Syndrome Therapeutics Market |
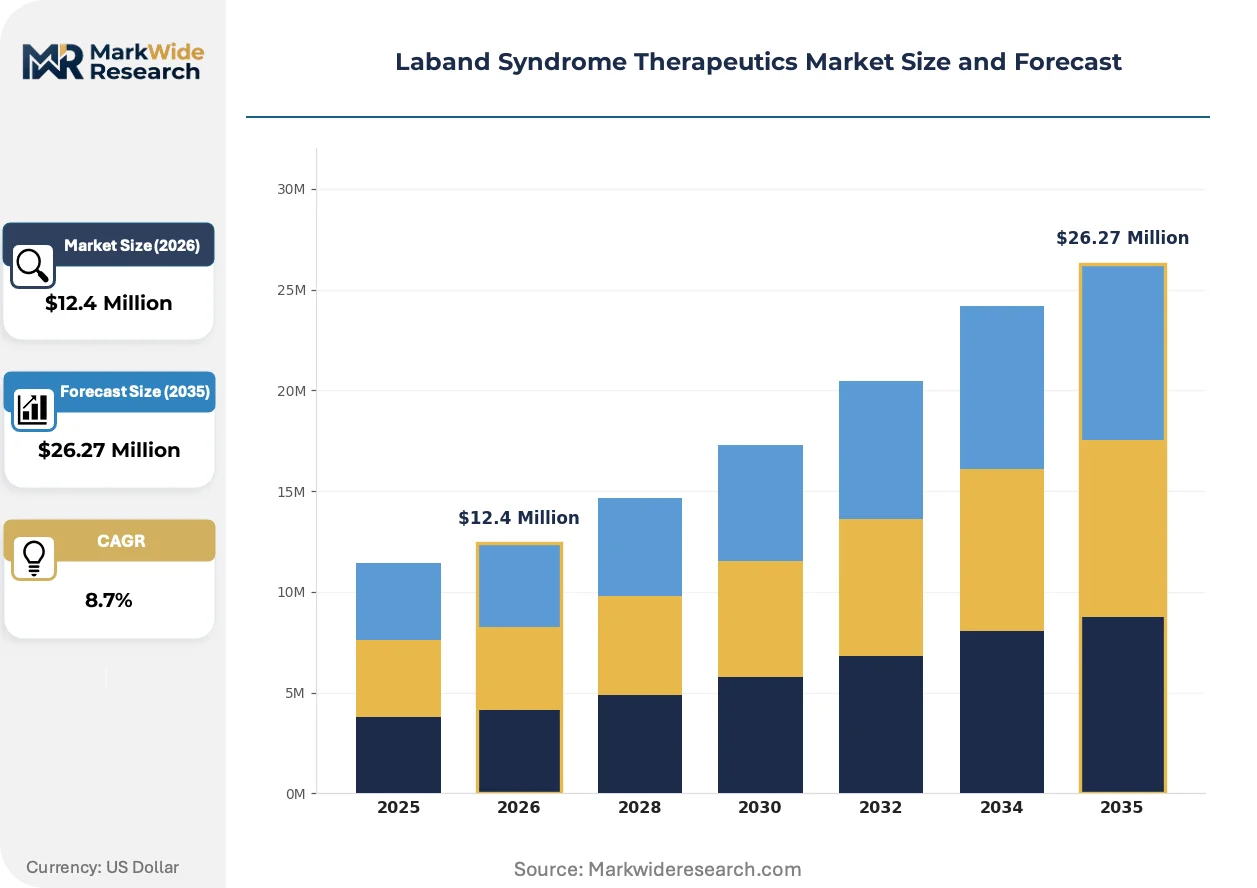
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $26.27 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Biologics, Gene Therapy, Combination Therapy Application: Pediatric Care, Genetic Disorder Treatment, Symptom Management, Clinical Trials Delivery Mode: Oral Administration, Injectable, Topical Application, Intravenous End User: Hospitals, Clinics, Research Laboratories, Home Care |
| Companies Covered | Pfizer Inc., Novartis AG, Eli Lilly and Company, Bristol-Myers Squibb, Amgen Inc., BioMarin Pharmaceutical, AbbVie, Gilead Sciences, Biogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laband Syndrome Therapeutics Market Shifts & Advancements
Platform standardization is converging with adaptive trial designs to reshape how Laband Syndrome therapeutics advance from preclinical stages through conditional approval. These intersecting forces are compressing traditional development timelines while elevating the importance of real-world evidence collection infrastructure.
CRISPR-based gene editing is unifying correction strategies for the GINGF locus mutations underlying Laband Syndrome phenotypes. Academic medical centers in Boston and Leiden are adopting these platforms for investigator-initiated trials. This convergence is enabling single-disease curative approaches that bypass chronic protein replacement economics.
EMA's priority medicines pathway is accelerating assessment timelines for therapies addressing unmet dental-skeletal morbidity. Sponsors receive enhanced scientific advice and accelerated review commitments. Pediatric genetic clinics in Germany and the Netherlands are restructuring internal workflows to align with these compressed regulatory schedules.
Caregiver advocacy networks are consolidating procurement influence through rare disease foundation purchasing cooperatives. These aggregators negotiate site-of-care contracts directly with specialty pharmacy distributors. This concentration is most visible in US metropolitan areas with established disease-specific family support organizations.
Laband Syndrome Therapeutics Market Segmentation
Laband Syndrome therapeutics demand fragments across four distinct structural dimensions. Product type determines manufacturing infrastructure requirements. Application and delivery mode shape reimbursement pathways. End user concentration dictates commercial access strategies for developers.
Product Type:
Standalone therapeutic platforms dominate current revenue capture, while embedded genetic correction systems attract development capital.
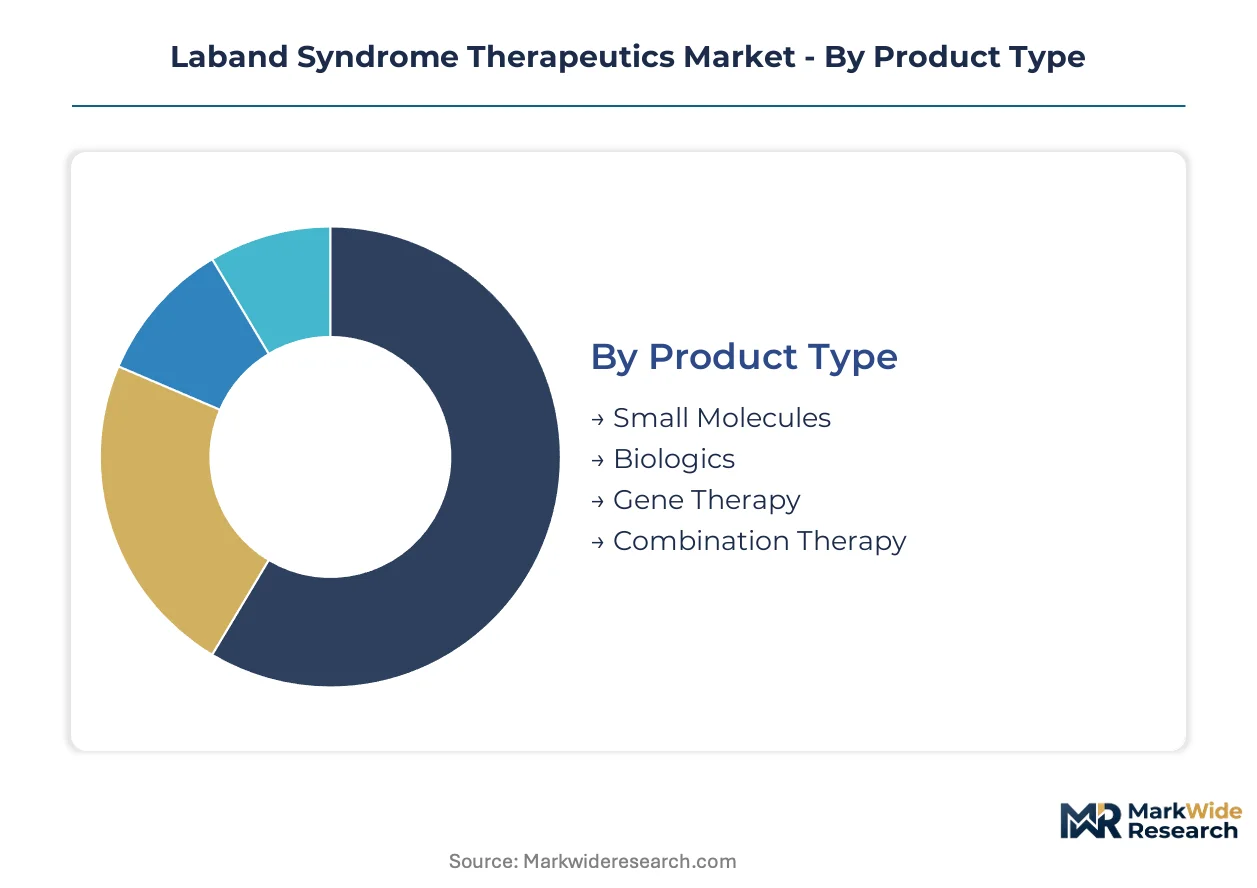
- Small Molecules:Oral bioavailability and established GMP manufacturing routes secure commercial scale for gingival fibromatosis symptom control. Demand concentrates in US specialty pharmacy networks where prior authorization pathways favor familiar dosage forms.
- Gene Therapy:Single-dose curative potential for GINGF locus mutations compresses lifetime treatment economics despite upfront manufacturing complexity. Boston and Leiden academic centers anchor investigator-initiated trial recruitment for these platforms.
- Biologics:Protein-based interventions leverage transferable enzyme replacement infrastructure from lysosomal storage disorder programs.
- Combination Therapy:Co-administration protocols addressing dental-skeletal multimorbidity require specialized multidisciplinary coordination.
Volume placements concentrate in Small Molecules; the faster expansion belongs to Gene Therapy.
Application:
Cost tier stratification separates acute intervention budgets from longitudinal management programs.
- Pediatric Care:Early intervention protocols in Munich and Heidelberg genetic clinics prioritize growth-sparing skeletal management. German pediatric networks enable rapid patient identification through dense specialist clustering.
- Genetic Disorder Treatment:Definitive correction approaches target underlying GINGF mutations rather than phenotypic manifestations. EMA priority medicines pathway accelerates assessment timelines for these disease-modifying candidates.
- Symptom Management:Palliative protocols address progressive gingival overgrowth and joint complications.
- Clinical Trials:Adaptive designs compress traditional development timelines through real-world evidence integration.
Revenue concentration sits with Pediatric Care; Genetic Disorder Treatment climbs the fastest.
Delivery Mode:
Patient burden differentiation drives caregiver preference formation across administration routes.
- Oral Administration:Familiar dosing schedules reduce treatment abandonment in adolescent populations managing concurrent orthodontic interventions.
- Injectable:Subcutaneous formulations expand addressable caregiver populations by eliminating infusion center dependency. US metropolitan rare disease foundations negotiate site-of-care contracts favoring home administration.
- Topical Application:Localized gingival delivery minimizes systemic exposure for surface-level fibromatosis control.
- Intravenous:Hospital-based infusion requirements concentrate utilization in centers of excellence with dedicated rare disease nursing staff.
Utilization clusters around Oral Administration; Injectable routes gain share fastest.
End User:
Maturity gradients separate established institutional purchasers from emerging distributed care models.
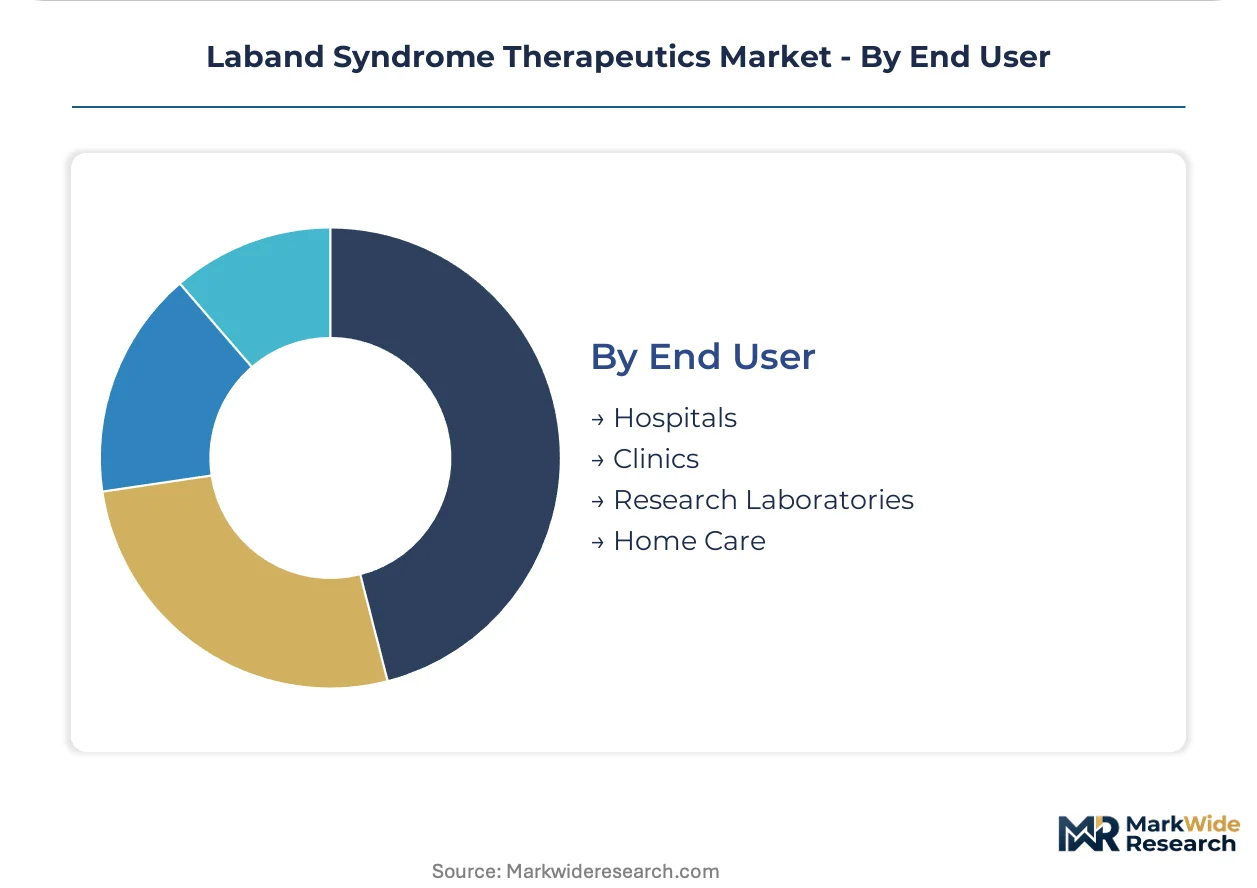
- Hospitals:Integrated rare disease centers in Boston and Heidelberg coordinate orthopedic-dental surgical sequences. These institutions capture complex multimorbidity cases requiring anesthesia-supported interventions.
- Clinics:German pediatric genetic networks anchor longitudinal outcome tracking for natural history studies. Dense Munich-Heidelberg clustering enables rapid protocol amendments based on emerging safety signals.
- Research Laboratories:Academic medical centers house CRISPR platform development for investigator-initiated gene editing trials.
- Home Care:Family support organizations in US metropolitan areas consolidate procurement influence through purchasing cooperatives.
Case volume concentrates in Hospitals; Home Care shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialty hospital networks concentrate demand through dedicated rare disease centers of excellence, while German pediatric genetic clinics anchor European patient identification capacity. FDA orphan drug incentives and EMA priority medicines pathways create divergent regulatory arbitrage opportunities across Atlantic markets. Industrial clustering in Boston, Heidelberg, and Leiden shapes therapeutic development geography.
United States
Pediatric genetic clinics in Boston and New York Metro drive patient cohort assembly for Laband Syndrome trials. FDA grants seven-year market exclusivity and tax credits through orphan drug designation. The Greater Boston biotech corridor houses CRISPR platform development for investigator-initiated gene editing studies.
Germany
Munich and Heidelberg pediatric networks enable rapid longitudinal outcome tracking for natural history studies. EMA priority medicines pathway provides accelerated assessment timelines for disease-modifying candidates. Bavaria's dense specialist clustering supports protocol amendments based on emerging safety signals.
Netherlands
Leiden academic medical centers adopt gene editing platforms for ultra-orphan indication research. EMA advanced therapy medicinal products standards guide CMC requirements for viral vector manufacturing. The Randstad region concentrates contract development organizations with GMP gene therapy experience.
United Kingdom
London rare disease centers coordinate orthopedic-dental surgical sequences for complex multimorbidity cases. MHRA aligns with EMA standards while maintaining independent accelerated access pathways. The Southeast England research corridor integrates real-world evidence collection infrastructure.
Switzerland
Swissmedic's streamlined advanced therapy approvals attract gene therapy sponsors seeking regulatory efficiency. Basel's biologics manufacturing base transfers enzyme replacement expertise to protein-based interventions. The country's centralized healthcare system enables rapid treatment protocol adoption.
Laband Syndrome Therapeutics Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers secure access to dispersed pediatric populations and viral vector manufacturing capacity. The vendor base concentrates around three tiers: global pharmaceutical conglomerates with rare disease divisions, mid-cap biotech specialists in genetic disorders, and platform technology owners controlling gene editing IP. Platform licensing and site network expansion represent the two primary competitive vectors reshaping market position.
Within the global pharmaceutical tier, Pfizer Inc. and Novartis AG exemplify archetypes leveraging established site networks and prior rare disease infrastructure. Eli Lilly and Company occupies a position bridging immunology expertise with ultra-orphan expansion. BioMarin Pharmaceutical represents the specialist archetype, anchoring its presence in enzyme replacement programs transferable to protein-based interventions. These three companies collectively illustrate how prior manufacturing experience and therapeutic area concentration determine competitive positioning in ultra-orphan markets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| Amgen Inc. |
| BioMarin Pharmaceutical |
| AbbVie |
| Gilead Sciences |
| Biogen |
| Others |
Supply & Pricing Matrix
Specialty biologics contractors with private-equity backing anchor viral vector manufacturing capacity, concentrating supply-side pricing power while compressing margins for developers dependent on external GMP production. This ownership pattern tightens both input cost discipline and downstream contracting leverage across the Laband Syndrome therapeutic value chain.
Pricing Analysis
Volume placements concentrate in small-molecule symptom control, while gene therapy commands premium positioning despite minimal patient throughput. Three-tier pricing structure across premium gene-editing platforms, standard biologic interventions, and economy small-molecule maintenance separates reimbursement tiers by curative intent. Cost compression in the small-molecule tier intensifies because oral generic substitutes erode originator pricing. Pediatric specialty clinics demonstrate lowest price sensitivity due to bundled reimbursement protocols, whereas home care purchasing cooperatives negotiate aggressively on administration-route economics.
Supply Chain Analysis
Single-source vulnerability sits with North American plasmid DNA suppliers facing eighteen-month GMP queue times. Manufacturing gravity centers on the United States, Germany, and the Netherlands for viral vector production. Raw material dependencies include GMP-grade plasmid DNA, HEK293 cell lines, and specialized bioreactor media. Tariff exposure on temperature-controlled logistics equipment amplifies cross-border sample transport risks. Distribution runs through integrated rare disease centers of excellence with captive specialty pharmacy relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform technology owners with manufacturing assets are consolidating competitive position as plasmid DNA bottlenecks force cash-constrained developers toward acquisition or partnership exits. Viral vector capacity scarcity is the primary pressure accelerating this consolidation dynamic.
For Market Incumbents: Acquire GMP gene therapy manufacturing facilities in the Randstadt corridor to secure captive viral vector supply. Lock in long-term plasmid DNA offtake agreements with North American contract manufacturers before queue times extend further. Vertical integration into subcutaneous formulation development addresses caregiver preference shifts away from infusion center dependency. For New Entrants and Emerging Players: Underserved home care purchasing cooperatives in US metropolitan areas offer the most penetrable entry point for subcutaneous delivery formulations. German pediatric genetic networks present secondary white-space opportunity for natural history study partnerships. A go-to-market angle anchored in EU AI Act compliance services for algorithmic patient stratification tools bypasses direct therapeutic development capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biotech specialists with existing enzyme replacement infrastructure in Bavaria or the Greater Boston corridor. These assets offer transferable manufacturing expertise across rare genetic indications with five-to-ten-year viability windows tied to EMA priority medicines pathway maturation. Monitor FDA gene editing manufacturing guidance publication as the critical inflection signal for regulatory filing sequence optimization.| Strategic Initiative | Industry Significance |
|---|---|
| Viral Vector Manufacturing Scale-Up | Captive GMP capacity in the Netherlands compresses development timelines for EMA submissions. |
| Subcutaneous Formulation Development | Home administration protocols expand addressable caregiver populations beyond infusion center catchments. |
| EU AI Act Compliance Services | Algorithmic transparency advisory creates non-dilutive revenue for recruitment platform developers. |
| Plasmid DNA Supply Agreement | Long-term offtake with North American contractors insulates against eighteen-month queue extensions. |
| Pediatric Genetic Network Partnership | Munich-Heidelberg clinic clustering enables rapid protocol amendment for investigator-initiated trials. |
Research Methodology
Independent corroboration across regulatory affairs specialists, GMP manufacturing directors, and rare disease center procurement managers underwrites the qualitative findings. Secondary validation draws from FDA orphan drug designation filings, EMA priority medicines pathway submissions, ClinicalTrials.gov protocol records, and German pediatric genetic network outcome databases. Bottom-up patient cohort modeling and top-down therapeutic category sizing were reconciled through iterative triangulation.
Rate-of-change decomposition across the projection horizon separates volume expansion in pediatric care from value capture in genetic disorder treatment. Segmentation dimensions modeled include product type, application category, delivery mode, and end-user concentration. CAGRs were derived from natural history study enrollment trajectories and regulatory approval pathway timelines. Forecast inputs incorporate EMA advanced therapy medicinal products standard evolution and FDA gene editing manufacturing control guidance development.
Revisions become necessary when plasmid DNA supply queue times extend beyond current contracting horizons or when EMA member-state CMC divergences fragment centralized approval pathways. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Iran Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Global Immuno Oncology Assays Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Bioequivalence Studies Market