
 Interleukin-6 (IL-6) Inhibitors Market | 2026-2036
Interleukin-6 (IL-6) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Interleukin-6 (IL-6) Inhibitors Market Foresight
Biologics manufacturing platforms is fragmenting as contract development organizations scale single-use bioreactor capacity for monoclonal antibody production. Novartis AG leverages its integrated biologics manufacturing network to sustain supply chain control across European and North American markets. Roche Holding AG anchors its position through deep specialization in intravenous formulation science. AbbVie, Inc. competes aggressively in the subcutaneous delivery segment with differentiated injection device technologies.
Interleukin-6 inhibitors comprise monoclonal antibodies and fusion proteins engineered to block IL-6 receptor signaling or neutralize circulating IL-6 cytokine, typically manufactured through Chinese hamster ovary cell culture with subsequent protein A chromatography purification and endotoxin testing below 0.25 EU per milligram. These therapeutics serve primarily to interrupt inflammatory cascades in autoimmune pathologies and cytokine release syndromes. The tocilizumab product segment leads current revenue pools due to established rheumatoid arthritis labeling and hospital formulary placement, while the subcutaneous administration route captures the fastest expansion as homecare settings reduce infusion center burden. The COVID-19 therapy area segment has matured into a residual demand channel following pandemic authorization withdrawals.
The FDA maintains stringent lot-release testing requirements for IL-6 inhibitor biologics through its Center for Drug Evaluation and Research, while the EMA oversees comparability protocols for biosimilar entrants under its biosimilar guidance framework. Japan's PMDA imposes additional local clinical bridging study mandates that shape market access timelines for foreign developers. Stakeholders must monitor evolving biosimilar substitution policies across reimbursement authorities and decide on manufacturing capacity allocation between intravenous and subcutaneous formats before competitive pressure intensifies.
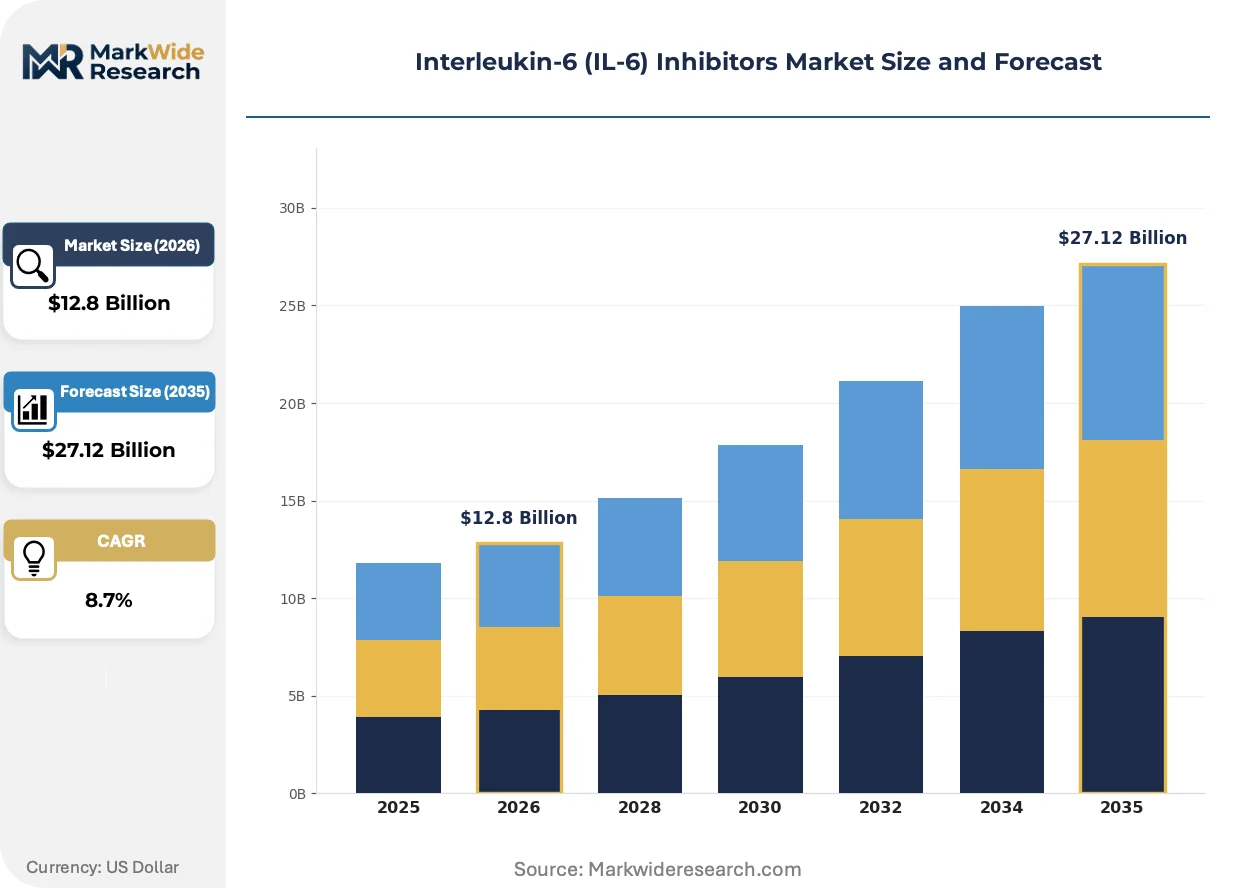
Market Dynamics
Single-use bioreactor adoption is fragmenting manufacturing capacity across contract development organizations, eroding the integrated facility advantage that historically anchored IL-6 inhibitor supply security.
Growth Catalysts
- Subcutaneous formulation engineering:Homecare administration protocols reduce infusion center burden and expand addressable patient populations beyond hospital-dependent intravenous regimens.
- EMA biosimilar guidance framework:Streamlined comparability protocols accelerate second-wave entrant timelines and compress development costs for follow-on monoclonal antibodies.
- Rheumatoid arthritis treatment protocols:Hospital system formulary placement in the United States, Germany, and Japan concentrates demand and secures revenue visibility for established intravenous products.
Market Restraints
- Protein A chromatography resin supply concentration:Three suppliers control critical purification media, exposing manufacturers to input cost volatility and allocation constraints during demand surges.
- PMDA local clinical bridging mandates:Japan's regulator imposes additional patient enrollment requirements that extend market access timelines by 18-24 months versus FDA or EMA pathways.
- Biosimilar substitution policy fragmentation:Reimbursement authorities in Germany, France, and the United Kingdom maintain divergent interchangeability standards that complicate forecasting and inventory planning.
Strategic Opportunities
- Cytokine release syndrome prophylaxis:CAR-T cell therapy expansion creates adjacent demand for IL-6 receptor blockade in oncology supportive care settings.
- Prefilled autoinjector device convergence:Combination product differentiation with electromechanical injection systems opens premium positioning in the subcutaneous delivery segment.
- Brazilian ANVISA accelerated pathway:Emerging market regulators are implementing priority review mechanisms for biologics addressing unmet autoimmune disease burden.
Industry Challenges
- Cell culture process analytical technology:Real-time quality attribute monitoring requires scarce talent in multivariate data modeling and spectroscopic method development.
- Endotoxin testing capacity:Lot-release bottlenecks at contract testing laboratories extend batch disposition timelines and compress working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interleukin-6 (IL-6) Inhibitors Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tocilizumab, Sarilumab, Siltuximab, Others Therapy Area: Rheumatoid Arthritis, Castleman Disease, COVID-19, Other Inflammatory Conditions End User: Hospitals, Clinics, Research Institutions, Homecare Settings Administration Route: Intravenous, Subcutaneous, Oral, Others |
| Companies Covered | Novartis AG, AbbVie, Inc., Roche Holding AG, GlaxoSmithKline Plc, Johnson & Johnson, Sanofi S.A., Pfizer Inc., Eli Lilly and Company, Regeneron Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interleukin-6 (IL-6) Inhibitors Market Shifts & Advancements
Continuous processing architectures are displacing traditional fed-batch paradigms, compressing manufacturing timelines and reshaping capital deployment patterns across the IL-6 inhibitor value chain.
Continuous perfusion bioreactor systems is hybridizing upstream cell culture operations with integrated online harvest capabilities. CDMOs in Switzerland and Singapore are adopting these platforms to reduce facility footprint requirements by sixty percent while maintaining comparable titers. The technology is hybridizing competitive positioning by enabling mid-scale players to challenge integrated pharmaceutical manufacturers on cost per gram without matching their capital intensity.
REACH regulation amendments on per- and polyfluoroalkyl substances are forcing reformulation of single-use bioprocess equipment coatings. European manufacturers must validate alternative materials for bioreactor liner films and tubing assemblies by 2027. The intravenous formulation segment faces the steepest compliance burden given its reliance on fluoropolymer-containing fluid contact surfaces in fill-finish operations.
Hospital procurement consortia are consolidating antibody purchasing decisions across integrated delivery networks in the United States and Germany. These entities now negotiate directly with manufacturers, bypassing traditional wholesale distribution channels and compressing price realization for established intravenous products. The shift is most visible in German sickness fund tendering, where annual volume commitments dominate supplier selection criteria.
Interleukin-6 (IL-6) Inhibitors Market Segmentation
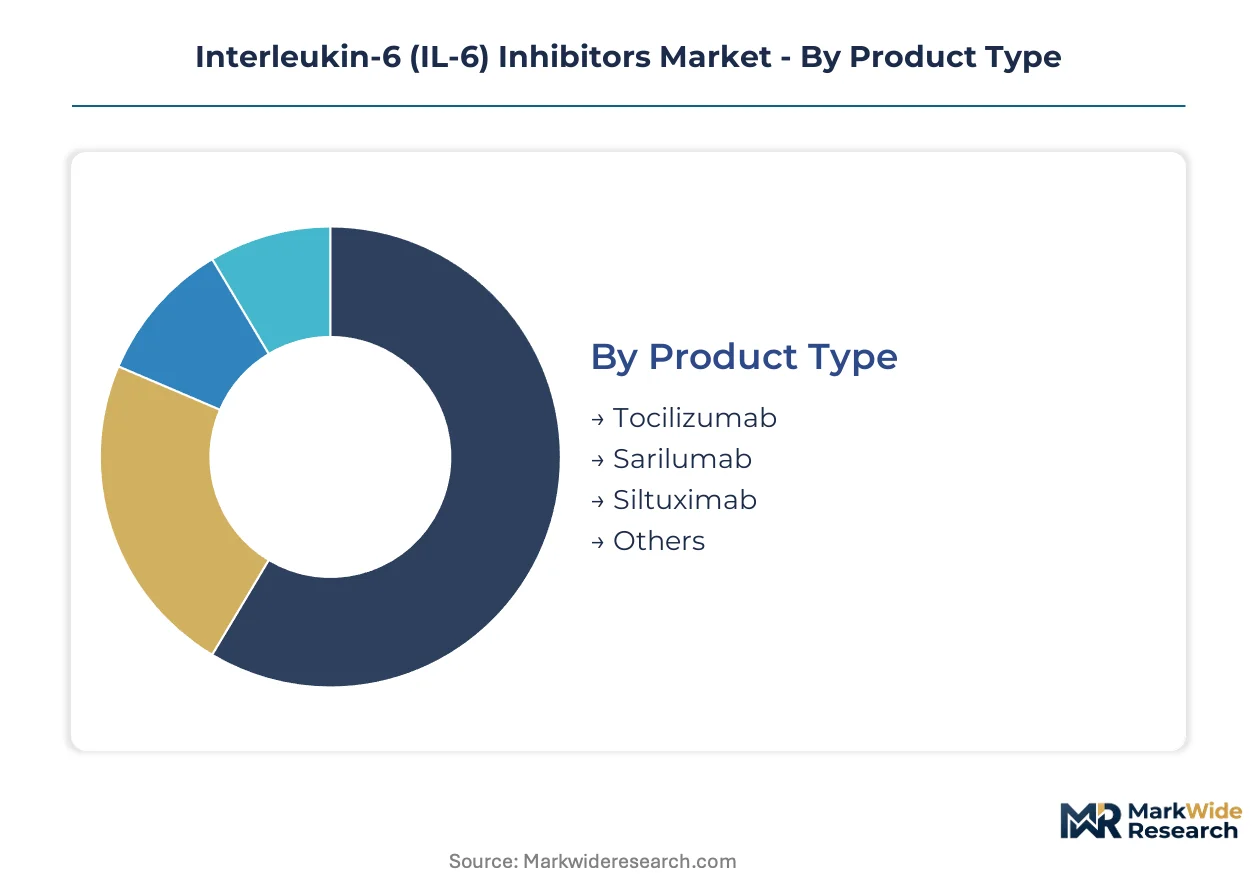
IL-6 inhibitor segmentation reveals divergent growth trajectories across administration routes and care settings. Product type concentration and therapy area maturation create distinct investment profiles for manufacturers navigating biosimilar entry timelines.
Product Type:
The use-case spectrum spans established rheumatology blockbusters to orphan disease monoclonal antibodies with contrasting commercial scale.
- Tocilizumab:Humanized monoclonal antibody targeting IL-6 receptor with dual intravenous and subcutaneous formulations. Hospital formulary placement in the United States, Germany, and Japan secures revenue visibility for rheumatoid arthritis protocols.
- Sarilumab:Fully human monoclonal antibody with subcutaneous-only delivery profile. Homecare administration protocols in North American markets drive fastest volume expansion outside infusion centers.
- Siltuximab:Chimeric monoclonal antibody approved for multicentric Castleman disease with limited patient population.
- Others:Investigational fusion proteins and biosimilar candidates in various development stages.
Established volume favors tocilizumab; emerging adoption favors sarilumab.
Therapy Area:
Cost tier stratification separates chronic autoimmune maintenance from acute intervention indications with divergent reimbursement durability.
- Rheumatoid Arthritis:Chronic autoimmune indication requiring lifelong therapy with established prior authorization pathways. German sickness fund tendering concentrates procurement decisions across integrated delivery networks.
- COVID-19:Emergency use authorization indication with residual demand following pandemic withdrawal. FDA and EMA label restrictions now limit use to cytokine release syndrome in hospitalized patients.
- Castleman Disease:Rare lymphoproliferative disorder with orphan drug exclusivity protecting siltuximab positioning.
- Other Inflammatory Conditions:Juvenile idiopathic arthritis, giant cell arteritis, and CAR-T prophylaxis expanding off-protocol utilization.
Chronic maintenance protocols dominate revenue stability; acute intervention segments face reimbursement compression.
End User:
Customer type fragmentation accelerates as administration shifts from hospital-based infusion to patient-managed delivery.
- Hospitals:Primary site for intravenous tocilizumab administration with pharmacy-controlled inventory and therapeutic drug monitoring capabilities.
- Homecare Settings:Subcutaneous self-administration expanding fastest as specialty pharmacies manage patient training and adherence programs.
- Clinics:Rheumatology practices handling injection training and subcutaneous product dispensing.
- Research Institutions:Clinical trial sites investigating expanded indications and biosimilar comparability protocols.
Institutional procurement favors hospitals; patient convenience favors homecare migration.
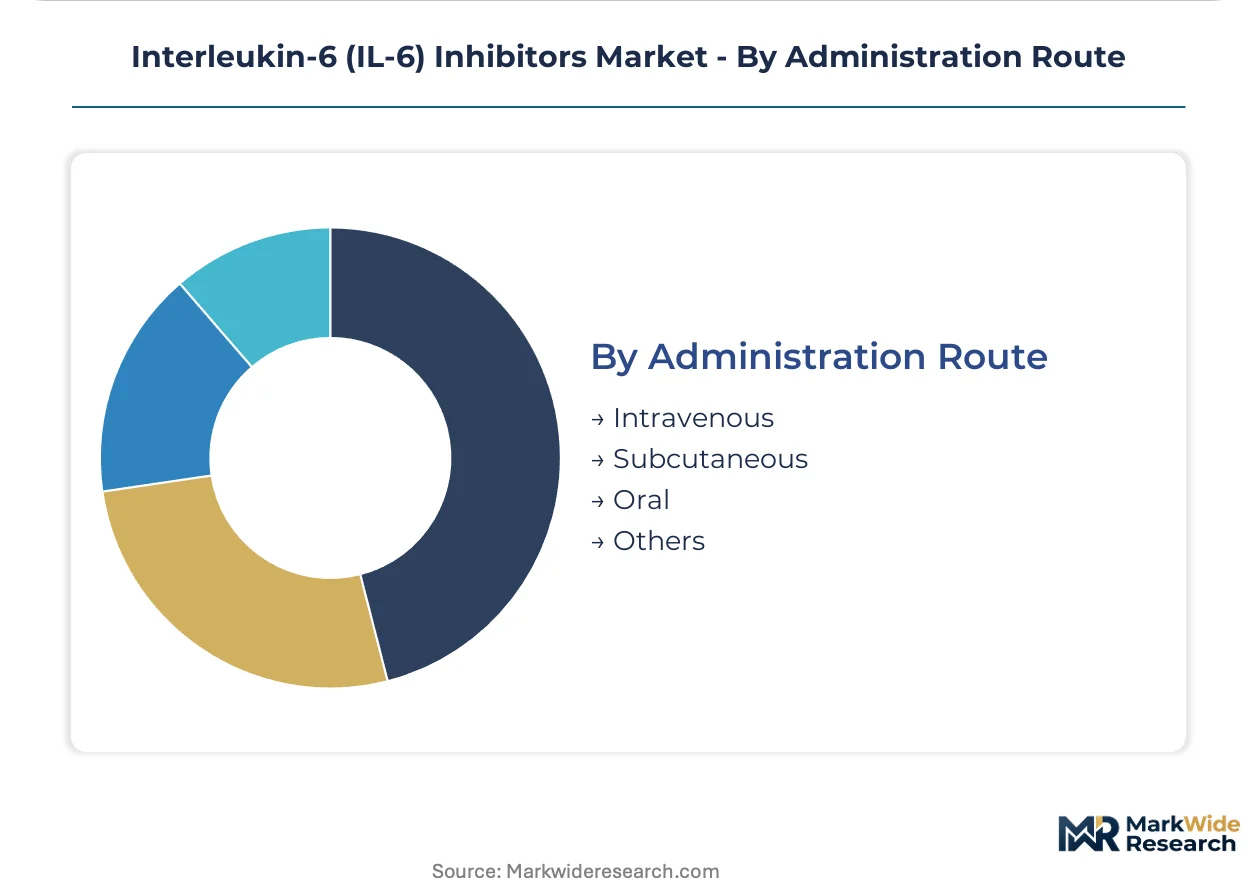
Administration Route:
Supply concentration in fill-finish capacity creates divergent manufacturing investment requirements across delivery formats.
- Intravenous:Lyophilized powder requiring reconstitution and infusion center infrastructure. Protein A chromatography resin allocation constraints concentrate production at integrated manufacturing networks.
- Subcutaneous:Prefilled syringe and autoinjector formats enabling patient self-administration. REACH regulation amendments on per- and polyfluoroalkyl substances force coating reformulation for European supply by 2027.
- Oral:Small molecule inhibitors in early development with distinct pharmacokinetic profiles from biologic therapies.
- Others:Investigational depot formulations and sustained-release injectables in preclinical stages.
Infusion infrastructure anchors current supply security; device-enabled delivery captures steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia concentrate demand across integrated delivery networks in the United States, Germany, and Japan, while contract development organizations expand single-use bioreactor capacity in Switzerland and Singapore to serve regional manufacturing needs.
United States
FDA lot-release testing requirements govern tocilizumab distribution through hospital pharmacy channels. The IRA price negotiation provisions reshape reimbursement timelines for rheumatoid arthritis biologics. Massachusetts and North Carolina biotech clusters anchor monoclonal antibody manufacturing capacity for domestic supply security.
Germany
Sickness fund tendering concentrates annual volume commitments across integrated delivery networks. EMA biosimilar guidance streamlines comparability protocols for follow-on entrants. Baden-Württemberg and Bavaria host contract manufacturing organizations scaling protein A chromatography purification for European supply.
Japan
PMDA local clinical bridging study mandates extend market access timelines by 18-24 months versus FDA pathways. METI industrial policy supports domestic biologics manufacturing infrastructure. Tokyo and Osaka metropolitan areas concentrate rheumatology practice networks driving intravenous tocilizumab utilization.
Switzerland
Swissmedic oversight aligns with EMA standards while permitting accelerated access pathways for orphan indications. REACH regulation amendments on per- and polyfluoroalkyl substances force single-use bioreactor coating reformulation by 2027. Basel and Zurich regions anchor continuous perfusion bioreactor adoption for contract manufacturing scale.
Brazil
ANVISA accelerated review mechanisms prioritize biologics addressing unmet autoimmune disease burden. Hospital formulary placement in São Paulo and Rio de Janeiro concentrates demand for imported intravenous formulations. Southeast region rheumatology centers drive off-protocol utilization for juvenile idiopathic arthritis expansion.
Interleukin-6 (IL-6) Inhibitors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented manufacturing tiers. Integrated pharmaceutical manufacturers anchor supply security through captive bioreactor networks. Contract development organizations capture share by scaling single-use capacity without matching capital intensity. Dominant competitive moves include strategic partnerships for fill-finish capacity allocation and geographic licensing for emerging market access.
Among Swiss-based integrated manufacturers, Novartis AG and Roche Holding AG exemplify channel-control archetypes through European and North American distribution networks. AbbVie, Inc. represents the subcutaneous delivery specialist tier with differentiated injection device positioning. These three entities anchor competitive positioning across intravenous formulation science and homecare administration segments.
| Leading Market Players |
|---|
| Novartis AG |
| AbbVie, Inc. |
| Roche Holding AG |
| GlaxoSmithKline Plc |
| Johnson & Johnson |
| Sanofi S.A. |
| Pfizer Inc. |
| Eli Lilly and Company |
| Regeneron Pharmaceuticals, Inc. |
| Others |
Supply & Pricing Matrix
Protein A chromatography resin production concentrates in three suppliers across the United States and Western Europe, anchoring margin capture upstream while hospital procurement consortia compress price realization downstream for intravenous tocilizumab formulations.
Pricing Analysis
Cost-plus contracts with protein A resin indexation govern biologics manufacturing agreements between CDMOs and pharmaceutical developers. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and lot-size scale, with intravenous lyophilized products commanding premium positioning over subcutaneous alternatives. Cost compression in standard-tier intravenous products is intensifying because German sickness fund tendering aggregates annual volume commitments across integrated delivery networks. Homecare settings demonstrate highest price sensitivity due to patient co-pay exposure, while hospital pharmacy procurement maintains lowest sensitivity given formulary lock-in and therapeutic drug monitoring requirements.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day payment terms have become standard for single-use bioreactor equipment procurement, stretching working capital across contract manufacturing networks. Manufacturing capacity concentrates in Switzerland, Singapore, and the United States for continuous perfusion bioreactor adoption. Upstream dependencies center on Chinese hamster ovary cell lines, protein A chromatography resins, and fluoropolymer-containing fluid contact surfaces for fill-finish operations. Single-source vulnerability in resin supply creates allocation risk during demand surges. Distribution runs through hospital pharmacy channels in developed markets and specialty pharmacy networks for subcutaneous homecare delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent in multivariate data modeling and spectroscopic method development remains scarce, constraining real-time quality attribute monitoring adoption and creating competitive differentiation for manufacturers with captive capability.
For Market Incumbents: Insulate intravenous formulation revenue through exclusive fill-finish capacity allocation at integrated manufacturing networks, while accelerating subcutaneous autoinjector platform development to capture homecare migration. Biosimilar substitution policy fragmentation across German, French, and United Kingdom reimbursement authorities threatens price realization for established products. Backward integration into protein A chromatography resin supply or long-term offtake agreements with resin suppliers secures input cost stability. For New Entrants and Emerging Players: Brazilian rheumatology centers in São Paulo and Rio de Janeiro represent underpenetrated demand for imported intravenous formulations, with ANVISA accelerated review mechanisms compressing regulatory timelines versus PMDA pathways. Juvenile idiopathic arthritis expansion offers white-space positioning outside established rheumatoid arthritis protocols. Partnership with Southeast Asian CDMOs scaling single-use bioreactor capacity enables manufacturing entry without matching integrated facility capital intensity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract development organizations possessing scaled single-use bioreactor networks but lacking integrated fill-finish capabilities. Long-term viability hinges on convergence toward continuous processing architectures and combination product differentiation. Watch for REACH regulation compliance deadlines forcing fluoropolymer coating reformulation as inflection indicator for European supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Perfusion Bioreactor Adoption | CDMOs in Switzerland reduce facility footprint sixty percent while matching integrated manufacturer titers. |
| Prefilled Autoinjector Device Convergence | Electromechanical injection systems differentiate subcutaneous delivery against standard prefilled syringe offerings. |
| EMA Biosimilar Comparability Investment | Streamlined protocols accelerate follow-on monoclonal antibody timelines and compress development costs. |
| Protein A Resin Supply Security | Long-term offtake agreements with resin suppliers mitigate allocation constraints during demand surges. |
| CAR-T Cytokine Release Syndrome Positioning | Oncology supportive care expansion creates adjacent demand for IL-6 receptor blockade prophylaxis. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation through FDA Center for Drug Evaluation and Research filings, EMA biosimilar guidance documentation, ClinicalTrials.gov protocol registries, and hospital formulary databases. Bottom-up patient population modeling triangulated against top-down manufacturer revenue attribution across administration routes and therapy areas.
Forecast inputs considered rheumatoid arthritis treatment protocol evolution, biosimilar entry timelines under EMA guidance, subcutaneous administration route adoption curves, and continuous processing technology penetration rates. Segmentation dimensions modeled included product type, therapy area, administration route, end user setting, and regional regulatory cluster. CAGRs derived from iterative convergence between epidemiological prevalence projections and pricing trajectory assumptions.
Practitioners should monitor biosimilar substitution policy shifts, protein A chromatography resin supply allocation, and REACH regulation compliance deadlines for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Protein Therapeutics Market