
 Wall Putty Powder Market | 2026-2036
Wall Putty Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Putty Powder Market Insights
Property developers is reorganizing procurement patterns around large-format ready-mix deliveries for high-rise residential towers. J.K. Cement Ltd anchors supply through backward integration into white cement kilns across Rajasthan and Madhya Pradesh. Birla White dominates brand recognition among independent contractors through specialized distribution networks in tier-2 and tier-3 cities. Saint-Gobain Weber navigates premium positioning by leveraging polymer-modified technology leadership in commercial building segments.
Wall putty powder comprises a blend of white cement, polymers, fillers, and additives designed to create smooth, absorbent substrates for paint adhesion, typically applied at 1-2 mm thickness over plastered surfaces. The manufacturing process involves controlled grinding of limestone clinker with micronized mineral extenders and redispersible polymer powders to achieve specified particle size distribution and binding strength. Ready mix formulations lead volume in urban markets where labor shortages favor pre-blended consistency, while polymer modified grades capture expanding margin pools in moisture-prone commercial applications. White cement based variants sustain dominance across infrastructure projects where alkaline compatibility with Portland cement plaster remains non-negotiable.
Bureau of Indian Standards certification governs product quality thresholds and packaging integrity for domestic manufacturers, while state-level real estate regulatory authorities in Maharashtra and Karnataka mandate material disclosure in project specifications. The EU Green Deal's embodied carbon tracking requirements are reshaping export qualification protocols for Indian and Chinese producers supplying decorative finishes to European property developers. Stakeholders must monitor evolving volatile organic compound limits under REACH and state pollution control mandates to preempt formulation reformulation cycles.
Market Dynamics
Polymer-modified formulation technology is compressing the performance gap between economy-grade and premium wall putty products, forcing incumbent white cement manufacturers to defend margin pools through backward integration into specialty additive production. This structural shift is reshaping procurement relationships between property developers and material suppliers across high-rise construction corridors.
Growth Catalysts
- Green building code enforcement:Bureau of Indian Standards certification mandates under stricter environmental compliance protocols are accelerating specification upgrades in commercial tower projects. Developers face binding disclosure requirements that favor certified polymer-modified grades.
- Limestone reserve proximity:Captive mineral access in Gujarat and Maharashtra manufacturing clusters is anchoring regional production scale and reducing inbound logistics costs for white cement-based formulations.
- Ready-mix labor substitution:Urban labor shortages in tier-1 construction markets are pulling demand toward pre-blended consistency products that eliminate on-site mixing variability and reduce skilled mason dependency.
Market Restraints
- White cement input cost volatility:Energy-intensive kiln operations and petcoke price swings transmit directly to putty manufacturing economics, compressing margins for non-integrated producers.
- Regional supply concentration:Rajasthan and Madhya Pradesh white cement capacity dominance creates geographic vulnerability to monsoon logistics disruptions and state-level freight policy changes.
- Acrylic emulsion substitution threat:Direct-to-plaster paint primers in moisture-controlled interior applications are capturing specification share from traditional skim-coat putty layers.
Strategic Opportunities
- Export qualification alignment:EU Green Deal embodied carbon tracking protocols are creating premium pricing tiers for Indian producers who achieve REACH-compliant volatile organic compound thresholds.
- Tier-2 distribution penetration:Specialized contractor networks in smaller cities remain underserved by polymer-modified product availability, offering first-mover positioning for technical-grade formulations.
- Redispersible powder convergence:Hybrid formulations combining vinyl acetate-ethylene copolymers with micronized calcium carbonate extenders are opening specification pathways in swimming pool and basement waterproofing segments.
Industry Challenges
- Skilled applicator scarcity:Proper surface preparation and thickness control for 1-2 mm skim coats requires trained masons, yet vocational certification programs for decorative finishes remain underdeveloped in secondary cities.
- Reformulation cycle compression:Evolving state pollution control mandates and volatile organic compound limits are forcing shorter product development timelines that strain R&D bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Putty Powder Market |
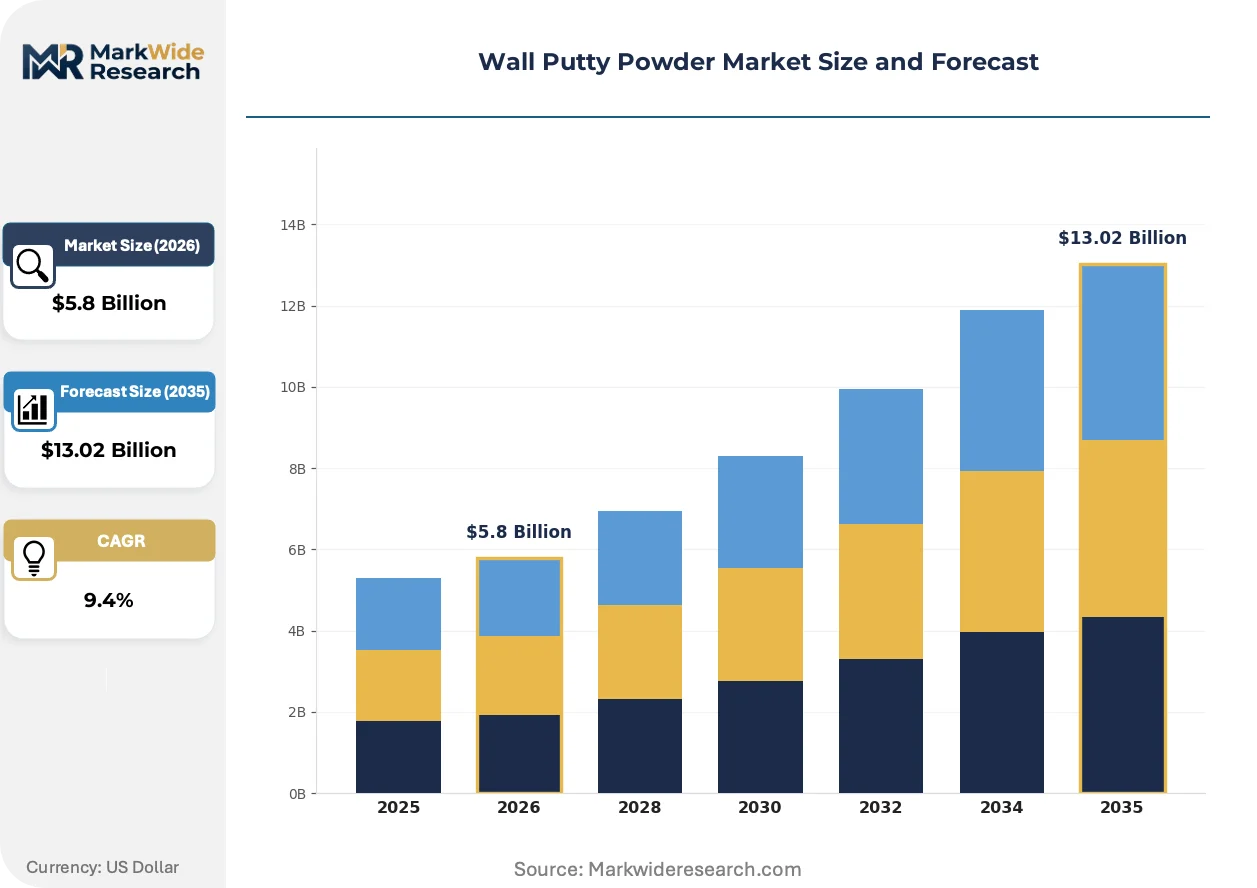
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready Mix, Powder Form, Acrylic Based, White Cement Based, Polymer Modified Application: Residential Construction, Commercial Building, Infrastructure Projects, Renovation Works, Decorative Finishes End User: Construction Companies, Independent Contractors, Interior Designers, Property Developers, Government Agencies Packaging Type: Paper Bags, Plastic Bags, Bulk Sacks, Pouches, 25 Kg Bags |
| Companies Covered | Asian Paints, J.K. Cement Ltd, Walplast, Meichao, Birla White, Nippon Paint, Mapei, Saint-Gobain Weber, Platinum Plaster Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Putty Powder Market Trends and Innovations
Formulation chemistry and procurement logistics are undergoing simultaneous transformation as environmental compliance tightens and construction labor models shift. These intersecting pressures are accelerating product segmentation and channel restructuring across the value chain.
Redispersible polymer powder technology is bifurcating the market between commodity white cement putty and high-performance modified grades. Commercial developers in moisture-prone building segments are specifying vinyl acetate-ethylene and acrylic-based additives at accelerating rates. This technology diffusion is compressing price premiums for mid-tier products while expanding margin pools at the specification-grade extreme.
REACH volatile organic compound limits and EU Green Deal carbon disclosure requirements are reshaping export qualification protocols for Asian producers. Indian manufacturers supplying European property developers must now document embodied emissions across limestone extraction, clinker calcination, and polymer additive synthesis. White cement-based variants face the steepest compliance burden due to energy-intensive kiln processes.
Large-format ready-mix deliveries are displacing bagged product procurement in high-rise residential towers. Property developers in Maharashtra and Karnataka are consolidating purchase volumes through direct manufacturer relationships that bypass traditional distributor networks. This channel consolidation is most visible in Mumbai and Bengaluru construction corridors where labor shortages favor pre-blended consistency guarantees.
Wall Putty Powder Market Segmentation
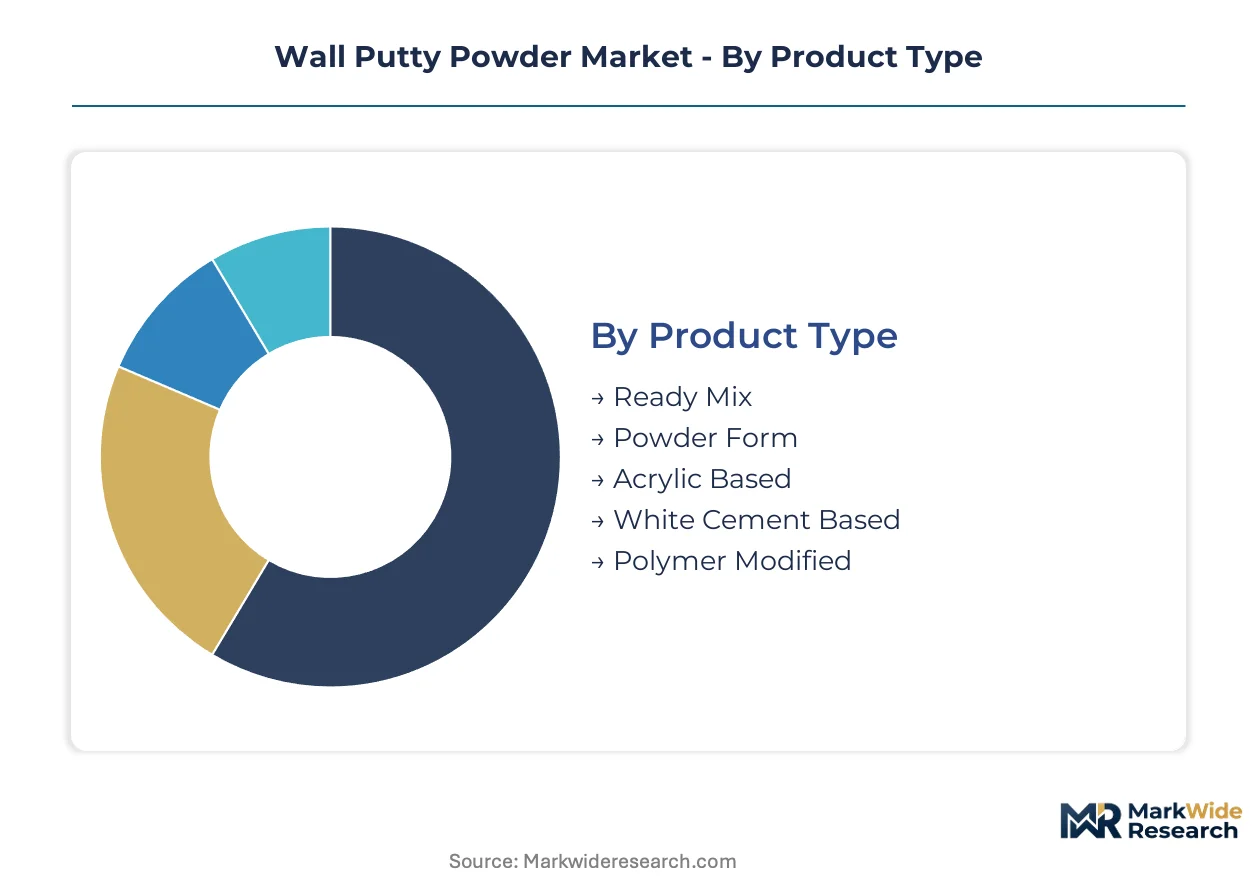
Wall putty powder segmentation reveals how formulation chemistry, application environment, and procurement channel intersect to create distinct margin architectures. Manufacturers configure product lines around performance tier, end-use durability requirements, and logistics format to capture value across construction market strata.
Product Type:
Margin pools concentrate in polymer-modified and white cement-based formulations where technical differentiation commands specification premiums.
- Polymer Modified:Vinyl acetate-ethylene and acrylic redispersible powders blended with micronized mineral extenders deliver enhanced adhesion and water resistance. Demand concentrates in Maharashtra and Karnataka commercial towers where Bureau of Indian Standards green building disclosure mandates favor certified grades. Labor shortages in Mumbai construction corridors accelerate specification of pre-blended consistency products.
- White Cement Based:Controlled grinding of limestone clinker with calcium carbonate fillers produces alkaline-compatible substrates for Portland cement plaster systems. Gujarat and Rajasthan manufacturing clusters anchor supply through captive limestone reserves, serving infrastructure projects where compatibility remains non-negotiable.
- Ready Mix:Pre-blended formulations eliminate on-site mixing variability for urban high-rise applications.
- Powder Form:Traditional bagged product retains volume in secondary cities with established mason networks.
- Acrylic Based:Direct-to-plaster primer alternatives capture share in moisture-controlled interior specifications.
White cement-based holds installed capacity. Polymer modified is rotating up the share rankings.
Application:
Commercial building and infrastructure projects concentrate procurement volumes through direct manufacturer relationships that bypass distributor markups.
- Commercial Building:Moisture-prone facades and basement specifications drive polymer-modified adoption with vinyl acetate-ethylene copolymer formulations. Mumbai and Bengaluru developers consolidate large-format ready-mix purchases through backward-integrated suppliers.
- Infrastructure Projects:Bridge soffits, tunnel linings, and public building substrates demand white cement-based alkaline compatibility with structural concrete. Rajasthan and Madhya Pradesh kiln proximity reduces inbound logistics costs for these volume contracts.
- Residential Construction:Tier-1 urban towers favor ready-mix consistency guarantees amid skilled mason scarcity.
- Renovation Works:Existing substrate repair applications sustain demand for powder-form flexibility in thickness control.
- Decorative Finishes:Premium interior specifications absorb acrylic and hybrid formulations for aesthetic surface quality.
Infrastructure projects anchor volume commitments. Commercial building is climbing the fastest as green code enforcement tightens.
End User:
Property developers and construction companies concentrate purchasing power through consolidated procurement of certified formulations.
- Property Developers:Maharashtra and Karnataka regulatory authorities mandate material disclosure in project specifications, pulling procurement toward Bureau of Indian Standards-certified polymer-modified grades. Direct manufacturer relationships secure volume pricing and consistency guarantees for high-rise portfolios.
- Construction Companies:Labor subcontracting models in tier-1 cities drive ready-mix specification to reduce on-site mixing variability and skilled mason dependency. Backward-integrated white cement producers anchor supply contracts through captive kiln capacity.
- Independent Contractors:Tier-2 and tier-3 city networks sustain powder-form demand through established distribution channels.
- Interior Designers:Decorative finish specifications influence premium-grade selection for aesthetic outcomes.
- Government Agencies:Public infrastructure tenders prioritize white cement-based compatibility with structural concrete systems.
Construction companies hold installed capacity. Property developers are gaining share fastest through regulatory-driven specification upgrades.
Packaging Type:
Bulk sacks and 25 kg bags concentrate margin capture at opposite ends of the logistics efficiency spectrum.
- Bulk Sacks:One-tonne flexible intermediate bulk containers serve high-rise tower projects with dedicated material hoists and on-site silo storage. Mumbai and Bengaluru developers specify bulk delivery to eliminate bag handling labor and reduce packaging waste disposal costs.
- 25 Kg Bags:Standard unitized packaging retains dominance in tier-2 contractor networks where purchase quantities fragment across multiple small projects. Established distribution infrastructure minimizes switching costs for this channel.
- Paper Bags:Recyclable packaging aligns with green building certification point systems in commercial specifications.
- Plastic Bags:Moisture barrier properties serve humid climate storage requirements in coastal construction markets.
- Pouches:Small-format retail packaging addresses touch-up and repair demand from homeowner direct purchases.
25 kg bags hold installed capacity. Bulk sacks are rotating up the share rankings as urban high-rise construction concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Ahmedabad Dedicated Freight Corridor underwrites India's dominance in wall putty powder manufacturing, anchoring limestone supply chains from Rajasthan kilns to Gujarat processing clusters. This rail infrastructure enables bulk raw material flows that sustain regional cost advantages.
India
Maharashtra and Karnataka property developers scale polymer-modified purchases to meet Bureau of Indian Standards green building disclosure mandates. The BIS certification protocol governs packaging integrity and volatile organic compound thresholds for domestic manufacturers. Mumbai and Bengaluru construction corridors concentrate large-format ready-mix procurement through direct manufacturer relationships.
China
Guangdong and Jiangsu province developers drive specification upgrades for moisture-resistant commercial facades. The Ministry of Ecology and Environment enforces dual carbon goals that reshape clinker calcination economics for white cement-based formulations. The Yangtze River Delta manufacturing belt anchors export-oriented production serving Southeast Asian infrastructure projects.
Germany
Commercial renovation contractors in North Rhine-Westphalia specify low-embodied-carbon skim coats for office tower retrofits. The EU Green Deal's carbon border adjustment mechanism pressures import qualification protocols for Asian producers. The Rhine-Ruhr industrial corridor concentrates specialty additive synthesis for redispersible polymer powders.
United States
Texas and Florida residential developers absorb ready-mix volumes for high-rise coastal construction amid skilled labor constraints. The EPA regulates volatile organic compound emissions from architectural coatings that intersect with putty primer systems. The Houston-Gulf Coast petrochemical complex supplies vinyl acetate-ethylene copolymer feedstocks for modified formulations.
Saudi Arabia
NEOM and Riyadh gigaproject contractors specify white cement-based compatibility for structural concrete systems in desert climates. The Saudi Standards, Metrology and Quality Organization mandates product quality disclosure for imported construction chemicals. The Eastern Province industrial cities anchor captive limestone grinding capacity for regional infrastructure pipelines.
Wall Putty Powder Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology tiers, creating a bifurcated structure where scale-driven cement producers and polymer-technology specialists occupy distinct margin pools. The market stratifies around backward-integrated white cement manufacturers, regional ready-mix distributors, and specialty additive technology licensors. Two dominant competitive moves define positioning: captive kiln capacity expansion in limestone-rich geographies and polymer-modified formulation partnerships with commercial developers seeking green building certification.
Among India-based integrated producers, J.K. Cement Ltd and Birla White exemplify the backward-integrated archetype, anchoring supply through captive white cement kilns across Rajasthan and Madhya Pradesh. Saint-Gobain Weber occupies a position on the premium technology vector, representing polymer-modified specialists targeting commercial building segments with vinyl acetate-ethylene formulation expertise. These three companies illustrate how geographic integration and technology specialization create divergent competitive positions within the same end-use markets.
| Leading Market Players |
|---|
| Asian Paints |
| J.K. Cement Ltd |
| Walplast |
| Meichao |
| Birla White |
| Nippon Paint |
| Mapei |
| Saint-Gobain Weber |
| Platinum Plaster Ltd |
| Others |
Pricing and Supply Chain Analysis
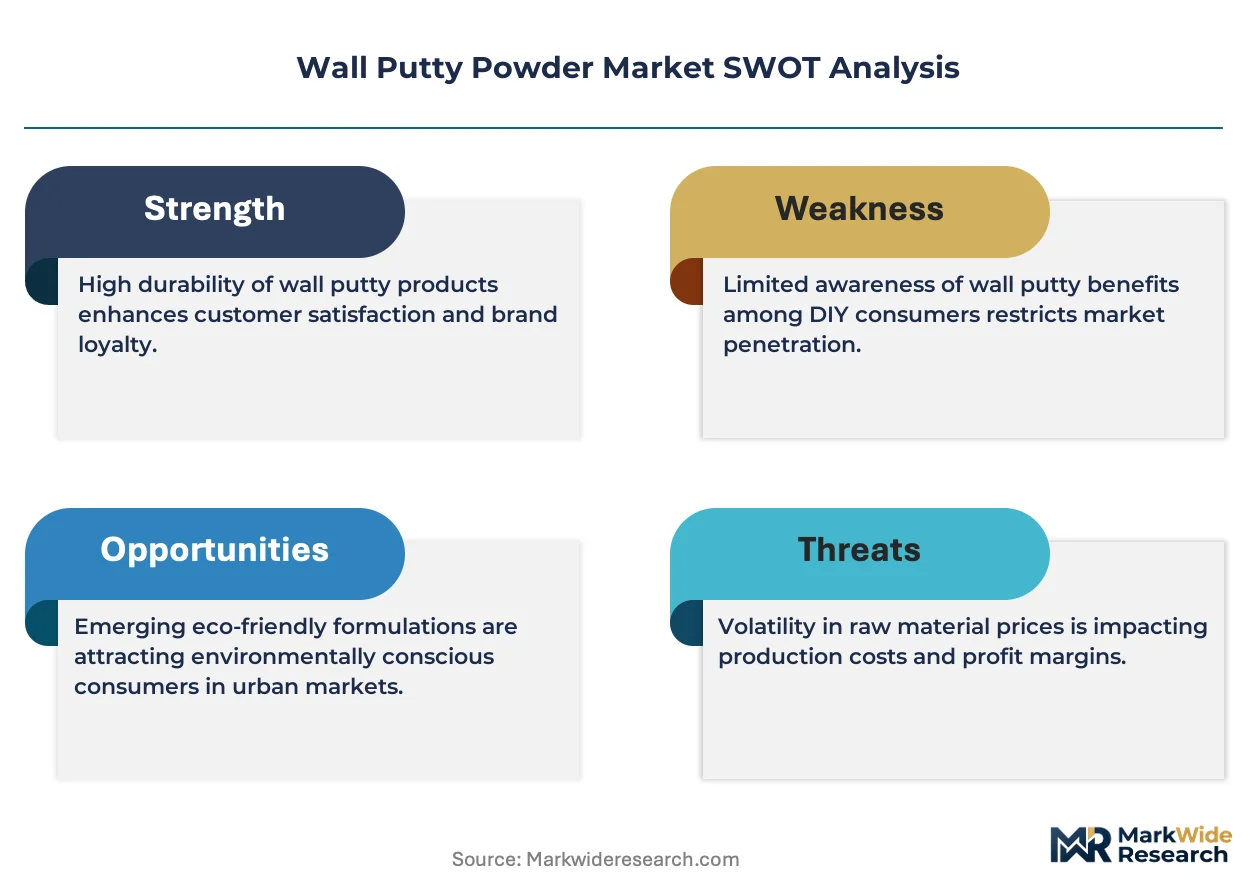
Long-term offtake agreements between Maharashtra property developers and Rajasthan kiln operators lock in both white cement supply access and eighteen-month price visibility against petcoke volatility. These contracts insulate integrated manufacturers from spot market swings while binding buyers to volume commitments that sustain plant utilization rates.
Pricing Analysis
Volume-discount tiering structures separate polymer-modified premium grades from standard white cement-based formulations and economy powder alternatives. Price differentiation hinges on Bureau of Indian Standards certification level and bulk delivery scale, with certified grades commanding substantial premiums in green building mandates. Cost compression in economy tiers is intensifying because acrylic emulsion primers erode skim-coat specifications in moisture-controlled interiors. Independent contractors in tier-2 cities exhibit highest price sensitivity, while commercial developers in Mumbai and Bengaluru prioritize consistency guarantees over per-kilogram economics.
Supply Chain Analysis
India and China anchor global wall putty powder production through captive limestone grinding clusters in Rajasthan and Guangdong provinces. Manufacturing draws from white cement clinker, redispersible polymer powders, and micronized calcium carbonate fillers as primary inputs. Single-source vulnerability concentrates in Rajasthan kiln capacity, where monsoon logistics disruptions can sever supply to western Indian construction corridors. Distribution runs through project-direct bulk deliveries for high-rise towers and established dealer networks for tier-2 contractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through Bureau of Indian Standards certification creates durable barriers against unqualified competitors.
For Market Incumbents: Secure captive limestone reserves in Gujarat and Maharashtra to defend margin pools against energy cost volatility, while accelerating polymer-modified formulation R&D to counter acrylic emulsion substitution threats. Backward integration into redispersible powder synthesis represents the critical lever for premium tier defense. For New Entrants and Emerging Players: Anchor in tier-2 city distribution gaps where polymer-modified availability remains sparse and contractor networks lack technical support infrastructure. Swimming pool and basement waterproofing segments offer the most penetrable white-space targets, with hybrid vinyl acetate-ethylene formulations as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Regional ready-mix specialists with established bulk logistics capabilities present the most compelling acquisition target archetype for portfolio exposure to urban high-rise construction concentration. Monitor Bureau of Indian Standards enforcement intensity across state real estate regulatory authorities as the inflection signal for specification upgrade velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Production | Captive redispersible polymer synthesis secures margin capture in premium grades against raw material volatility. |
| Bulk Logistics Infrastructure Expansion | Flexible intermediate bulk container handling capacity unlocks direct relationships with Mumbai and Bengaluru developers. |
| Green Certification Program Investment | EU Green Deal REACH compliance opens export qualification pathways to European property developers. |
| Tier-2 Distribution Network Penetration | Specialized contractor relationships in underserved cities capture first-mover positioning in technical-grade formulations. |
| Hybrid Formulation Development | Vinyl acetate-ethylene copolymer convergence with calcium carbonate extenders targets waterproofing specification expansion. |
Research Methodology
A spread of perspectives from white cement plant managers, property development procurement leads, distribution channel partners, and technical R&D directors converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from Bureau of Indian Standards filings, customs trade data, state pollution control board records, and SEC disclosures from listed building materials producers. Bottom-up project pipeline assessments and top-down construction sector macro indicators were triangulated to establish volume foundations.
Segmentation dimensions modeled include formulation chemistry tier, application environment durability requirements, procurement channel format, and regional regulatory cluster intensity across the projection horizon. CAGRs were derived from regression analysis against historical construction completion data and policy implementation timelines. Forecast inputs incorporated limestone reserve depletion curves and skilled mason availability indices as industry-specific demand modifiers.
Material uncertainties — regulatory enforcement variance across Indian states, petcoke price volatility, and acrylic primer technology diffusion rates — sit outside the modeled envelope. Forecasts reflect assumptions about continued Bureau of Indian Standards mandate expansion and stable clinker calcination economics. Recalibration cycles align with material shifts in green building code adoption velocity and export qualification protocol changes under EU carbon border mechanisms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market