
 Iran Paints and Coatings Market | 2026-2036
Iran Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Paints and Coatings Market Foresight
Color-matching software and digital tinting services is pivoting how Iranian distributors and applicators specify coatings, shifting value from bulk pigment sales to precision formulation support. Peka Chemie leverages its domestic manufacturing footprint to sustain supply continuity despite import constraints. Jotun anchors premium marine and protective coatings through specialized distribution in southern port zones. Rangsazi Iran Company competes on breadth, occupying multiple price tiers across architectural and industrial lines.
Paints and coatings are liquid, powder, or UV-curable film-forming materials applied to substrates for protection, decoration, or functional performance, typically comprising binders, pigments, solvents or water carriers, and additives that cure through oxidation, coalescence, or radiation crosslinking. Their primary purpose spans corrosion prevention, aesthetic enhancement, and surface durability across constructed assets and manufactured goods. Water-based technology leads volume in residential applications where indoor air quality concerns and regulatory pressure converge, while powder coatings extend fastest in manufacturing sector and OEM channels seeking zero-VOC, high-transfer-efficiency finishes. Solvent-based systems retain structural share in marine and aerospace applications where extreme chemical resistance and film integrity remain non-negotiable.
Iran's national standards body sets mandatory VOC content ceilings and product labeling requirements that directly determine which formulations gain market access, while the country's environmental regulator enforces industrial emissions protocols affecting coating application facilities. Construction sector participants must navigate building material certification tied to fire resistance and indoor air safety standards. Stakeholders should monitor how domestic resin supply constraints and standards evolution interact to reshape competitive advantage between local compounders and import-dependent distributors.
Market Dynamics
Iran's national standards body is tightening VOC ceilings faster than domestic resin capacity can reformulate, forcing compounders to choose between import dependency or accelerated water-based R&D investment.
Growth Catalysts
- Tehran-Isfahan Infrastructure Corridor:Rehabilitation of aging public buildings and transport nodes is pulling architectural coatings through state-backed procurement channels.
- Water-Based Formulation Mandates:Iran's national standards body is lowering permissible solvent content in interior architectural products, redirecting technical investment toward emulsion polymerization capabilities.
- Marine Protective Demand:Southern port expansion at Bandar Abbas and Chabahar is generating specification-grade corrosion protection requirements for offshore structures and vessel maintenance.
Market Restraints
- Petrochemical Feedstock Volatility:Domestic alkyd and epoxy resin supply fluctuates with refinery output allocation, compressing margin predictability for mid-tier compounders.
- Import Licensing Friction:Specialty additives and titanium dioxide pigment channels face extended customs clearance timelines, elongating working capital cycles for distributors.
- High-Performance Solvent Retention:Aerospace and marine specifications still require aromatic solvent carriers that conflict with indoor air quality standards, creating formulation bifurcation costs.
Strategic Opportunities
- Kurdistan and Azerbaijan Province Construction:Underpenetrated residential development outside Tehran-Isfahan axis offers volume expansion for regionally distributed production assets.
- Powder Coating OEM Integration:Appliance and automotive component manufacturers are adopting zero-VOC electrostatic application lines, opening captive supply relationships.
- Digital Tinting Infrastructure:Color-matching software deployment through distributor networks enables precision formulation services that differentiate against bulk commodity sellers.
Industry Challenges
- Formulation Chemist Scarcity:Water-based polymer science expertise remains concentrated in Tehran, constraining technical service reach to provincial manufacturing zones.
- Dual Certification Burden:Products serving both export-adjacent free zones and domestic markets must satisfy divergent testing protocols, doubling compliance documentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Paints and Coatings Market |
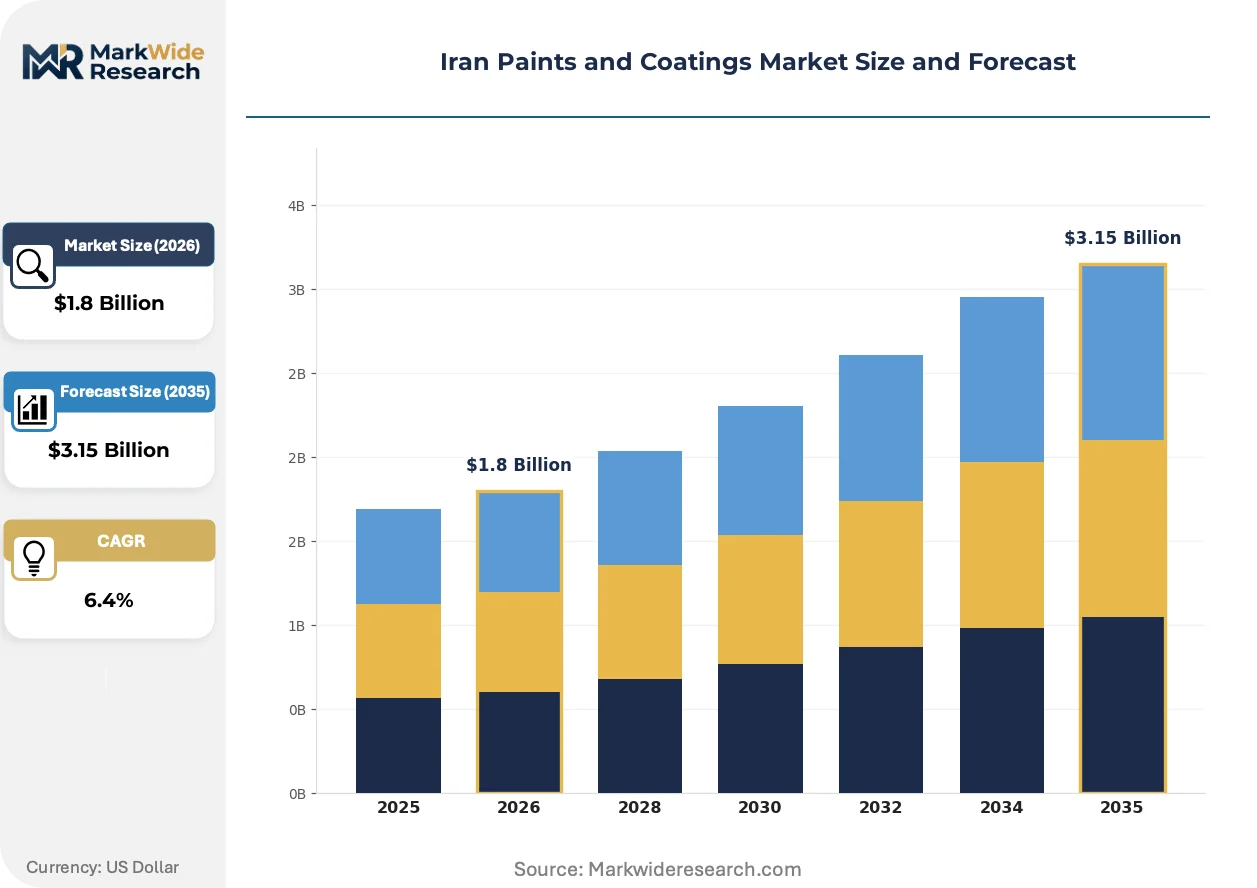
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Paints, Industrial Coatings, Specialty Coatings, Decorative Finishes Application: Construction, Automotive, Aerospace, Marine Technology: Water-Based, Solvent-Based, Powder Coatings, UV-Cured Coatings End User: Residential Sector, Commercial Sector, Manufacturing Sector, OEMs |
| Companies Covered | Peka Chemie, Ronass Chemical Producing Co., Jotun, Nippon Paint, Saba Shimi Arya, Alvan Paint Co., Rangsazi Iran Company, Ranguin Co., Pars Pamchal Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Paints and Coatings Market Shifts & Advancements
Reformulation pressure from Iran's environmental regulator is intersecting with digital distribution tools to compress traditional specification hierarchies and accelerate product lifecycle turnover.
Nano-scale functional additives is converging with conventional architectural binders to deliver self-cleaning and anti-microbial surface properties. Tehran-based hospital and food-processing facility specifiers are piloting these systems in high-traffic interior zones. The technology is converging with standard emulsion platforms to create premium tier differentiation without full resin system replacement.
Iran's national standards body is implementing phased VOC content ceilings with mandatory product labeling disclosure. Industrial coating application facilities must now document emissions control equipment compliance during facility inspection cycles. Marine and protective segments face the steepest reformulation timelines given solvent-dependent performance baselines.
Specification authority is migrating from bulk distributors to certified applicator networks equipped with digital color-matching hardware. Tehran Province residential developers increasingly contract directly with tinting-capable painting contractors, disintermediating traditional merchant wholesale channels. This pattern concentrates in high-rise commercial projects where shade consistency across phased construction is non-negotiable.
Iran Paints and Coatings Market Segmentation
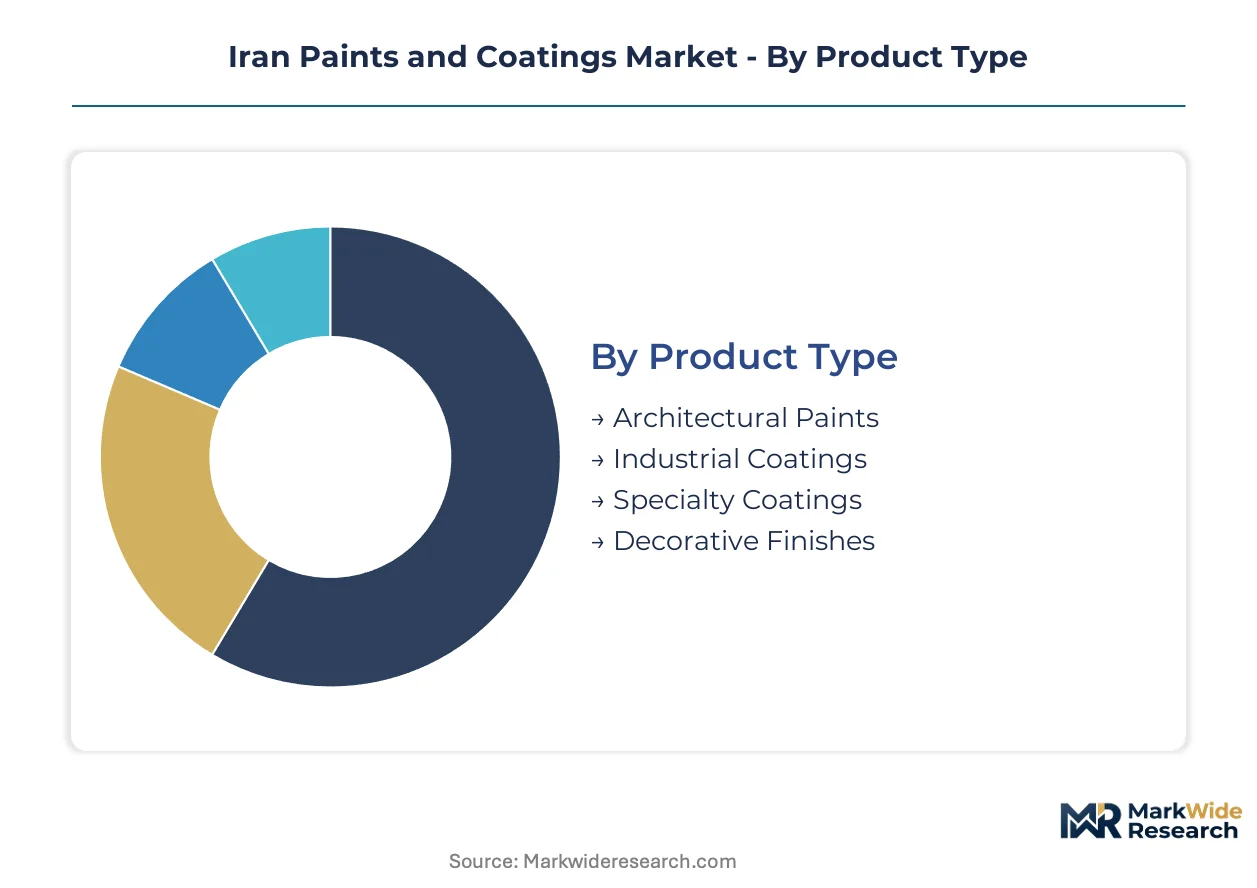
Segmentation in the Iranian coatings market reveals how regulatory pressure and infrastructure spending reshape procurement patterns across distinct buyer categories. Each dimension exposes different vulnerability to import constraints, VOC compliance costs, and regional demand concentration.
Product Type:
Buyers prioritize performance specifications against reformulation timelines when selecting product categories.
- Architectural Paints:Emulsion-based interior and exterior finishes dominate residential rehabilitation in Tehran Province. State-backed procurement for public building renovation pulls volume through certified contractor networks.
- Industrial Coatings:Epoxy and polyurethane systems protect manufacturing equipment and infrastructure assets. Petrochemical feedstock volatility compresses margin predictability for compounders serving Isfahan's steel and automotive supplier base.
- Specialty Coatings:High-performance formulations for extreme chemical or thermal environments.
- Decorative Finishes:Textured and faux-finish products for aesthetic differentiation in premium residential developments.
Volume sits with architectural paints; growth tilts toward industrial coatings.
Application:
Project scale and specification authority determine channel structure across end-use environments.
- Construction:Film-forming materials applied to structural substrates across building envelopes and interior surfaces. Tehran-Isfahan corridor infrastructure rehabilitation accelerates specification-grade procurement through state contracting channels.
- Automotive:OEM and refinish coatings for vehicle assembly and aftermarket repair. Domestic assembly plant expansion in central provinces drives electrocoat and clearcoat specification.
- Aerospace:High-altitude exposure systems requiring aromatic solvent carriers that conflict with evolving VOC ceilings.
- Marine:Corrosion protection for offshore structures and vessel maintenance at Bandar Abbas and Chabahar port zones.
Construction commands current volume; marine applications face the steepest reformulation timeline.
Technology:
Carrier chemistry selection now hinges on Iran's national standards body enforcement timelines rather than pure performance optimization.
- Water-Based:Emulsion polymer systems using water carriers and coalescing agents. Residential indoor air quality concerns and mandatory VOC labeling accelerate specification in Tehran Province high-rise developments.
- Solvent-Based:Alkyd and epoxy formulations relying on organic solvent carriers. Marine and aerospace specifications retain structural share where extreme chemical resistance remains non-negotiable.
- Powder Coatings:Zero-VOC thermoset powders applied electrostatically to metal substrates. Appliance and automotive component manufacturers adopt captive application lines for transfer efficiency.
- UV-Cured Coatings:Rapid-curing systems for specialized industrial finishing where line speed outweighs capital equipment cost.
Water-based systems absorb regulatory-driven switching; powder coatings gain share fastest in manufacturing integration.
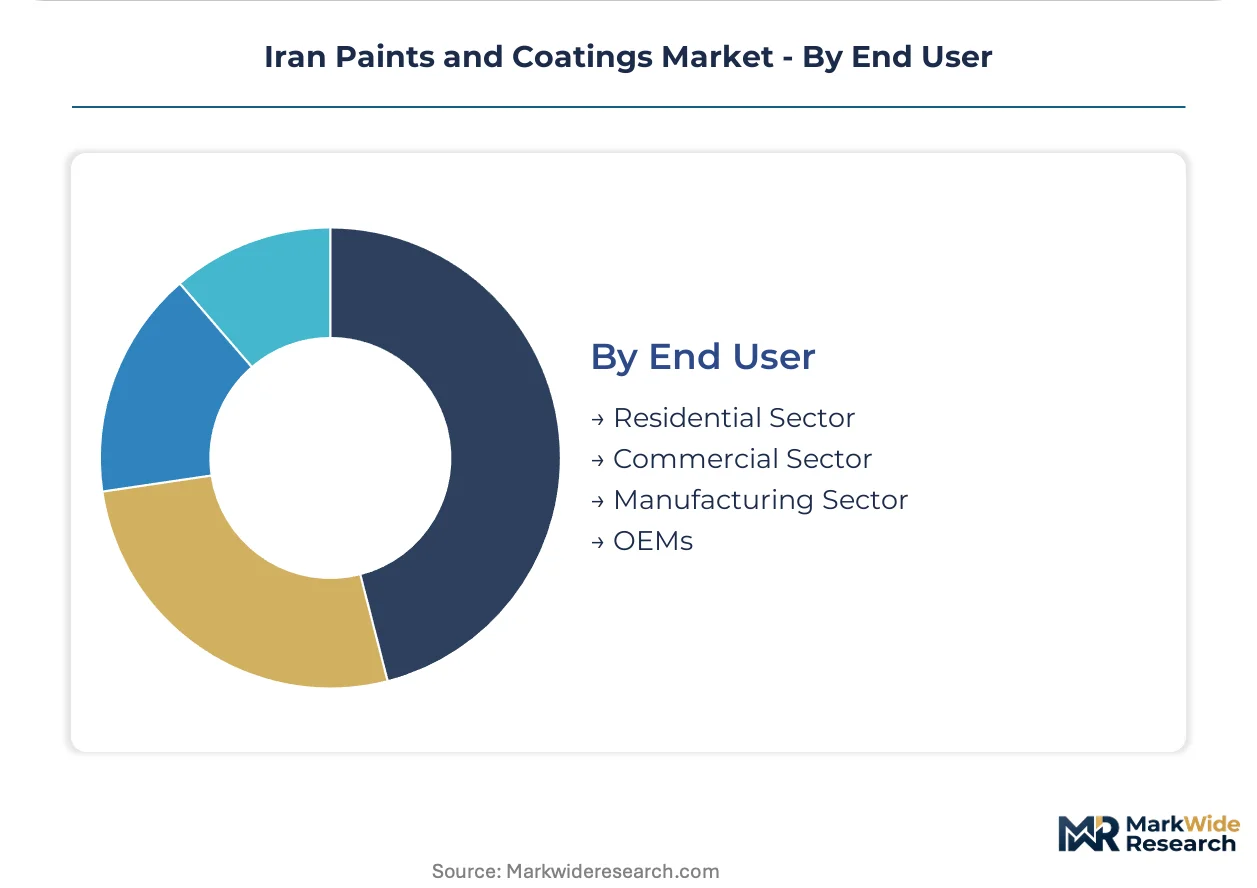
End User:
Procurement sophistication and specification authority separate volume buyers from premium segment capture.
- Residential Sector:Individual homeowners and small-scale developers selecting decorative and protective finishes. Tehran Province concentration drives distributor network density and digital tinting service deployment.
- Commercial Sector:Corporate and institutional developers with phased construction requirements. Shade consistency mandates across high-rise projects disintermediate traditional wholesale channels.
- Manufacturing Sector:Industrial facilities applying protective and functional coatings to capital equipment. Feedstock volatility and resin supply constraints complicate long-term supplier relationships.
- OEMs:Original equipment manufacturers with captive coating application lines and specification-grade quality systems.
Residential volume dominates current offtake; OEM relationships offer the most defensible margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tehran Province concentrates over half of national coatings consumption, with the Tehran-Isfahan infrastructure corridor pulling architectural volumes through state procurement channels.
Tehran Province
High-rise residential and commercial rehabilitation dominates demand, with public building renovation accelerating specification-grade procurement. Iran's national standards body enforces mandatory VOC labeling disclosure for interior architectural products. The city of Tehran hosts the densest distributor networks and digital tinting service deployment.
Isfahan Province
Steel fabrication and automotive component manufacturing drive industrial coatings consumption. The country's environmental regulator inspects coating application facilities for emissions control compliance. Isfahan's industrial zones attract epoxy and polyurethane system suppliers serving capital equipment protection.
Hormozgan Province
Bandar Abbas and Chabahar port expansion generates marine protective coatings demand for offshore structures and vessel maintenance. Port authority specifications require corrosion-resistant formulations meeting international maritime standards. The southern coastline anchors Jotun's specialized distribution footprint.
Kurdistan Province
Underpenetrated residential construction offers volume expansion for regionally distributed production assets. Domestic resin supply constraints complicate long-term supplier relationships outside Tehran-based technical service reach. Sanandaj and surrounding cities present untapped architectural coatings penetration.
East Azerbaijan Province
Manufacturing sector growth in Tabriz industrial zones pulls industrial coatings through OEM captive application lines. Feedstock volatility from domestic petrochemical allocation affects alkyd resin availability for regional compounders. The province sits outside Tehran's formulation chemist concentration.
Iran Paints and Coatings Market Competitive Landscape
Capital-heavy domestic manufacturers compete with asset-light import-dependent distributors for specification authority. The market structures around three tiers: integrated resin-to-coatings compounders, specialty import distributors, and bulk commodity wholesalers. Strategic moves concentrate on water-based R&D investment and digital tinting infrastructure deployment.
Among domestic integrated producers, Peka Chemie and Rangsazi Iran Company exemplify the compounder archetype with captive manufacturing assets. Jotun anchors the premium import-distributor tier through marine and protective specialization. These three occupy distinct competitive positions: domestic scale, import premium, and portfolio breadth.
| Leading Market Players |
|---|
| Peka Chemie |
| Ronass Chemical Producing Co. |
| Jotun |
| Nippon Paint |
| Saba Shimi Arya |
| Alvan Paint Co. |
| Rangsazi Iran Company |
| Ranguin Co. |
| Pars Pamchal Company |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap compounders anchor Iran's coatings supply base, translating captive resin production into pricing discipline that buffers volatile petrochemical allocations. Their localized manufacturing footprints limit working capital strain from import licensing friction while sustaining margin capture against commodity wholesalers.
Pricing Analysis
Outcome-based pricing tied to shade consistency and application durability anchors premium tier capture in Tehran Province high-rise developments. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade architectural emulsions from bulk commodity trade. Pricing pressure stems from titanium dioxide import dependency and extended customs clearance timelines that elongate distributor cash conversion cycles. Residential homeowners exhibit acute price sensitivity, while commercial developers with phased construction mandates prioritize batch-to-batch color stability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with China for titanium dioxide pigment and specialty epoxy resin intermediates. Domestic alkyd production draws from Iran's refinery output allocation, creating feedstock volatility that ripples through mid-tier compounder margins. Bandar Abbas port congestion and customs inspection delays constitute the dominant logistics chokepoint for imported additives. Distribution runs through certified contractor networks equipped with digital tinting hardware, displacing traditional bulk merchant wholesale channels in Tehran Province specification-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic resin capacity constraints prop pricing power for integrated compounders, as import licensing friction prevents rapid supply response to demand surges in the Tehran-Isfahan corridor.
For Market Incumbents: Extend water-based emulsion R&D investment to preempt Iran's national standards body VOC ceiling tightening, while securing captive titanium dioxide supply through long-term offtake arrangements with Chinese producers. Backward integration into emulsion polymerization capabilities defends margin position against reformulation-dependent competitors facing chemist scarcity outside Tehran. For New Entrants and Emerging Players: Iran's national standards body phased VOC mandates in interior architectural products opens a window for digital tinting service deployment in Kurdistan and East Azerbaijan Province construction markets. Target underpenetrated residential development in Sanandaj and Tabriz satellite cities where Tehran-based technical service reach remains thin. Lead with precision color-matching hardware partnerships that disintermediate bulk commodity distributors. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed domestic compounders with captive manufacturing assets in Hormozgan Province marine protective corridors. Long-term viability hinges on water-based formulation patent portfolios and port-proximate distribution infrastructure. Monitor Bandar Abbas and Chabahar port authority specification-grade procurement volumes as inflection indicator for marine coatings demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emulsion Polymerization | Captive resin production buffers Peka Chemie and Rangsazi Iran Company against petrochemical allocation volatility. |
| Digital Tinting Infrastructure Deployment | Precision color-matching hardware disintermediates bulk wholesalers in Tehran Province high-rise commercial projects. |
| Specialty Additive Import Channel Diversification | Multiple customs clearance routes reduce working capital cycle elongation from Iran's import licensing friction. |
| Marine Protective Formulation Certification | Port authority specifications at Bandar Abbas and Chabahar anchor Jotun's premium distribution positioning. |
| Regional Production Asset Distribution | Kurdistan and East Azerbaijan Province manufacturing footprints extend technical service reach beyond Tehran concentration. |
Research Methodology
Document review covered Iranian national standards body VOC regulatory filings, customs trade data for titanium dioxide and epoxy resin imports, and petrochemical sector output reports, complemented by interviews with formulation chemists at Tehran-based compounders, procurement leads at Isfahan steel and automotive suppliers, distributor network managers, and marine coatings applicators at Bandar Abbas port facilities. Secondary validation drew from Iran's environmental regulator emissions inspection protocols, construction sector procurement databases, and hospital and food-processing facility specifier surveys. Bottom-up volume modeling and top-down value triangulation cross-referenced distributor shipment records against end-use consumption estimates.
Historical volume trajectories were cross-referenced against expert panel input from plant managers and technical R&D directors to establish baseline growth parameters across the projection horizon. Segmentation dimensions modeled include product type tier, application environment, carrier technology chemistry, and end-user procurement sophistication. CAGRs were derived through iterative reconciliation of demand elasticity coefficients with capacity expansion timelines. Industry-specific forecast inputs incorporated Iran's national standards body phased VOC implementation schedule and Tehran-Isfahan infrastructure corridor state procurement pipeline visibility.
The model assumes a particular technology adoption path; alternative pathways for nano-scale functional additive integration would alter the outlook. Forecasts reflect assumptions regarding domestic resin supply stability and customs clearance efficiency that may shift with regulatory enforcement intensity or geopolitical trade friction. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Low VOC Paints and Coatings Market