

Paint Curing Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Curing Lamp Market Insights
Maintenance contracts and remote diagnostics software is recalibrating how paint curing lamp vendors monetize hardware deployments. Heraeus Noblelight leverages its spectral engineering heritage to dominate high-intensity UV arc and LED system supply for automotive lines. Nordson Corporation anchors North American installed base service revenue through predictive thermal monitoring subscriptions. Dr. Hönle AG differentiates via modular lamp head architectures that slash retrofit downtime for furniture and electronics producers.
Paint curing lamps are radiant energy devices that polymerize or dry coatings through controlled electromagnetic emission, typically operating across UV-A through infrared wavelengths with irradiance levels measured in watts per square centimeter. Their primary industrial purpose is to accelerate cure cycles while reducing volatile organic compound release compared to conventional thermal ovens. LED technology leads capital deployment growth due to mercury-free operation and instant on-off cycling that eliminates warm-up energy losses. Infrared retains margin density in heavy-body automotive clearcoat applications where deep penetration matters. Electronics Manufacturing represents the fastest-growing application vector as miniaturized conformal coating demands sub-60-second cure windows.
EPA NESHAP standards for hazardous air pollutants compel coating facilities to adopt lower-emission cure technologies, directly expanding addressable demand for UV and LED lamp retrofits. OSHA permissible exposure limits for ultraviolet radiation shape product guard design and interlock requirements across US manufacturing plants. ISO 9001 quality management and IEC 62471 photobiological safety certifications increasingly gate market access for lamp suppliers serving multinational vehicle assemblers. Stakeholders must weigh energy efficiency regulations against throughput requirements when selecting between LED and infrared architectures for specific substrate-coating combinations.
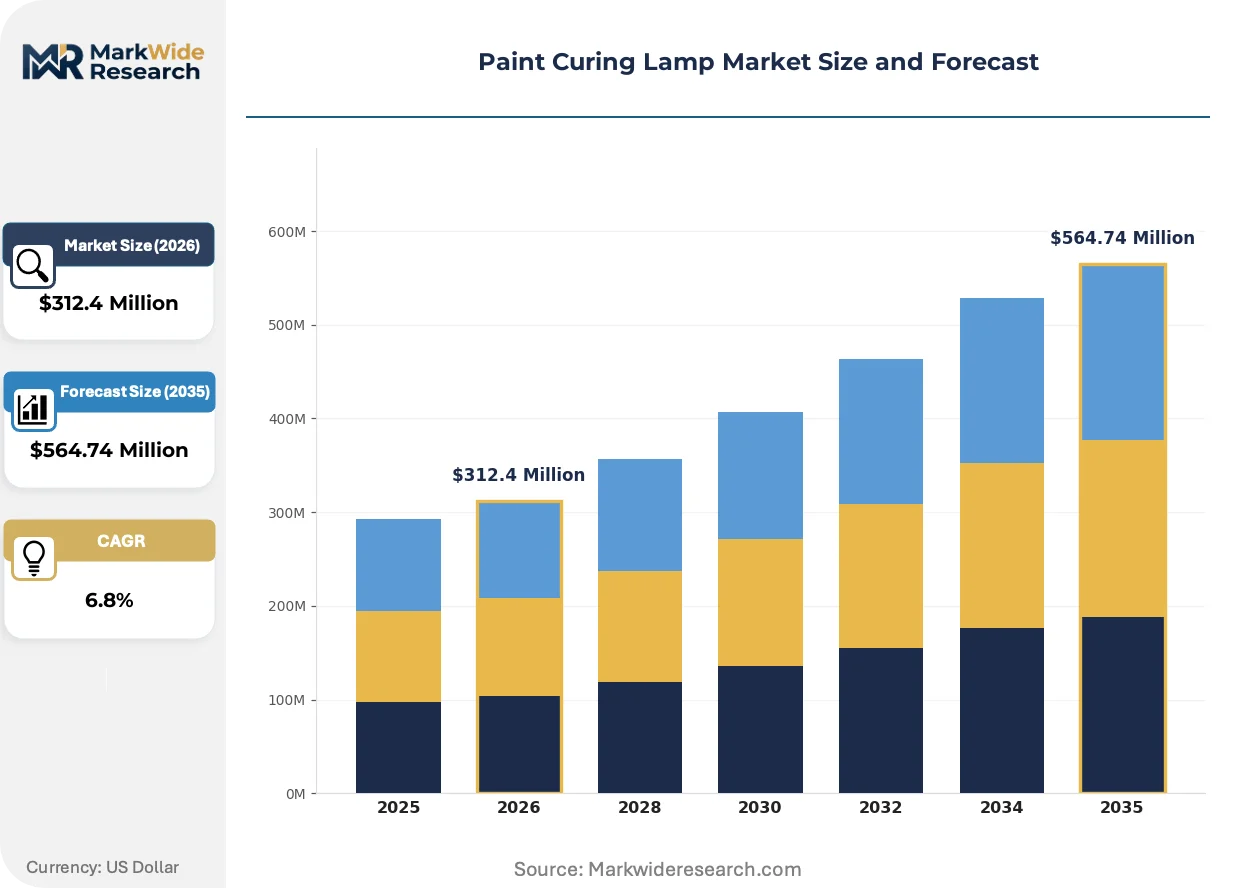
Market Dynamics
LED UV curing systems are compressing thermal oven footprints across automotive assembly lines while EPA NESHAP standards eliminate solvent-based alternatives. Equipment procurement now hinges on spectral efficiency metrics rather than capital cost alone.
Growth Catalysts
- EPA NESHAP Hazardous Air Pollutant Standards:US coating facilities face mandated emission reductions that directly accelerate UV and LED lamp retrofits. Compliance deadlines force capital deployment toward radiant cure technologies.
- Electronics Manufacturing:Miniaturized conformal coatings demand sub-60-second cure windows that only high-intensity UV systems deliver. Smartphone and semiconductor packaging lines drive specification intensity.
- Automotive OEM Equipment Procurement:Germany's vehicle assemblers anchor European demand as clearcoat quality requirements tighten. Tier-1 suppliers standardize on modular lamp architectures for paint shop flexibility.
Market Restraints
- Mercury Supply Concentration:Traditional UV arc lamps depend on mercury vapor chemistry with supply chains concentrated in limited refining jurisdictions. Price volatility constrains legacy system economics.
- Infrared Penetration Limitations:Deep-body automotive coatings retain thermal cure requirements where radiant energy cannot achieve substrate adhesion. LED UV wavelengths fail to polymerize certain high-build primers.
- OSHA Permissible Exposure Limits:Ultraviolet radiation safety thresholds mandate expensive interlock systems and protective guarding. Compliance adds 15-20% to installed system costs.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and mobile device production create virgin demand for conformal coating cure systems. Greenfield fabs specify mercury-free LED architectures.
- AI-Driven Predictive Maintenance:Machine learning algorithms analyzing lamp degradation patterns enable subscription-based thermal monitoring services. Equipment vendors capture recurring revenue from installed base analytics.
- Furniture and Wood Coatings:Water-based UV formulations are penetrating flatline finishing operations previously dominated by solvent thermal cures. Italian and Polish producers retrofit aging lines with modular LED heads.
Industry Challenges
- Spectral Engineering Talent Scarcity:Few technicians possess combined expertise in photopolymer chemistry and electromagnetic emitter design. Lamp vendors compete for limited application engineering resources.
- IEC 62471 Certification Timelines:Photobiological safety testing for new LED array configurations extends product launch cycles by 8-12 months. Multinational assemblers gate supplier qualification on complete certification packages.
- Legacy Thermal Oven Integration:Hybrid production lines requiring both radiant and convection stages face control system incompatibility. Retrofit projects stall on SCADA harmonization between old and new cure modules.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Curing Lamp Market Trends and Innovations
Spectral tunability and digital service layers are redefining competitive advantage in paint curing equipment. Vendors now compete on photon delivery precision rather than hardware durability alone.
UV-A LED arrays with adjustable peak wavelengths between 365-405 nanometers are rewriting cure protocol flexibility for mixed-substrate production lines. Automotive tier-1 suppliers in Germany and the United States adopt these systems to process both metal body panels and plastic bumper fascias without hardware changeover. The technology is compressing batch change intervals from hours to minutes while eliminating warm-up energy losses.
REACH restrictions on mercury-containing products are accelerating LED substitution timelines across European coating operations. The regulation forces automotive and furniture producers to eliminate medium-pressure arc lamps from 2027 compliance horizons. German OEMs are pre-emptively specifying mercury-free architectures in new paint shop tenders despite 15-20% capital premiums.
Subscription-based thermal monitoring contracts are displacing traditional break-fix service arrangements in North American installed bases. Fleet operators of curing equipment purchase predictive diagnostics through SaaS platforms rather than per-incident technician dispatch. This model concentrates among high-volume automotive assembly plants where unplanned downtime exceeds subscription costs within single shift losses.
Paint Curing Lamp Market Segmentation
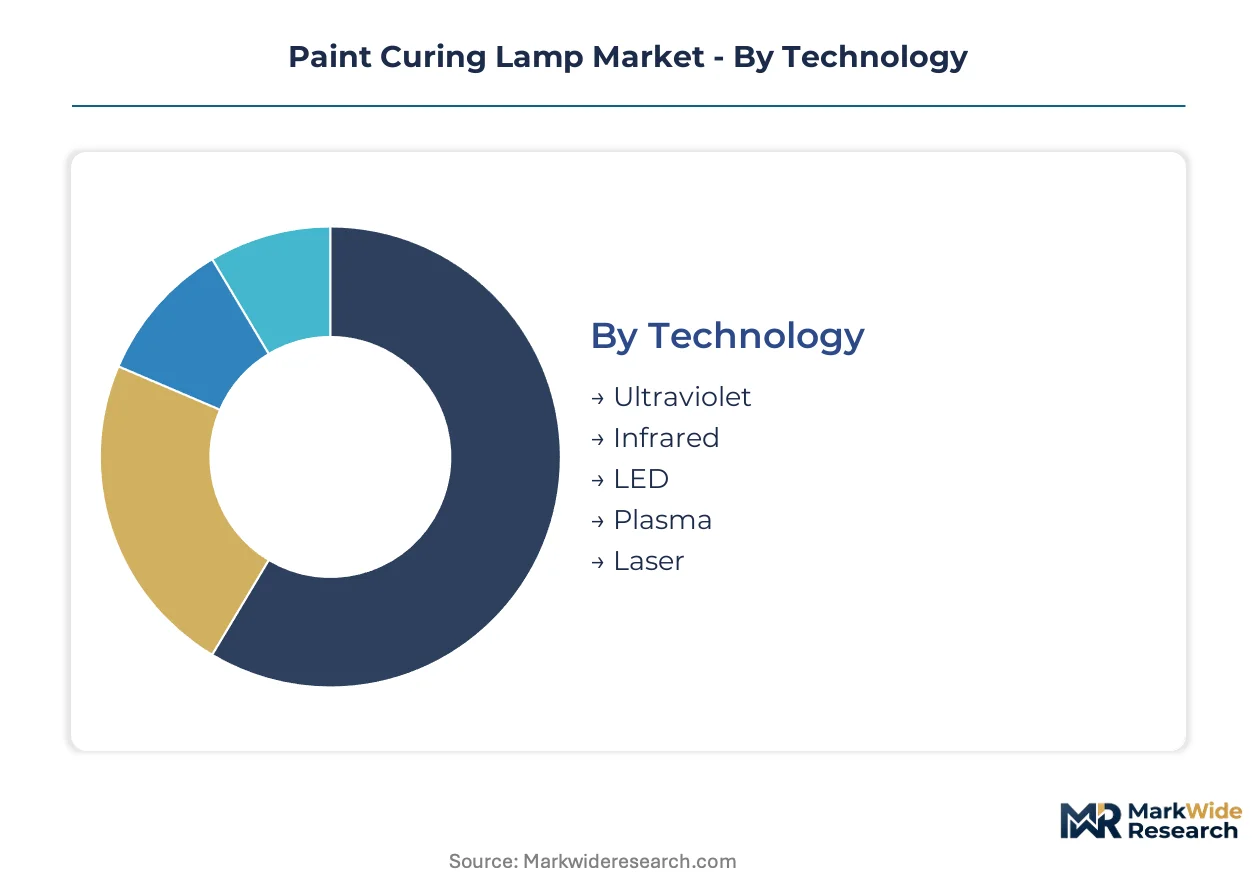
Paint curing lamp procurement varies sharply by substrate chemistry, throughput requirements, and regulatory exposure across end-use verticals. Technology selection determines spectral output, energy efficiency, and compliance trajectory for coating operations.
Technology:
Standardization dominates UV and infrared platforms while LED architectures offer modular customization for mixed-production environments.
- Ultraviolet:Medium-pressure mercury arc systems emit broadband UV-A and UV-B radiation through doped quartz envelopes for photoinitiator activation in automotive clearcoats. German OEM paint shops specify these for high-throughput metal finishing where spectral intensity trumps energy efficiency.
- LED:Solid-state semiconductor arrays deliver monochromatic output at 365-405 nanometers with instant on-off cycling and zero warm-up losses. Electronics manufacturing lines in India and Vietnam specify mercury-free LED heads to meet REACH pre-compliance and PLI scheme environmental requirements.
- Infrared:Ceramic and quartz-halogen emitters provide deep thermal penetration for high-build primers and heavy-body coatings.
- Plasma:Dielectric barrier discharge systems generate vacuum ultraviolet for specialized optical coating polymerization.
- Laser:Diode and fiber laser sources enable pinpoint cure control for microelectronic conformal coatings.
Most installed capacity flows through Ultraviolet. Expansion is steepest in LED.
Application:
Volume concentration in automotive contrasts with specification intensity in electronics and aerospace segments.
- Automotive OEMs:Integrated paint shop lines deploy multi-zone cure tunnels for electrocoat, primer, basecoat, and clearcoat stages. German vehicle assemblers anchor European procurement as EPA NESHAP compliance deadlines accelerate US retrofit demand.
- Electronics Manufacturing:Smartphone and semiconductor packaging lines require sub-60-second cure windows for miniaturized conformal coatings. Indian greenfield fabs under PLI incentives specify LED architectures exclusively.
- Aerospace Assemblies:Low-VOC primer and topcoat systems for airframe sections demand precise thermal control.
- Wood Finishing:Flatline operations for furniture and cabinetry adopt water-based UV formulations.
- Metal Fabrication:Coil coating and general industrial finishing utilize medium-wattage infrared systems.
Revenue concentration sits with Automotive OEMs. Climbing the fastest is Electronics Manufacturing.
Power Rating:
Capital deployment scales with substrate mass and line speed requirements across wattage tiers.
- High Wattage:Systems exceeding 100W/cm irradiance serve automotive clearcoat tunnels and heavy metal fabrication where thermal mass demands peak energy delivery. German tier-1 suppliers standardize on adjustable high-wattage heads for paint shop flexibility.
- Adjustable Output:Digitally controlled power modulation enables single-lamp processing of mixed metal and plastic substrates. US automotive tier-1 suppliers adopt these for bumper-to-body panel transitions without hardware changeover.
- Medium Wattage:40-80W/cm systems balance throughput and energy efficiency for general industrial coating.
- Low Wattage:Sub-40W/cm units serve laboratory and small-batch electronics prototyping.
Deployment volume clusters in High Wattage. Gaining share fastest is Adjustable Output.
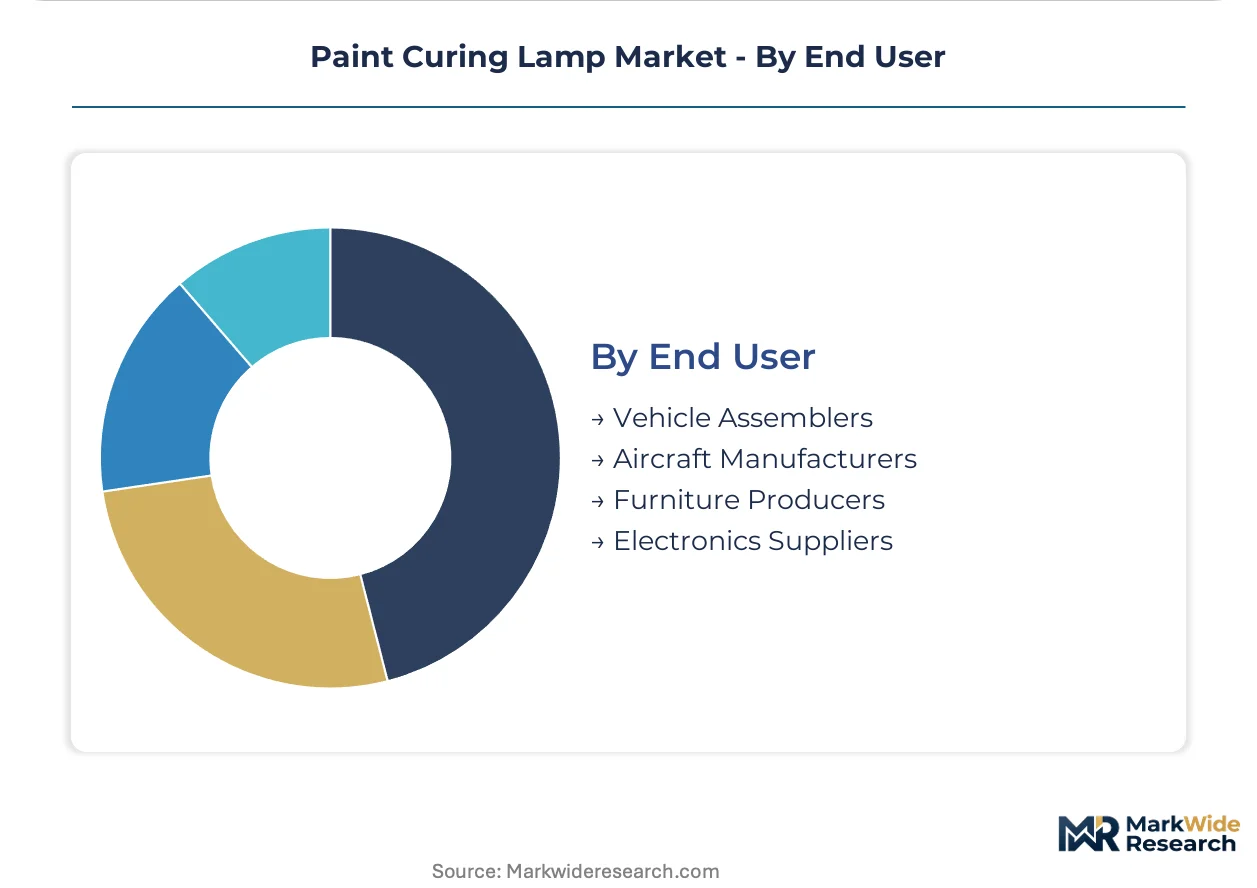
End User:
Procurement sophistication separates multinational assemblers from regional specialist producers.
- Vehicle Assemblers:Integrated manufacturing campuses operate captive paint shops with dedicated cure tunnel engineering teams. German OEMs and US-based transplants specify IEC 62471-certified systems with predictive maintenance subscriptions.
- Electronics Suppliers:Contract manufacturers and captive semiconductor fabs prioritize mercury-free LED compliance and sub-60-second cycle times. Indian and Vietnamese production facilities drive specification intensity for conformal coating lines.
- Aircraft Manufacturers:Airframe assemblers and tier suppliers demand specialized low-VOC cure protocols.
- Furniture Producers:Italian and Polish flatline finishing operations retrofit aging thermal ovens with modular UV heads.
Procurement volume concentrates in Vehicle Assemblers. Steepest expansion trajectory belongs to Electronics Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium automotive paint shop specifications while the United States drives regulatory retrofit cycles through EPA compliance deadlines. Equipment procurement intensity concentrates where OEM assembly density intersects with emissions enforcement.
United States
Automotive transplants and domestic OEMs accelerate UV and LED lamp retrofits as EPA NESHAP hazardous air pollutant deadlines approach. OSHA permissible exposure limits for ultraviolet radiation shape interlock system specifications across Michigan and Ohio assembly corridors. Detroit-area tier-1 suppliers standardize on predictive maintenance subscriptions to minimize unplanned downtime costs.
Germany
Vehicle assemblers anchor European demand through integrated paint shop tenders specifying IEC 62471-certified systems. REACH restrictions on mercury-containing products force pre-emptive LED architecture adoption from 2027 compliance horizons. Bavarian and Baden-Württemberg automotive clusters drive specification intensity for modular lamp head designs.
China
Domestic EV manufacturers expand captive paint shop capacity with mercury-free LED specifications aligned with dual carbon goals. GB standards for industrial emissions shape cure technology selection in Yangtze River Delta coating operations. Shanghai and Guangzhou automotive hubs deploy high-wattage adjustable output systems for mixed metal-plastic substrate processing.
India
PLI scheme incentives for semiconductor and mobile device production create virgin demand for conformal coating cure systems. BIS certification requirements gate market access for lamp suppliers serving greenfield electronics fabs. Karnataka and Tamil Nadu electronics manufacturing clusters specify sub-60-second cycle LED architectures exclusively.
Japan
Precision electronics and automotive coating operations demand photobiological safety-compliant systems for high-throughput lines. METI energy efficiency guidelines favor instant on-off LED technologies over thermal oven alternatives. Kanto and Kansai industrial corridors concentrate specification development for miniaturized conformal coating applications.
Paint Curing Lamp Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with spectral engineering heritage determining premium positioning. The vendor base organizes around three strategic archetypes: German-engineered UV system houses, North American integrated equipment platforms, and Asian precision electronics specialists. Consolidation pressure concentrates among mid-scale infrared suppliers facing LED substitution. Dominant competitive moves include predictive diagnostics service layering and modular lamp head architecture licensing.
Among German-engineered specialists, Heraeus Noblelight and Dr. Hönle AG occupy positions anchored by spectral engineering heritage and modular architecture expertise respectively. Nordson Corporation represents the North American integrated platform archetype with installed base service revenue concentration. These three exemplify how geographic origin and company structure correlate with competitive positioning across automotive and electronics verticals.
| Leading Market Players |
|---|
| Heraeus Noblelight |
| GEW (EC) Limited |
| Dr. Hönle AG |
| Nordson Corporation |
| Excelitas Technologies |
| Ushio America |
| American Ultraviolet |
| Dymax Corporation |
| Infratech |
| Others |
Pricing and Supply Chain Analysis
LED UV curing technology migration simultaneously compresses production costs for solid-state emitters and concentrates supply leverage among semiconductor foundries with gallium nitride epitaxy capabilities. This dual transformation rewards buyers scaling procurement volumes while penalizing legacy mercury-arc lamp producers facing input volatility and regulatory obsolescence timelines.
Pricing Analysis
Capacity additions in China and Vietnam are reshaping price floors for LED curing modules as domestic epitaxial wafer production scales. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62471-certified automotive systems from uncertified industrial units. Cost compression in mid-wattage tiers is intensifying because Chinese EV manufacturers negotiate volume offtakes. Electronics contract manufacturers in India exhibit highest price sensitivity; German automotive OEMs prioritize spectral precision over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated paint shop systems, while distributor networks serve retrofit and aftermarket segments. German, Chinese, and Japanese suppliers anchor global production of quartz envelope materials and gallium nitride substrates. The supply chain draws from concentrated mercury refining jurisdictions for legacy arc lamp production. Single-source vulnerability persists in high-purity alumina ceramic substrates for infrared emitters. Distribution runs through specialized industrial equipment dealers with application engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
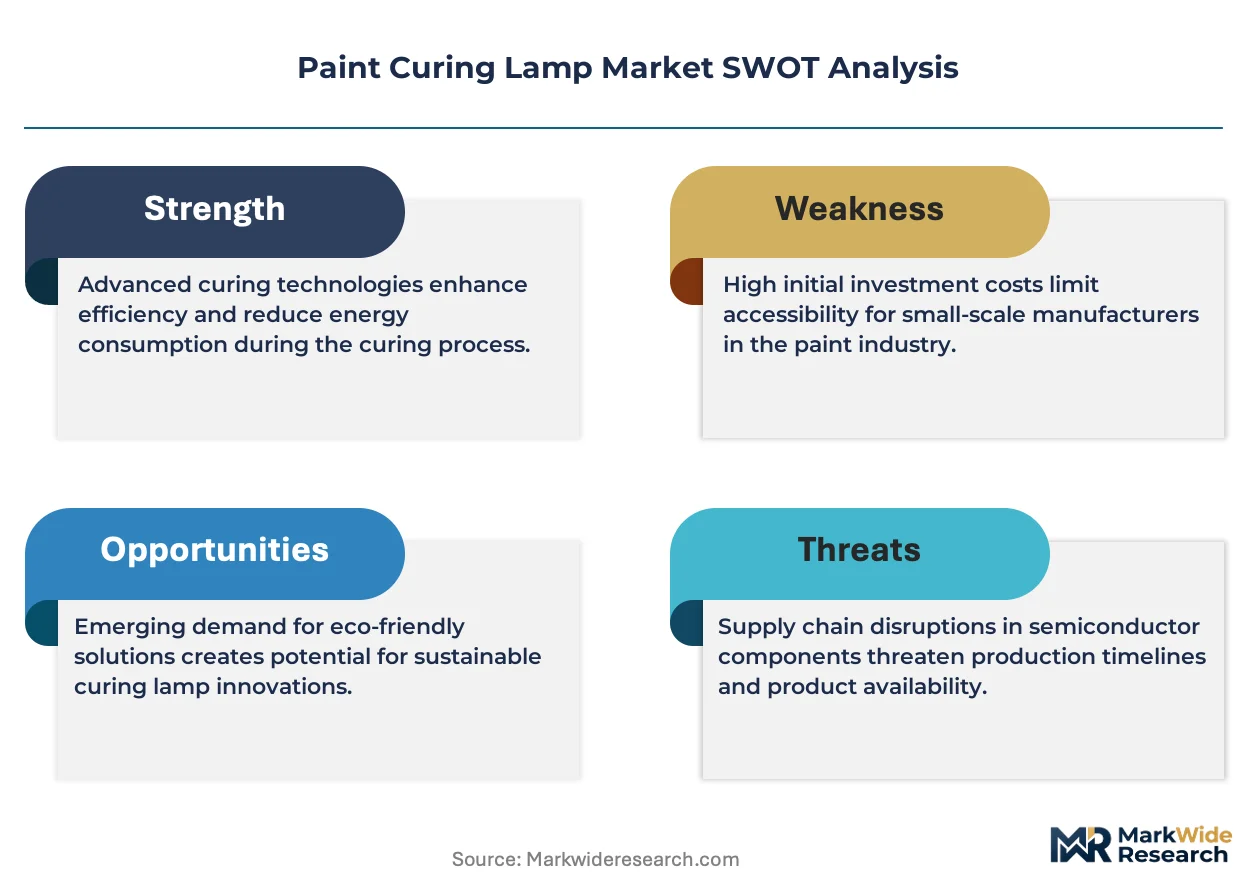
Paint curing equipment has entered a late-cycle quality phase where REACH compliance and spectral tunability specifications command procurement priority over capital cost minimization. Electronics manufacturing and automotive clearcoat segments now specify premium-tier LED architectures exclusively.
For Market Incumbents: Cement service revenue concentration through predictive thermal monitoring subscriptions that lock in automotive installed base relationships. Deepen backward integration into gallium nitride epitaxy supply to defend margin position against Chinese LED module producers. Prioritize IEC 62471 certification investment as multinational assemblers gate supplier qualification on complete photobiological safety packages. For New Entrants and Emerging Players: The 15-20% capital premium gap between mercury-free LED and legacy arc systems creates entry space for mid-tier modular architectures targeting Polish and Italian furniture retrofit demand. Target electronics manufacturing greenfield facilities in Karnataka and Tamil Nadu where PLI scheme incentives override first-cost sensitivity. Pursue licensing arrangements with established spectral engineering houses to accelerate market access without captive R&D burden. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale infrared specialists facing LED substitution pressure and lacking predictive diagnostics service layering. Long-term viability favors vendors with combined spectral engineering heritage and SaaS-enabled installed base monetization. Monitor REACH enforcement acceleration as the inflection signal for mercury-arc lamp obsolescence timelines and associated distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Epitaxy | Captures margin from Chinese wafer producers while securing supply for high-wattage automotive modules. |
| Predictive Diagnostics Platform Launch | Transforms Nordson's installed base into recurring revenue through thermal monitoring subscriptions. |
| IEC 62471 Certification Acceleration | Gates supplier qualification for German OEM tenders with 2027 REACH compliance horizons. |
| Modular Lamp Head Architecture Licensing | Enables Dr. Hönle AG to capture retrofit demand without direct sales force expansion. |
| PLI Scheme Alignment for Indian Electronics | Positions mercury-free LED systems for Karnataka and Tamil Nadu greenfield fab specifications. |
Research Methodology
Multiple input streams — primary interviews, regulatory filing analysis, and trade data reconciliation — were synthesized to construct market estimates. Paint shop engineering directors, Tier 1 supplier procurement leads, and electronics manufacturing facility managers provided operational perspective. Secondary validation drew from EPA NESHAP dockets, REACH restriction timelines, IEC certification registries, and automotive production databases. Bottom-up equipment deployment counts and top-down coating industry value chain analysis were cross-referenced for triangulation.
Segment-level outputs across the analysis window were reconciled against technology substitution curves and regulatory compliance deadlines. Modeled dimensions span curing technology type, power rating tier, end-use vertical, and geographic production cluster. CAGRs were derived from fitted adoption curves weighted by regulatory enforcement intensity and OEM capital expenditure cycles. Forecast inputs incorporated spectral efficiency improvement trajectories for LED arrays and mercury supply concentration risk factors.
Caveats apply where REACH enforcement acceleration or gallium nitride substrate supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding EPA NESHAP compliance adherence and PLI scheme continuation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.