
 Paint and Coating Stripper Market | 2026-2036
Paint and Coating Stripper Market Size, Share, and Industry Trends Forecast 2026-2036
Paint and Coating Stripper Market Analytics
Asset-light leasing models for industrial stripping equipment is narrowing the capital barrier for mid-sized contractors. Henkel AG & Co. KGaA leverages its adhesive and surface preparation heritage to anchor premium formulation sales across European automotive networks. Sherwin-Williams Company sustains dense distribution through its retail and professional contractor channels. Dumond Chemicals specializes in non-toxic, soy-based strippers that compete on safety compliance rather than speed.
Paint and coating stripper denotes a chemical formulation designed to dissolve, swell, or degrade cured paint, varnish, or protective coatings through alkaline hydrolysis, solvent penetration, or enzymatic action, typically operating at ambient or mildly elevated temperatures with dwell times ranging from minutes to hours. Its primary purpose spans surface restoration, substrate reclamation, and preparation for recoating across industrial maintenance, automotive refinishing, and building renovation workflows. Solvent-based formulations still dominate volume but face structural decline as OSHA methylene chloride restrictions and REACH substance evaluations curtail their addressable market. Environmentally friendly and biochemical segments capture expanding margin pools as contractors and manufacturing end users absorb modest price premiums to preempt regulatory liability and workplace exposure claims. Gel and paste formulations lead in residential and DIY channels where vertical cling and controlled application reduce spill risk.
EPA risk evaluations under the Toxic Substances Control Act, OSHA worker protection standards for methylene chloride, and REACH authorization requirements collectively reshape product portfolios toward safer active ingredients. BIS standards in India and China's GB standards for volatile organic compound emissions add compliance layers for exporters targeting manufacturing hubs. Stakeholders must monitor pending chemical hazard designations and pre-position formulation pipelines before regulatory deadlines eliminate incumbent chemistries from commercial use.
Market Dynamics
OSHA methylene chloride restrictions and REACH authorization timelines are forcing incumbent formulators to rebuild active ingredient portfolios from the ground up. This regulatory compression is collapsing legacy product lines faster than replacement chemistries can achieve commercial scale.
Growth Catalysts
- EPA air quality mandates:Automotive refinishing shops in California and Texas face escalating VOC limits. Low-emission stripping systems secure operational permits where solvent-heavy alternatives face shutdown orders.
- Water-based hydrolysis chemistry:Industrial maintenance contractors adopt alkaline gel systems for tank and vessel cleaning. Extended dwell times trade off against eliminated respiratory protection requirements and disposal liability.
- China manufacturing maintenance cycles:Heavy equipment producers in Jiangsu and Guangdong provinces execute scheduled coating removal at 18-month intervals. Sustained production volumes feed recurring chemical demand.
Market Restraints
- Feedstock concentration:N-methyl-2-pyrrolidone and dibasic ester supply chains cluster in German and Chinese petrochemical corridors. Price volatility transmits directly to stripper formulation costs.
- Performance gap in biochemical alternatives:Soy-based and enzyme-activated strippers require 3-4x dwell time versus methylene chloride on epoxy and polyurethane coatings. Productivity losses limit adoption in high-throughput refinishing environments.
- REACH authorization friction:ECHA substance evaluation timelines for remaining solvent chemistries extend 24-36 months. Formulators face portfolio gaps during transition periods.
Strategic Opportunities
- India industrial infrastructure buildout:BIS standards for VOC emissions in manufacturing facilities are tightening. First-mover biochemical suppliers capture specification-setting authority with domestic paint producers and state-owned refineries.
- On-site regeneration services:Equipment leasing models pair chemical supply with spent solvent recovery. Contractors convert capital expenditure to operational spend while vendors secure recurring revenue streams.
- EU Green Deal procurement mandates:Public infrastructure maintenance contracts in Germany and France now require environmental product declarations. Certified low-toxicity strippers gain preferential bidding status.
Industry Challenges
- Formulation chemist scarcity:Expertise in enzymatic and biosurfactant chemistry sits concentrated in academic and specialty biotech channels. Industrial chemical recruiters compete against pharmaceutical and agricultural sectors for equivalent talent pools.
- Dual certification timelines:Products requiring both EPA Safer Choice designation and EU Ecolabel face 14-18 month parallel review processes. Launch windows compress against regulatory deadlines eliminating incumbent chemistries.
- Legacy equipment incompatibility:Existing spray application and immersion tank systems in automotive body shops require material-of-construction upgrades for water-based stripper compatibility. Capital barriers slow fleet turnover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint and Coating Stripper Market |
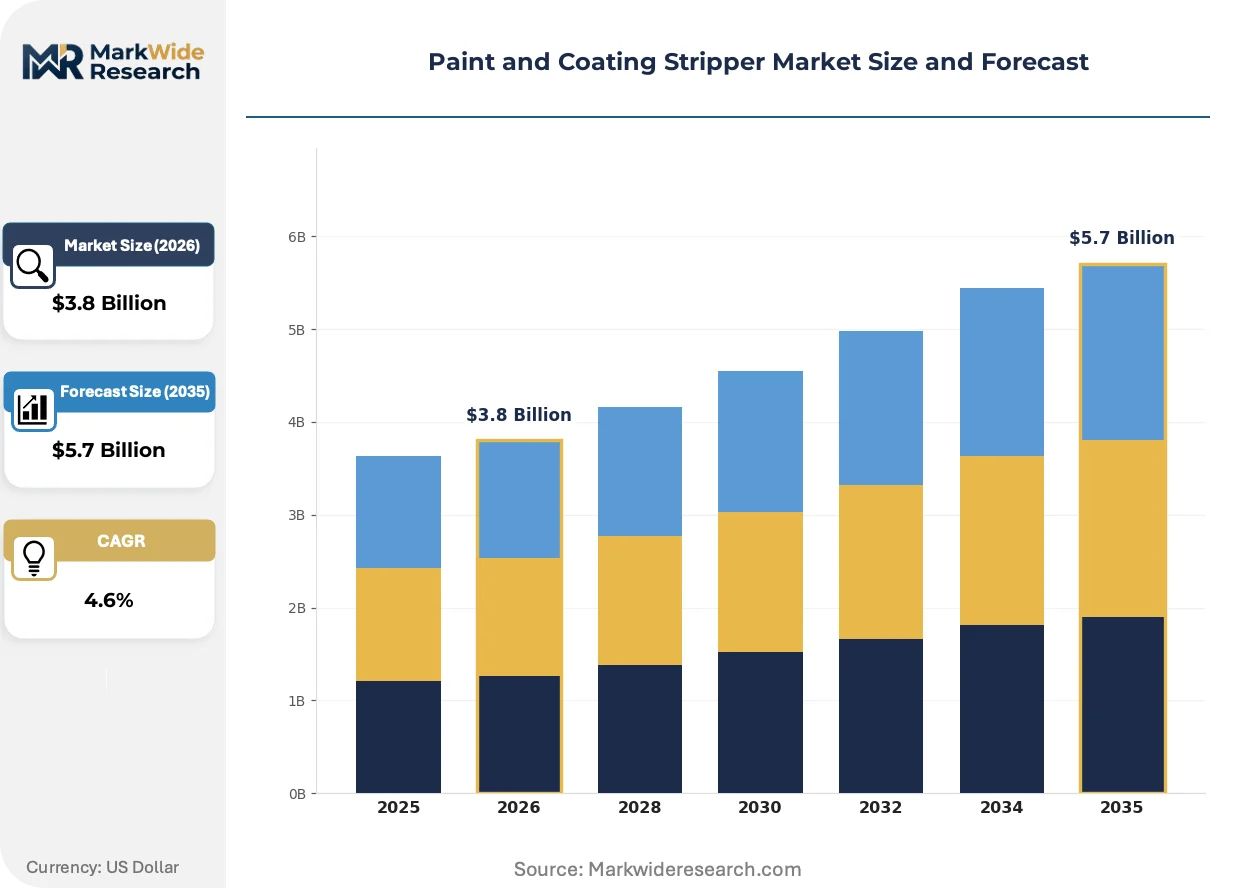
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Caustic-Based, Biochemical, Environmentally Friendly Formulation: Liquid, Gel, Paste, Foam Application: Industrial, Residential, Automotive, Marine End User: Contractors, DIY Enthusiasts, Manufacturing, Construction Firms |
| Companies Covered | 3M, PPG Industries, Sherwin-Williams Company, Akzo Nobel N.V., Henkel AG & Co. KGaA, RPM International Inc., Dumond Chemicals, Franmar Chemical, Sunnyside Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint and Coating Stripper Market Evolving Landscape
Active ingredient portfolios are bifurcating between high-performance industrial solvents facing phased elimination and emerging bio-based systems trading speed for safety compliance. Formulators now optimize for regulatory survival rather than pure technical efficacy.
Biochemical enzyme systems incorporating lipase and protease blends are migrating from laboratory validation to commercial refinishing contracts. Tier-one automotive OEMs in Stuttgart and Detroit specify these systems for warranty repair operations where worker exposure documentation is mandatory. The technology is migrating from premium niche positioning toward volume parity as unit economics improve with scale fermentation.
ECHA's 2024 update to REACH candidate list criteria is accelerating substitution planning across coating removal supply chains. German and Dutch formulators now pre-emptively withdraw products containing substances of very high concern before formal authorization deadlines. Automotive networks in Bavaria and North Rhine-Westphalia face compressed supplier qualification cycles as approved chemical lists shrink quarterly.
Asset-light chemical management contracts are displacing bulk purchase agreements in North American industrial maintenance channels. Facility managers at Ohio and Michigan manufacturing plants outsource inventory, application equipment, and waste handling to integrated service providers. This restructuring concentrates purchasing authority with national account managers and erodes regional distributor margins.
Paint and Coating Stripper Market Segmentation
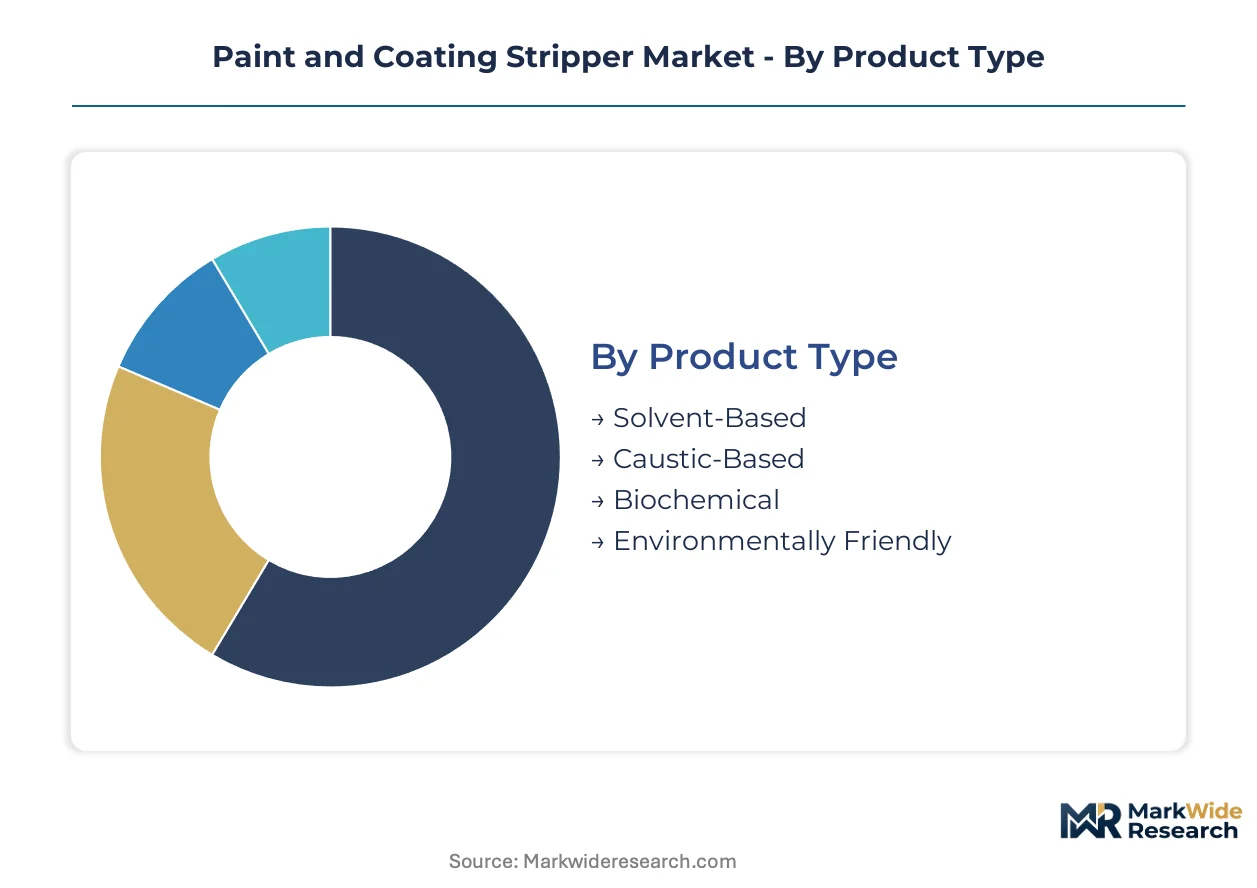
Paint and coating stripper segmentation tracks the regulatory migration from solvent-heavy formulations toward compliant alternatives. Manufacturers align R&D pipelines with end-use performance requirements and regional chemical restrictions.
Product Type:
Cost tier structures the competitive landscape, with premium biochemical formulations commanding price multiples over commodity solvents while regulatory elimination of legacy chemistries compresses mid-market positioning.
- Solvent-Based:Methylene chloride and N-methyl-2-pyrrolidone formulations deliver rapid coating dissolution through aggressive solvent penetration. Automotive refinishing shops in Texas and California face operational permit restrictions as EPA VOC limits tighten, forcing accelerated fleet turnover to compliant alternatives.
- Biochemical:Enzyme-activated systems incorporating lipase and protease blends hydrolyze coating polymers through catalytic action rather than solvent dissolution. Tier-one automotive OEMs in Stuttgart and Detroit specify these for warranty repair operations where OSHA worker exposure documentation is mandatory.
- Caustic-Based:Alkaline hydrolysis chemistry using sodium hydroxide or potassium hydroxide saponifies oil-based coatings. Industrial tank cleaning contractors favor extended dwell times against eliminated respiratory protection requirements.
- Environmentally Friendly:Soy-based and citrus-derived terpene formulations target residential and DIY channels where safety certification drives purchase decisions.
Solvent-Based holds installed capacity. Biochemical is rotating up the share rankings.
Formulation:
Application method determines dwell time control, vertical cling performance, and spill risk profiles across industrial and consumer use cases.
- Gel:Thickened rheology enables application to vertical and overhead surfaces without runoff, critical for architectural restoration and aircraft maintenance. Contractors in Bavaria specify gel systems for EU Green Deal procurement mandates requiring environmental product declarations.
- Liquid:Low-viscosity penetration suits immersion tank operations and spray application in high-throughput manufacturing environments. Existing equipment in Ohio and Michigan body shops requires material compatibility upgrades for water-based liquid alternatives.
- Paste:Heavy-bodied consistency provides extended surface contact for thick coating buildup removal. Marine maintenance yards favor paste formulations for hull stripping where controlled application reduces environmental release.
- Foam:Expansive delivery increases surface area coverage per unit volume, gaining traction in large-scale industrial maintenance contracts.
Liquid holds installed capacity. Gel is rotating up the share rankings.
Application:
Volume concentration varies by maintenance cycle frequency, regulatory exposure, and coating specification complexity across end-use environments.
- Industrial:Scheduled coating removal at manufacturing facilities in Jiangsu and Guangdong provinces sustains recurring chemical demand at 18-month maintenance intervals. Asset-light leasing models for stripping equipment narrow capital barriers for mid-sized contractors.
- Automotive:Refinishing operations face the most stringent VOC compliance requirements, with EPA and state-level air quality rules in California and Texas driving low-emission system adoption.
- Residential:DIY consumers prioritize safety certification and controlled application over stripping speed, favoring gel and paste formulations with reduced spill risk.
- Marine:Hull maintenance and antifouling coating removal operate under port authority environmental discharge regulations, favoring biodegradable alternatives.
Industrial holds installed capacity. Automotive is rotating up the share rankings.
End User:
Customer type determines procurement authority structure, with integrated service contracts displacing bulk purchase agreements in institutional channels.
- Contractors:Mid-sized stripping specialists convert capital expenditure to operational spend through equipment leasing paired with chemical supply and waste handling services.
- Manufacturing:Facility managers at Michigan and Ohio plants outsource inventory management to integrated providers, concentrating purchasing authority with national account managers.
- DIY Enthusiasts:Retail channel consumers respond to safety labeling and VOC content disclosure, with gel formulations leading residential purchase patterns.
- Construction Firms:Building renovation contractors face project-specific coating removal requirements with variable substrate conditions and coating age profiles.
Contractors hold installed capacity. Manufacturing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA methylene chloride restrictions and REACH authorization timelines are compressing formulation portfolios across major industrial economies. Regulatory deadlines eliminate incumbent chemistries faster than replacement systems achieve commercial scale.
United States
Automotive refinishing shops in California and Texas face escalating VOC limits under EPA air quality mandates. OSHA worker protection standards for methylene chloride force operational permit restrictions. Low-emission stripping systems secure compliance where solvent-heavy alternatives face shutdown orders.
Germany
ECHA substance evaluation timelines extend 24-36 months for remaining solvent chemistries. Formulators in Bavaria and North Rhine-Westphalia face compressed supplier qualification cycles. German automotive networks pre-emptively withdraw products containing substances of very high concern.
China
Heavy equipment producers in Jiangsu and Guangdong provinces execute scheduled coating removal at 18-month maintenance intervals. GB standards for volatile organic compound emissions add compliance layers for domestic manufacturers. Sustained production volumes feed recurring chemical demand across manufacturing hubs.
India
BIS standards for VOC emissions in manufacturing facilities are tightening. First-mover biochemical suppliers capture specification-setting authority with domestic paint producers. State-owned refineries drive demand for compliant stripping systems in industrial maintenance cycles.
Paint and Coating Stripper Market Competitive Landscape
On the supply side, the industry is consolidating around formulation specialists with regulatory compliance capabilities and diversified chemical portfolios. The competitive terrain separates legacy solvent formulators facing phased elimination from emerging bio-based entrants trading speed for safety certification. Three archetypes dominate: diversified coatings conglomerates with dense distribution networks, specialty chemical houses with surface preparation heritage, and niche biochemical producers competing on toxicity compliance. Dominant competitive moves include portfolio diversification into low-VOC alternatives and strategic partnerships with equipment lessors to capture recurring service revenue.
Within the diversified coatings tier, 3M and PPG Industries occupy positions anchored by broad industrial distribution and cross-selling capabilities into refinishing and maintenance channels. Sherwin-Williams Company exemplifies the retail-professional hybrid model with contractor-facing supply chains. Dumond Chemicals represents the biochemical specialist archetype, competing on safety compliance rather than stripping speed. These three players illustrate the strategic bifurcation between scale-driven incumbents and compliance-focused challengers reshaping competitive positioning.
| Leading Market Players |
|---|
| 3M |
| PPG Industries |
| Sherwin-Williams Company |
| Akzo Nobel N.V. |
| Henkel AG & Co. KGaA |
| RPM International Inc. |
| Dumond Chemicals |
| Franmar Chemical |
| Sunnyside Corporation |
| Others |
Value Network & Pricing Analysis
N-methyl-2-pyrrolidone and dibasic ester production clusters in German and Chinese petrochemical corridors anchor formulation cost structures. Margin pools concentrate with biochemical specialists commanding safety-compliance premiums while solvent-based incumbents absorb feedstock volatility.
Pricing Analysis
Certification level (EPA Safer Choice, EU Ecolabel) creates the primary spread between biochemical premium tiers and commodity solvent positioning. Three-tier pricing structure across premium biochemical, mid-market caustic, and economy solvent levels stratifies by compliance documentation depth. Pricing pressure stems from REACH authorization timelines compressing legacy product viability before replacement chemistries achieve scale. DIY enthusiasts exhibit highest price sensitivity; tier-one automotive OEMs absorb premiums for worker exposure liability mitigation.
Supply Chain Analysis
Upstream N-methyl-2-pyrrolidone, dibasic ester, and soy-derived terpene feedstocks draw from concentrated German, Chinese, and North American agricultural processing hubs. Specialty enzyme suppliers in Danish and Dutch biotech corridors feed emerging biochemical formulation pipelines. Single-source vulnerability sits with petrochemical intermediates facing European energy cost volatility. Distribution runs through integrated service contracts displacing regional distributor networks in North American industrial maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light chemical management platforms are reconfiguring procurement authority toward national account structures. Interoperability between stripping equipment leasing, chemical supply, and waste recovery services creates ecosystem lock-in for first movers.
For Market Incumbents: Build regulatory compliance moats through parallel EPA Safer Choice and EU Ecolabel certification pipelines. Accelerate backward integration into captive enzyme fermentation capacity before biotech talent pools deplete. Pre-emptively withdraw substances of very high concern before formal REACH deadlines to compress competitor qualification cycles. Channel control through contractor equipment leasing secures recurring revenue against spot chemical purchases. For New Entrants and Emerging Players: Establish a beachhead in Indian industrial infrastructure buildout where BIS standard tightening creates specification-setting windows. Target state-owned refinery maintenance contracts with biochemical systems that preempt domestic regulatory escalation. White-space exists in on-site regeneration services pairing chemical supply with spent solvent recovery. Go-to-market through integrated service contracts converts capital expenditure barriers into operational spend acceptance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical houses holding surface preparation heritage but lacking biochemical R&D depth. Five-to-ten year viability hinges on successful portfolio rotation from solvent-based to enzyme-activated systems before regulatory elimination accelerates. Acquisition targets include enzymatic formulation specialists with Tier-one automotive OEM qualifications. Signal to monitor: ECHA candidate list expansion velocity as inflection indicator for substitution timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Fermentation | Captive lipase and protease supply secures biochemical formulation margins against biotech sector competition. |
| Parallel Certification Investment | Dual EPA Safer Choice and EU Ecolabel pipelines compress launch windows against regulatory deadlines. |
| Equipment Leasing Platform Expansion | Asset-light models convert contractor capital barriers into recurring chemical and service revenue streams. |
| India Market Specification Capture | First-mover biochemical positioning with domestic paint producers anchors BIS-compliant supply relationships. |
| On-Site Regeneration Service Launch | Spent solvent recovery integration closes waste liability loops while securing long-term chemical offtake. |
Research Methodology
Operator-level perspectives from plant managers at refinishing shops, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors anchored the qualitative base. Secondary validation drew from EPA risk evaluations, ECHA substance dossiers, SEC 10-K filings from coatings conglomerates, and customs trade data on N-methyl-2-pyrrolidone flows. Bottom-up triangulation across end-use demand segments converged with top-down macroeconomic and regulatory scenario analysis.
Scenario-bracketing around OSHA enforcement intensity, REACH authorization velocity, and China manufacturing maintenance cycle durability framed the projection horizon. Segmentation dimensions modeled include product type tier, formulation rheology, application environment, and end-user procurement structure. CAGRs were derived from segment-level volume build-ups cross-checked against regulatory phase-out timelines and replacement chemistry commercialization curves. Feedstock price elasticity and equipment leasing adoption curves fed industry-specific sensitivity inputs.
Stress conditions across N-methyl-2-pyrrolidone supply disruption, accelerated methylene chloride elimination, and biochemical dwell-time performance gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory implementation schedules and enzyme production scale economics. Cross-checking against automotive OEM warranty repair specification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
India Automotive OEM Coatings Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Road Marking Paints and Coatings Market