
 Aliphatic Hydrocarbon Solvents and Thinners Market | 2026-2036
Aliphatic Hydrocarbon Solvents and Thinners Market Size, Share, and Industry Trends Forecast 2026-2036
Aliphatic Hydrocarbon Solvents and Thinners Market Analysis
Refinery expansions across the US Gulf Coast are expanding aliphatic solvent availability for downstream chemical processing. ExxonMobil Corporation leverages integrated refinery-chemical complexes to secure feedstock cost advantages. Shell plc anchors its position through global distribution networks spanning industrial clusters. BASF differentiates via specialized high-purity grades targeting pharmaceutical and electronics applications.
Aliphatic hydrocarbon solvents and thinners comprise saturated straight-chain and branched hydrocarbons typically in the C5-C12 range, produced through crude oil distillation and subsequent hydrotreating to achieve defined boiling point fractions and aromatic content below specified thresholds. These solvents function primarily as diluents, carriers, and cleaning agents where controlled evaporation rates and minimal residue are essential. Mineral spirits dominates volume consumption across paint thinning and general industrial cleaning applications where cost-performance balance matters most. Hexane extracts edible oils and serves as polymerization reaction medium, commanding premium pricing in food-grade and polymer-grade specifications. Laboratory grade solvents carry the tightest purity certifications, creating concentrated margin pools despite smaller absolute volumes.
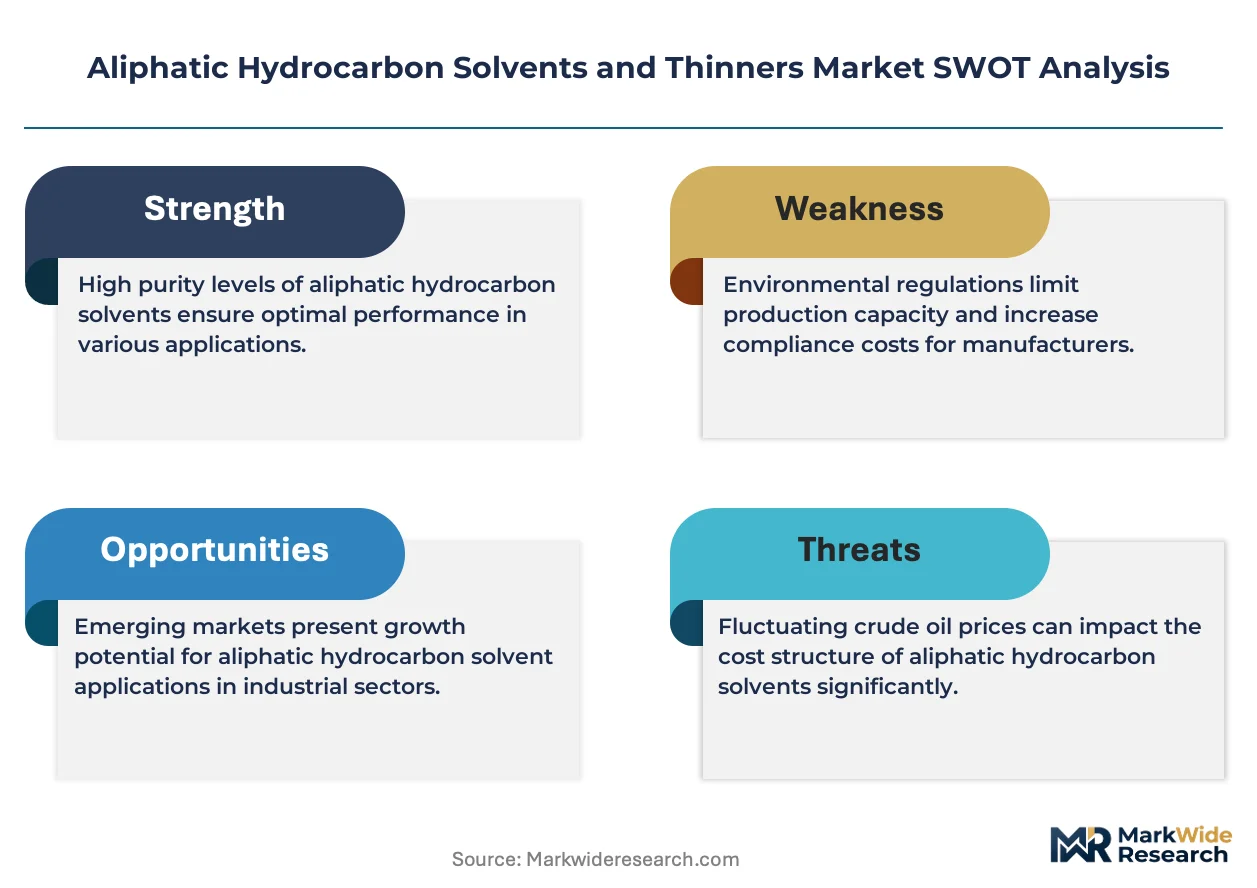
EPA regulates volatile organic compound emissions under Clean Air Act mandates, pushing reformulation toward low-aromatic and high-flash-point alternatives. OSHA enforces permissible exposure limits for n-hexane and other neurotoxic components, directly constraining product composition and workplace handling protocols. ECHA classifies certain aliphatic fractions as substances of very high concern under REACH, reshaping import and formulation requirements for European market access. Stakeholders must monitor regulatory divergence between jurisdictions while evaluating bio-based hydrocarbon alternatives that could disrupt conventional petroleum-derived supply structures.
Market Dynamics
Waterborne coating maturation in automotive refinishing is compressing solvent demand intensity per unit of paint applied, forcing suppliers to reformulate toward high-flash-point, low-aromatic grades that meet performance thresholds with reduced VOC content.
Growth Catalysts
- EPA Clean Air Act enforcement:Regulatory pressure on VOC emissions accelerates replacement demand for compliant reformulated thinners in industrial coating operations across the United States.
- Edible oil extraction:Food-grade hexane specifications tighten supply discipline, sustaining premium pricing tiers for producers achieving pharmaceutical-grade purity certifications.
- China petrochemical capacity:Domestic refinery expansions in Shandong and Zhejiang provinces reduce import dependency for C6-C9 aliphatic fractions serving regional manufacturing clusters.
Market Restraints
- Crude oil price volatility:Feedstock cost swings directly compress margin structures for hydrotreated naphtha producers lacking integrated refinery positions.
- N-hexane neurotoxicity constraints:OSHA permissible exposure limits below 50 ppm force workplace ventilation investments and product substitution in adhesives manufacturing.
- Bio-based hydrocarbon emergence:Renewable naphtha from pyrolysis oils threatens conventional petroleum-derived solvent positioning in European cosmetics applications.
Strategic Opportunities
- India specialty chemicals:PLI scheme incentives for domestic manufacturing create entry paths for high-purity solvent grades serving pharmaceutical API production.
- Electronics cleaning applications:Semiconductor wafer processing demands ultra-low residue C9-C12 isoparaffins with sub-ppb metal content specifications.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive solvents reward producers with hydrotreater carbon capture integration.
Industry Challenges
- REACH SVHC compliance timelines:ECHA substance of very high concern classifications for certain C10-C13 fractions force 18-month reformulation cycles with uncertain substitution efficacy.
- Specialized hydrotreater engineering:Catalyst replacement intervals and sulfur guard bed maintenance demand technical workforce capabilities scarce outside major refining centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aliphatic Hydrocarbon Solvents and Thinners Market |
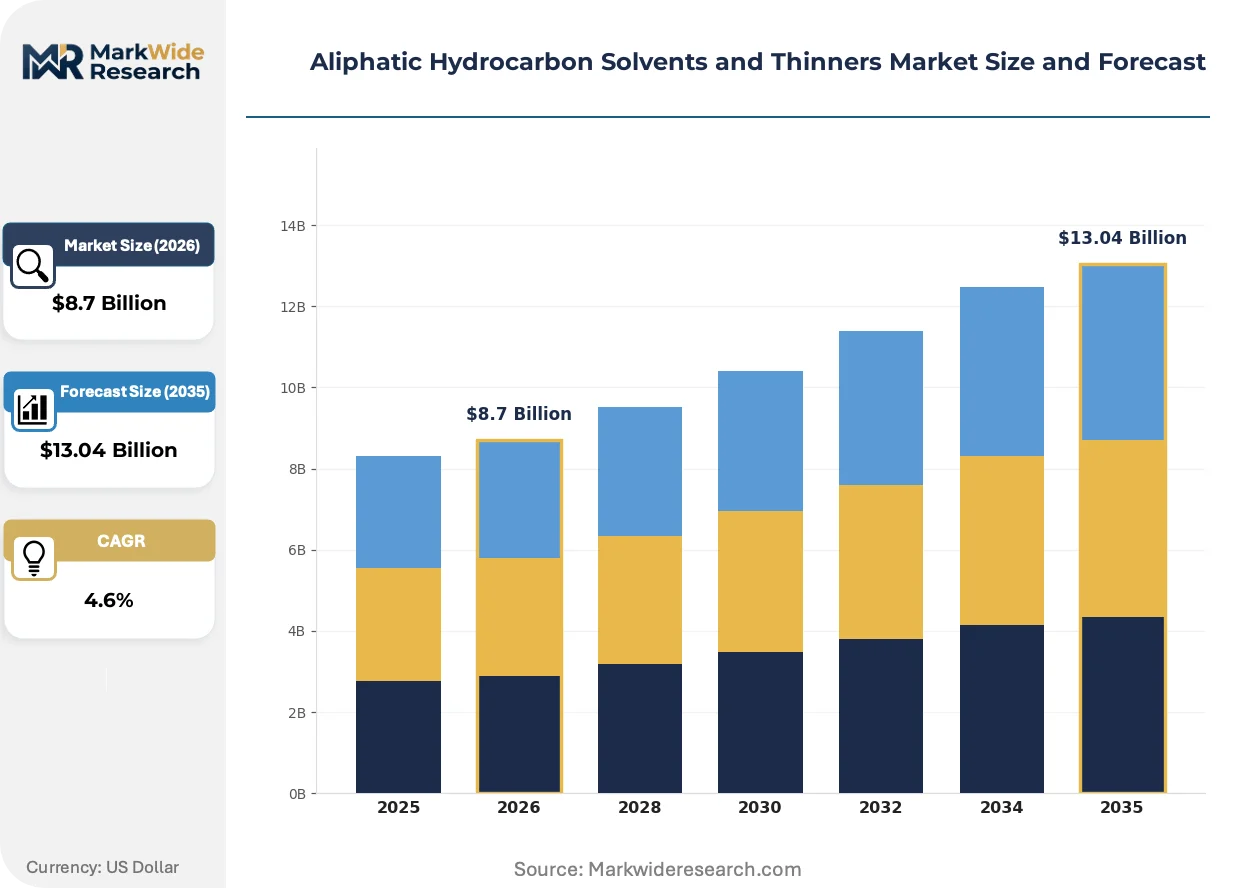
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Spirits, Cyclohexane, Hexane, Kerosene Application: Paint Thinning, Metal Cleaning, Adhesive Solvent, Textile Finishing Grade: Industrial Grade, Commercial Grade, Laboratory Grade, Technical Grade End User: Manufacturing, Automotive, Construction, Healthcare |
| Companies Covered | ExxonMobil Corporation, Shell plc, BASF, Chevron Phillips Chemical Company LLC, TotalEnergies, Phillips 66, Calumet, Inc., SK Geocentric Co., Ltd., INEOS Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aliphatic Hydrocarbon Solvents and Thinners Market Emerging Trajectories
Formulation science is pivoting toward molecular precision—tailoring carbon distribution, aromatic content, and evaporation curves to specific coating cure chemistries rather than selling commodity boiling point cuts.
Membrane separation technology is converging with traditional distillation in solvent recovery systems. Automotive OEM paint shops in Germany and Japan are retrofitting closed-loop cleaning circuits that regenerate mineral spirits on-site. This hybrid approach is converging with sustainability reporting requirements to compress virgin solvent procurement volumes by half in integrated facilities.
REACH authorization procedures for C9-C14 aliphatic hydrocarbons are tightening downstream documentation burdens. Downstream users in adhesives and sealants must now submit chemical safety assessments with every formulation change. Coating manufacturers serving construction applications face the steepest compliance cost escalation, driving consolidation toward larger formulators with dedicated regulatory affairs functions.
Specification-driven procurement is displacing spot-market purchasing for critical solvent grades. Tier-one paint producers in the United States now contract directly with refinery operators for defined C6-C8 isoparaffin fractions, bypassing traditional distributor channels. This direct engagement concentrates in architectural coatings, where batch consistency requirements override price flexibility.
Aliphatic Hydrocarbon Solvents and Thinners Market Segmentation
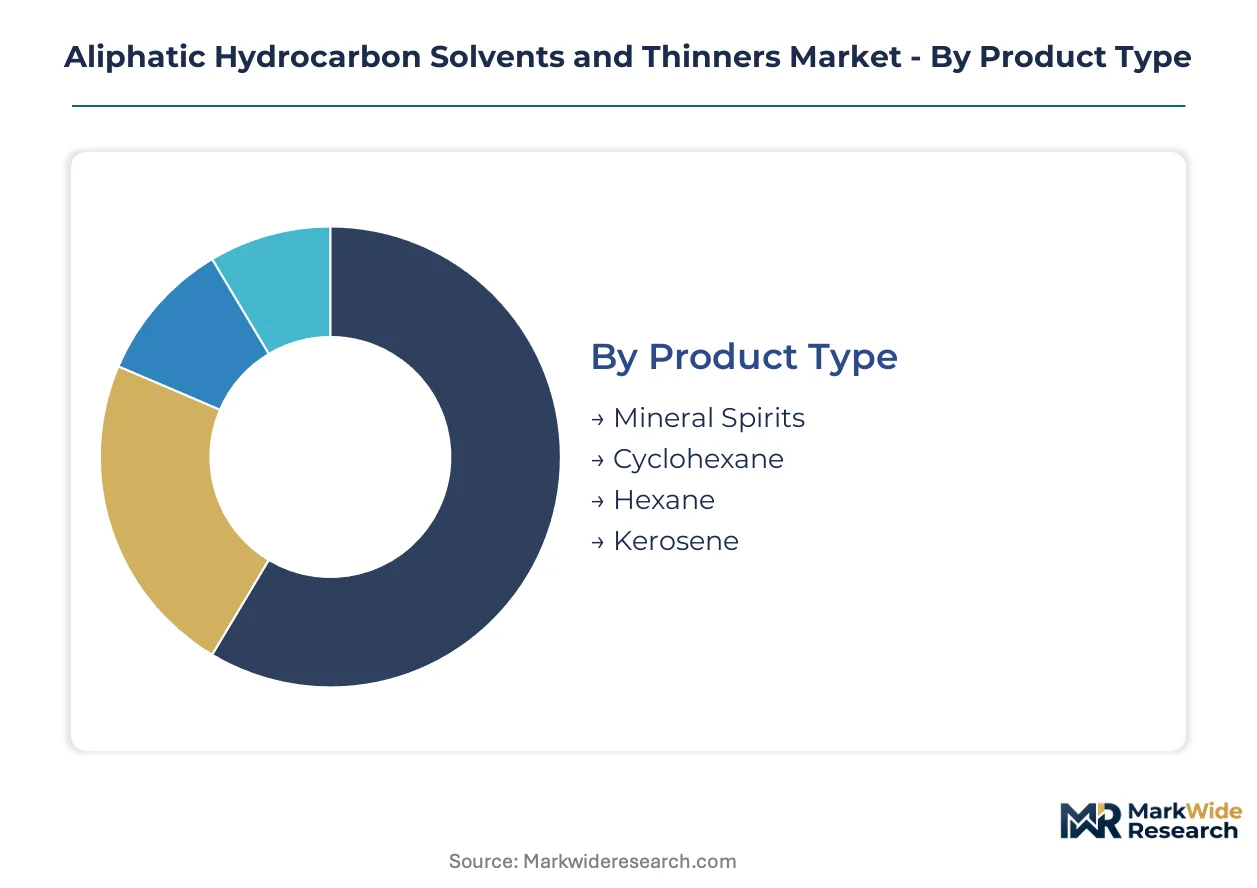
Aliphatic solvent buyers segment procurement by evaporation profile, residue tolerance, and regulatory compliance burden. Specification divergence across end-uses forces suppliers to maintain parallel product lines rather than commoditized bulk offerings.
Product Type:
Buyers differentiate primarily by boiling point range and aromatic content thresholds, which dictate compatibility with specific coating chemistries and extraction processes.
- Mineral Spirits:Hydrotreated petroleum distillate in the C7-C12 range with controlled aromatic content below 25 percent. Paint thinning applications in US automotive refinishing absorb the largest volumes as EPA VOC regulations tighten reformulation requirements.
- Hexane:Straight-chain C6 hydrocarbon produced through selective refinery fractionation and severe hydrotreating. Food-grade specifications for edible oil extraction in China sustain premium pricing tiers above industrial grades.
- Cyclohexane:Saturated cyclic hydrocarbon serving as nylon intermediate feedstock and specialized reaction solvent. Polymerization chemistry demands in Germany and Japan concentrate demand for high-purity grades.
- Kerosene:Higher boiling fraction (C9-C16) with elevated flash point for heavy-duty cleaning and fuel applications. Metal degreasing operations in India leverage kerosene where slower evaporation improves soil suspension.
Mineral Spirits leads volumes today; Hexane is gaining share fastest.
Application:
Application selection tracks surface preparation requirements, coating system chemistry, and residue sensitivity in finished goods.
- Paint Thinning:Dilution of alkyd, acrylic, and epoxy coatings to achieve spray viscosity and flow characteristics. Waterborne technology maturation in automotive OEM shops is compressing solvent demand intensity per unit applied.
- Metal Cleaning:Removal of machining oils, particulates, and oxidation from fabricated components prior to finishing. Precision manufacturing clusters in Japan specify low-residue isoparaffins for electronics substrate preparation.
- Adhesive Solvent:Dissolution of rubber-based and synthetic polymer adhesives for uniform application and controlled open time. OSHA n-hexane exposure limits below 50 ppm are forcing formulation shifts toward cyclohexane alternatives.
- Textile Finishing:Carrier for dye penetration and fabric softening agents in synthetic fiber processing. Zhejiang province mills in China represent concentrated demand for C8-C10 fractions with defined evaporation curves.
Paint Thinning dominates current procurement; Metal Cleaning exhibits the steepest expansion trajectory.
Grade:
Grade stratification reflects purity certification requirements, analytical testing protocols, and documentation burdens downstream.
- Industrial Grade:Standard hydrotreated fractions with basic moisture and particulate specifications. General manufacturing cleaning and dilution applications in India absorb volume through price-sensitive procurement.
- Commercial Grade:Intermediate purity with tighter aromatic limits and color stability metrics. Architectural coating formulators in the United States specify commercial grade for consistent batch-to-batch performance.
- Laboratory Grade:Ultra-high purity with sub-ppm contaminant thresholds and comprehensive Certificate of Analysis documentation. Pharmaceutical API synthesis in Switzerland and analytical chemistry applications command 3-5x pricing premiums.
- Technical Grade:Application-specific formulations with custom evaporation profiles or additive packages. Electronics cleaning in South Korea drives technical grade specifications for semiconductor wafer processing.
Industrial Grade anchors volume shipments; Laboratory Grade climbs the fastest on value terms.
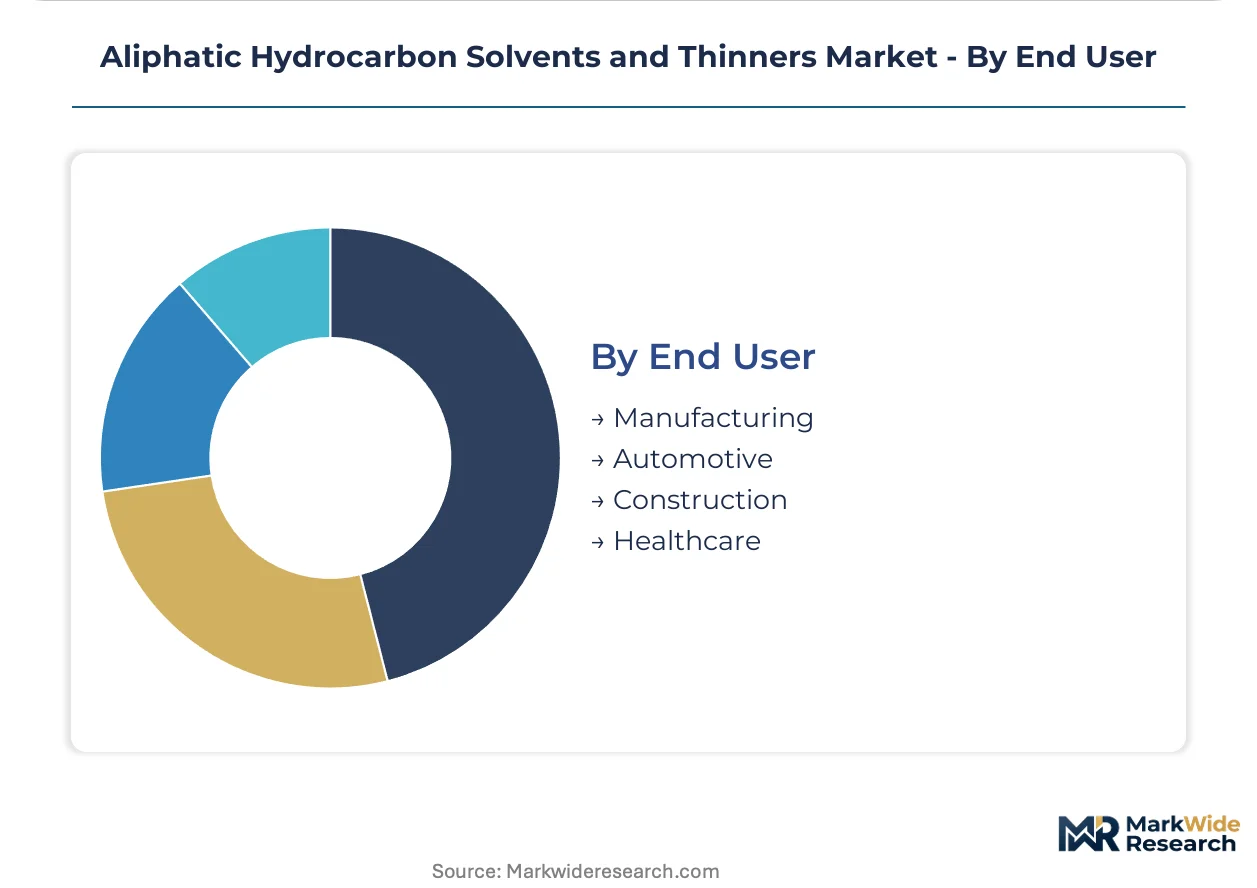
End User:
End user segmentation tracks capital intensity, regulatory exposure, and specification stringency in procurement decision-making.
- Manufacturing:Broad industrial base encompassing metal fabrication, plastics processing, and general equipment maintenance. Shandong province chemical clusters in China concentrate demand for C6-C9 aliphatic fractions.
- Automotive:OEM assembly plants and refinishing operations with exacting surface preparation standards. EPA Clean Air Act enforcement is accelerating compliant reformulated thinner adoption across US production facilities.
- Construction:Field application of architectural coatings, sealants, and waterproofing systems. REACH SVHC documentation burdens in Europe are consolidating procurement toward larger formulators with dedicated regulatory functions.
- Healthcare:Pharmaceutical manufacturing and medical device cleaning with validated sterilization compatibility. FDA process validation requirements for residual solvent testing sustain laboratory grade demand.
Manufacturing leads absolute consumption; Healthcare expands most quickly on specification premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China sustains heavier solvent consumption volumes than the United States, yet German refiners command tighter specification premiums for pharmaceutical-grade outputs. Regulatory divergence across these three markets is fragmenting procurement strategies.
United States
EPA Clean Air Act enforcement accelerates reformulated thinner adoption across automotive refinishing shops. OSHA maintains n-hexane permissible exposure limits below 50 ppm, forcing ventilation investments in Ohio and Michigan adhesive plants. Gulf Coast refinery expansions near Houston expand hydrotreated naphtha availability for downstream chemical processors.
China
Domestic manufacturing growth in Shandong and Zhejiang provinces sustains C6-C9 aliphatic fraction consumption. MEE implements dual carbon goals that tighten emissions standards for solvent recovery systems. Petrochemical clusters in Ningbo and Qingdao reduce import dependency through integrated refinery-chemical complexes serving regional paint manufacturers.
Germany
Automotive OEM paint shops in Stuttgart and Munich retrofit closed-loop mineral spirits regeneration circuits. ECHA REACH authorization procedures for C9-C14 fractions impose 18-month reformulation timelines on adhesives formulators. BASF's Ludwigshafen complex anchors high-purity solvent production for European pharmaceutical API synthesis.
India
PLI scheme incentives for domestic specialty chemicals manufacturing create entry paths for laboratory-grade solvent suppliers. BIS certification requirements tighten import documentation for C5-C12 hydrocarbon thinners. Maharashtra chemical clusters near Mumbai concentrate metal cleaning applications for precision engineering subcontractors.
Japan
Semiconductor wafer processing in Kyushu demands ultra-low residue C9-C12 isoparaffins with sub-ppb metal content. METI promotes carbon neutrality targets that accelerate solvent recovery technology adoption. Nagoya-area automotive coating facilities specify technical grade thinners for consistent batch-to-batch performance.
Aliphatic Hydrocarbon Solvents and Thinners Market Vendor Landscape
US Gulf Coast producers anchor one tier; European and Asian specialists hold differentiated positions in high-purity and electronics-grade segments. The vendor base concentrates around integrated refinery operators and standalone hydrotreater facilities. Three archetypes dominate: integrated petrochemical majors, regional refinery operators, and specialty purity specialists. Capacity expansion and direct contracting with end-users represent the dominant competitive moves reshaping distribution channels.
Within the integrated major tier, ExxonMobil Corporation and Shell plc exemplify geographic diversification across refining and chemical complexes. BASF occupies a position representing the specialty purity archetype, with laboratory-grade certifications commanding substantial pricing premiums. SK Geocentric Co., Ltd. anchors the Asian specialist segment. Chevron Phillips Chemical Company LLC and TotalEnergies sit within the scale-driven refinery operator category, while Calumet, Inc. and Phillips 66 represent North American independent refining positions. INEOS Group Limited exemplifies European chemical platform integration.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| BASF |
| Chevron Phillips Chemical Company LLC |
| TotalEnergies |
| Phillips 66 |
| Calumet, Inc. |
| SK Geocentric Co., Ltd. |
| INEOS Group Limited |
| Others |
Supply Flow & Price Mechanics
Captive refinery-chemical complex integration across the US Gulf Coast and China's Shandong province anchors both supply security and pricing power for hydrotreated naphtha producers. This upstream control over C5-C12 feedstock streams insulates integrated operators from crude volatility while forcing standalone hydrotreater facilities into spot-market procurement vulnerability.
Pricing Analysis
Capacity additions in China's Ningbo and Qingdao petrochemical corridors are reshaping price floors for C6-C9 aliphatic fractions. Contract-based long-term offtake dominates procurement between integrated majors and tier-one coating formulators, with price differentiation hinging on pharmaceutical-grade purity certifications and ISO-documented batch consistency. Cost compression in industrial-grade mineral spirits is intensifying because Shandong's refinery expansions flood regional spot markets. General manufacturing buyers in India exhibit the highest price sensitivity, while semiconductor wafer processors in Japan accept substantial premiums for sub-ppb metal content specifications.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore orchestrate hub-and-spoke patterns for solvent thinners moving into coating and extraction applications. Geographic supply concentration centers on the United States, China, and Germany, with hydrotreater output feeding from crude oil distillation units, sulfur guard bed catalysts, and specialized membrane separation modules. Tariff exposure on European imports of C9-C14 fractions under EU carbon border adjustments threatens margin structures for non-integrated Asian exporters. Distribution runs through direct refinery-to-formulator contracting for high-specification grades, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with specification premiums widening as pharmaceutical and electronics applications displace commodity paint-thinning volumes. Buyers now prioritize documented purity over spot-price flexibility.
For Market Incumbents: Cement laboratory-grade certification pipelines through hydrotreater carbon capture integration, defending against bio-based hydrocarbon substitutes penetrating European cosmetics channels. Prioritize backward integration into refinery naphtha streams where Gulf Coast capacity expansions offer feedstock cost anchors. For New Entrants and Emerging Players: Membrane separation technology for on-site solvent regeneration presents a technology-first wedge into automotive OEM paint shops facing EPA VOC compliance deadlines. Target India's PLI-backed specialty chemicals corridor with technical grade offerings for pharmaceutical API synthesis, leveraging BIS certification gaps that slow multinational entry. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH SVHC documentation burdens exceed smaller formulators' regulatory affairs capacity. Five-to-ten year viability favors integrated refinery operators with captive hydrotreater assets over standalone solvent processors. Watch for ECHA authorization timeline delays as the signal indicating premium capture opportunities for pre-compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Naphtha | ExxonMobil's integrated complexes secure feedstock cost advantages against standalone hydrotreaters. |
| Hydrotreater Carbon Capture Installation | EU Green Deal border adjustments reward low-carbon solvent production with tariff exemptions. |
| Laboratory Grade Certification Investment | BASF's Ludwigshafen facility commands 3-5x pricing premiums for pharmaceutical API applications. |
| Membrane Separation Technology Deployment | German automotive OEM shops halve virgin solvent procurement through closed-loop regeneration circuits. |
| Direct Refinery-to-Formulator Contracting | US architectural coating producers bypass distributors for defined C6-C8 isoparaffin batch consistency. |
Methodological Framework
Coverage spans the United States, China, Germany, India, and Japan, with primary inputs from each market through structured interviews with refinery operations managers, downstream coating formulator procurement leads, pharmaceutical QA directors, and specialty chemical distribution channel partners. Secondary validation draws from EPA enforcement databases, ECHA REACH registration filings, ACC solvent trade statistics, and SEC 10-K disclosures from integrated petrochemical majors. Bottom-up volume modeling triangulates against top-down industry association aggregates.
Granularity extends to grade tier, end-use industry, and regional production hub for value projections across the analysis window. CAGRs derive from segment-level growth rate blending weighted by current procurement volumes. Forecast inputs incorporate MEE dual carbon goal implementation timelines and FDA process validation requirements for residual solvent testing.
The model holds under stable crude oil price corridors and steady regulatory enforcement intensity; deviation in ECHA SVHC reclassification timing or bio-based hydrocarbon cost parity would shift specification premium capture trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Asia-Pacific Ethane Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Green Solvents Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Decanol Market
Solvents
Solvent Cement Market
Solvents
2-Phenylethanol Market
Solvents
Global Droppers Market
Solvents
Dibutyl Ether Market
Solvents
Electronic Cleaning Solvents Market
Solvents
Global Solvent Evaporation Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
Methyl Acetate Market