
 Oman Paints and Coatings Market | 2026-2036
Oman Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Paints and Coatings Market Analytics
ISO 12944 corrosion-protection certification is bifurcating the competitive landscape between qualified system suppliers and commodity traders. Jotun A/S leverages its marine and protective coatings pedigree to dominate industrial infrastructure bids across Port of Duqm expansions. Hempel A/S anchors its position through deep supply relationships with oil and gas maintenance contractors in the Sultanate. Gulf Paints competes on shorter lead times and localized tinting services for residential and commercial applicators in Muscat.
Paints and coatings constitute formulated liquid, paste, or powder systems comprising binders, pigments, extenders, solvents or water carriers, and functional additives that cure into adherent protective or decorative films; their primary purpose spans substrate protection against corrosion, UV degradation, and chemical attack alongside aesthetic finishing of built structures and manufactured goods. Architectural coatings occupies the largest value share given sustained housing stock growth and retail renovation cycles across Omani urban centers. Industrial coatings registers the fastest expansion trajectory, propelled by petrochemical facility maintenance schedules and desalination plant investments. Water-based technology segments are gaining formulation share as contractor preferences shift toward lower workplace hazard profiles and faster re-coat intervals.
Oman's Ministry of Commerce, Industry and Investment Promotion and the Gulf Standardization Organization collectively enforce VOC content ceilings and product labeling requirements that restrict solvent-heavy imports while privileging compliant domestic blenders. The national building code administered by the Ministry of Housing and Urban Planning mandates specific coating performance grades for coastal and high-humidity zones, directly shaping specification behavior among project consultants. Stakeholders must monitor how forthcoming GSO harmonization protocols and Oman Vision 2040 infrastructure commitments recalibrate the balance between import dependency and localized manufacturing scale-up.
Market Dynamics
ISO 12944 corrosion-protection certification is fragmenting competitive positioning between qualified system suppliers and commodity traders across Oman's industrial infrastructure pipeline. The bifurcation accelerates as Port of Duqm expansions and petrochemical maintenance schedules demand validated coating systems.
Growth Catalysts
- Duqm Special Economic Zone infrastructure:Megaproject construction creates concentrated demand pull for protective industrial coatings in marine and heavy industrial applications.
- Gulf Standardization Organization VOC harmonization:Low-VOC formulation mandates privilege compliant domestic blenders over solvent-heavy imports.
- Water-based technology substitution:Contractor preferences shift toward reduced workplace hazard profiles and faster re-coat intervals in residential and commercial applications.
Market Restraints
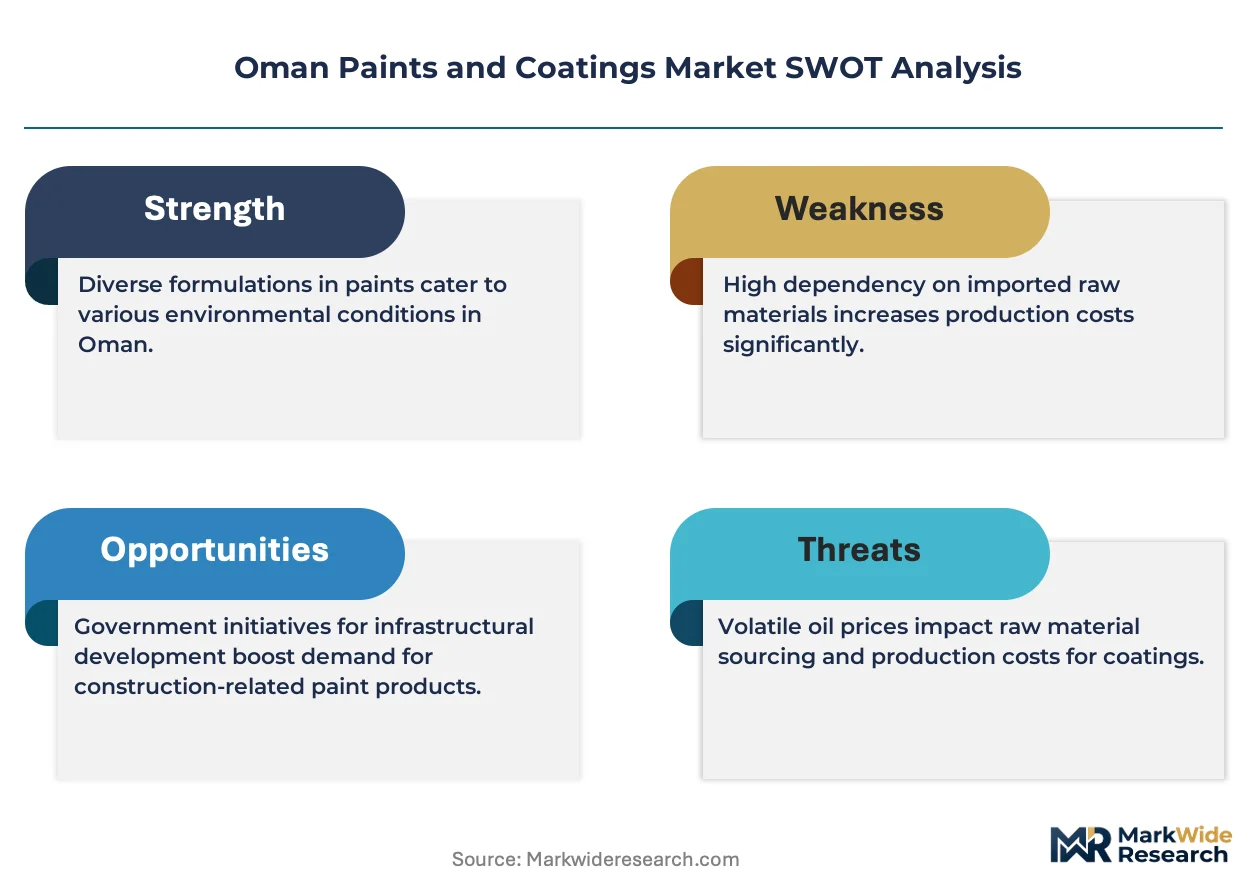
- Petrochemical feedstock volatility:Epoxy resin and titanium dioxide input costs fluctuate with global crude pricing, compressing blender margins.
- Import dependency concentration:Specialty additives and high-performance binders originate primarily from European and Asian manufacturing bases.
- Coastal zone performance limitations:Standard acrylic formulations degrade prematurely in high-salinity, high-humidity conditions along Oman's Arabian Sea coastline.
Strategic Opportunities
- Dhofar Governorate residential construction:Salalah and surrounding urban centers exhibit underpenetrated coating consumption relative to Muscat and Seeb.
- Desalination plant investments:Reverse osmosis and thermal distillation facilities require specialized anti-corrosion and anti-fouling coating systems.
- Oman Vision 2040 localization incentives:Domestic manufacturing scale-up subsidies reduce import dependency for standard architectural formulations.
Industry Challenges
- ISO 12944 certification timeline compression:Laboratory testing and field validation cycles extend bid qualification periods for infrastructure tenders.
- Tinting equipment capex requirements:Automated color-matching systems demand substantial upfront investment for localized service capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Paints and Coatings Market |
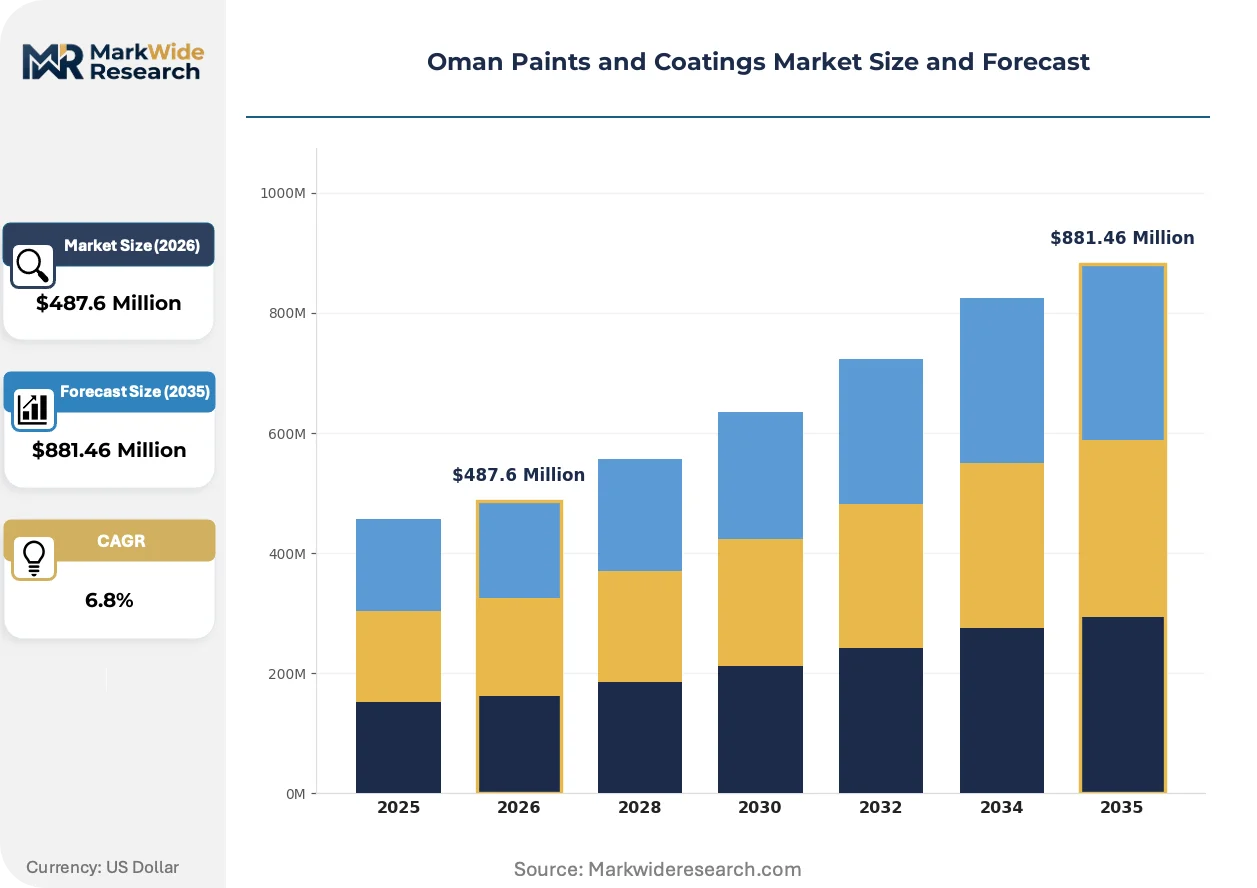
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Coatings, Industrial Coatings, Specialty Coatings, Automotive Coatings Application: Residential, Commercial, Industrial, Infrastructure Technology: Water-based, Solvent-based, Powder Coatings, UV-cured End User: OEMs, Contractors, Retailers, Distributors |
| Companies Covered | Hempel A/S, Gulf Paints, Jotun A/S, Asian Paints Berger, Al Jazeera Paints, AkzoNobel N.V., Oasis Paints, Khimji Paints, National Paints Factories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Paints and Coatings Market Evolving Landscape
Formulation chemistry and certification protocols are actively reshaping supplier positioning across Oman's coating value chain. Technology trajectories favor water-based and high-solids systems while regulatory pressure accelerates compliance investments.
Nano-engineered corrosion inhibitors are fragmenting traditional barrier-protection approaches in industrial maintenance applications. Oil and gas contractors in the Sultanate adopt these additives for extended asset-life projections. The technology compresses specification windows for conventional zinc-rich primers in offshore and coastal infrastructure.
Gulf Standardization Organization VOC content ceilings and product labeling requirements are restricting solvent-heavy imports while privileging compliant domestic blenders. The Ministry of Commerce, Industry and Investment Promotion enforcement actions reshape import licensing patterns. Architectural coating segments respond fastest through reformulation partnerships with regional chemical distributors.
Specification consultants increasingly mandate certified coating systems over commodity alternatives in public infrastructure tenders. Project engineering firms in Muscat and Duqm consolidate procurement around pre-qualified supplier lists. The pattern concentrates most visibly in marine and protective coating categories for port and industrial zone developments.
Oman Paints and Coatings Market Segmentation
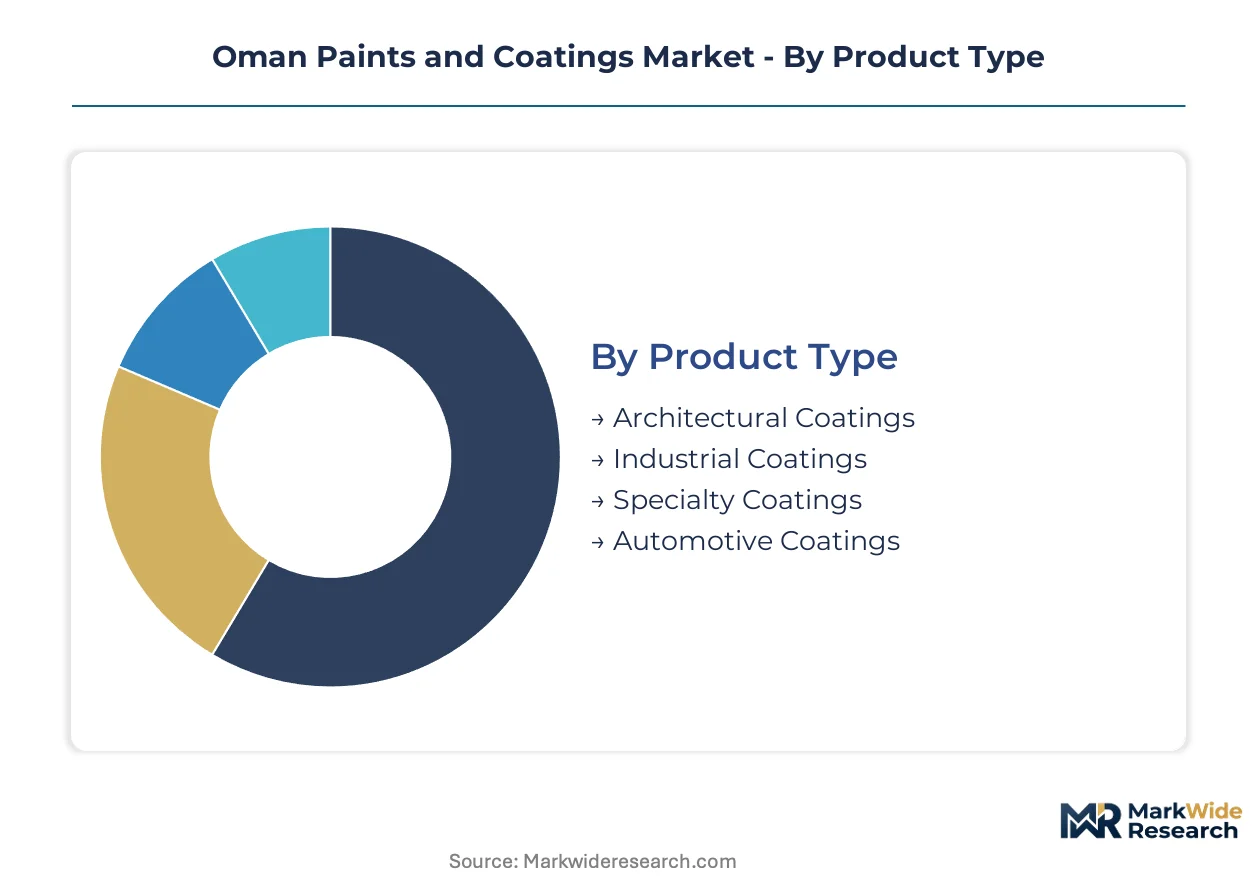
Segmentation reveals how coating demand fragments across Oman's construction and industrial economy. Distinct specification behaviors, margin structures, and regulatory pressures operate within each category.
Product Type:
Margin pools concentrate in industrial formulations where ISO 12944 certification creates pricing power, while architectural volumes dominate absolute revenue.
- Architectural Coatings:Acrylic, alkyd, and emulsion-based systems formulated for decorative and protective finishing of buildings. Demand concentrates in residential construction clusters across Seeb and Salalah, driven by Ministry of Housing and Urban Planning mandates for coastal zone performance grades.
- Industrial Coatings:Epoxy, polyurethane, and zinc-rich systems engineered for corrosion protection in heavy infrastructure and petrochemical assets. Port of Duqm expansions and oil field maintenance schedules pull demand toward qualified system suppliers with laboratory-validated specifications.
- Specialty Coatings:High-performance formulations for extreme environments including tank linings and fire protection.
- Automotive Coatings:OEM refinish and collision repair systems serving dealership networks and independent body shops.
The dominant share belongs to Architectural Coatings, while Industrial Coatings is closing the gap fastest.
Application:
Contractor procurement patterns vary sharply by project type, with infrastructure tenders demanding certified systems and residential work favoring localized service.
- Residential:Interior and exterior decorative coatings applied to housing stock across Oman's urban centers. Salalah and surrounding Dhofar Governorate zones exhibit underpenetrated consumption relative to Muscat, with tinting services and shorter lead times driving contractor loyalty.
- Commercial:Retail, office, and hospitality finishing systems subject to faster renovation cycles. Muscat's retail expansion creates recurring demand for re-coat intervals and aesthetic refresh specifications.
- Industrial:Manufacturing facility and warehouse protective coatings exposed to chemical and mechanical wear.
- Infrastructure:Bridges, ports, and public works requiring extended asset-life warranties and field-validated performance.
Residential applications command the largest volume position, though Infrastructure is expanding most quickly on Duqm megaproject commitments.
Technology:
Formulation chemistry determines regulatory compliance trajectory and workplace hazard profiles across contractor segments.
- Water-based:Acrylic and polyurethane dispersions using water as primary carrier, emitting minimal VOC during application. Contractor preferences in residential and commercial segments shift toward these systems for faster re-coat intervals and reduced workplace exposure.
- Solvent-based:Traditional alkyd and epoxy systems delivering superior adhesion in high-humidity coastal conditions. Gulf Standardization Organization VOC ceilings restrict import volumes while privileging compliant domestic blenders with reformulation capabilities.
- Powder Coatings:Thermoset and thermoplastic dry films applied electrostatically to metal substrates.
- UV-cured:Rapid-curing systems activated by ultraviolet exposure for specialized industrial finishing.
Water-based technology holds the volume lead, while Powder Coatings is gaining share fastest on industrial automation investments.
End User:
Purchasing authority and specification influence fragment across the value chain, determining pricing power and service requirements.
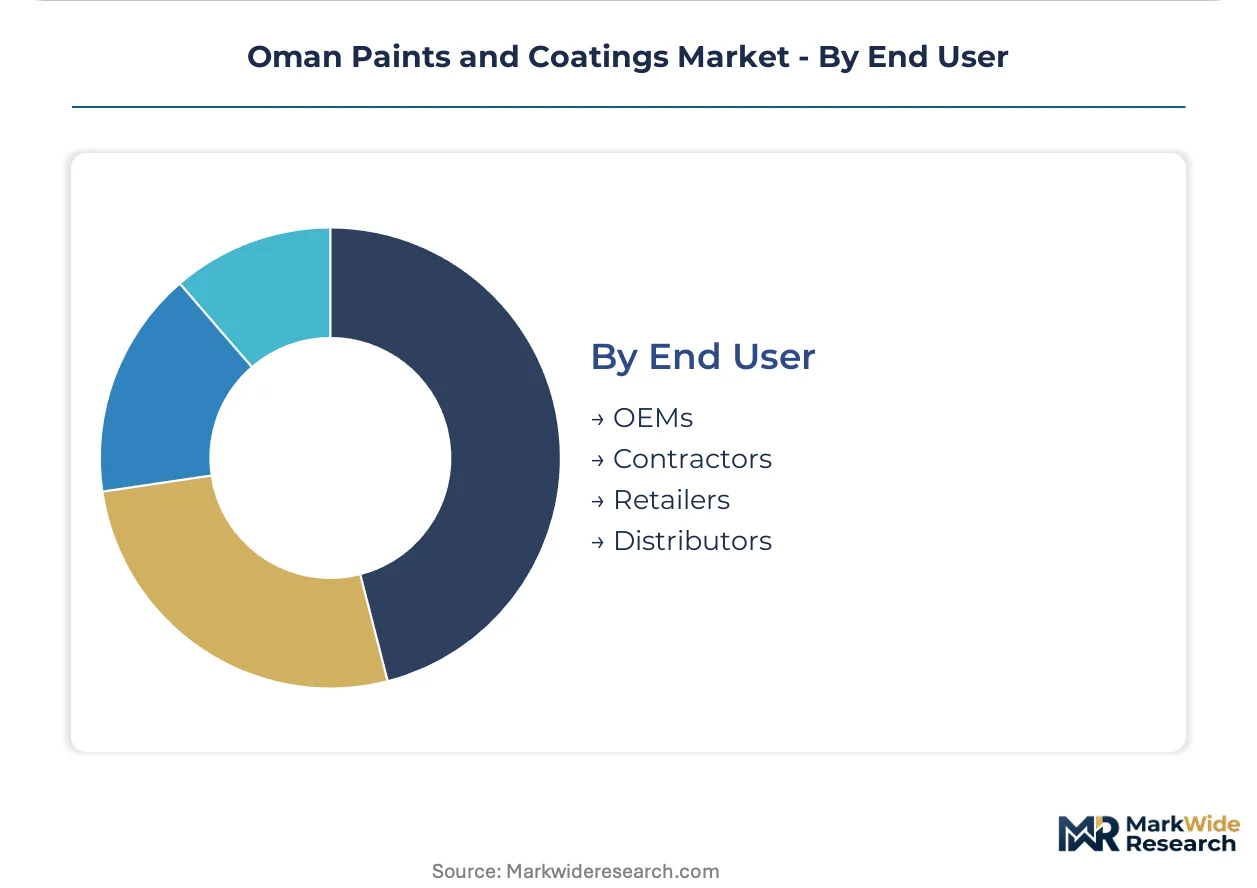
- OEMs:Original equipment manufacturers integrating coatings into manufactured products at the factory level.
- Contractors:Application professionals executing on-site finishing work across residential, commercial, and industrial projects. Seeb and Salalah residential contractors represent the most concentrated demand pull, with localized tinting capabilities and technical support driving supplier selection.
- Retailers:Hardware and paint stores serving DIY consumers and small professional accounts.
- Distributors:Wholesale channels stocking bulk formulations for project-based procurement.
Contractors control the dominant procurement volume, while OEMs are climbing the fastest on industrial manufacturing scale-up under Oman Vision 2040.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oman Vision 2040 infrastructure commitments and GSO harmonization protocols are redistributing coating demand across the Sultanate's economic zones. Sub-regional specialization is emerging as contractors and blenders align with distinct project pipelines and regulatory enforcement patterns.
Muscat Governorate
Residential construction clusters in Seeb and Al Amerat sustain architectural coating volumes through retail renovation cycles and housing stock expansion. The Ministry of Housing and Urban Planning enforces coastal zone performance grades that privilege compliant domestic blenders. Port Sultan Qaboos maintenance schedules and commercial retail developments concentrate procurement among contractors demanding localized tinting services.
Al Wusta Governorate
Duqm Special Economic Zone megaprojects generate concentrated demand for marine and protective industrial coatings across port expansions and heavy industrial facilities. ISO 12944 certification requirements filter supplier participation toward qualified system suppliers with laboratory-validated specifications. Oil and gas maintenance contractors operating from Duqm anchor procurement relationships with epoxy and polyurethane formulators.
Dhofar Governorate
Salalah and surrounding urban centers exhibit underpenetrated coating consumption relative to Muscat, with residential construction accelerating on Vision 2040 decentralization incentives. The Ministry of Commerce, Industry and Investment Promotion extends low-VOC formulation mandates that reshape import licensing for solvent-heavy products. Salalah Port free zone developments and tourism infrastructure projects pull specialized anti-corrosion systems toward qualified applicators.
Al Batinah South Governorate
Industrial manufacturing scale-up under localization subsidies drives OEM coating demand for fabricated metal goods and construction materials. Water-based technology substitution accelerates as contractors prioritize reduced workplace hazard profiles in high-temperature climates. Sohar Port and Freezone petrochemical maintenance schedules sustain recurring demand for zinc-rich primers and high-solids systems.
Ad Dakhiliyah Governorate
Inland residential and commercial construction operates with less stringent coastal performance requirements, permitting broader formulation flexibility among regional distributors. GSO VOC harmonization protocols still restrict solvent-heavy imports, privileging compliant blenders with reformulation partnerships. Nizwa's retail and hospitality expansion creates recurring demand for decorative finishing systems with faster re-coat intervals.
Oman Paints and Coatings Market Competitive Landscape
Player mix skews toward multinational specialists with ISO 12944 certification capabilities and regional blenders competing on service proximity. Market structure bifurcates between qualified system suppliers commanding industrial infrastructure bids and commodity traders serving price-sensitive residential segments. Two strategic archetypes dominate: marine-protective specialists leveraging laboratory validation and localized blenders optimizing tinting response times. Competitive moves concentrate on certification timeline acceleration and automated color-matching capacity deployment.
Within the multinational specialist tier, Jotun A/S and Hempel A/S occupy positions anchored by marine and protective coatings pedigrees. Gulf Paints exemplifies the regional blender archetype competing on shorter lead times and localized service capabilities. AkzoNobel N.V. sits within the diversified multinational category with broad formulation portfolios spanning architectural and industrial segments.
| Leading Market Players |
|---|
| Hempel A/S |
| Gulf Paints |
| Jotun A/S |
| Asian Paints Berger |
| Al Jazeera Paints |
| AkzoNobel N.V. |
| Oasis Paints |
| Khimji Paints |
| National Paints Factories |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Oman's domestic blending facilities shapes both supply concentration and price floors for architectural formulations. Scale advantages among Muscat-based producers compress margins for smaller regional competitors while reinforcing tiered pricing power across certified industrial grades.
Pricing Analysis
Certification level (ISO 12944-grade) creates the primary spread between qualified system suppliers and commodity traders. Project-based pricing dominates infrastructure tenders, with ISO-validated formulations commanding premiums over standard architectural coatings. Cost compression in commodity architectural tiers intensifies because of titanium dioxide and epoxy resin volatility. Residential contractors in Seeb and Salalah exhibit highest price sensitivity, while oil and gas maintenance procurement demonstrates lowest sensitivity due to warranty requirements.
Supply Chain Analysis
Port congestion at Jebel Ali and Salalah Port elevates inbound logistics costs for specialty additives and high-performance binders. Raw material sourcing draws from Germany, South Korea, and India for corrosion inhibitors and polyurethane dispersions. Single-source vulnerability concentrates in European-sourced zinc-rich primer formulations. Distribution runs through project-based wholesale channels serving infrastructure contractors and retail hardware networks for residential applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tinting services and technical support contracts represent a service-attach opportunity expanding faster than base coating volumes. Recurring revenue from color-matching subscriptions and applicator training programs outpaces hardware growth across Oman's contractor base.
For Market Incumbents: Consolidate laboratory validation capabilities to defend ISO 12944 certification advantages against emerging regional blenders. Deepen backward integration into water-based resin production to offset petrochemical feedstock volatility. Channel control through exclusive distributor arrangements in Dhofar Governorate reinforces pricing power in underpenetrated zones.
For New Entrants and Emerging Players: Anchor in Salalah's residential construction acceleration, where localized tinting response times lag Muscat service levels. Target desalination plant maintenance schedules requiring specialized anti-fouling formulations. Partner with Oman Vision 2040 localization subsidy programs to bypass import licensing barriers for solvent-heavy products.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic blenders with water-based reformulation partnerships and GSO compliance infrastructure. Five-to-ten year viability hinges on capturing Dhofar Governorate residential expansion and industrial maintenance contract consolidation. Monitor Gulf Standardization Organization harmonization announcements as inflection indicators for import licensing restriction intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 12944 Certification Investment | Laboratory validation capabilities unlock Port of Duqm infrastructure tenders and petrochemical maintenance contracts. |
| Water-Based Reformulation Partnership | GSO VOC compliance privileges domestic blenders over solvent-heavy imports in architectural segments. |
| Automated Tinting System Deployment | Color-matching capacity in Salalah and Seeb shortens lead times for residential contractor loyalty. |
| Backward Integration into Resin Production | In-house epoxy and acrylic dispersion manufacturing buffers margin compression from crude-linked feedstock costs. |
| Dhofar Distribution Network Expansion | Underpenetrated consumption in Salalah residential clusters offers first-mover advantage before infrastructure maturity. |
Research Methodology
Initial hypotheses were tested against primary input from coating plant managers, procurement leads at EPC contractors, distribution channel partners, and technical R&D directors at domestic blenders and refined through secondary validation. Customs and trade data from Oman's National Centre for Statistics and Information, SEC filings from multinational suppliers, Gulf Standardization Organization technical regulations, and Ministry of Commerce enforcement records anchored bottom-up and top-down triangulation across volume and value estimates.
Variance decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled encompass product type (architectural, industrial, specialty), application (residential, commercial, infrastructure), technology (water-based, solvent-based, powder), and end-user procurement authority. CAGRs derived from elasticity-adjusted demand curves incorporating Duqm megaproject commitments, desalination investment pipelines, and housing stock expansion trajectories.
Underlying assumptions cover GSO harmonization implementation timelines, Oman Vision 2040 infrastructure disbursement schedules, and petrochemical feedstock price band stability, with deviation risk concentrated in regulatory enforcement intensity and import licensing restriction scope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Paint Sprayer Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
ASEAN Paints and Coatings Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Water Color Market
Paints & Coatings
Global Primer Market