
 Europe Paints and Coatings Market | 2026-2036
Europe Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Paints and Coatings Market Foresight
The premium-commodity split in Europe's paints and coatings sector is recalibrating around sustainability credentials and performance guarantees versus cost-per-liter procurement. Akzo Nobel NV leverages its decorative coatings heritage to dominate specification channels among continental European architects. BASF SE anchors industrial demand through captive resin supply and automotive OEM relationships. Jotun A/S specializes in marine and protective segments where Nordic technical standards create defensible margin pools.
Paints and coatings are liquid or powder formulations comprising binders, pigments, solvents or water carriers, and functional additives that cure to form adherent protective or decorative films on substrates. The primary purpose spans corrosion prevention, surface aesthetics, chemical resistance, and substrate longevity across metal, wood, masonry, and composite materials. Waterborne technology leads volume in architectural applications as contractors face tightening VOC limits under EU directives. Powder coatings represent the fastest-expanding industrial technology where metal fabricators eliminate solvent handling entirely. Protective coatings command premium pricing in offshore energy and infrastructure where failure costs dwarf material expenditure.
REACH registration requirements and the EU Green Deal carbon-border adjustments are forcing reformulation investments across solventborne product lines. ECHA substance restrictions on titanium dioxide classification and microplastic additives are reshaping pigment and thickener selection for manufacturers serving European end users. EMA and national building codes in Germany, France, and Italy layer additional performance certification demands that fragment compliance burdens. Stakeholders must monitor how the F-Gas Regulation's phase-down affects polyurethane coating supply chains and whether national green public procurement rules harden into mandatory bio-content thresholds.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are forcing wholesale reformulation of solventborne product lines across European manufacturing facilities, redirecting capital toward bio-based binder development and waterborne production infrastructure.
Growth Catalysts
- Urban refurbishment cycles:Western European cities face aging building stock requiring protective and decorative recoating, particularly in Germany and France where residential renovation rates exceed new construction.
- ECHA substance restrictions:Regulatory pressure on titanium dioxide classification and microplastic additives is accelerating substitution investments that open market share for compliant early movers.
- Offshore energy expansion:North Sea wind infrastructure and subsea cabling projects generate demand for high-performance protective coatings with extended service intervals.
Market Restraints
- Petrochemical feedstock volatility:Epoxy and polyurethane resin costs fluctuate with crude oil and natural gas derivatives, compressing margin predictability for formulated products.
- Titanium dioxide supply concentration:Pigment production clusters in China create European import dependency and price transmission lag during supply disruptions.
- F-Gas Regulation phase-down:Blowing agent restrictions for polyurethane coatings limit insulation-performance formulations without qualified alternatives.
Strategic Opportunities
- Eastern European construction acceleration:Poland and Romania exhibit underpenetrated specification-grade coatings demand as building codes converge with Western standards.
- Green public procurement mandates:National bio-content thresholds in Germany and France create preferential purchasing channels for certified sustainable formulations.
- Powder coating-metal fabrication convergence:Automotive and appliance OEMs eliminate solvent handling through integrated electrostatic application lines.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in bio-based binder synthesis and VOC-compliant solvent systems commands premium compensation and extended recruitment timelines.
- Multi-jurisdiction certification complexity:EMA building codes, national fire ratings, and CE marking requirements fragment product registration burdens across EU member states.
- Legacy equipment retrofit costs:Waterborne and powder coating transitions require spray booth reconfiguration and drying system upgrades at contractor and fabricator facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Paints and Coatings Market |
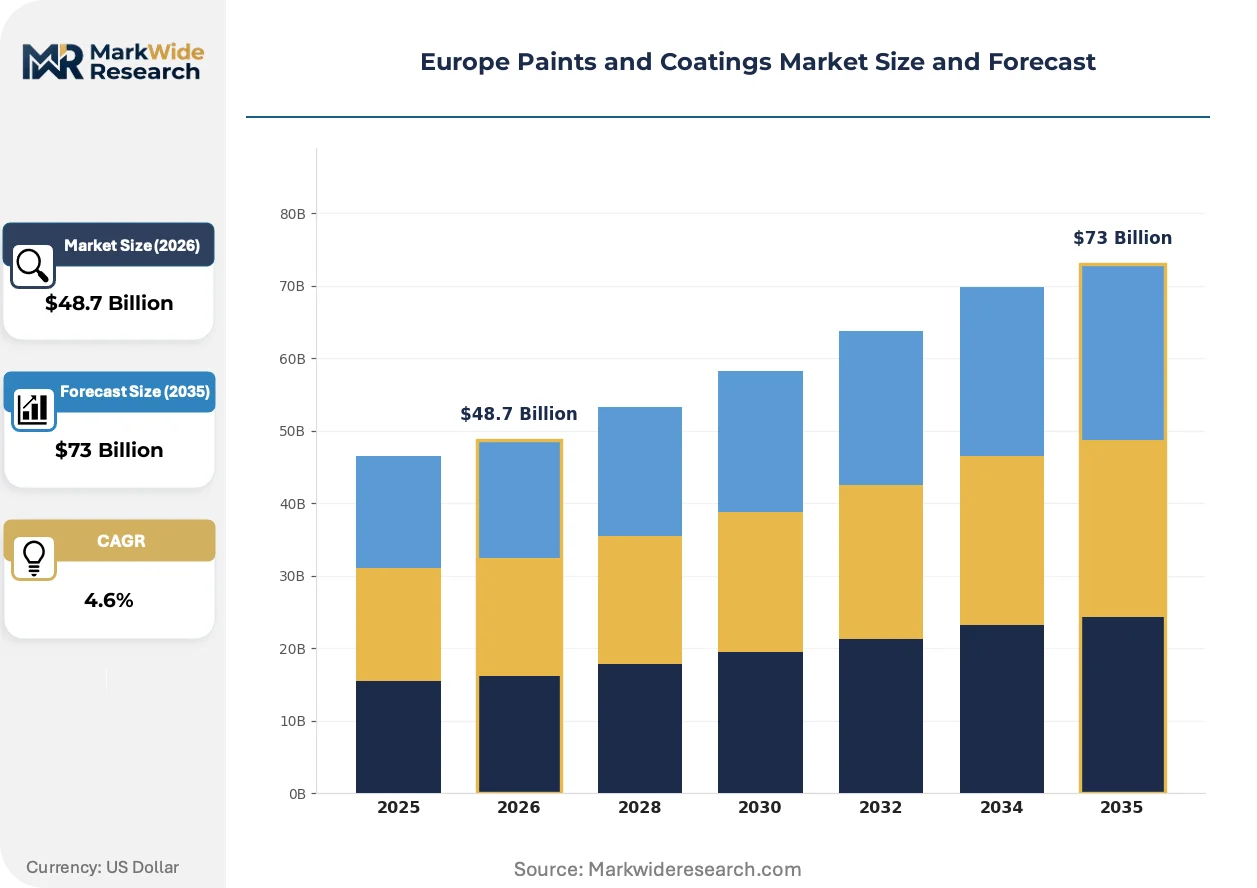
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Coatings, Industrial Coatings, Automotive Coatings, Protective Coatings, Marine Coatings, Powder Coatings Technology: Waterborne, Solventborne, UV Curable, Powder, High-Solid, Epoxy Application: Building & Construction, Transportation Equipment, Consumer Goods, Aerospace Components, Metal Fabrication, Packaging End User: Manufacturers, Aftermarket Providers, Construction Contractors, OEMs, Marine Engineers, Metal Processors |
| Companies Covered | Akzo Nobel NV, PPG Industries, Inc., The Sherwin-Williams Company, BASF SE, Jotun A/S, Axalta Coating Systems, Hempel A/S, RPM International Inc., Sika AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Paints and Coatings Market Shifts & Advancements
Formulation science and application technology are converging around elimination of hazardous substance exposure, with regulatory compliance now serving as the primary innovation vector rather than secondary constraint.
Bio-based alkyd and acrylic binders derived from agricultural waste streams and plant oils are expanding into architectural maintenance coatings. Municipal housing authorities and commercial property managers in the Netherlands and Scandinavia specify these materials for interior applications where occupant exposure duration is highest. This expansion is compressing the cost premium against petroleum-derived equivalents as production scales and feedstock logistics mature.
REACH registration requirements and the EU Green Deal carbon-border adjustment mechanism are restructuring raw material sourcing decisions. Chemical manufacturers face documentation burdens for imported intermediates that previously entered duty-free, redirecting procurement toward European resin producers with verified supply chain emissions data. Industrial coatings segments with complex multi-origin formulations are most affected, accelerating backward integration into captive resin production.
Specification decisions among German and French construction contractors now prioritize certified environmental product declarations and health performance labels over cost-per-liter metrics. Distributors respond by unbundling technical advisory services from material supply, charging separately for color matching, substrate assessment, and warranty documentation. This behavioral shift concentrates purchasing power among specification-influencing architects and facility managers rather than price-focused procurement departments.
Europe Paints and Coatings Market Segmentation
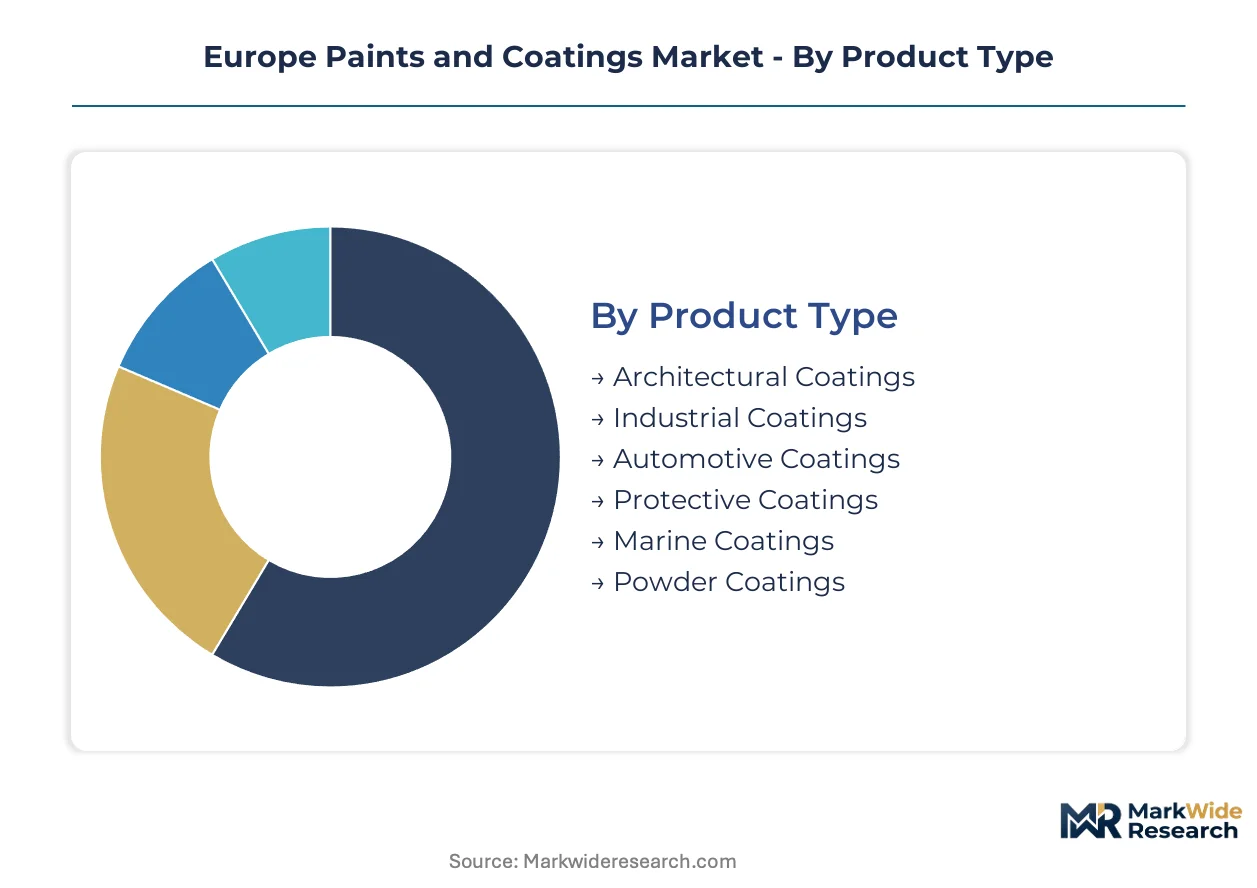
Segmentation in the Europe Paints and Coatings Market reveals how capital deployment, regulatory compliance burdens, and end-use specifications fragment competitive positioning across distinct technology and customer clusters. Understanding these divides exposes where formulation investments yield margin protection versus commodity exposure.
Product Type:
Capital intensity varies sharply across product categories, with industrial-scale resin synthesis and marine certification infrastructure demanding the heaviest upfront commitment.
- Architectural Coatings:Waterborne acrylic and alkyd formulations dominate residential and commercial building stock renovation across Germany and France. Demand concentrates in urban refurbishment where low-VOC compliance under EU directives dictates specification decisions.
- Industrial Coatings:Epoxy and polyurethane systems serve automotive OEM lines and metal fabrication facilities. Capital requirements for captive resin production and application equipment integration run highest here, compressing viable competitor sets.
- Automotive Coatings:Basecoat-clearcoat systems with integrated electrostatic application lines.
- Protective Coatings:High-performance formulations for offshore energy infrastructure and subsea cabling.
- Marine Coatings:Anti-fouling and corrosion-resistant systems meeting Nordic technical standards.
- Powder Coatings:Solvent-free thermoset applications for appliance and automotive component finishing.
Architectural Coatings absorbs the bulk of installed capacity; Powder Coatings is expanding most quickly as fabricators eliminate solvent handling entirely.
Technology:
Margin structures align with regulatory pressure intensity, where compliance-driven transitions reshape production economics.
- Waterborne:Acrylic and polyurethane dispersions carry pigments and binders without hazardous air pollutant exposure. German and French contractors specify these for interior applications where occupant health certification carries weight.
- Solventborne:Traditional alkyd and nitrocellulose systems face REACH-driven reformulation costs. ECHA substance restrictions on titanium dioxide classification and VOC limits are accelerating substitution investments.
- UV Curable:Instant-cure acrylate oligomers for wood furniture and packaging printing.
- Powder:Thermoset epoxy and polyester systems applied electrostatically without solvent carriers.
- High-Solid:Reduced-solvent formulations bridging performance and compliance gaps.
- Epoxy:Two-component systems for protective and marine applications requiring chemical resistance.
Waterborne technology commands the largest production footprint; UV Curable is climbing the fastest as furniture and packaging converters adopt instant-cure lines.
Application:
Customer concentration patterns determine go-to-market economics, with fragmented construction contracting contrasting against consolidated OEM relationships.
- Building & Construction:Exterior facades, interior walls, and structural steel protection across residential, commercial, and infrastructure projects. Western European refurbishment cycles in Germany and France sustain volume as new construction stagnates.
- Transportation Equipment:Automotive, rail, and aerospace finishing with specification-grade performance guarantees. OEM direct relationships and integrated supply contracts create high switching costs.
- Consumer Goods:Appliances, electronics housings, and furniture coatings.
- Aerospace Components:Specialized primers and topcoats meeting EASA certification requirements.
- Metal Fabrication:General industrial finishing for machinery and structural components.
- Packaging:Food-contact and decorative coatings for metal and plastic containers.
Building & Construction represents the dominant demand pool; Transportation Equipment is gaining share fastest through OEM consolidation and specification-grade contracting.
End User:
Procurement sophistication tiers separate specification-influencing stakeholders from price-driven volume buyers.
- Construction Contractors:German and French firms expanding specification of certified environmental product declarations and health performance labels. Technical advisory services now unbundle from material supply, shifting purchasing power toward architects.
- OEMs:Automotive, appliance, and industrial equipment manufacturers with integrated coating lines and captive application expertise. Long-term supply agreements and co-development contracts lock in formulation partnerships.
- Manufacturers:In-house coating operations for own-production integration.
- Aftermarket Providers:Refinish and maintenance coating distributors serving collision repair and facility management.
- Marine Engineers:Shipyard and offshore platform operators specifying protective systems.
- Metal Processors:Coil coaters and metal service centers applying prefabrication finishes.
Construction Contractors account for the broadest customer base; OEMs are expanding procurement scale fastest through integrated supply chain consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp chemical corridor anchors European coatings formulation capacity, with integrated resin production clustering around North Sea port infrastructure and REACH compliance expertise concentrating in Dutch and Belgian regulatory consulting networks.
Germany
Urban refurbishment in Berlin, Munich, and Hamburg sustains architectural coatings demand as residential renovation rates outpace new construction. The national building code and KBA vehicle certification requirements layer performance standards atop EU baseline regulations. The Rhine-Ruhr industrial belt hosts captive resin synthesis for automotive OEM supply chains.
France
Commercial property renovation in Paris and Lyon drives specification-grade decorative coatings procurement. ANSM and national green public procurement rules mandate bio-content thresholds for public building projects. The Normandy and Provence-Alpes-Côte d'Azur regions concentrate marine and protective coatings production for offshore energy applications.
United Kingdom
London's commercial real estate retrofit cycle and Northern England manufacturing revival generate divergent demand profiles. Post-BREXIT UK REACH divergence creates parallel registration burdens for formulations crossing the Irish Sea. The Midlands automotive cluster sustains industrial coatings volume despite OEM consolidation pressures.
Italy
Lombardy and Veneto furniture manufacturing exports sustain UV-curable wood coating demand. CE marking and national fire rating requirements fragment product registration across EU and domestic certification schemes. The Emilia-Romagna industrial corridor anchors metal fabrication powder coating adoption.
Poland
Warsaw and Kraków construction acceleration outpaces Western European growth rates as building codes converge with EU standards. ECHA REACH enforcement timelines lag Western adoption curves, creating temporary formulation flexibility. The Silesian industrial zone attracts automotive component coating investment from German supply chain extension.
Europe Paints and Coatings Market Competitive Landscape
Capital-heavy producers with captive resin synthesis compete with asset-light formulators outsourcing intermediate supply. The European market structures around three tiers: integrated chemical conglomerates controlling upstream binders, mid-scale specialists dominating specification channels, and regional blenders serving price-sensitive maintenance segments. Dominant competitive moves include backward integration into bio-based feedstock cultivation and strategic partnerships with architectural specification influencers.
Among Dutch-origin multinationals, Akzo Nobel NV exemplifies heritage-driven specification channel dominance. German chemical conglomerate BASF SE anchors industrial demand through integrated resin supply. Norwegian specialist Jotun A/S occupies a defensible position in marine and protective segments where Nordic technical standards create certification barriers.
| Leading Market Players |
|---|
| Akzo Nobel NV |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| BASF SE |
| Jotun A/S |
| Axalta Coating Systems |
| Hempel A/S |
| RPM International Inc. |
| Sika AG |
| Others |
Supply & Pricing Matrix
The EU Green Deal carbon-border adjustment mechanism gates qualified supply access and premium-tier pricing power for European coatings formulators. REACH-compliant resin producers in Germany and the Netherlands command pricing premiums over import-dependent competitors while bio-based certification thresholds segment procurement channels.
Pricing Analysis
Performance-guarantee pricing anchors specification-grade coatings, where extended service intervals and warranty coverage determine contract value. Pricing stratifies across certified sustainable, REACH-compliant, and commodity solventborne tiers based on EPD documentation and VOC certification levels. Cost compression in standard architectural grades intensifies as Eastern European imports erode margin pools. Small-scale maintenance contractors exhibit highest price sensitivity; offshore energy operators prioritize total-cost-of-ownership over per-liter expenditure.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Antwerp, and Hamburg orchestrate hub-and-spoke delivery to fabrication clusters across the Rhine-Ruhr and Northern Italian industrial corridors. Captive resin synthesis concentrates in Germany, Belgium, and the Netherlands while titanium dioxide feedstock draws from Chinese pigment producers. Single-source vulnerability in epoxy hardener intermediates creates formulation disruption risk during supply shocks. Distribution runs through technical distributor networks that bundle specification advisory with material fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemist scarcity props pricing for compliant product lines across European manufacturing facilities. Capacity constraints in bio-based binder synthesis create defendable margin pools for early movers.
For Market Incumbents: Deploy captive resin production expansion to lock in supply security against petrochemical feedstock volatility. Deepen specification channel control through architect certification programs and EPD documentation services. Acquire bio-based alkyd specialists in Scandinavia before feedstock logistics mature and valuation multiples compress.
For New Entrants and Emerging Players: REACH substance restrictions on titanium dioxide classification in France and Germany open a window for compliant pigment substitute suppliers. Target Polish and Romanian construction acceleration where building code convergence lags Western certification complexity. Enter through municipal green procurement channels with certified bio-content formulations.
For Investors and Strategic Acquirers: German KBA tightening automotive coating performance standards is the leading indicator that specification-grade industrial assets will command scarcity premiums. Target mid-scale specialists with marine certification infrastructure and Nordic technical standard approvals. Watch for F-Gas Regulation phase-down acceleration as inflection signal for polyurethane coating supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstock | Secures supply chain emissions documentation for EU Green Deal compliance. |
| REACH Certification Investment | Unlocks specification channels among German and French public procurement authorities. |
| Marine Certification Infrastructure Expansion | Captures North Sea offshore wind protective coatings demand with Nordic technical barriers. |
| Powder Coating Application Line Integration | Eliminates solvent handling costs for automotive and appliance OEM customers. |
| Architectural Specification Partnership Program | Concentrates purchasing power among Dutch and Scandinavian municipal housing authorities. |
Research Methodology
Independent corroboration across plant managers at resin synthesis facilities, procurement leads at German automotive OEMs, and technical R&D directors at formulation houses underwrites the qualitative findings. Distribution channel partners in the Rotterdam-Antwerp corridor and specification-influencing architects in France and the Netherlands provided primary field intelligence. Secondary validation drew from ECHA substance restriction filings, Cefic production statistics, customs trade data for titanium dioxide imports, and SEC 10-K disclosures from listed coatings producers. Bottom-up capacity estimates and top-down demand segmentation were reconciled through iterative triangulation.
Rate-of-change decomposition across technology transitions, regulatory compliance timelines, and end-use substitution patterns structured the analytical framework. Segmentation dimensions modeled include product type, technology platform, application sector, and end-user procurement sophistication across the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends informed by feedstock cost pass-through analysis and certification premium capture rates.
The model assumes a particular technology adoption path; alternative pathways for waterborne polyurethane dispersions would alter the outlook if solventborne reformulation costs prove lower than anticipated. Forecasts reflect documented assumptions regarding REACH enforcement timelines and bio-based feedstock scaling curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
South Africa Paints and Coatings Market