
 Global Thermoplastic Vulcanizate (TPV) Market | 2026-2036
Global Thermoplastic Vulcanizate (TPV) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermoplastic Vulcanizate (TPV) Market Foresight
Aftermarket service revenue for TPV compound reprocessing is narrowing as virgin resin producers tighten supply-chain control. Celanese Corporation leverages its integrated acetyl chain to secure captive EPDM feedstock for TPV production. Teknor Apex competes through specialized color-matching capabilities across medical-grade and consumer-goods grades. Mitsui Chemicals anchors its position in Asia through Milastomer production scale and direct OEM supplier relationships in Japan and Thailand.
Thermoplastic vulcanizate consists of fully cross-linked rubber particles, typically EPDM, dispersed within a continuous thermoplastic matrix such as polypropylene, achieved through dynamic vulcanization under high shear. This morphology delivers elastomeric performance with thermoplastic processability, enabling injection molding and extrusion recycling while maintaining compression set resistance comparable to conventional vulcanized rubber. Hard TPV commands the largest volume share in automotive under-hood applications where heat resistance and dimensional stability justify premium positioning. Soft TPV is displacing conventional TPEs in medical device seals and grips as US FDA biocompatibility requirements intensify scrutiny of extractables and leachables. High-performance TPV grades incorporating silicone hybrid phases are capturing margin pools in electrical insulation for EV powertrain components.
US EPA fuel economy standards and NHTSA vehicle safety regulations are mandating lighter-weight materials in automotive assemblies, directly expanding TPV substitution for dense rubber and metal components. EU REACH restrictions on phthalate plasticizers and RoHS substance limits are reshaping formulation requirements for consumer electronics and household appliance applications. China's GB standards for automotive interior air quality and MIIT new energy vehicle specifications are creating parallel compliance pathways that favor low-VOC TPV compounds. Stakeholders must monitor evolving automotive electrification timelines and polymer recycling certification schemes to align capacity investments with the next wave of specification-driven demand.
Market Dynamics
Automotive electrification timelines are compressing specification cycles for under-hood materials, forcing compounders to validate TPV grades against simultaneous thermal, electrical, and chemical resistance criteria that thermoset rubbers cannot satisfy.
Growth Catalysts
- EPA vehicle emission standards:US fuel-efficiency mandates are accelerating TPV substitution for dense rubber and metal components in engine bay assemblies.
- EPDM-polypropylene morphology:Dynamic vulcanization technology enables full recycling of production scrap, aligning with EU Green Deal circularity requirements for automotive suppliers.
- China:MIIT new energy vehicle specifications and GB standards for interior air quality are creating dedicated demand for low-VOC TPV compounds in domestic EV production.
Market Restraints
- Propylene feedstock volatility:Polypropylene matrix costs fluctuate with naphtha and propylene monomer pricing, compressing compounder margins during upstream petrochemical cycles.
- German automotive cluster concentration:Tier-1 supplier networks in Stuttgart, Munich, and Wolfsburg dominate procurement, creating customer concentration risk for non-integrated compounders.
- Thermoset rubber legacy:Established EPDM and NBR supply contracts with decades-long qualification inertia block rapid TPV conversion in heavy-duty truck and industrial hose segments.
Strategic Opportunities
- Thailand:Japanese OEM transplant production and domestic supplier development create an underpenetrated hub for Milastomer-grade TPV localization outside China.
- Silicone-EPDM hybrid phases:Converging silicone rubber and TPV process technologies are opening electrical insulation specifications for EV powertrain components.
- US FDA biocompatibility pathways:Intensifying scrutiny of extractables in medical device seals is creating regulatory tailwind for validated soft TPV grades.
Industry Challenges
- Dynamic vulcanization process control:Cross-link density uniformity across high-shear extrusion lines requires specialized rheology expertise scarce in conventional thermoplastics operations.
- OEM qualification timelines:Automotive platform validation cycles spanning 24-36 months delay revenue realization even after compound development completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermoplastic Vulcanizate (TPV) Market |
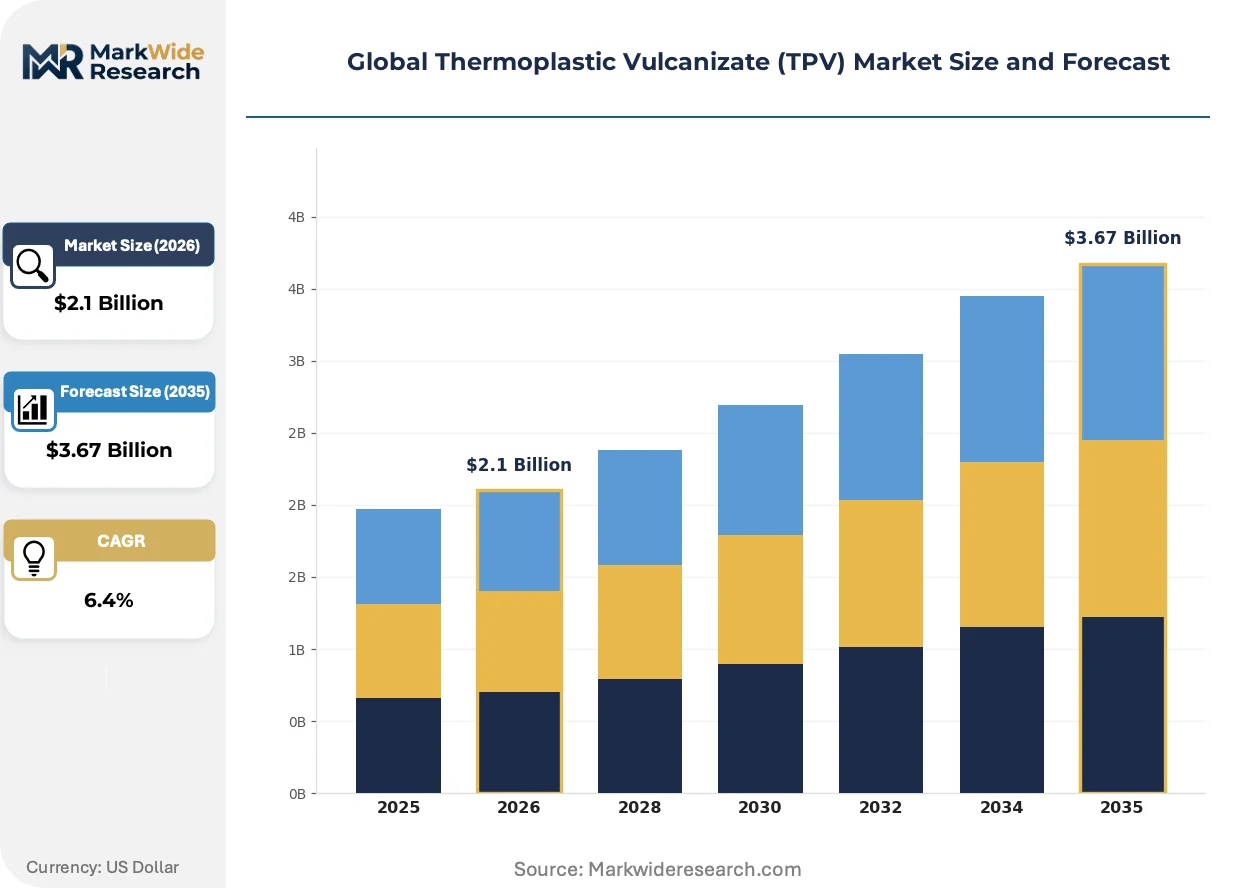
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard TPV, Soft TPV, High-Performance TPV, Medium-Grade TPV Application: Seals & Gaskets, Automotive Interior Components, Electrical Insulation, Medical Devices, Consumer Goods Manufacturing Process: Dynamic Vulcanization, Injection Molding, Extrusion, Compression Molding End User Industry: OEM Suppliers, Electronics Manufacturers, Medical Equipment Producers, Household Appliances, Construction Contractors |
| Companies Covered | Celanese Corporation, Teknor Apex, Mitsui Chemicals Inc., Avient Corporation, Kumho Polychem, DuPont de Nemours, Inc., Mitsubishi Chemical Corporation, ExxonMobil, RTP Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermoplastic Vulcanizate (TPV) Market Shifts & Advancements
Material science convergence and regulatory chemistry restrictions are rewriting formulation priorities, with hybrid-phase architectures and closed-loop reprocessing protocols emerging as the primary vectors of competitive differentiation.
Silicone-modified TPV is migrating from niche medical tubing into mainstream EV battery thermal management and high-voltage connector seals. Automotive tier-1 suppliers in Germany and Japan are adopting these grades at pilot scale for 800V architectures. The technology is migrating from premium positioning toward volume qualification as OEMs consolidate supplier lists around multi-functional compounds.
EU REACH restrictions on phthalate plasticizers and RoHS substance limits are eliminating legacy plasticized formulations from consumer electronics and appliance supply chains. Compounders must reformulate with bio-based or non-phthalate alternatives while maintaining Shore A hardness and compression set specifications. Medical device and household appliance segments are most affected, with procurement teams demanding full material disclosure documentation.
Automotive OEMs are unbundling after-sales service contracts from original component supply agreements, forcing compounders to establish independent reprocessing and technical service capabilities. Tier-1 suppliers are responding by building captive grinding and pelletizing operations rather than outsourcing to virgin resin distributors. This pattern is most visible in Michigan and Lower Saxony, where domestic production clusters generate sufficient scrap volume to justify dedicated recycling infrastructure.
Global Thermoplastic Vulcanizate (TPV) Market Segmentation
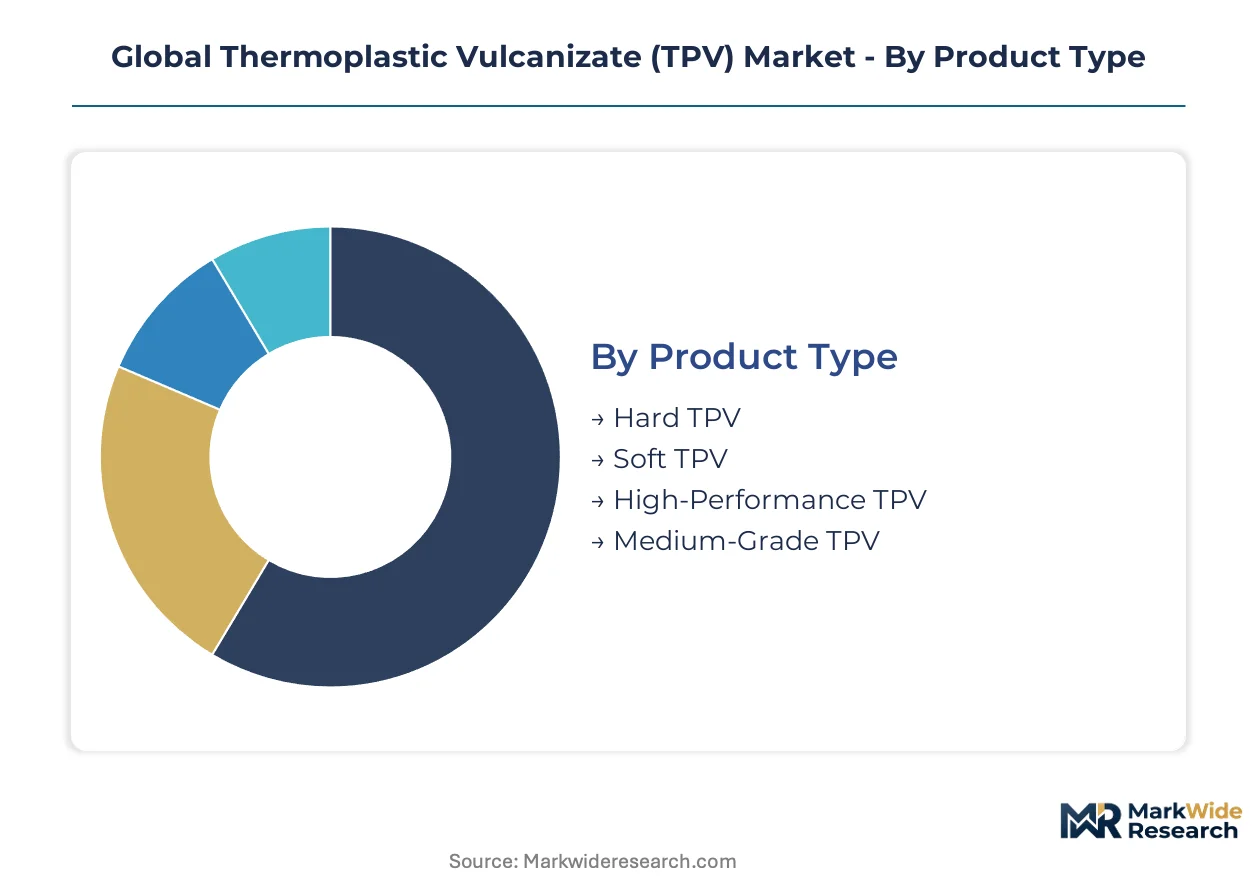
TPV segmentation reflects divergent technical requirements across automotive electrification, medical biocompatibility, and consumer electronics compliance pathways. Specification intensity varies dramatically by hardness grade, processing method, and end-use regulatory exposure.
Product Type:
Use-case spectrum spans dense under-hood assemblies through soft-touch medical interfaces to high-voltage electrical barriers.
- Hard TPV:High Shore D hardness formulations with elevated heat distortion temperatures serve under-hood seals and engine mounts. German OEM supplier clusters in Stuttgart and Wolfsburg specify these grades for thermal stability above 150°C in turbocharged powertrains.
- Soft TPV:Low Shore A compounds deliver elastomeric compression set performance for medical device seals and consumer grips. US FDA 21 CFR biocompatibility validation is concentrating procurement among compounders with extractables documentation capabilities.
- High-Performance TPV:Silicone hybrid phases achieve dielectric strength for 800V EV architectures. Japanese tier-1 suppliers are piloting these grades for battery thermal management.
- Medium-Grade TPV:General-purpose hardness range serves appliance gaskets and industrial hoses where cost-positioning trumps specification intensity.
Established volume favors Hard TPV; emerging adoption favors High-Performance TPV.
Application:
Functional demands fragment across fluid containment, occupant interface, electrical isolation, and regulatory-exposed healthcare segments.
- Seals & Gaskets:Dynamic vulcanization morphology delivers compression set resistance for engine bay fluid sealing. EPA fuel economy standards are accelerating substitution for dense EPDM and metal fasteners in US domestic production.
- Automotive Interior Components:Low-VOC emission profiles satisfy China GB standards for cabin air quality. MIIT new energy vehicle specifications are creating dedicated demand pools for domestic EV platforms.
- Electrical Insulation:Dielectric grades with silicone hybrid phases serve high-voltage connector seals. 800V powertrain architectures are expanding specification cycles beyond conventional thermoset capabilities.
- Medical Devices:Soft TPV grades with USP Class VI validation displace conventional TPEs in syringe seals and surgical grips. FDA scrutiny of leachables is narrowing qualified supplier pools.
- Consumer Goods:Appliance grips and electronics housings face EU REACH phthalate restrictions. RoHS substance limits are eliminating legacy plasticized formulations from supply chains.
Automotive applications dominate procurement volume; medical devices are climbing the fastest on regulatory tailwinds.
Manufacturing Process:
Process selection trades cycle efficiency against morphological control and scrap recovery economics.
- Dynamic Vulcanization:Continuous high-shear extrusion achieves fully cross-linked EPDM dispersion within polypropylene matrix. This core technology enables full production scrap recycling aligned with EU Green Deal circularity mandates.
- Injection Molding:Rapid cycle times serve high-volume automotive interior components. Tooling amortization across million-unit platforms justifies capital intensity in Germany and US Midwest production clusters.
- Extrusion:Profile production for seals and gaskets demands rheology expertise scarce in conventional thermoplastics operations. Cross-link density uniformity determines compression set performance.
- Compression Molding:Legacy process retains position in heavy-duty truck and industrial hose segments where thermoset rubber qualification inertia blocks rapid TPV conversion.
Dynamic vulcanization anchors technology leadership; injection molding captures highest volume throughput.
End User Industry:
Customer concentration and qualification timelines vary sharply across consolidated automotive supply chains versus fragmented construction procurement.
- OEM Suppliers:Tier-1 networks in Germany, Japan, and US Midwest dominate specification-setting. Platform validation cycles spanning 24-36 months delay revenue realization after compound development.
- Electronics Manufacturers:Consumer device assemblers face EU RoHS and REACH substance restrictions. Full material disclosure documentation is becoming standard procurement requirement.
- Medical Equipment Producers:US FDA and EU MDR biocompatibility pathways favor validated soft TPV grades with extractables testing protocols.
- Household Appliances:White goods producers seek low-VOC compounds for interior gaskets and exterior grips. China's domestic appliance production clusters generate regional demand concentration.
- Construction Contractors:Fragmented procurement and price-sensitive specification limit TPV penetration in window seals and roofing membranes.
OEM suppliers command specification authority; medical equipment producers offer steepest expansion trajectory on regulatory differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and Thailand exhibit high price elasticity on commodity-grade compounds, while German and US automotive OEMs prioritize specification compliance over unit cost. This demand-elasticity contrast shapes regional procurement patterns.
United States
EPA fuel economy standards and NHTSA vehicle safety regulations mandate lighter-weight under-hood materials. Domestic OEM suppliers in Michigan and Ohio specify TPV grades for turbocharged powertrain seals. The Midwest automotive cluster generates concentrated demand for hard TPV compounds.
Germany
EU Green Deal circularity requirements and REACH substance restrictions accelerate thermoset rubber substitution. Tier-1 supplier networks in Stuttgart, Munich, and Wolfsburg dominate procurement of heat-resistant grades. Stuttgart anchors specification-setting for 150°C thermal stability requirements.
China
MIIT new energy vehicle specifications and GB standards for automotive interior air quality create dedicated low-VOC demand. Domestic EV production clusters in Shanghai and Guangzhou concentrate procurement. Shanghai-based platforms prioritize cabin air quality compliance.
Japan
METI industrial policy and JIS standards shape material qualification pathways. Direct OEM supplier relationships anchor Milastomer-grade production for transplant operations in Thailand. Nagoya-based tier-1 suppliers pilot silicone hybrid grades for 800V architectures.
Thailand
Japanese OEM transplant production and domestic supplier development create underpenetrated localization opportunities. Bangkok and Eastern Economic Corridor industrial zones concentrate automotive assembly. Eastern Seaboard facilities generate scrap volumes justifying captive reprocessing infrastructure.
Global Thermoplastic Vulcanizate (TPV) Market Competitive Landscape
Capability concentration sits with integrated petrochemical players; scale advantage sits with specialized compounders. The market structures around three tiers: upstream-integrated resin producers, mid-scale formulation specialists, and regional distribution-focused compounders. Strategic moves center on captive feedstock security and qualification timeline compression through direct OEM relationships.
Within the integrated-resin tier, Celanese Corporation and ExxonMobil exemplify upstream control over EPDM and polypropylene feedstocks. Teknor Apex and Mitsui Chemicals occupy positions as formulation specialists with differentiated color-matching and medical-grade validation capabilities. DuPont de Nemours, RTP Company, and Avient Corporation represent the diversified materials portfolio archetype spanning multiple elastomer technologies.
| Leading Market Players |
|---|
| Celanese Corporation |
| Teknor Apex |
| Mitsui Chemicals Inc. |
| Avient Corporation |
| Kumho Polychem |
| DuPont de Nemours, Inc. |
| Mitsubishi Chemical Corporation |
| ExxonMobil |
| RTP Company |
| Others |
Supply & Pricing Matrix
Undercapacity in European TPV compounding is tightening supplier leverage against automotive OEM procurement teams. This utilization squeeze rewards integrated resin producers with captive EPDM feedstock while forcing non-integrated compounders toward longer-term contract structures.
Pricing Analysis
After-sales service revenue from compound reprocessing and technical support drives lifetime value for TPV suppliers. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade validated compounds from automotive commodity grades. Cost compression in standard-grade automotive TPV is intensifying because virgin resin producers are tightening supply-chain control. Electronics manufacturers exhibit highest price sensitivity due to fragmented procurement, while German OEM suppliers prioritize thermal stability certification over unit cost.
Supply Chain Analysis
Extended payment terms from tier-1 automotive suppliers are squeezing working capital for regional compounders without supply-chain finance facilities. Production concentrates in Germany, China, and the United States where domestic automotive clusters anchor demand. Feedstock draws from Saudi Arabian propylene derivatives, South Korean EPDM rubber, and US Gulf Coast polypropylene. Single-source vulnerability sits with specialized rheology expertise for dynamic vulcanization process control. Distribution runs through tier-1 supplier networks rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized rheology expertise for dynamic vulcanization represents the critical capability gap separating integrated resin producers from formulation specialists. Securing this talent or licensing the technology determines competitive viability.
For Market Incumbents: Harden qualification timeline advantages by embedding technical service teams within Stuttgart, Munich, and Wolfsburg OEM supplier clusters. Expand captive grinding and pelletizing operations in Michigan and Lower Saxony to capture scrap reprocessing revenue streams. Defend against silicone-EPDM hybrid phase substitution by accelerating R&D in electrical insulation grades. For New Entrants and Emerging Players: Build out medical-grade soft TPV capabilities targeting US FDA biocompatibility validation as the most penetrable segment. Thailand's Eastern Economic Corridor offers underexploited localization opportunities outside Chinese supply chains. Pursue direct OEM supplier relationships in Japan to bypass established distributor networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with integrated reprocessing infrastructure and multi-year automotive platform contracts. Long-term viability favors upstream-integrated players with captive EPDM security over formulation specialists exposed to feedstock volatility. Monitor silicone hybrid phase adoption curves in 800V EV architectures as the inflection signal for technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Feedstock | Celanese Corporation's integrated acetyl chain secures captive rubber supply against propylene volatility. |
| Medical-Grade Validation Investment | US FDA biocompatibility pathways concentrate procurement among compounders with extractables documentation. |
| Thailand Localization Partnership | Japanese OEM transplant production in Bangkok and Eastern Economic Corridor generates Milastomer-grade demand. |
| Silicone Hybrid Phase Development | Dielectric grades for 800V EV powertrains capture margin pools beyond conventional thermoset capabilities. |
| Captive Reprocessing Infrastructure | Tier-1 suppliers in Michigan and Lower Saxony build grinding operations to retain aftermarket service revenue. |
Research Methodology
Initial hypotheses were tested against primary input from tier-1 supplier procurement managers, compounder technical directors, and automotive platform engineers and refined through secondary validation. Stakeholder interviews combined with customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up demand modeling across hardness grades and top-down market sizing triangulated volume estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions included hardness grade, end-use industry, manufacturing process, and regional production hub. CAGRs derived from regression analysis of historical automotive production correlations and polymer substitution elasticities. Key inputs encompassed EPA fuel economy standard stringency trajectories and EU REACH substance restriction timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by non-integrated compounders would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Snap on Rubber Stopper Market
Rubber
Rubber Chemicals Market
Rubber
Abrasion-Resistant Rubber Pipe Market
Rubber
Rubber Foam Materials Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Rubber Splicing Tape Market
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Polybutadiene Elastomers Market
Rubber
Acrylic Based Elastomers Market
Rubber
Medical Rubber and Balloon Products Market
Rubber
Europe Rubber Hose Market
Rubber
Tire and Rubber Lubricants Market
Rubber
Rubber Bulb Seals Market