
 Medical Rubber and Balloon Products Market | 2026-2036
Medical Rubber and Balloon Products Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Rubber and Balloon Products Market Intelligence
The adoption of drug-eluting balloon technologies is redrawing the market structure for vascular intervention products. Boston Scientific Corporation leverages its extensive R&D in this area to maintain a leading market position. Medtronic plc competes through its broad portfolio of catheter-based systems and a global distribution network. Terumo Corporation specializes in high-performance materials for its interventional systems.
Medical rubber and balloon products encompass a range of elastomeric components designed for therapeutic and diagnostic applications. These items, often manufactured from materials like silicone rubber or latex, must exhibit specific durometer hardness and biocompatibility for safe patient contact. Catheters represent the largest product segment due to their widespread use in vascular and urological procedures. Within materials, thermoplastic elastomers are gaining share from traditional latex due to superior hypoallergenic properties and design flexibility.
Regulatory bodies including the US FDA, the European Medicines Agency (EMA), and China's NMPA impose strict standards on material purity and device performance. These regulations directly influence material selection and require extensive clinical validation, creating high barriers to market entry. Navigating the evolving landscape of material science and regional regulatory approvals remains the central challenge for manufacturers.
Market Dynamics
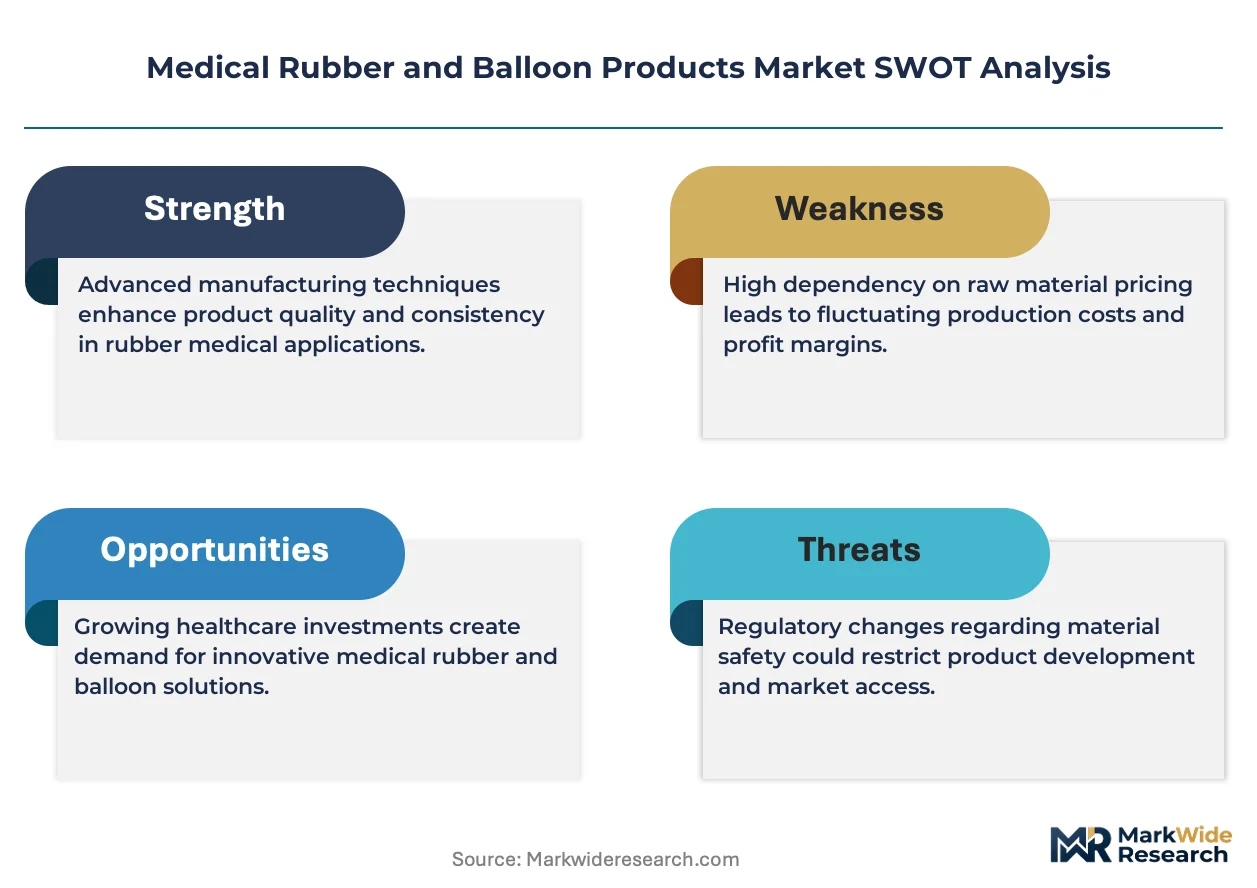
The central dynamic in the medical rubber and balloon products market is the push for material innovation, particularly with thermoplastic elastomers, clashing with the escalating stringency of global regulatory frameworks like the EU's Medical Device Regulation (MDR).
Growth Catalysts
- Drug-Eluting Technologies:The development and adoption of drug-eluting balloon technologies for vascular procedures provide a significant stimulus, creating demand for advanced, specialized balloon components that can deliver therapeutic agents effectively.
- Demographic Shifts:Aging populations in developed nations, including Japan and the United States, are leading to a higher incidence of chronic conditions, thereby increasing the volume of urological and cardiovascular procedures that rely on catheters and balloons.
- Biocompatibility Standards:Stricter enforcement of biocompatibility standards, such as ISO 10993, compels manufacturers to shift towards higher-grade materials like medical-grade silicone and specific thermoplastic elastomers, driving value growth.
Market Restraints
- Material Cost and Sourcing:High costs and supply chain volatility for key raw materials, including medical-grade silicone and specialized polymers, create significant cost pressures for manufacturers and can constrain production volumes.
- Regulatory Hurdles:The extensive and costly clinical validation processes mandated by regulatory bodies like the US FDA and the European Medicines Agency (EMA) create high barriers to entry and lengthen product development timelines.
- Substitution by Alternatives:In certain non-critical applications, the threat of substitution from lower-cost standard polymers or alternative non-elastomeric devices can limit market penetration and apply downward pressure on pricing.
Strategic Opportunities
- Emerging Market Expansion:Underpenetrated healthcare systems in regions like Southeast Asia and Latin America represent significant growth opportunities as infrastructure develops and access to advanced medical procedures improves.
- Bioresorbable Materials:The development of bioresorbable polymers for temporary balloon applications, such as in certain surgical or drug-delivery contexts, opens a new frontier for product innovation, eliminating the need for device removal.
- Smart Device Integration:Integrating micro-sensors and wireless technology into balloon catheters for real-time pressure monitoring, temperature sensing, or positional feedback presents a major opportunity for value-added differentiation.
Industry Challenges
- Regulatory Harmonization:Manufacturers face the operational challenge of navigating and maintaining compliance with divergent and often non-harmonized regulatory requirements between major markets, such as the US, EU, and China.
- Supply Chain Traceability:Ensuring end-to-end traceability and purity of raw materials from source to final device is a complex logistical challenge, made more difficult by global supply chain disruptions and stringent documentation demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Rubber and Balloon Products Market |
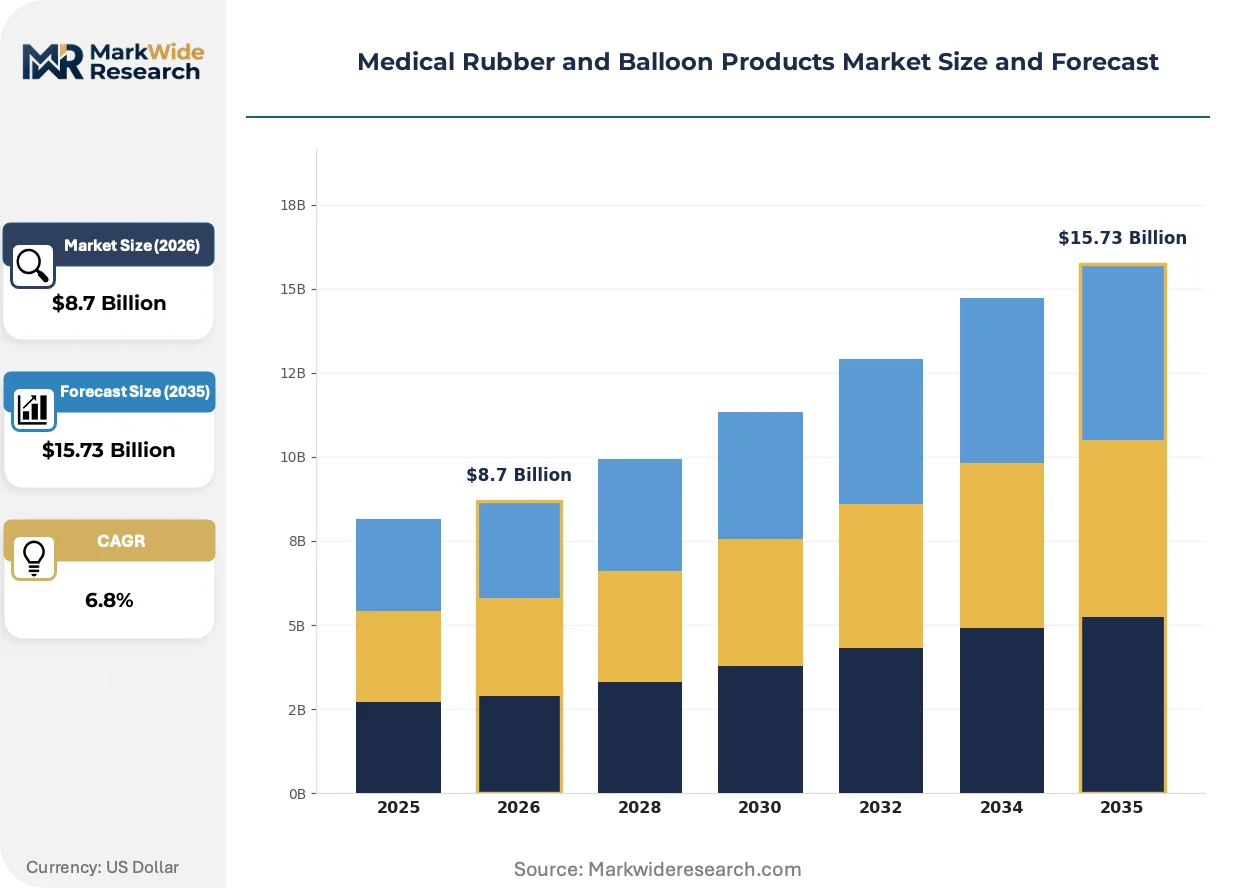
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Endoscopic Balloons, Inflation Devices, Medical Tubing, Surgical Gloves Material: Silicone Rubber, Latex, Neoprene, Polyisoprene, Thermoplastic Elastomer Application: Vascular Procedures, Gastroenterology, Urology, Pulmonology, Dermatology End User: Ambulatory Surgical Centers, Diagnostic Laboratories, Dental Clinics, Outpatient Facilities |
| Companies Covered | B. Braun Melsungen, AngioDynamics, Abbott Laboratories, Terumo Corporation, Ansell Healthcare, Boston Scientific Corporation, Cardinal Health, Hartalega Holdings Berhad, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Rubber and Balloon Products Market Strategic Shifts & Innovations
The market is advancing toward less invasive and more intelligent devices, a movement defined by the convergence of material science breakthroughs and the integration of data-generating components into traditional products. This evolution prioritizes patient safety, procedural efficacy, and enhanced diagnostic capabilities.
Advanced micro-molding and multi-lumen extrusion processes are enabling the production of highly complex and smaller-diameter balloon catheters. Interventional cardiologists and neurovascular surgeons are the primary adopters, seeking tools for accessing more challenging anatomies. This technology is miniaturizing the profile of interventional devices, facilitating access to delicate and previously unreachable vascular pathways.
The European Union's Medical Device Regulation (MDR) has introduced more rigorous requirements for clinical evidence, risk management, and post-market surveillance. This forces manufacturers to undertake extensive re-certification of existing products and invest more heavily in data collection for new ones. The catheter segment is particularly impacted, with firms reallocating significant R&D resources to ensure compliance and maintain market access in Europe.
A distinct shift in hospital purchasing behavior is evident, with large healthcare networks moving toward vendor consolidation and value-based contracts for high-volume disposables. This model disrupts the sales channels of smaller, specialized suppliers while benefiting large-scale manufacturers who can offer a broad portfolio. This procurement pattern is most visible across health systems in the United States and parts of Western Europe.
Medical Rubber and Balloon Products Market Segmentation
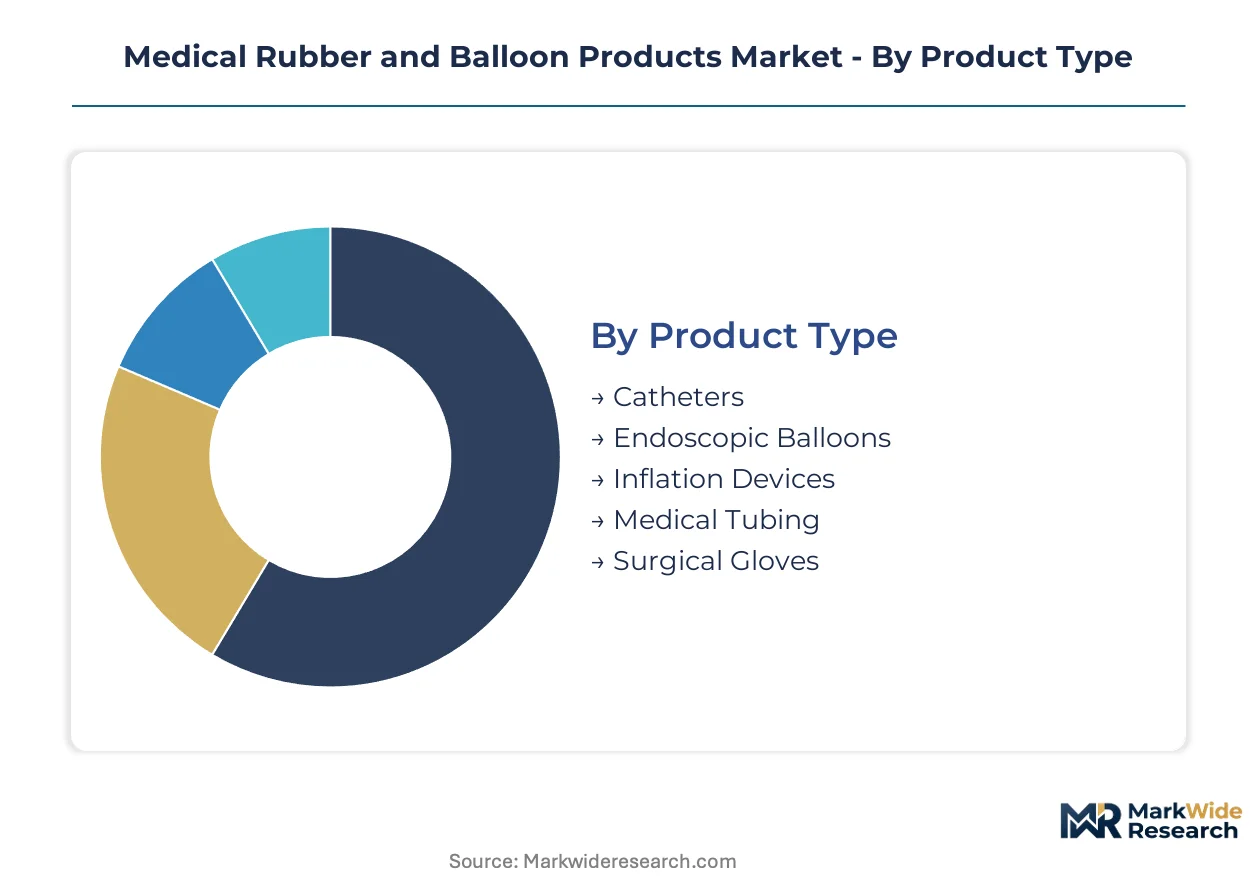
Understanding the distinct segments within the medical rubber and balloon products market is crucial for manufacturers and healthcare providers. This segmentation highlights the diverse material science requirements, application-specific design considerations, and varying end-user demands that collectively define market opportunities and competitive landscapes.
Product Type:
The geographic spread of product adoption often differentiates domestic manufacturing capabilities from export-led specializations, influencing regional market structures for medical devices.
- Catheters:These flexible tubes, typically made from silicone or thermoplastic elastomers, are inserted into body cavities, ducts, or vessels for fluid drainage, medication administration, or surgical access. Demand for advanced catheter designs is concentrating in the United States due to the high volume of cardiovascular and urological procedures.
- Endoscopic Balloons:Designed for dilation, hemostasis, or foreign body retrieval within the digestive or respiratory tracts, these devices require precise inflation control and biocompatible materials. European healthcare systems are driving innovation in smaller diameter, high-pressure endoscopic balloons for less invasive diagnostics.
- Inflation Devices:These specialized tools provide controlled pressure and volume to inflate medical balloons during interventional procedures. Their utility spans across various therapeutic areas, from vascular to urological applications.
- Medical Tubing:Essential for fluid delivery, drainage, and gas transfer, medical tubing must meet stringent sterility and biocompatibility standards. Hospitals and clinics utilize these components in numerous patient care settings.
- Surgical Gloves:Providing a sterile barrier for medical professionals during surgical procedures, these gloves are critical for infection control. Latex and nitrile variants are widely adopted across all healthcare facilities.
Catheters commands the established base. The steepest expansion runs through Endoscopic Balloons.
Material:
Material choices are primarily driven by cost-tier considerations, balancing performance requirements with economic viability across different product categories.
- Thermoplastic Elastomer:These materials offer superior design flexibility, excellent biocompatibility, and can be processed using advanced manufacturing techniques like injection molding and extrusion. The shift towards thermoplastic elastomers is accelerating in European medical device manufacturing due to stringent MDR requirements.
- Silicone Rubber:Known for its high biocompatibility, flexibility, and temperature resistance, medical-grade silicone rubber is widely used in long-term implantable devices and catheters. United States medical device innovators frequently specify silicone for chronic care applications.
- Latex:Derived from natural rubber, latex offers high elasticity and strength but faces declining use due to allergenicity concerns in patient populations. Lower-cost medical devices in emerging markets still utilize latex for its economic advantages.
- Polyisoprene:A synthetic rubber that mimics natural latex properties without the allergenicity, polyisoprene is gaining traction as a hypoallergenic alternative for gloves and seals. Its adoption is increasing in clinical settings prioritizing patient safety.
- Neoprene:Offering good chemical resistance and mechanical strength, neoprene is utilized in specific medical applications where durability and barrier properties are paramount. Certain medical tubing and protective covers incorporate neoprene.
Material procurement patterns are shifting towards Thermoplastic Elastomer for advanced products. Silicone Rubber maintains a strong position in high-performance applications.
Application:
The market's application landscape is shaped by the specific procedural needs and the volume of patient interventions across various medical specialties.
- Vascular Procedures:This segment includes angioplasty, stenting, and thrombectomy, heavily relying on advanced balloon catheters and guidewires for minimally invasive interventions. The rising incidence of cardiovascular diseases in developed nations like Japan fuels demand here.
- Urology:Procedures such as urinary catheterization, stone removal, and prostate treatments utilize specialized balloons and tubing for diagnostic and therapeutic purposes. Aging populations in the United States contribute significantly to the volume of urological interventions.
- Gastroenterology:Endoscopic procedures for diagnosing and treating conditions of the digestive tract frequently employ balloons for dilation, stent placement, and polyp removal. Hospitals across Western Europe are seeing consistent demand for these specialized devices.
- Pulmonology:Respiratory interventions, including bronchoscopy and airway management, use medical balloons and tubing for diagnostic sampling, foreign body removal, and stent deployment. Specialized pulmonology clinics are driving innovation in this niche.
- Dermatology:While a smaller segment, dermatology applications involve certain specialized devices for wound care, tissue expansion, or localized drug delivery. Aesthetic and reconstructive procedures represent a growing area of use.
Vascular Procedures currently holds the largest share of demand. Growth is particularly pronounced in the Urology segment.
End User:
Customer type significantly influences procurement strategies and product specifications, with large institutions seeking volume discounts and specialized facilities requiring tailored solutions.
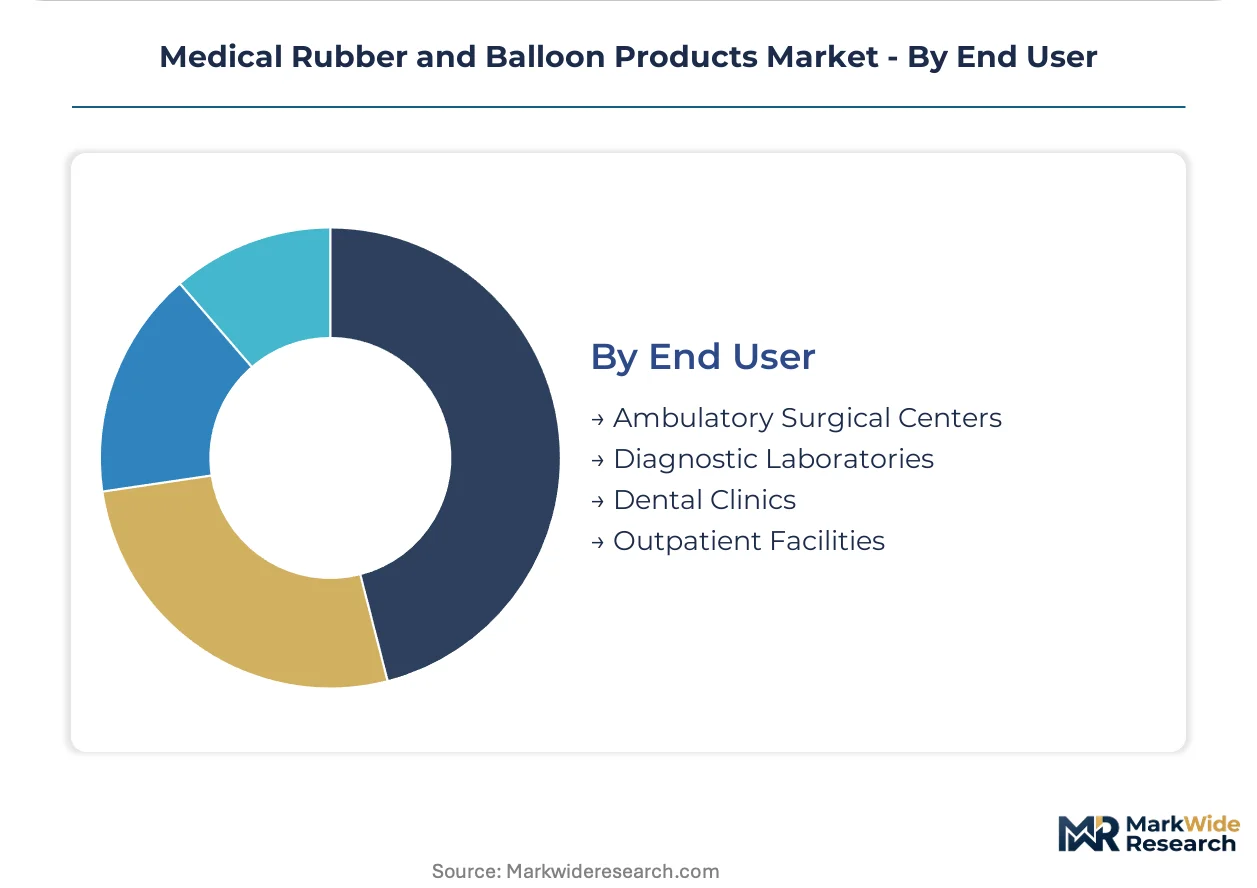
- Ambulatory Surgical Centers:These facilities perform outpatient surgical procedures, driving demand for single-use, cost-effective medical rubber and balloon products. Their focus on efficiency and rapid patient turnover shapes product preferences.
- Outpatient Facilities:Providing a range of diagnostic and therapeutic services outside of traditional hospitals, these centers require versatile and easy-to-use devices for various patient needs. The expansion of community clinics in the United States increases consumption.
- Diagnostic Laboratories:While not direct users of balloon products, these labs utilize medical tubing and rubber components for sample collection, processing, and analysis. Stringent quality control is paramount for their specialized workflows.
- Dental Clinics:Specific dental procedures require small-scale rubber and balloon products for isolation, impression taking, or restorative work. Material biocompatibility for oral contact is a key factor.
Ambulatory Surgical Centers are rapidly expanding their procurement of specialized devices. Outpatient Facilities represent a substantial and growing customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global medical rubber and balloon products market exhibits varied regional dynamics, often influenced by local healthcare investment and regulatory environments. While some nations drive innovation and export high-value components, others focus on domestic manufacturing to meet local demand. This export-import balance shapes regional market structures.
United States
Demand for advanced catheter designs and interventional devices is significant in the United States, driven by a high volume of cardiovascular and urological procedures. The US FDA imposes rigorous standards on device safety and efficacy, influencing material selection and product development. Major medical device clusters in states like California and Massachusetts foster continuous innovation in specialized balloon components.
Germany
European healthcare systems, particularly in Germany, emphasize innovation in smaller diameter and high-pressure endoscopic balloons for less invasive diagnostics. The EU's Medical Device Regulation (MDR) has intensified requirements for clinical evidence and risk management across the region. Medical technology hubs in Bavaria and North Rhine-Westphalia are central to developing and manufacturing high-grade medical elastomers.
Japan
Aging populations in Japan contribute to a higher incidence of chronic conditions, increasing the volume of urological and cardiovascular procedures. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict oversight of material purity and device performance. Companies in the Kanto region, including Tokyo, specialize in precision manufacturing for high-performance interventional systems.
China
China's expanding healthcare infrastructure and rising incidence of chronic diseases drive a growing demand for medical rubber and balloon products. The National Medical Products Administration (NMPA) sets stringent standards for material quality and device approval. Manufacturers in the Yangtze River Delta region are increasing domestic production of essential medical consumables.
India
Emerging healthcare systems in India represent significant growth opportunities as access to advanced medical procedures improves. The Central Drugs Standard Control Organization (CDSCO) regulates the import and manufacture of medical devices within the country. Cities like Bengaluru and Hyderabad are becoming centers for medical device manufacturing and R&D, catering to both domestic and regional markets.
Medical Rubber and Balloon Products Market Key Industry Players
Listed leaders compete with private specialists across product innovation and market reach within the medical rubber and balloon products market. The market structure features a mix of large, diversified healthcare conglomerates and specialized manufacturers focusing on niche applications. Strategic archetypes include broad-portfolio providers, material science innovators, and regional specialists. Dominant competitive moves involve portfolio diversification and strategic partnerships to navigate regulatory complexities.
Among the established multinational corporations, Boston Scientific Corporation and Medtronic plc occupy strong positions, leveraging extensive research and development capabilities. Boston Scientific Corporation represents a leader in drug-eluting balloon technologies for vascular procedures. Medtronic plc exemplifies a company with a broad portfolio of catheter-based systems and a global distribution network. Terumo Corporation, a Japanese entity, sits within the archetype of material science innovators, specializing in high-performance materials for interventional systems.
| Leading Market Players |
|---|
| B. Braun Melsungen |
| AngioDynamics |
| Abbott Laboratories |
| Terumo Corporation |
| Ansell Healthcare |
| Boston Scientific Corporation |
| Cardinal Health |
| Hartalega Holdings Berhad |
| Medtronic plc |
| Others |
Cost & Logistics Intelligence
Ninety-day lead times for specialized medical-grade polymers connect directly to a supply chain concentrated in specific material science hubs, which in turn influences pricing power for advanced medical rubber and balloon products.
Pricing Analysis
Hospital Group Purchasing Organizations (GPOs) anchor contract-based long-term offtake pricing for high-volume disposables. Price differentiation stems from certification level, particularly EU MDR compliance, and the degree of material customization for specific device applications. Pricing softness reflects the intense competition for large-volume contracts among established manufacturers. Ambulatory Surgical Centers often exhibit the most price-sensitive procurement behaviors.
Supply Chain Analysis
Six-month inventory buffers for medical-grade silicone indicate supply chain vulnerabilities. Geographic supply concentration for key raw materials resides in countries like China, Germany, and the United States. The market draws from specialized polymers and medical-grade silicone as critical inputs. Commodity price volatility for these base materials represents a structural supply chain risk. Distribution runs through direct sales forces and established medical device distributors to healthcare facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical rubber and balloon products market presents a defensive moat story, primarily due to the significant regulatory entrenchment and high switching costs associated with validated medical devices.
For Market Incumbents:
Compound existing R&D investments in advanced material science, particularly thermoplastic elastomers, to maintain a lead in device performance. Strengthen relationships with major healthcare networks through value-based contracts, mitigating the threat from smaller, specialized suppliers. Invest in comprehensive clinical validation for new products under frameworks like the EU MDR, acting as a barrier to entry. Deepen channel control by offering integrated solutions across product segments.
For New Entrants and Emerging Players:
Anchor in niche applications requiring highly specialized materials or unique design capabilities, such as bioresorbable polymers for temporary balloon applications. Target underpenetrated emerging markets like Southeast Asia, focusing on building local manufacturing and distribution partnerships. A go-to-market angle focused on superior patient outcomes through smart device integration offers a differentiation pathway. The pulmonology segment represents a penetrable application white space.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting in an upward direction across the advanced catheter and interventional systems sub-segment. The long-term viability favors entities capable of navigating complex regulatory landscapes and investing in continuous material innovation. Acquisition targets should be specialized manufacturers with strong intellectual property in thermoplastic elastomers or drug-eluting technologies. The signal to watch is the increasing rate of regulatory approvals for novel bioresorbable devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Thermoplastic Elastomer Portfolio | This initiative enhances biocompatibility and design flexibility for next-generation interventional devices. |
| Invest in Drug-Eluting Balloon R&D | This focuses on delivering therapeutic agents effectively for improved vascular procedure outcomes. |
| Strengthen EU MDR Compliance Programs | This ensures continued market access and mitigates regulatory risks within European healthcare systems. |
| Form Strategic Partnerships with GPOs | This secures high-volume procurement contracts and broadens market reach within hospital networks. |
| Integrate Micro-sensors into Catheters | This enables real-time monitoring capabilities for enhanced diagnostic and therapeutic precision. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. Primary insights were gathered from biomedical engineers, hospital purchasing committees, regulatory affairs leads, and R&D directors across major markets. This qualitative data was triangulated with quantitative information from secondary sources.
The analytical framework modeled market dynamics across the analysis window, segmenting by product type, material, application, and end user. An additional dimension, regulatory compliance tier, was also integrated into the model. Compound Annual Growth Rates were derived from historical data trends and projected future demand, considering factors like chronic disease incidence rates and regulatory approval timelines.
Material uncertainties — including unforeseen supply chain disruptions or significant shifts in healthcare reimbursement models — sit outside the modeled envelope. Forecasts reflect assumptions documented through stakeholder consensus and trend analysis. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Hospital Rubber Sheet Market
Rubber
Industrial Rubber Products Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market
Rubber
Global Crumb Rubber Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Cellular Rubber Market
Rubber
Rubber Chemicals Market
Rubber
Oil Saver Rubber Market
Rubber
Rubber Masterbatch Market
Rubber
Liquid Silicone Rubber Market
Rubber
Rubber Splicing Tape Market
Rubber
Acrylic Based Elastomers Market
Rubber
Tire Softener Market
Rubber
Synthetic Rubber Market
Rubber
Polybutadiene Elastomers Market
Rubber
Rubber Carbon Black Market