
 Global Medical Rubber and Balloon Products Consumption Market | 2026-2036
Global Medical Rubber and Balloon Products Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Rubber and Balloon Products Consumption Market Foresight
Silicone-to-thermoplastic elastomer conversion is reshaping catheter construction across cardiovascular and urology applications. Abbott Laboratories leverages vertically integrated balloon molding capabilities to sustain catheter supply security for electrophysiology labs. Boston Scientific Corporation anchors its competitive position through proprietary compliant balloon technologies in peripheral interventions. Hartalega dominates disposable latex and nitrile examination glove supply to hospital procurement networks across Southeast Asia.
Medical rubber and balloon products encompass elastomer-based devices engineered to precise durometer specifications, tensile strength parameters, and biocompatibility grades for minimally invasive diagnostics and therapy. Balloon catheters deploy polyethylene terephthalate or nylon blends inflated to rated burst pressures for vessel dilation, stent deployment, or occlusion management. Rubber catheters and surgical tubing represent mature, high-volume categories where natural rubber latex competes with synthetic polyisoprene for allergy-sensitive segments. Balloon devices command premium positioning in cardiology and pulmonology applications where burst integrity and profile minimization determine clinical outcomes. Silicone rubber formulations are gaining share in neurology and gastroenterology channels due to superior chemical inertness and extended implant tolerance.
FDA 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements impose escalating compliance burdens on balloon catheter manufacturers seeking dual-market access. ISO 10993 biocompatibility testing protocols govern material selection for long-dwell surgical tubing and implantable balloon structures. Japan's PMDA maintains distinct pharmaceutical and medical device classification pathways that shape registration strategies for multinational suppliers. Stakeholders must monitor evolving EUDAMED registration timelines and FDA digital health pre-certification pilots that could accelerate software-integrated balloon delivery systems.
Market Dynamics
Silicone-to-thermoplastic elastomer conversion is compressing catheter manufacturing costs while FDA and EMA biocompatibility standards tighten material purity thresholds, creating simultaneous cost and compliance pressures across cardiovascular and urology supply chains.
Growth Catalysts
- Aging demographics in developed economies:Germany, Japan, and the United States sustain procedural volumes for balloon catheters as cardiac intervention rates rise with elderly population expansion.
- EU MDR technical documentation requirements:Stricter conformity assessment pathways are accelerating R&D investment in next-generation biocompatible elastomers for implantable devices.
- Polyethylene terephthalate balloon molding:Advanced polymer processing enables thinner-wall, higher-burst-pressure catheters that expand treatable patient anatomies.
Market Restraints
- Natural rubber latex price volatility:Plantation supply disruptions in Southeast Asia create input cost instability for examination glove and surgical tubing manufacturers.
- ISO 10993 biocompatibility testing burden:Extended cytotoxicity and sensitization study timelines stretch product development cycles and capital lockup periods.
- Thermoplastic elastomer substitution threat:TPEs displace silicone in short-dwell applications, compressing margins in commoditized catheter segments.
Strategic Opportunities
- Neurology and gastroenterology channels:Silicone rubber's superior chemical inertness opens underpenetrated indications for extended-implant tolerance devices.
- Japan PMDA pharmaceutical-medical device convergence:Streamlined combination product pathways enable novel drug-eluting balloon catheter registrations.
- Digital health pre-certification pilots:FDA software-integrated device frameworks create regulatory tailwinds for sensor-embedded balloon delivery systems.
Industry Challenges
- Balloon molding technician scarcity:Specialized thin-wall extrusion and blow-molding expertise concentrates in legacy manufacturing clusters, constraining capacity expansion.
- EUDAMED registration timeline uncertainty:Evolving database go-live schedules complicate EU market entry planning for multinational catheter suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Rubber and Balloon Products Consumption Market |
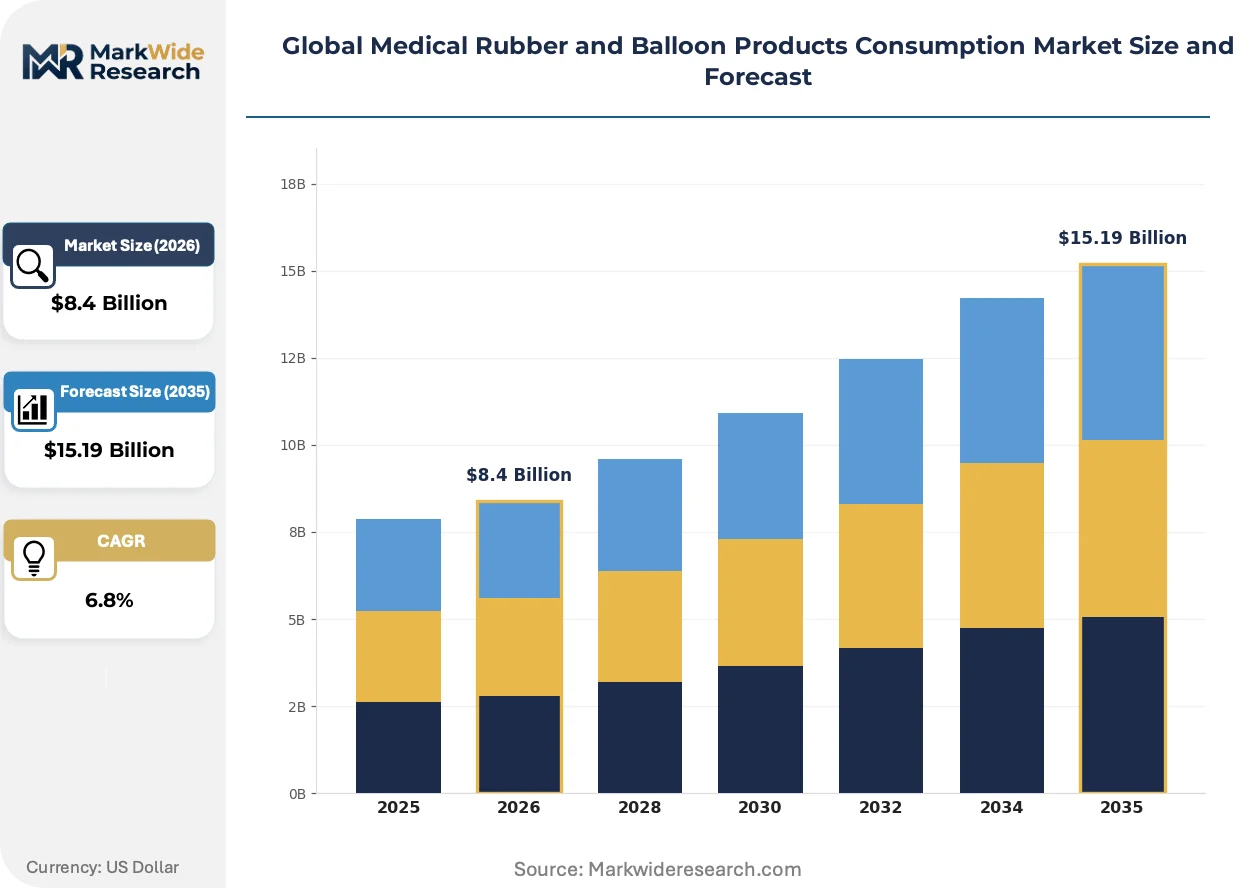
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Catheters, Balloon Catheters, Latex Gloves, Surgical Tubing, Balloon Devices Application Area: Cardiology, Urology, Gastroenterology, Pulmonology, Neurology End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Specialty Clinics Material Type: Natural Rubber, Synthetic Rubber, Silicone Rubber, Neoprene, Butyl Rubber |
| Companies Covered | Abbott Laboratories, B. Braun Melsungen, Cardinal Health, Boston Scientific Corporation, AngioDynamics, Ansell Healthcare, Adventa Berhad, Hartalega, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Rubber and Balloon Products Consumption Market Shifts & Advancements
Material science convergence with digital manufacturing is redefining precision, traceability, and customization capabilities across elastomer-based medical device production.
Smart balloon catheter systems embedding pressure sensors and flow monitors are digitizing real-time procedural feedback for electrophysiology labs and interventional cardiology suites. Hospitals in the United States and Germany are piloting these connected devices to reduce fluoroscopy exposure and improve dilation endpoint determination. The technology is digitizing clinical workflow documentation and enabling outcome-based reimbursement pilot programs.
REACH Annex XVII restrictions on N-nitrosamines in rubber products are forcing reformulation of accelerators and vulcanization agents across latex and synthetic polyisoprene glove manufacturing. Compounders serving the European market are validating alternative cross-linking chemistries to maintain CE marking compliance. Surgical tubing and implantable balloon structures face extended material qualification timelines as suppliers document substance migration profiles.
Hospital procurement consortia are consolidating balloon catheter purchasing through centralized tenders that unbundle device pricing from procedure support services. Academic medical centers in Japan and the United States are driving this aggregation, pressuring manufacturers to absorb clinical training and field technical support costs. The shift is most visible in cardiology departments where electrophysiology lab standardization programs favor single-source balloon supply agreements.
Global Medical Rubber and Balloon Products Consumption Market Segmentation
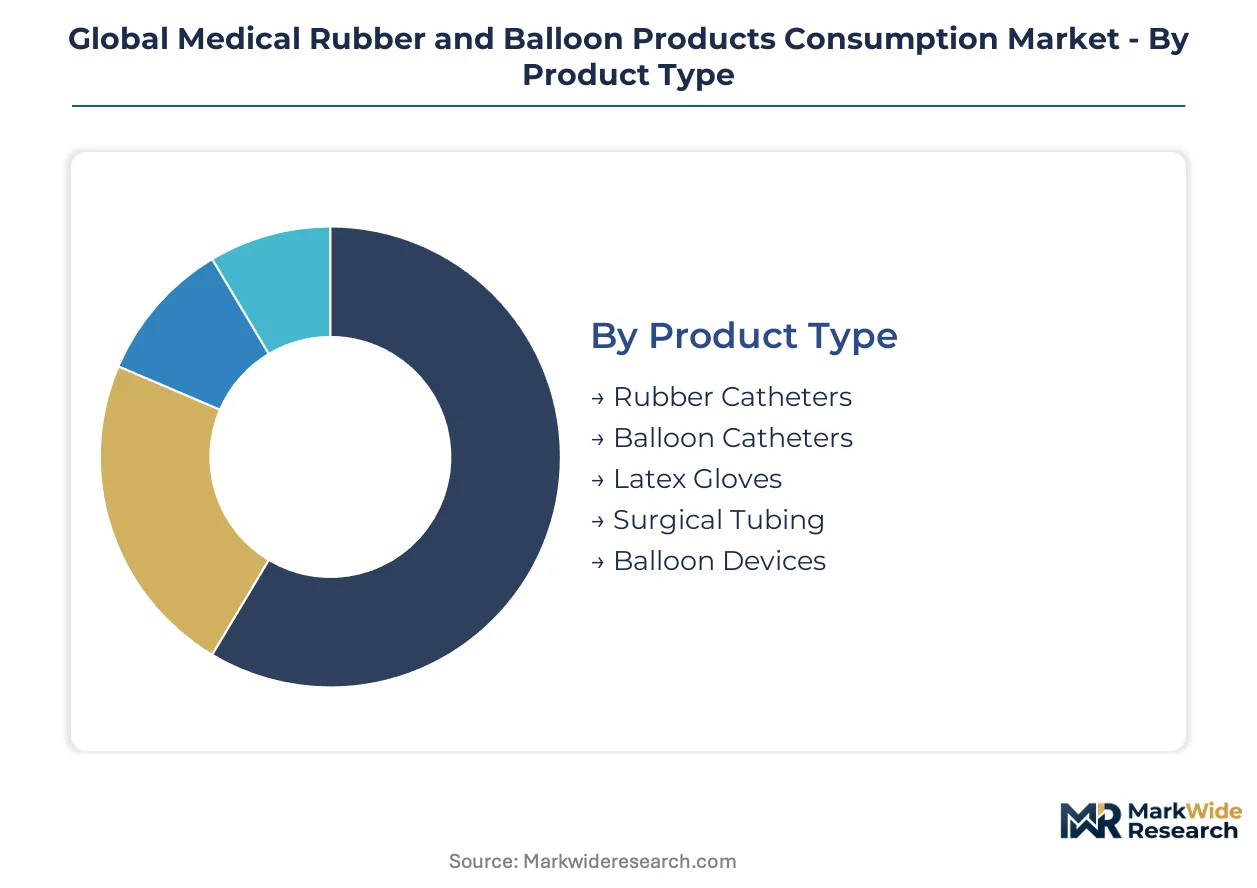
Elastomer-based medical devices fragment across multiple technical dimensions, each carrying distinct regulatory pathways, margin profiles, and service requirements. Understanding these divides reveals where procurement consolidation concentrates and where specialized suppliers defend position.
Product Type:
After-sales service intensity varies sharply across product categories, with balloon catheters demanding field technical support and procedure training while commodity gloves operate on volume logistics alone.
- Balloon Catheters:Polyethylene terephthalate or nylon-blend constructs inflate to rated burst pressures for vessel dilation and stent deployment. Demand concentrates in electrophysiology labs across Germany, Japan, and the United States where cardiac intervention volumes track elderly population expansion.
- Rubber Catheters:Natural rubber latex and synthetic polyisoprene formulations serve drainage and irrigation functions across urology and general surgery. Procurement is consolidating through hospital consortia tenders that absorb clinical training costs into device pricing.
- Latex Gloves:Examination and surgical-grade barrier protection dominates high-turnover consumption in infection control protocols.
- Surgical Tubing:Peristaltic pump compatibility and kink resistance specifications serve anesthesia and perfusion applications.
- Balloon Devices:Occlusion and occlusion-release systems for pulmonology and gastroenterology channels require burst integrity validation under ISO 10993 protocols.
Balloon catheters hold the largest share; momentum sits with balloon devices as neurology and gastroenterology channels expand.
Application Area:
Cost tier stratification separates premium interventional cardiology from commoditized diagnostic applications, with reimbursement rates determining elastomer grade selection.
- Cardiology:Percutaneous coronary intervention and electrophysiology procedures drive compliant and non-compliant balloon demand. Japan's aging demographics and Germany's hospital system consolidation sustain procedural volume concentration.
- Urology:Foley and intermittent catheterization represents mature volume consumption where silicone-to-thermoplastic elastomer conversion compresses manufacturing costs.
- Gastroenterology:Dilatation balloons for stricture management exploit silicone rubber's chemical inertness for extended implant tolerance.
- Pulmonology:Bronchial occlusion and stent deployment balloons require profile minimization for navigational access.
- Neurology:Embolectomy and flow-directed catheter balloons represent emerging indications with extended regulatory pathways.
Cardiology commands premium positioning; gastroenterology is climbing the fastest as silicone formulations penetrate underpenetrated stricture management.
End User:
Customer type determines purchasing modality, with academic medical centers driving standardization programs while ambulatory settings prioritize inventory velocity.
- Hospitals:Integrated delivery networks in the United States and Japan centralize balloon catheter procurement through single-source agreements. Electrophysiology lab standardization programs bundle device supply with clinical education and field technical support.
- Ambulatory Surgery Centers:Cost-sensitive outpatient settings favor synthetic polyisoprene gloves and commoditized catheters over premium silicone formulations.
- Diagnostic Laboratories:Specimen handling and phlebotomy glove consumption tracks testing volume without procedure complexity.
- Specialty Clinics:Urology and gastroenterology-focused practices source procedure-specific devices through distributor networks rather than direct manufacturer contracts.
Hospitals hold the largest share; specialty clinics are gaining share fastest as procedure migration accelerates.
Material Type:
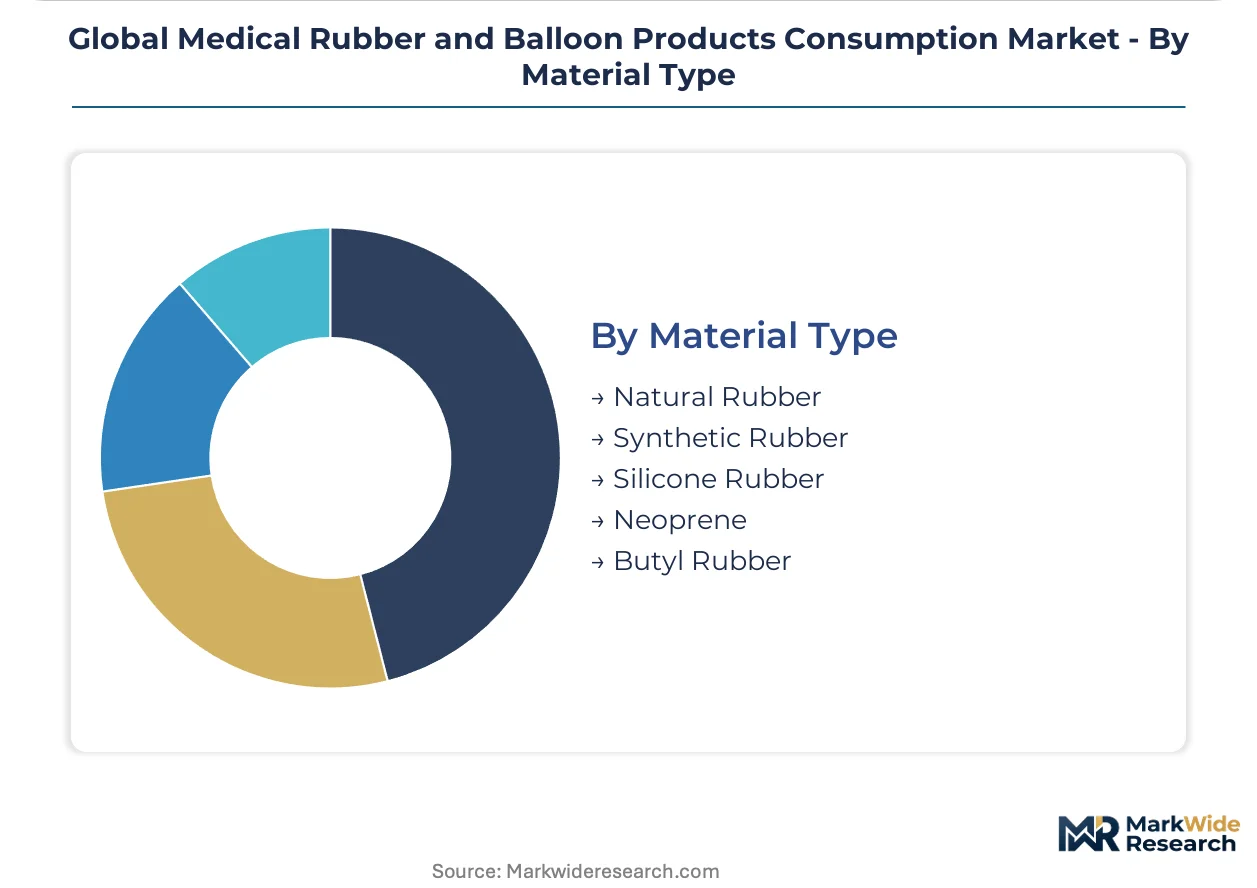
Supply concentration shapes competitive dynamics, with natural rubber latex vulnerable to plantation disruptions and synthetic alternatives commanding formulation expertise premiums.
- Silicone Rubber:Platinum-cured formulations deliver superior biocompatibility for long-dwell implants and drug-device combination products. FDA and EMA tightening of material purity thresholds accelerates R&D investment in next-generation grades.
- Natural Rubber:Hevea brasiliensis latex maintains cost advantage in examination gloves despite protein allergen concerns driving synthetic substitution.
- Synthetic Rubber:Polyisoprene and styrene-butadiene alternatives capture allergy-sensitive segments with processing characteristics matching natural latex.
- Neoprene:Chloroprene formulations serve chemical resistance applications in industrial-medical crossover segments.
- Butyl Rubber:Isobutylene-isoprene copolymers provide gas impermeability for pharmaceutical stopper and syringe plunger applications.
Natural rubber holds the largest share; silicone rubber shows steepest expansion trajectory as implantable indications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia exports examination gloves to hospital procurement networks across the United States and Germany. Japan imports balloon catheters for electrophysiology labs serving aging patient populations. Trade corridors between Southeast Asian rubber processors and Western medical device distributors sustain material flow across the value chain.
United States
Hospital procurement consortia centralize balloon catheter purchasing through single-source agreements bundling device supply with clinical training. FDA 21 CFR Part 820 quality system regulations impose escalating compliance burdens on manufacturers seeking market access. Electrophysiology lab standardization programs in academic medical centers favor integrated delivery network contracts.
Germany
Hospital system consolidation sustains procedural volumes for percutaneous coronary intervention and peripheral vascular procedures. EU MDR technical documentation requirements accelerate R&D investment in next-generation biocompatible elastomers for implantable devices. Manufacturing clusters in Baden-Württemberg concentrate precision balloon molding capabilities for cardiovascular applications.
Japan
Aging demographics drive cardiac intervention rates and sustain demand for compliant and non-compliant balloon catheters. PMDA maintains distinct pharmaceutical and medical device classification pathways that shape registration strategies for multinational suppliers. Tokyo and Osaka metropolitan areas concentrate electrophysiology lab networks standardizing on premium-tier device supply.
Malaysia
Natural rubber latex plantation supply supports high-volume examination glove production for infection control protocols. EUDAMED registration timeline uncertainty complicates EU market entry planning for rubber product exporters. Klang Valley manufacturing zones dominate disposable glove supply to Southeast Asian hospital procurement networks.
China
Domestic medical device consumption expands as hospital infrastructure upgrades accelerate in tier-one cities. NMPA regulatory pathways govern material selection and biocompatibility testing for silicone rubber implantable devices. Yangtze River Delta industrial clusters concentrate polymer processing capabilities for catheter and surgical tubing production.
Global Medical Rubber and Balloon Products Consumption Market Competitive Landscape
On the supply side, the industry is tiered between multinational device manufacturers with captive balloon molding capabilities and specialized elastomer compounders serving commoditized segments. Vertically integrated cardiology specialists compete with independent rubber processors on divergent axes of regulatory sophistication and manufacturing scale. Two strategic archetypes dominate: premium-tier interventional device suppliers with proprietary compliant balloon technologies, and high-volume disposable glove manufacturers leveraging plantation-proximate raw material access. Competitive moves concentrate on backward integration into polymer compounding and strategic partnerships with academic medical centers for clinical validation.
Among US-based multinationals, Abbott Laboratories and Boston Scientific Corporation occupy positions within the premium interventional tier, exemplifying vertically integrated balloon molding capabilities that secure catheter supply security for electrophysiology labs. Hartalega represents the scale-driven disposable segment, anchoring high-volume latex and nitrile examination glove supply to hospital procurement networks across Southeast Asia.
| Leading Market Players |
|---|
| Abbott Laboratories |
| B. Braun Melsungen |
| Cardinal Health |
| Boston Scientific Corporation |
| AngioDynamics |
| Ansell Healthcare |
| Adventa Berhad |
| Hartalega |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
Klang Valley manufacturing zones concentrate examination glove production capacity, translating plantation-proximate latex access into margin leverage for Malaysian exporters serving German and US hospital procurement networks. Balloon catheter pricing power concentrates with vertically integrated device manufacturers holding captive molding capabilities, while commodity rubber segments face cost compression from thermoplastic elastomer substitution.
Pricing Analysis
Next-generation silicone-to-thermoplastic elastomer conversion widens the pricing gap against legacy natural rubber formulations across cardiovascular and urology catheter segments. Three-tier pricing structure across premium, standard, and economy levels separates platinum-cured silicone implants from synthetic polyisoprene alternatives and commodity latex drainage devices. Cost compression in standard-tier catheters is intensifying because hospital procurement consortia unbundle clinical training from device pricing. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers in Japan and Germany absorb premium tiers for electrophysiology lab standardization programs.
Supply Chain Analysis
US export controls on advanced polymer processing equipment constrain balloon molding capability transfers to emerging manufacturing hubs, preserving capacity concentration in Baden-Württemberg clusters and US medical device corridors. Malaysia, Thailand, and Indonesia anchor natural rubber latex supply for examination glove production. Klang Valley compounders draw from Hevea brasiliensis plantation networks and petroleum-based synthetic polyisoprene feedstocks. Single-source vulnerability concentrates in specialized thin-wall extrusion technician pools. Distribution runs through hospital procurement consortia and group purchasing organizations consolidating catheter purchasing across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from field technical support and clinical education contracts expands faster than hardware margins as hospital standardization programs bundle procedure training with balloon catheter supply agreements.
For Market Incumbents: Harden supply security through backward integration into platinum-cured silicone compounding and balloon molding capacity expansion in Germany or Japan. Thermoplastic elastomer substitution in short-dwell applications threatens commoditized catheter margins; defend position through proprietary compliant balloon R&D and electrophysiology lab exclusive supply contracts. For New Entrants and Emerging Players: Neurology and gastroenterology silicone balloon devices for extended-implant tolerance represent the most penetrable entry point, with Japan PMDA combination product pathways offering streamlined registration. Target specialty clinics migrating procedures from hospital settings through distributor partnerships emphasizing inventory velocity and procedure-specific device bundles. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital procurement aggregation favors scaled suppliers with captive molding capabilities and regulatory documentation depth. Acquisition target archetype: mid-tier catheter manufacturers with ISO 10993 testing infrastructure and established GPO contracts. Monitor FDA digital health pre-certification pilot expansion as inflection signal for sensor-embedded balloon system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation accelerates next-generation biocompatible elastomer registrations for implantable devices. |
| Hospital System Partnership | Single-source agreements with academic medical centers bundle device supply with electrophysiology lab standardization programs. |
| Software Companion Development | Sensor-embedded balloon delivery systems align with FDA digital health pre-certification frameworks for real-time procedural feedback. |
| Backward Integration | Captive polymer compounding secures material purity compliance under tightening FDA and EMA biocompatibility thresholds. |
| Reimbursement Strategy | Outcome-based pilot programs for connected catheter systems align with Medicare innovation center payment models. |
Research Methodology
A spread of perspectives from electrophysiology lab directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions driving procedural volume forecasts and procurement consolidation patterns. Primary interview insights combined with secondary validation from FDA 510(k) filings, EUDAMED registration databases, CMS Medicare procedure data, and hospital procurement contract disclosures. Bottom-up catheter shipment modeling and top-down healthcare expenditure triangulation anchored value estimates across the analysis window.
Demand-supply-balance framing integrated aging demographic projections, cardiac intervention rate elasticities, and balloon molding capacity constraints across the projection horizon. Segmentation dimensions spanned product type, application area, end user category, and material grade tier. CAGRs derived from logistic diffusion curves for technology substitution and price elasticity-adjusted volume projections. Industry-specific inputs incorporated EU MDR transition timelines and PMDA pharmaceutical-medical device convergence pathways.
Practitioners should monitor EUDAMED database go-live schedules, REACH Annex XVII N-nitrosamine enforcement actions, and thermoplastic elastomer substitution rates for early signals of forecast revision triggers. Material shifts in regulatory classification pathways or breakthrough device designation grants would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Neoprene Rubber Market
Rubber
FKM Elastomers Market
Rubber
Rubber Accelerators Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Polybutadiene Market
Rubber
Cellular Rubber Market
Rubber
Carboxylated Nitrile Rubber Market
Rubber
Global Rubber Vulcanization Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Natural Rubber Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Rubber Ropes Market
Rubber
Global Chloroprene Rubber Market
Rubber
Global Latex Allergy Market
Rubber
Silicone Rubber Market
Rubber
Rubber Wear Liners Market