
 Europe Rubber Hose Market | 2026-2036
Europe Rubber Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rubber Hose Market Intelligence
SAE 100R1AT specification-grade hydraulic assemblies is redrawing procurement standards across European OEM supply chains. Continental AG leverages captive rubber compounding operations to secure compound consistency for high-pressure applications. Semperit AG Holdings anchors its position through specialized extrusion capabilities serving Austrian and German hydraulics markets. Danfoss competes on integrated fitting-and-hose systems that reduce assembly labor for industrial distributors.
Europe rubber hose denotes reinforced elastomeric tubing, typically constructed from synthetic rubber compounds such as nitrile, EPDM, or chloroprene with braided textile or wire reinforcement, designed to convey fluids, gases, or granular materials under pressure across temperatures ranging from minus forty to plus one hundred twenty degrees Celsius. Hydraulic hose commands the deepest margin pool due to pressure-rating certification requirements and replacement-cycle predictability in German and French machinery fleets. Fuel hose faces structural pressure from electrification in automotive applications, while water hose segments in agricultural settings maintain steadier replacement demand across Iberian and Balkan farming operations.
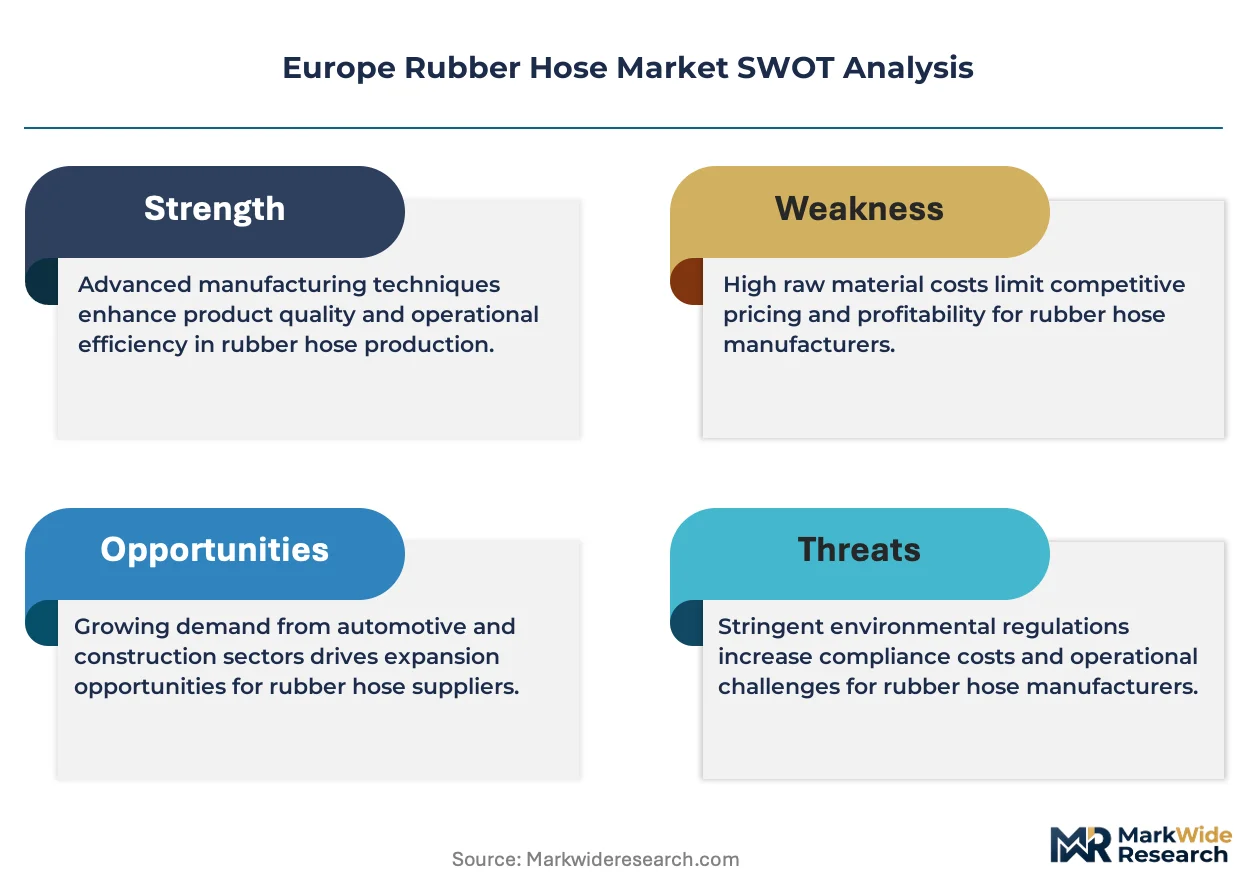
REACH compliance through ECHA governs chemical substance restrictions in rubber compounding, directly elevating formulation costs for non-EU suppliers seeking European market access. The EU Green Deal industrial emissions framework and CE marking under the Machinery Directive jointly shape product testing protocols and cross-border distribution eligibility. Stakeholders must track regulatory divergence between EU harmonized standards and emerging national sustainability mandates in Central European manufacturing hubs.
Market Dynamics
The EU F-Gas Regulation phase-down is forcing rapid fluoropolymer hose substitution across German and French automotive coolant systems, compressing incumbent supply chains while opening formulation gaps for EPDM and bio-based elastomer alternatives.
Growth Catalysts
- Lightweighting mandates:German automotive OEM procurement of reduced-mass coolant hoses intensifies as CO2 fleet targets tighten, pulling aramid-reinforced EPDM formulations into series production.
- REACH compliance elevation:ECHA substance restrictions in rubber compounding elevate technical barriers for non-EU suppliers, securing margin pools for European compounders with certified formulation libraries.
- Hydraulic replacement cycles:Predictable maintenance intervals in German and French machinery fleets create recurring demand for SAE 100R1AT specification-grade assemblies.
Market Restraints
- Raw material volatility:Synthetic rubber feedstock costs fluctuate with crude-derived butadiene and styrene monomer pricing, compressing compounder margins during energy price spikes.
- Electrification displacement:Battery electric vehicle penetration eliminates fuel hose volumes in passenger car segments faster than thermal management hose demand can offset.
- Supply concentration risk:Wire braiding capacity concentrates in Northern Italian manufacturing clusters, creating single-source vulnerability for high-pressure hydraulic reinforcement.
Strategic Opportunities
- Polish industrial corridor expansion:Underpenetrated hydraulics aftermarket in Silesian manufacturing zones offers distributor consolidation potential for specification-grade assemblies.
- EU Green Deal alignment:Industrial emissions framework incentives favor bio-based rubber feedstocks and solvent-free extrusion processes in Austrian and Czech production bases.
- Integrated fitting systems:Crimped assembly standardization reduces field failure rates and captures labor cost savings for Iberian agricultural equipment distributors.
Industry Challenges
- Compound formulation expertise:REACH-compliant EPDM-nitrile blends for sub-zero hydraulic performance require polymer science capabilities scarce in Eastern European manufacturing.
- CE marking timeline compression:Machinery Directive conformity assessment delays product launches for mid-cap suppliers lacking in-house testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rubber Hose Market |
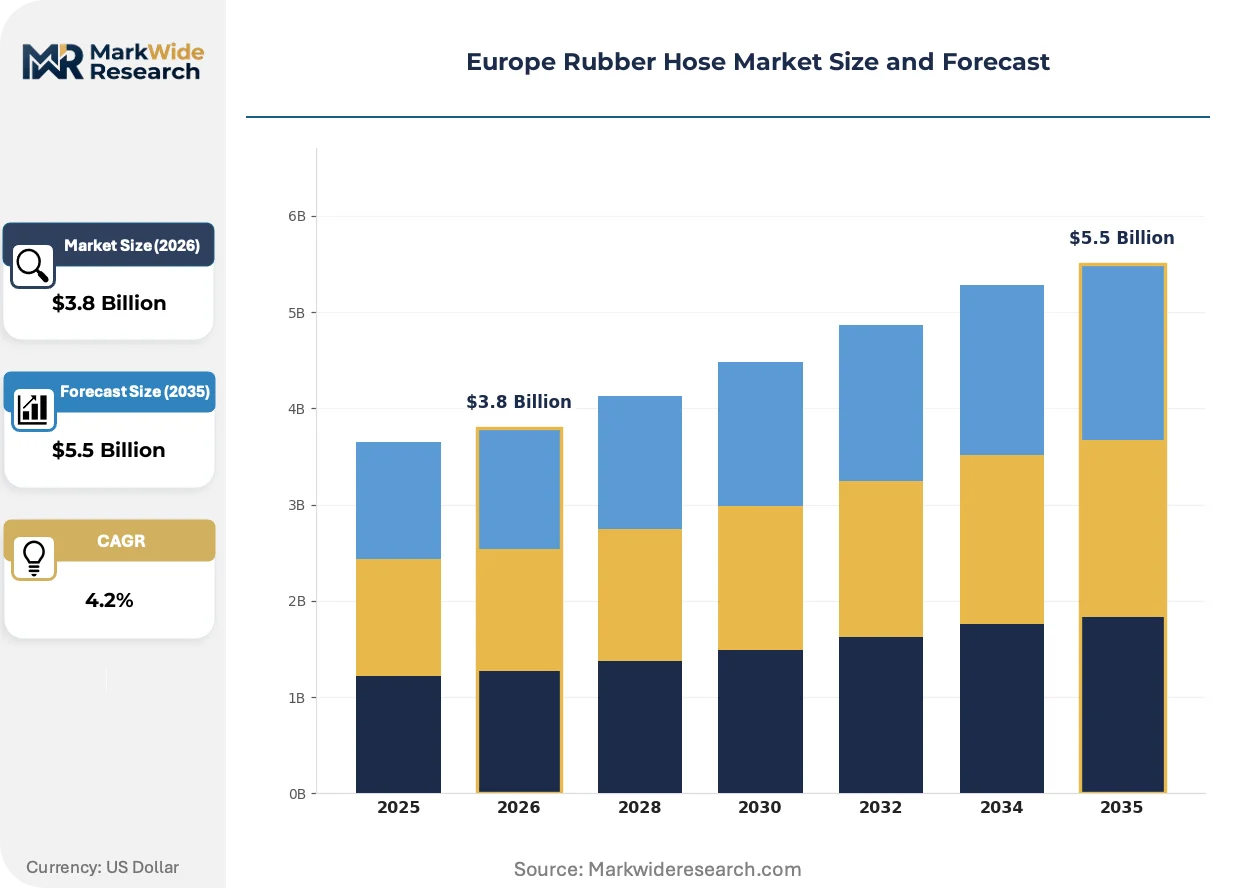
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Hose, Water Hose, Fuel Hose, Hydraulic Hose Application: Automotive, Industrial, Agriculture, Construction End User: Manufacturers, Distributors, Retailers, Service Providers Size: Small, Medium, Large, Extra Large |
| Companies Covered | Manuli Hydraulics, Danfoss, Parker Hannifin Corporation, Tricoflex SAS, Semperit AG Holdings, Continental AG, Gates Corporation, WITZENMANN, Trelleborg Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rubber Hose Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are fragmenting established product hierarchies across European rubber hose supply chains. Three developments merit particular attention.
Aramid fiber reinforcement is bifurcating the high-pressure hydraulic segment. The material delivers 40% weight reduction versus steel wire braiding at equivalent pressure ratings. German construction equipment OEMs specify aramid-reinforced SAE 100R7 thermoplastic hoses for boom lift applications. This substitution compresses traditional wire-braided rubber volumes while elevating compound compatibility requirements for elastomer-to-aramid adhesion.
REACH Annex XVII expansion governs chemical substance restrictions in rubber compounding, directly elevating formulation costs and testing burdens. The regulation forces reformulation of plasticizers and accelerators in nitrile and chloroprene compounds. Non-EU suppliers face extended ECHA notification timelines, advantaging Continental and Semperit with pre-registered substance portfolios.
Buyer consolidation among German automotive Tier-1s compresses supplier rosters and extends contract durations. Procurement teams at Bosch and ZF Friedrichshafen now require five-year compound consistency guarantees and lot-traceable raw material documentation. This behavioral shift favors captive rubber compounding operations over merchant compounders, visible most acutely in powertrain thermal management hose awards.
Europe Rubber Hose Market Segmentation
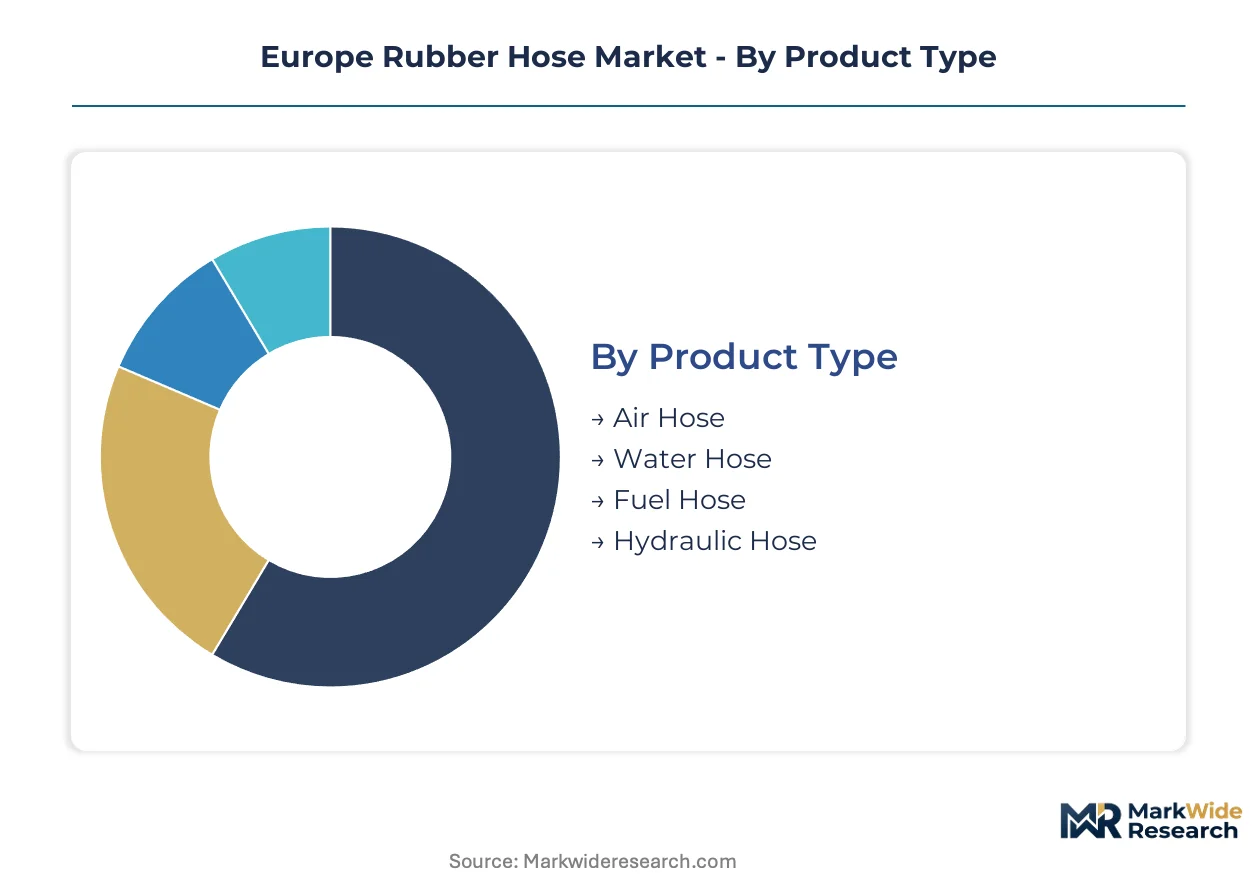
Segmentation in the Europe rubber hose market exposes divergent pressure dynamics across product categories. Substitution threats from thermoplastic alternatives and metal tubing vary sharply by application pressure and temperature requirements.
Product Type:
Hydraulic and fuel hose segments face the most acute substitution pressure from aramid-reinforced thermoplastics and fluoropolymer alternatives under EU F-Gas Regulation compliance mandates.
- Hydraulic Hose:Steel wire-braided or spiral-reinforced constructions rated for 3,000-6,000 PSI operating pressure dominate German and French machinery maintenance cycles. Aramid fiber substitution is compressing traditional rubber volumes in construction equipment OEM specifications.
- Fuel Hose:Nitrile rubber inner tubes with chloroprene covers handle gasoline, diesel, and biofuel permeation resistance. Electrification in German and French passenger car production is eliminating volumes faster than thermal management hose demand offsets.
- Air Hose:EPDM or hybrid rubber-PVC constructions serve compressed air distribution in general industrial settings.
- Water Hose:EPDM or SBR formulations with textile reinforcement convey irrigation and drainage fluids across Iberian and Balkan agricultural operations.
Hydraulic hose retains volume leadership; fuel hose holds the steepest contraction curve.
Application:
Cost tier stratification separates specification-grade OEM supply from price-sensitive aftermarket procurement across European manufacturing corridors.
- Automotive:Coolant, fuel, and brake hose assemblies face lightweighting mandates and REACH formulation constraints. German OEM procurement of aramid-reinforced EPDM coolant hoses intensifies as CO2 fleet targets tighten.
- Industrial:Hydraulic maintenance cycles in German and French machinery fleets generate predictable replacement demand for SAE 100R1AT specification-grade assemblies.
- Construction:High-pressure boom lift and excavator applications specify thermoplastic or hybrid constructions over traditional rubber in German equipment OEM sourcing.
- Agriculture:Irrigation and spraying equipment in Iberian and Balkan farming operations maintains steadier replacement demand for water and chemical-resistant hose constructions.
Automotive commands the deepest margin pool; agriculture offers the most stable volume baseline.
End User:
Customer type determines specification stringency and lot-traceability requirements under REACH and Machinery Directive compliance frameworks.
- Manufacturers:Automotive and machinery OEMs demand five-year compound consistency guarantees and raw material documentation for thermal management and hydraulic system integration.
- Distributors:Industrial hydraulics distributors in German and Austrian markets stock specification-grade assemblies for fleet maintenance contractors.
- Service Providers:Mobile repair operations prioritize crimped fitting standardization to reduce field failure rates.
- Retailers:Agricultural equipment dealers in Iberian markets serve seasonal replacement demand with economy-tier water hose inventories.
Manufacturers concentrate value capture; distributors anchor volume throughput.
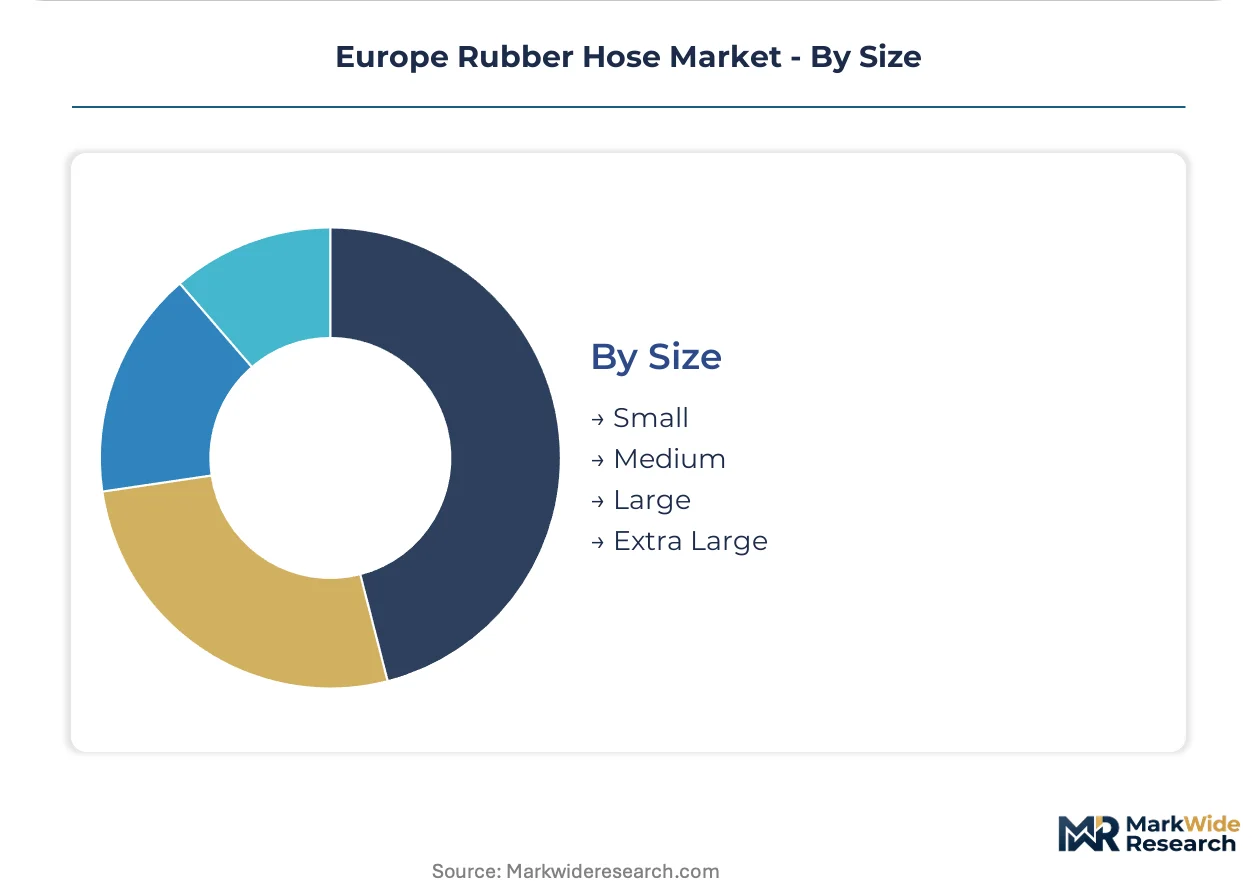
Size:
Supply concentration in Northern Italian wire braiding clusters creates single-source vulnerability for large-diameter high-pressure reinforcement.
- Large:2-4 inch inner diameter hoses for mining and marine suction applications require specialized mandrel extrusion capabilities.
- Extra Large:Above 4 inch diameter constructions for dredging and bulk material handling face limited European compounding capacity.
- Medium:0.5-1.5 inch diameter hydraulic and fuel hoses dominate German automotive and machinery OEM procurement volumes.
- Small:Under 0.5 inch diameter assemblies for precision instrumentation and medical gas applications command premium formulation costs.
Medium diameter retains procurement volume leadership; extra large faces the tightest supply constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's rubber hose trade flows reveal a structural surplus in German and Italian manufacturing against import dependence in Eastern European assembly operations. The region's regulatory chemistry restrictions and automotive OEM proximity create distinct competitive zones.
Germany
Automotive OEM procurement of lightweight coolant hoses and construction equipment specification-grade hydraulics anchors demand. REACH compliance through ECHA elevates technical barriers for non-EU compounders. The Stuttgart industrial corridor concentrates captive rubber compounding operations serving powertrain thermal management systems.
Italy
Wire braiding capacity for high-pressure hydraulic reinforcement clusters in Northern Italian manufacturing zones. CE marking under the Machinery Directive shapes export eligibility for machinery hose assemblies. The Lombardy-Veneto axis supplies reinforcement components across European OEM supply chains.
France
EU F-Gas Regulation phase-down accelerates fluoropolymer hose substitution in automotive coolant systems. Agricultural equipment manufacturers in Auvergne-Rhône-Alpes source chemical-resistant hose constructions for spraying operations. The region's machinery fleet maintenance generates predictable hydraulic replacement cycles.
Poland
Underpenetrated hydraulics aftermarket in Silesian manufacturing zones attracts distributor consolidation plays. The EU Green Deal industrial emissions framework incentivizes solvent-free extrusion process adoption. Warsaw-based distributors increasingly stock specification-grade assemblies for fleet contractors.
Spain
Iberian agricultural operations sustain steadier replacement demand for water and irrigation hose segments. Bio-based rubber feedstock adoption aligns with EU sustainability mandates in Catalan production bases. Valencia and Andalusian equipment dealers serve seasonal replacement cycles with economy-tier inventories.
Europe Rubber Hose Market Key Industry Players
Concentration sits with integrated compounder-manufacturers possessing REACH-certified formulation libraries and captive wire braiding capacity. The market structure tiers across specification-grade OEM suppliers, merchant compounders serving aftermarket distributors, and specialized extrusion houses. Strategic archetypes include backward-integrated rubber compounders, integrated fitting-and-hose system providers, and regional extrusion specialists. Dominant competitive moves center on five-year compound consistency guarantees for automotive Tier-1 procurement and crimped assembly standardization for distributor channel capture.
Among German and Austrian-based fabricators, Continental AG and Semperit AG Holdings exemplify the backward-integrated compounder archetype with captive rubber operations. Danfoss occupies a position on the integrated systems vector, competing through fitting-and-hose combinations that reduce field assembly labor. These three anchors illustrate how regulatory chemistry expertise and manufacturing integration separate premium-tier positioning from merchant supply.
| Leading Market Players |
|---|
| Manuli Hydraulics |
| Danfoss |
| Parker Hannifin Corporation |
| Tricoflex SAS |
| Semperit AG Holdings |
| Continental AG |
| Gates Corporation |
| WITZENMANN |
| Trelleborg Group |
| Others |
Cost & Logistics Intelligence
CE marking under the Machinery Directive gates both supply qualification and price differentiation across European rubber hose markets, forcing non-certified manufacturers into economy tiers while REACH-compliant compounders capture premium positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on SAE 100R1AT certification grade and five-year compound consistency guarantees. Cost compression in standard-tier hydraulic assemblies is intensifying because electrification eliminates fuel hose volumes faster than thermal management demand offsets. Distributor channels show highest price sensitivity; captive compounder operations command least.
Supply Chain Analysis
Germany and Italy anchor high-pressure hydraulic hose manufacturing across Europe. Synthetic rubber feedstock draws from crude-derived butadiene and styrene monomer suppliers. Single-source vulnerability concentrates in Northern Italian wire braiding clusters. Distribution runs through industrial hydraulics distributors serving German and Austrian fleet maintenance contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for REACH-compliant EPDM-nitrile blends represents the critical scarcity asset, separating premium-tier compounders from merchant suppliers unable to meet sub-zero hydraulic performance specifications.
For Market Incumbents: Secure five-year compound consistency guarantees with German automotive Tier-1s before aramid-reinforced thermoplastics displace steel-braided rubber volumes. Deepen backward integration into captive wire braiding capacity to reduce Northern Italian supply concentration risk. Prioritize solvent-free extrusion process investment in Austrian and Czech production bases. For New Entrants and Emerging Players: Anchor in Silesian manufacturing zones where hydraulics aftermarket penetration remains underdeveloped. Target specification-grade assembly distribution for Polish fleet contractors. Differentiate through crimped fitting standardization that reduces field failure rates for agricultural equipment dealers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bio-based rubber feedstock processing. Long-term viability favors compounder-manufacturers with REACH-certified formulation libraries and captive reinforcement capabilities. Watch EU Green Deal industrial emissions framework incentives as the signal for solvent-free extrusion adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive formulation control secures REACH compliance and margin pools against merchant compounders. |
| Aramid Fiber Reinforcement Adoption | Weight reduction specifications from German construction equipment OEMs compress traditional wire-braided volumes. |
| Solvent-Free Extrusion Process Transition | EU Green Deal alignment in Austrian and Czech production bases attracts sustainability-linked procurement. |
| Crimped Assembly Standardization | Reduced field failure rates capture labor cost savings for Iberian agricultural equipment distributors. |
| Distributor Consolidation in Eastern Europe | Silesian manufacturing zones offer underpenetrated hydraulics aftermarket volume capture potential. |
Research Approach
The analysis maps hydraulic hose, fuel hose, air hose, and water hose segments, each validated through procurement directors at German automotive Tier-1s, plant engineers at French machinery OEMs, and aftermarket distributors in Austrian industrial corridors. Primary interviews with rubber compounding specialists, ECHA regulatory consultants, and wire braiding equipment suppliers combined with secondary validation from SEC filings of listed compounders, ECHA substance registration databases, and EU customs trade data. Bottom-up volume modeling and top-down value reconciliation provided cross-check triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, application, end user, and size segmentation dimensions. CAGRs derived from historical trajectory analysis and forward-looking replacement cycle predictability in German and French machinery fleets. Industry-specific forecast inputs included automotive electrification penetration curves and EU F-Gas Regulation phase-down timelines.
Decision-makers should treat outputs as directional under stable regulatory chemistry assumptions; material deviation in REACH Annex XVII expansion scope would warrant model refresh. Forecasts reflect assumptions on raw material cost trajectories and automotive platform electrification rates. Recalibration cycles align with material shifts in EU Green Deal industrial emissions framework implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
FKM Elastomers Market
Rubber
Global Chloroprene Rubber Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Liquid Silicone Rubber Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Nitrile Elastomers Market
Rubber
Rubber Chemicals Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market
Rubber
Global Rubber Additives Market
Rubber
Silica for S-SBR Market
Rubber
Rubber Accelerators Market
Rubber
Rubber Splicing Tape Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Oil Saver Rubber Market