
 Rubber Chemicals Market | 2026-2036
Rubber Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Chemicals Market Outlook
China's rubber chemicals capacity build-out is rewriting regional supply dynamics. LANXESS AG leverages its integrated production base in Jiangsu to serve tire makers across East Asia. KUMHO PETROCHEMICAL anchors Korean supply through captive petrochemical feedstock access. Evonik Industries competes on specialty antioxidant technology for high-performance tire formulations.
Rubber chemicals comprise functional additives including accelerators, antioxidants, fillers, and processing oils that modify vulcanization kinetics, oxidative stability, and mechanical properties of natural and synthetic rubber compounds. These substances typically operate at loadings between 0.5 and 5 parts per hundred rubber, with accelerator classes such as sulfenamides and thiazoles controlling crosslink density for durability in dynamic applications. Accelerators command the largest volume share due to their essential role in sulfur vulcanization across tire and industrial rubber production. Antioxidants generate premium margin pools as thermal and flex-cracking resistance specifications tighten for automotive under-the-hood components. The powder form dominates bulk handling in tire factories, though liquid dispersions are gaining traction in automated mixing operations for process consistency.
China's MEE enforces wastewater discharge limits on rubber chemical plants in Shandong and Jiangsu provinces, raising compliance costs for smaller producers. The EU REACH framework restricts certain amine-based antioxidants, redirecting formulation development toward alternative chemistries. India's BIS certification requirements for rubber chemicals used in domestic tire manufacturing are tightening market access standards. Stakeholders must monitor regulatory divergence between Asian production hubs and European import specifications to align product portfolios with diverging compliance thresholds.
Market Dynamics
REACH restrictions on amine-based antioxidants are forcing tire compounders across Europe to reformulate with alternative chemistries, compressing approval timelines and raising R&D burn rates for chemical suppliers serving automotive OEMs.
Growth Catalysts
- Automotive electrification:Battery electric vehicles require specialized tire compounds with lower rolling resistance, expanding demand for high-performance accelerators and silica coupling agents in passenger vehicle tire manufacturing.
- India's PLI scheme for tire manufacturing:Domestic capacity additions under the production-linked incentive framework are accelerating chemical offtake from local rubber chemical producers serving Apollo Tyres, MRF, and JK Tyre supply chains.
- Sulfenamide accelerator innovation:TBBS and CBS variants with controlled scorch safety are enabling faster vulcanization cycles in automated tire building operations, improving factory throughput for high-volume producers.
Market Restraints
- Aniline feedstock volatility:Crude oil price swings directly impact antioxidant production economics, squeezing margin pools for producers of IPPD and 6PPD grades serving tire makers.
- Shandong supply concentration:China's rubber chemical manufacturing clusters face recurring environmental compliance shutdowns under MEE wastewater discharge enforcement, creating supply intermittency for export markets.
- REACH substance restrictions:ECHA evaluations of certain thiazole derivatives are limiting formulation flexibility for European tire compounders, redirecting development resources toward unproven alternative accelerator classes.
Strategic Opportunities
- Indonesia tire manufacturing expansion:Bridgestone, Michelin, and Goodyear are localizing production to serve ASEAN automotive assembly, creating greenfield demand for accelerator and antioxidant supply contracts.
- Silica-rubber coupling technology:Organosilane chemistry integration with precipitated silica is enabling fuel efficiency gains in passenger tires, opening premium formulation service revenue for specialty chemical suppliers.
- EU Green Deal sustainable chemistry mandates:Bio-based processing oils and renewable-derived antioxidants qualify for preferential procurement scoring in European tire OEM supplier qualification programs.
Industry Challenges
- Vulcanization kinetics modeling expertise:Tire makers require compounders with rheometer interpretation skills to optimize cure systems for multi-layer tire architectures, creating talent scarcity in technical service functions.
- BIS certification timelines:India's mandatory quality standards for rubber chemicals used in domestic tire production extend product approval cycles, delaying market entry for new supplier qualifications.
- Legacy mixing equipment compatibility:Liquid dispersion formats for automated batching require capital retrofit of powder-handling infrastructure at older tire factories, slowing process consistency adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Chemicals Market |
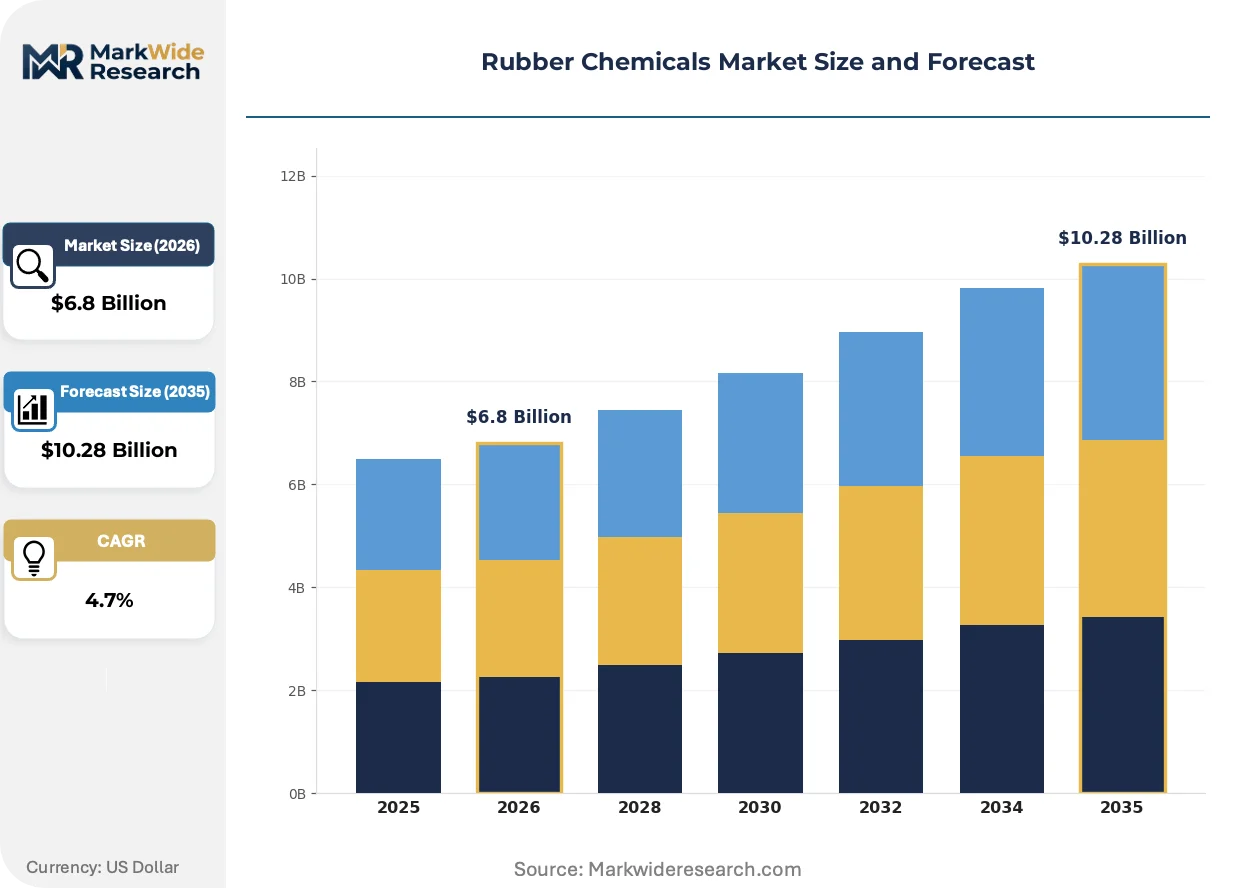
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerators, Antioxidants, Fillers, Processing Oils Application: Automotive, Footwear, Industrial Goods, Consumer Products End User: Manufacturers, OEMs, Distributors, Retailers Form: Powder, Liquid, Granules, Paste |
| Companies Covered | LANXESS AG, Evonik Industries, SI Group, Nocil Limited, Akrochem Corporation, Sennics Co., Ltd., R.T. Vanderbilt, KUMHO PETROCHEMICAL, Eastman Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Chemicals Market Strategic Shifts
Digitalization of compound development and sustainability-driven chemistry substitution are compressing traditional formulation cycles while opening new technical service revenue models for specialty chemical suppliers.
Pre-dispersed rubber chemical masterbatches is hybridizing solid additive delivery with polymer-bound carrier systems, enabling dust-free handling and improved dispersion uniformity. Tire makers in Germany and Japan are adopting these formats for critical accelerator and antioxidant loadings in high-performance tire lines. This technology is hybridizing batch-to-batch consistency metrics with reduced workplace exposure compliance, compressing quality variance in automated mixing halls.
REACH authorization requirements for substances of very high concern are tightening downstream notification obligations for tire compounders using certain antioxidant classes. The European Chemicals Agency's 2024-2025 evaluation roadmap specifically targets amine-based thermal stabilizers common in truck tire formulations. German and Italian tire manufacturers are accelerating alternative chemistry validation programs to maintain uninterrupted EU market access for their finished products.
Direct supplier engagement models are replacing traditional distributor relationships as tire makers consolidate qualified chemical vendor lists and demand integrated technical service support. Compound development laboratories at major tire manufacturers now expect rheological testing collaboration and cure system optimization from their chemical partners. This pattern is most visible in South Korea and Thailand, where Hankook, Kumho, and Thai tire producers have reduced their approved supplier bases while deepening technical integration with retained partners.
Rubber Chemicals Market Segmentation
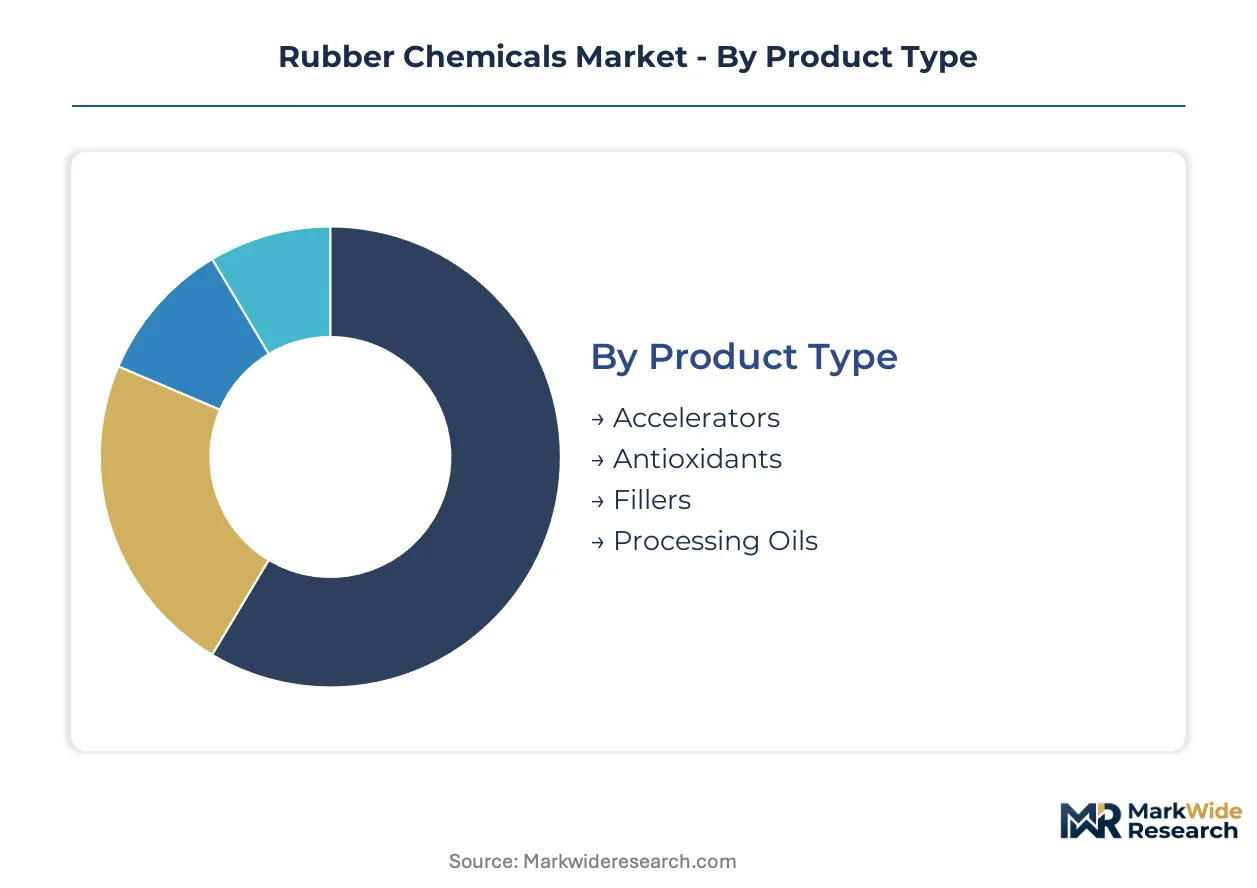
Rubber chemicals serve distinct functional roles across vulcanization kinetics, oxidative stability, and mechanical property modification. Segmentation reveals how formulation requirements diverge between high-volume tire manufacturing and specialized industrial applications.
Product Type:
Accelerator compounds span sulfenamide and thiazole chemistries for sulfur crosslink control, while antioxidant classes address thermal degradation protection across dynamic service conditions.
- Accelerators:TBBS and CBS variants control scorch safety and cure rate in tire manufacturing. Southeast Asian tire producers are expanding procurement of these compounds to serve automotive OEM supply chains under tightening vulcanization cycle requirements.
- Antioxidants:IPPD and 6PPD grades protect against flex-cracking and thermal oxidation in truck tire formulations. REACH restrictions on amine-based chemistries are forcing European compounders toward alternative thermal stabilizer development.
- Fillers:Carbon black and precipitated silica reinforce mechanical properties at loadings of 30-60 parts per hundred rubber.
- Processing Oils:Aromatic and naphthenic oils improve processability and low-temperature flexibility in compound mixing operations.
Established volume favors accelerators; emerging adoption favors silica coupling agent integration for fuel efficiency specifications.
Application:
End-use differentiation tracks load-bearing intensity, with automotive applications demanding dynamic durability under cyclic stress.
- Automotive:Passenger and commercial vehicle tires require specialized accelerator systems for multi-layer architectures. Battery electric vehicle platforms are expanding demand for low rolling resistance compounds using silica-rubber coupling technology.
- Industrial Goods:Conveyor belts, hoses, and seals operate under continuous mechanical stress with extended service life requirements. Mining and construction equipment OEMs in India are accelerating chemical offtake from domestic capacity additions.
- Footwear:Soling compounds utilize processing oils and fillers for abrasion resistance and comfort properties.
- Consumer Products:Sporting goods and household items employ lower loadings of functional additives for cost-optimized performance.
Automotive applications command premium formulation margins; industrial goods represent the steepest expansion trajectory in emerging manufacturing hubs.
End User:
Procurement patterns bifurcate between integrated tire manufacturers seeking technical service partnerships and distributor-mediated access for smaller compounders.
- Manufacturers:Tire makers consolidate qualified vendor lists while demanding rheological testing collaboration and cure system optimization from retained chemical partners.
- OEMs:Automotive assemblers specify compound performance standards that cascade through tiered supplier qualification programs.
- Distributors:Regional chemical traders serve smaller rubber processors with fragmented demand profiles across industrial and consumer segments.
- Retailers:Aftermarket channels supply replacement tire and repair compound markets through packaged additive formulations.
Direct supplier engagement is displacing traditional distributor relationships among high-volume tire producers; distributor networks retain relevance for geographically dispersed industrial accounts.
Form:
Physical format selection balances dust exposure compliance, automated handling compatibility, and dispersion uniformity requirements.
- Powder:Dominates bulk handling in high-volume tire factories with established pneumatic conveying infrastructure.
- Liquid:Dispersions enable automated batching consistency in modern mixing operations. German and Japanese tire manufacturers are adopting these formats for critical accelerator loadings in high-performance product lines.
- Granules:Dust-reduced formats improve workplace exposure metrics while maintaining conventional handling equipment compatibility.
- Paste:Pre-dispersed masterbatches polymer-bound for improved dispersion uniformity in specialty compound applications.
Powder retains cost advantage in legacy infrastructure; liquid formats are gaining share fastest in greenfield automated facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE wastewater discharge enforcement anchors supply-side dynamics, while formulation standards diverge across manufacturing hubs. Tire capacity expansion in India and Southeast Asia redirects chemical procurement flows. Regulatory fragmentation between REACH restrictions and emerging Asian certification requirements shapes regional competitive positioning.
China
Shandong and Jiangsu provinces concentrate rubber chemical manufacturing capacity serving domestic tire production. MEE enforcement of wastewater discharge limits raises compliance costs for smaller producers, triggering intermittent supply shutdowns. Qingdao-based tire makers expand accelerator procurement to supply automotive OEM export contracts.
Germany
REACH authorization requirements for amine-based antioxidants force reformulation across tire compounders serving premium automotive OEMs. ECHA's 2024-2025 evaluation roadmap specifically targets thermal stabilizers common in truck tire formulations. Cologne and Leverkusen anchor specialty chemical R&D clusters developing alternative antioxidant chemistries.
India
PLI scheme incentives accelerate domestic tire capacity additions by Apollo Tyres, MRF, and JK Tyre, expanding chemical offtake from local producers. BIS certification requirements for rubber chemicals extend product approval cycles for new supplier qualifications. Gujarat and Maharashtra host expanding manufacturing clusters for accelerator and antioxidant production.
United States
EPA emissions standards and OSHA workplace exposure regulations shape rubber chemical handling protocols at tire manufacturing facilities. NHTSA fuel efficiency mandates cascade through OEM supplier qualification programs, expanding silica coupling agent demand. Southeast automotive assembly corridors in Tennessee and South Carolina concentrate tire plant investment.
Indonesia
Bridgestone, Michelin, and Goodyear localize production to serve ASEAN automotive assembly, creating greenfield demand for accelerator supply contracts. Domestic regulatory frameworks for chemical imports remain less stringent than REACH or GB standards. Java-based manufacturing zones attract regional distribution hub investment from chemical suppliers.
Rubber Chemicals Market Competitive Environment
Integrated petrochemical conglomerates and specialty chemical innovators split the market between scale-driven commodity supply and premium formulation services. The vendor base organizes around three archetypes: captive feedstock-integrated producers, technology-specialized antioxidant developers, and regional manufacturing specialists serving proximate tire clusters. Consolidation pressures intensify as tire makers reduce approved supplier lists while demanding integrated technical support. Capacity expansion and direct supplier engagement models represent the dominant competitive moves reshaping commercial relationships.
Within the integrated petrochemical tier, LANXESS AG and KUMHO PETROCHEMICAL exemplify archetypes anchored by captive production bases and feedstock access. Evonik Industries occupies a position representing specialty antioxidant technology development for high-performance applications. These three entities sit within distinct strategic segments: German integrated production, Korean petrochemical-backed supply, and specialty chemical innovation.
| Leading Market Players |
|---|
| LANXESS AG |
| Evonik Industries |
| SI Group |
| Nocil Limited |
| Akrochem Corporation |
| Sennics Co., Ltd. |
| R.T. Vanderbilt |
| KUMHO PETROCHEMICAL |
| Eastman Chemical |
| Others |
Value Chain & Pricing Dynamics
Shandong province's accelerator manufacturing clusters concentrate over half of China's rubber chemical capacity, creating asymmetric pricing power for sulfenamide suppliers serving tire makers across East Asia. MEE wastewater enforcement intermittently idles smaller producers, tightening spot availability and amplifying volatility in contract negotiations with procurement teams at Apollo Tyres and MRF.
Pricing Analysis
Price spreads between Jiangsu and Shandong production hubs reflect compliance cost differentials under MEE discharge limits. Three-tier pricing structure across premium, standard, and economy levels tracks antioxidant purity grades and REACH certification status. Pricing pressure stems from aniline feedstock volatility squeezing IPPD and 6PPD margins. Volume tire manufacturers exhibit highest price sensitivity; specialty compounders serving German automotive OEMs accept premium tiers for technical service integration.
Supply Chain Analysis
Aniline and carbon disulfide feedstock sourcing draws from petrochemical complexes in China, South Korea, and Thailand. Rubber chemical production rests on captive access to these intermediates plus sulfur derivatives from oil refining. Single-source vulnerability concentrates in Shandong environmental compliance exposure. Distribution runs through qualified supplier lists consolidated by Hankook, Kumho, and Thai tire producers replacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery electric vehicle tire specifications are reshaping rubber chemical demand profiles, with silica-rubber coupling technology and low-rolling-resistance accelerators creating formulation discontinuities that favor technical service-integrated suppliers.
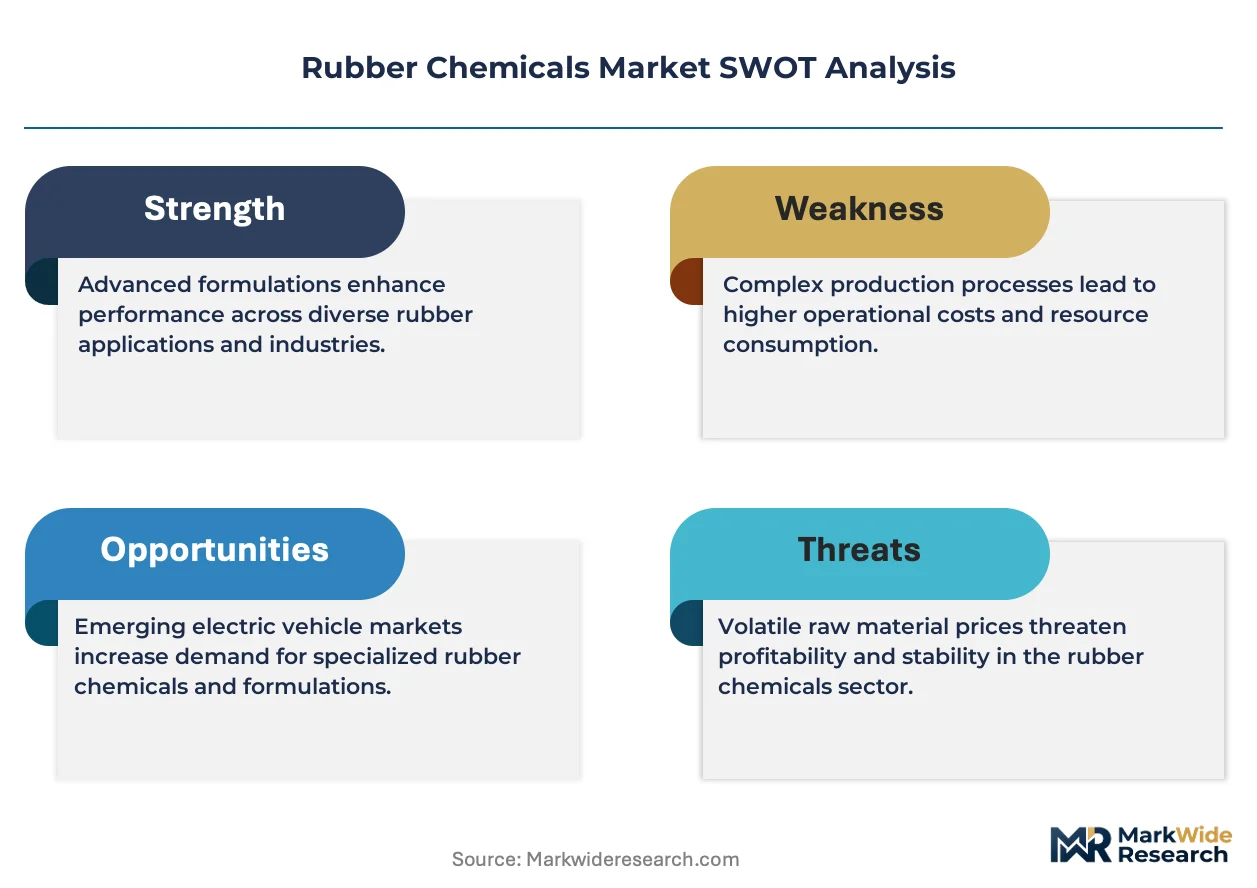
For Market Incumbents: Build regulatory compliance moats by accelerating REACH alternative chemistry validation and securing BIS certification ahead of India's domestic tire capacity expansion. Shandong environmental shutdowns threaten supply continuity; backward integration into aniline feedstock or captive Jiangsu production bases reduces exposure. Deepen rheological testing collaboration with retained tire OEM partners as approved supplier lists contract. For New Entrants and Emerging Players: Indonesia's greenfield tire manufacturing zones represent the most penetrable entry point, with Bridgestone, Michelin, and Goodyear localizing production under less stringent chemical import frameworks than REACH or GB standards. Liquid dispersion formats for automated mixing operations offer differentiation against legacy powder suppliers. Target technical service partnerships with mid-tier ASEAN tire producers seeking cure system optimization expertise. For Investors and Strategic Acquirers: Long-term, this sits as a specialty formulation consolidation play because direct supplier engagement models are displacing distributor relationships and concentrating margin pools with technical service-capable producers. Acquisition targets include regional antioxidant specialists with BIS certification traction and silica coupling agent technology. Monitor ECHA evaluation roadmap announcements for amine-based thermal stabilizers as inflection signals for alternative chemistry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstock | Captive supply from petrochemical complexes insulates margin pools from crude oil volatility affecting IPPD economics. |
| REACH Alternative Chemistry Validation | ECHA substance restrictions on amine-based antioxidants redirect formulation development toward premium-margin thermal stabilizers. |
| Indonesia Greenfield Supply Contracts | Bridgestone and Michelin localization creates first-mover accelerator procurement relationships in ASEAN automotive corridors. |
| Liquid Dispersion Format Expansion | German and Japanese tire manufacturers adopt automated batching consistency for high-performance passenger tire lines. |
| BIS Certification Pre-Positioning | Apollo Tyres and JK Tyre domestic capacity additions under PLI scheme extend approval cycles for uncertified suppliers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical company filings, and ACC industry reports to anchor volume estimates. Primary interviews engaged technical R&D directors at tire manufacturers, procurement leads at downstream OEMs, plant managers at Shandong and Jiangsu production facilities, and distribution channel partners serving fragmented industrial accounts. Bottom-up segment sizing triangulates against top-down trade flow analysis across the analysis window.
Forecast inputs incorporate grade tier differentiation between commodity accelerators and specialty antioxidants, end-use industry splits across automotive tire and industrial rubber applications, packaging format evolution from powder to liquid dispersions, and regional production hub capacity utilization under MEE enforcement. CAGRs derive from elasticity modeling against tire production forecasts and regulatory-driven chemistry substitution rates. Silica coupling agent penetration in BEV tire formulations and BIS certification timeline assumptions shape trajectory outputs.
Practitioners should monitor ECHA authorization decisions, MEE enforcement intensity in Shandong, and aniline price volatility for early signals requiring forecast revision. Cross-checking against IHS Markit tire production databases and ACC capacity utilization surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Liquid Polybutadiene Market
Rubber
Rubber Masterbatch Market
Rubber
Global Latex Allergy Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Conductive Silicone Rubber Market
Rubber
EPDM Market
Rubber
Rubber Compound Market
Rubber
Rubber Block Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Global Cast Elastomers Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
FKM Elastomers Market
Rubber
Recycled Elastomers Market
Rubber
Abrasion-Resistant Rubber Pipe Market
Rubber
Global Rubber Process Oil Market
Rubber
Rubber Valve Stem Market