
 Ethylene Propylene Rubber Cable Market | 2026-2036
Ethylene Propylene Rubber Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Propylene Rubber Cable Market Insights
A capital-intensity divergence between integrated compound producers and pure cable assemblers is reorganizing competitive tiers in the Ethylene Propylene Rubber Cable industry. Prysmian Group leverages captive EPR compounding capacity across Italian and Dutch plants to secure margin on specialty medium-voltage products. Nexans S.A. sustains technical leadership through continuous vulcanization R&D investments at its Lyon facility. LS Cable & System Ltd. anchors Asian supply with integrated rubber extrusion lines serving Korean automotive OEMs.
Ethylene propylene rubber cable denotes insulated conductors using EPM or EPDM elastomer jackets rated for continuous operation between minus 50°C and 150°C, manufactured via continuous vulcanization or steam-cure processes to achieve dielectric stability under thermal stress. Its primary commercial purpose centers on power distribution and automotive wiring where flexibility, ozone resistance, and moisture impermeability outperform thermoplastic alternatives. Medium voltage cables with thermoset insulation dominate installed value due to utility grid hardening cycles, while E-Mobility application cables represent the fastest-expanding margin pool as charging infrastructure scales. Specialty cables with flame-retardant compounding command premium positioning in tunnel and mass-transit deployments where IEC 60332-3-24 compliance is mandatory.
FDA oversight of EPDM feedstock purity in medical-adjacent cable applications, combined with REACH restrictions on process oils and EU Green Deal carbon-border adjustments on imported compound, shapes formulation choices and sourcing geography. China's GB/T standards for rubber-insulated power cables and India's BIS certification requirements for flame-retardant building wire create divergent compliance portfolios for multinational suppliers. Stakeholders must monitor evolving ECHA substance-of-very-high-concern listings for curatives and accelerators that could force compound reformulation mid-decade.
Market Dynamics
Automotive electrification is compressing product development cycles and forcing compound-to-cable integration that rewards captive EPR production over merchant supply. Tier-1 harness suppliers now specify thermal cycling performance thresholds that disqualify generalist cable assemblers.
Growth Catalysts
- GB/T 12706 compliance mandates:China's medium-voltage grid hardening requires thermoset EPR insulation rated for 90°C continuous operation, pulling compound demand toward domestic certified producers.
- EV platform proliferation:Automotive OEMs specify multi-conductor flexible harnesses with ozone and fluid resistance that thermoplastic alternatives cannot match.
- Steam-cure continuous vulcanization:This manufacturing process achieves dielectric stability under thermal stress faster than batch autoclave methods, shortening lead times for utility tenders.
Market Restraints
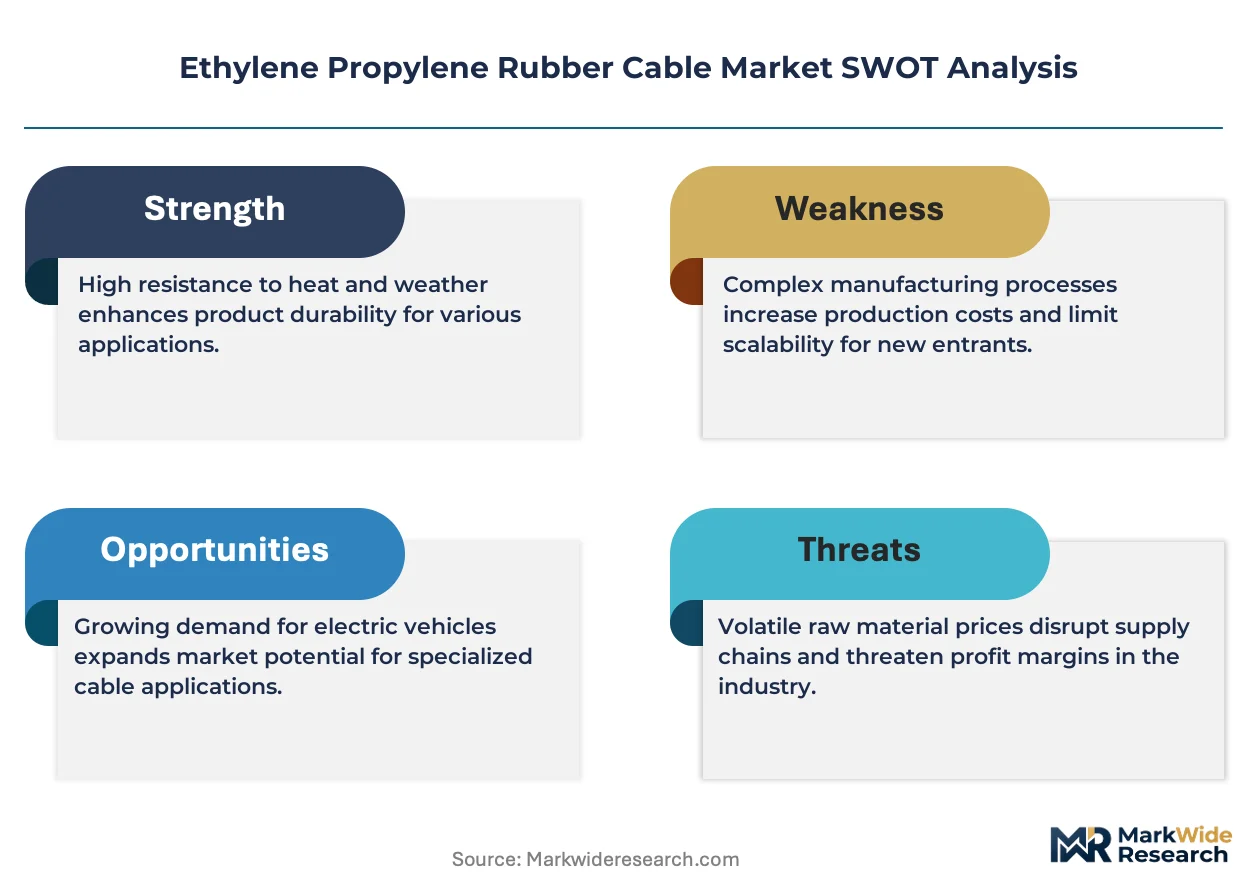
- EPDM feedstock concentration:Ethylene and propylene monomer supply clusters in Gulf Coast petrochemical complexes, exposing compounders to hurricane disruption and feedstock allocation priorities.
- REACH process oil restrictions:ECHA substance-of-very-high-concern listings for aromatic extender oils force reformulation toward pricier paraffinic alternatives.
- Silicone rubber substitution:High-temperature automotive applications above 150°C increasingly specify silicone where EPR thermal ceilings prove inadequate.
Strategic Opportunities
- India BIS certification gap:Domestic flame-retardant building wire capacity lags behind infrastructure targets, creating import substitution potential for EPR-insulated products meeting IS 694 standards.
- EU Green Deal carbon-border adjustments:CBAM phase-in disadvantages imported compound from carbon-intensive production, rewarding European captive EPR compounding investments.
- Wireless charging pad integration:EPR-jacketed flexible power coils for inductive EV charging represent an emerging specification category with limited incumbent supply.
Industry Challenges
- Continuous vulcanization line operators:Skilled technicians capable of calibrating steam-pressure and line-speed parameters for specialty medium-voltage grades remain scarce relative to expansion plans.
- IEC 60332-3-24 certification timelines:Flame-retardant tunnel cable approvals require extended burn-test protocols that delay project revenue recognition by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Propylene Rubber Cable Market |
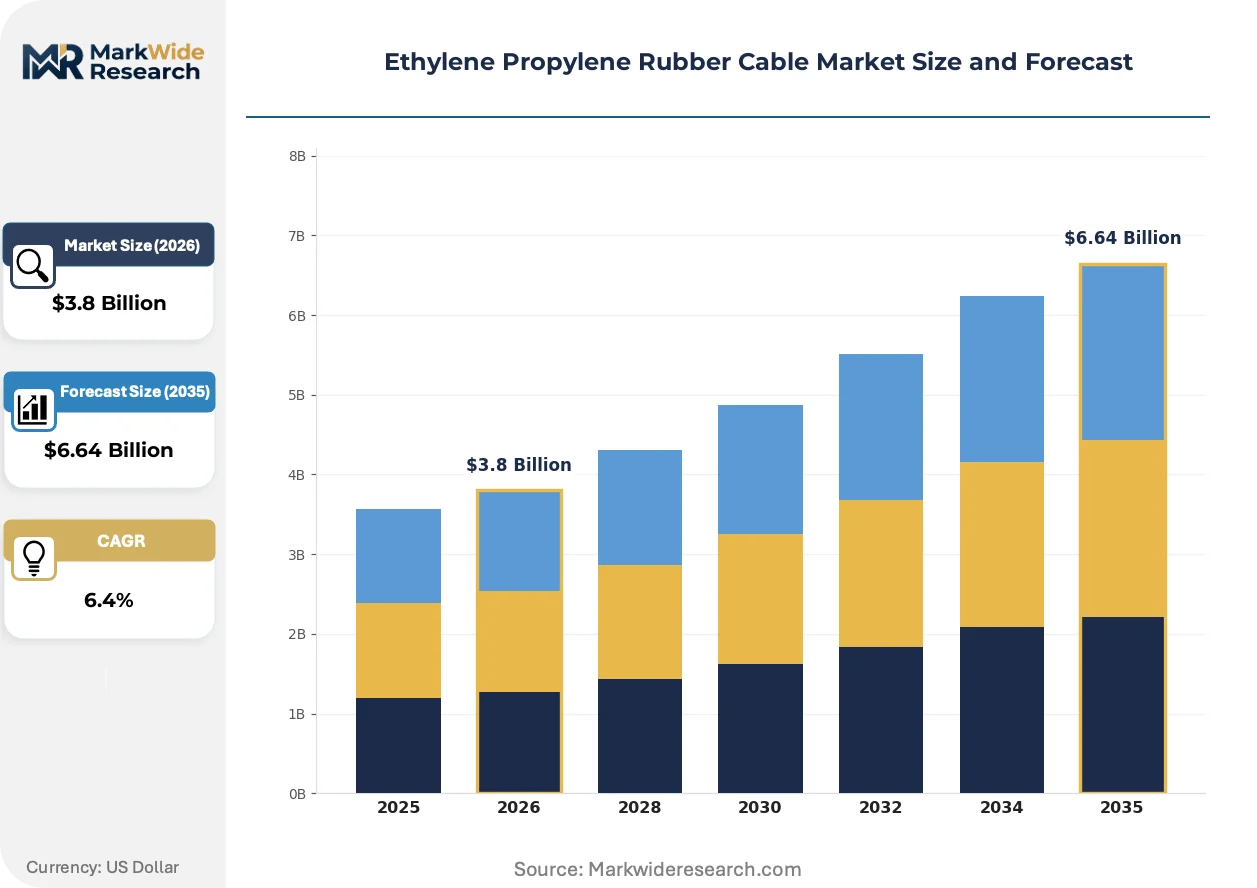
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Specialty Cables End User: Construction, Automotive, Industrial, Telecommunications Insulation Type: Thermoplastic, Thermoset, Composite, Flame-Retardant Application: Power Distribution, Communication, Automotive Wiring, E-Mobility |
| Companies Covered | Prysmian Group, Nexans S.A., LS Cable & System Ltd., Sumitomo Electric Industries, Ltd., Southwire Company, LLC, NKT A/S, Furukawa Electric Co., Ltd., KEI Industries Limited, Polycab India Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Propylene Rubber Cable Market Trends and Innovations
Formulation science and manufacturing control systems are converging to enable lot-size flexibility that was economically impossible under legacy autoclave batch processing. This shift is redrawing competitive boundaries between integrated compounders and cable specialists.
Peroxide-cured EPR compounds with tailored scorch safety profiles are fragmenting the medium-voltage cable market. Utility procurement teams in Germany and South Korea specify these grades for grid hardening projects requiring 40-year thermal aging guarantees. The technology is fragmenting supplier tiers by rewarding in-house compounding capability over merchant purchase.
REACH restrictions on process oils and curatives are tightening formulation latitude across European EPR cable production. ECHA's 2024-2025 SVHC consultation timeline threatens mid-decade reformulation for accelerators currently standard in steam-cure lines. Automotive harness suppliers serving Stuttgart and Munich OEMs are qualifying alternative sulfur-donor systems ahead of anticipated listings.
Buyer concentration among tier-1 automotive harness suppliers is compressing supplier qualification cycles and unbundling technical service from compound supply. Korean and Japanese OEMs now conduct joint compound-cable validation programs that bypass traditional merchant compounder relationships. This pattern is most visible in the Busan and Nagoya automotive clusters where charging infrastructure harness specifications are being locked three years ahead of platform launch.
Ethylene Propylene Rubber Cable Market Segmentation
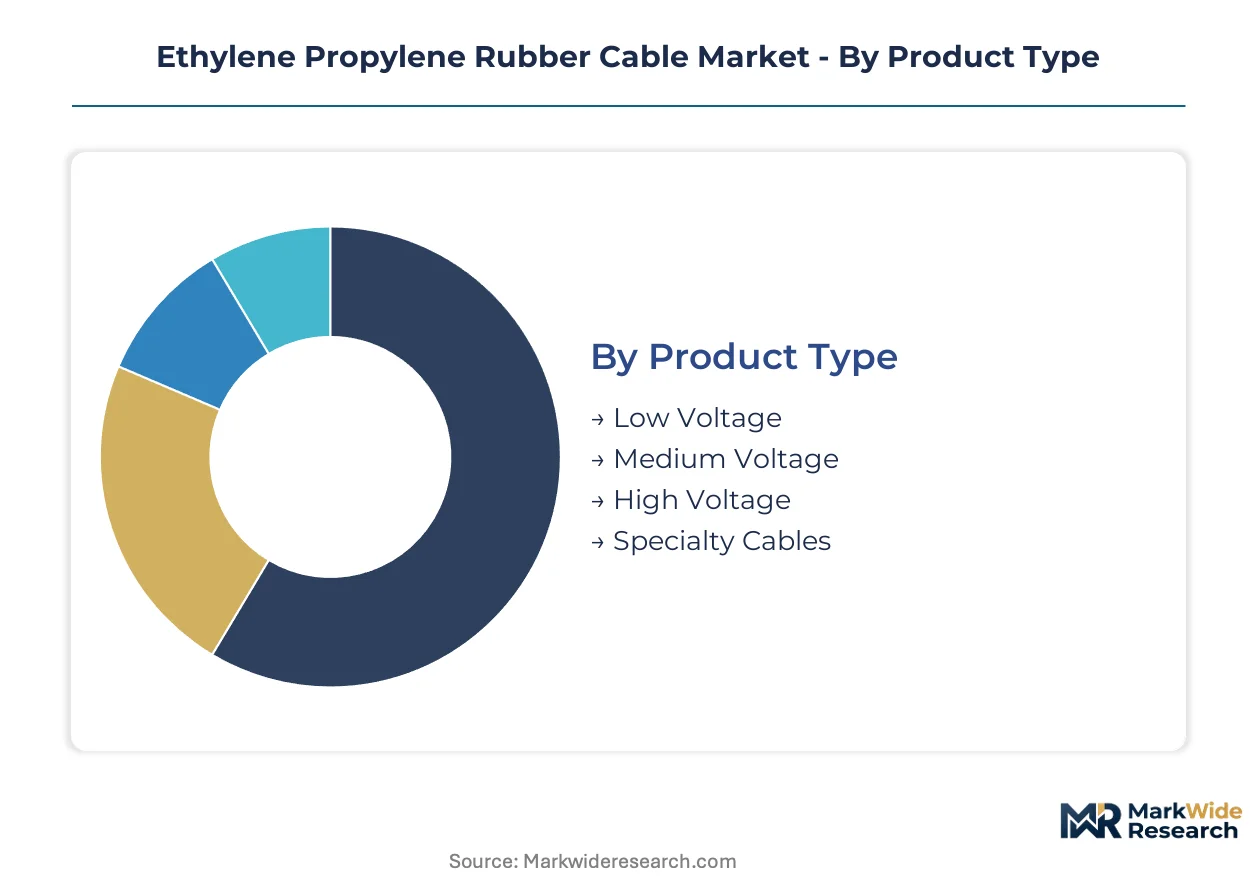
EPR cable market segmentation reveals divergent vulnerability profiles to silicone and thermoplastic substitution. Each dimension exposes distinct pressure points where compound formulation and manufacturing integration determine competitive survival.
Product Type:
Substitution pressure from silicone rubber and cross-linked polyethylene concentrates on thermal ceiling boundaries, with voltage rating serving as the primary defensive moat.
- Low Voltage:EPR-jacketed cables rated below 1 kV face intense thermoplastic PVC competition in building wire applications. Construction sector procurement in India favors cost-optimized PVC for non-critical circuits, compressing EPR to industrial and marine niches where oil resistance is mandatory.
- Medium Voltage:Thermoset EPR insulation dominates 6-35 kV distribution networks through superior dielectric stability under thermal cycling. China's GB/T 12706 grid hardening mandates pull compound demand toward domestic certified producers capable of continuous vulcanization at scale.
- High Voltage:EPR compounds above 66 kV encounter technical displacement by cross-linked polyethylene in submarine and underground transmission. XLPE's lower dielectric loss tips procurement decisions at voltage thresholds where EPR flexibility advantages diminish.
- Specialty Cables:Flame-retardant tunnel cables and nuclear-qualified containment penetrations command formulation premiums. IEC 60332-3-24 certification requirements extend approval timelines, creating supply scarcity for qualified manufacturers.
Medium voltage anchors the volume base while specialty cables gain share at the steepest rate through certification-constrained scarcity.
End User:
Customer concentration patterns fragment procurement power, with automotive OEMs exerting compound-to-cable integration demands that generalist assemblers cannot satisfy.
- Construction:Building wire specifications split across cost-driven PVC and code-mandated EPR for high-rise fire safety. India's BIS IS 694 flame-retardant standards lag domestic capacity, opening import substitution windows for certified EPR suppliers.
- Automotive:Tier-1 harness suppliers specify multi-conductor flexible assemblies with ozone and fluid resistance. Korean OEMs conduct joint compound-cable validation programs that bypass traditional merchant compounder relationships in Busan and Seoul clusters.
- Industrial:Mining and petrochemical operations require abrasion-resistant jackets rated for continuous flexing. EPDM's moisture impermeability outperforms thermoplastic alternatives in submersible pump cables for oilfield applications.
- Telecommunications:Fiber optic power feed cables utilize EPR jacketing for rodent resistance and UV stability. This segment faces silicone displacement in high-temperature aerial deployments.
Industrial applications provide the most stable demand foundation while automotive wiring expands most quickly through platform proliferation.
Insulation Type:
Material chemistry divides the market between recyclable thermoplastics and thermoset durability, with regulatory flame standards increasingly dictating formulation choices.
- Thermoplastic:PVC and TPE compounds offer end-of-life recyclability and lower processing energy. REACH restrictions on plasticizers and halogenated flame retardants narrow formulation latitude for European cable producers.
- Thermoset:Peroxide-cured EPR achieves 40-year thermal aging guarantees required by German and South Korean utility procurement. Steam-cure continuous vulcanization shortens lead times versus batch autoclave methods.
- Composite:Hybrid constructions layer thermoset EPR over thermoplastic cores for cost-optimized performance. These designs concentrate in mass-transit applications where IEC 60332-3-24 compliance must balance material cost with burn-test certification.
- Flame-Retardant:Halogen-free EPR formulations with aluminum trihydrate loading meet tunnel and mass-transit smoke toxicity standards. ECHA SVHC consultations threaten mid-decade reformulation for standard accelerators.
Thermoset insulation commands the value pool while flame-retardant grades climb the fastest through regulatory mandate expansion.
Application:
Use-case thermal and mechanical stress profiles determine whether EPR's flexibility premium justifies cost displacement by alternative elastomers.
- Power Distribution:Utility grid hardening cycles in China and Germany specify medium-voltage thermoset cables for underground residential distribution. Peroxide-cured compounds with tailored scorch safety profiles fragment supplier tiers by rewarding in-house compounding capability.
- Communication:Coaxial and fiber optic power feeds utilize EPR jacketing for environmental sealing. This application faces silicone substitution in high-temperature aerial deployments above 150°C.
- Automotive Wiring:Engine compartment harnesses specify fluid-resistant EPDM jackets where thermoplastics degrade under oil exposure. Stuttgart and Munich OEMs are qualifying alternative sulfur-donor curing systems ahead of anticipated ECHA listings.
- E-Mobility:Charging infrastructure cables and wireless charging pad power coils represent emerging specification categories. EPR-jacketed flexible conductors for inductive EV charging encounter limited incumbent supply.
Power distribution provides the installed value base while E-Mobility applications gain share at the steepest rate through infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement teams in Germany and South Korea accept premium pricing for peroxide-cured compounds with 40-year thermal aging guarantees. Construction buyers in India and Brazil remain acutely price-sensitive, favoring PVC alternatives where building codes permit.
China
GB/T 12706 grid hardening mandates pull compound demand toward domestic certified producers capable of continuous vulcanization at scale. The country's dual carbon goals accelerate underground residential distribution projects requiring thermoset EPR insulation rated for 90°C continuous operation. Yangtze River Delta manufacturers concentrate medium-voltage cable output serving state grid tenders.
Germany
Utility procurement teams specify peroxide-cured EPR compounds with tailored scorch safety profiles for grid hardening infrastructure. EU Green Deal carbon-border adjustments disadvantage imported compound from carbon-intensive production, rewarding European captive EPR compounding investments. Industrial clusters in Bavaria and North Rhine-Westphalia anchor specialty cable formulation for tunnel and mass-transit applications.
United States
Gulf Coast petrochemical concentration exposes compounders to hurricane disruption and ethylene-propylene monomer allocation priorities. EPA oversight of process emissions shapes compounding site selection for medium-voltage utility cable supply. Houston-area producers serve grid hardening cycles across Texas and Southeast utilities.
India
BIS IS 694 flame-retardant standards lag domestic capacity, opening import substitution windows for certified EPR suppliers. The country's infrastructure buildout concentrates demand in Maharashtra and Gujarat industrial corridors. Construction sector procurement favors cost-optimized PVC for non-critical circuits, compressing EPR to industrial niches where oil resistance is mandatory.
South Korea
Automotive OEMs conduct joint compound-cable validation programs that bypass traditional merchant compounder relationships. MFDS-equivalent standards for industrial cable quality shape supplier qualification protocols. Busan and Seoul automotive clusters lock charging infrastructure harness specifications three years ahead of platform launch.
Ethylene Propylene Rubber Cable Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that lacks captive EPR compounding capability. Prysmian Group and Nexans S.A. anchor the upper tier through backward integration into compound production, while pure cable assemblers face margin compression from feedstock volatility. Strategic archetypes include integrated compound-cable producers, regional harness specialists, and merchant compound suppliers. Capacity expansion and qualification-driven partnerships constitute the dominant competitive moves as automotive electrification compresses product development cycles.
Within the integrated tier, Prysmian Group represents European compound-cable convergence, Nexans S.A. exemplifies technical leadership through continuous vulcanization specialization, and LS Cable & System Ltd. anchors Asian supply integration. These three occupy positions that reward captive EPR production over merchant supply as tier-1 harness suppliers specify thermal cycling performance thresholds. Specialists without in-house compounding capability sit at a structural disadvantage under this procurement pattern.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans S.A. |
| LS Cable & System Ltd. |
| Sumitomo Electric Industries, Ltd. |
| Southwire Company, LLC |
| NKT A/S |
| Furukawa Electric Co., Ltd. |
| KEI Industries Limited |
| Polycab India Limited |
| Others |
Pricing and Supply Chain Analysis
Continuous vulcanization line scale in China and South Korea anchors cost floors for medium-voltage cable production, concentrating pricing power among integrated compounders while squeezing merchant suppliers. EPDM feedstock volatility and REACH-compliant reformulation costs transmit directly to utility procurement premiums, fragmenting price discipline across automotive and grid-hardening segments.
Pricing Analysis
After-sales service contracts for continuous vulcanization line maintenance and compound technical support drive lifetime value for integrated producers. Three-tier pricing structure across premium peroxide-cured grades, standard steam-cure products, and economy batch-autoclave alternatives reflects certification complexity and thermal aging guarantees. Cost compression in economy tiers intensifies as Indian construction buyers favor PVC substitutes where BIS codes permit. Automotive OEMs exhibit lowest price sensitivity due to joint validation requirements, while Indian building wire distributors remain acutely cost-driven.
Supply Chain Analysis
Gulf Coast ethylene-propylene monomer concentration creates a chokepoint exposing compounders to hurricane disruption and allocation priority shifts. EPDM rubber production clusters in the United States, the Netherlands, and China, with peroxide curatives and flame-retardant additives sourced from German and Japanese specialty chemical producers. Single-source vulnerability concentrates in aromatic process oil substitutes forced by ECHA SVHC listings. Distribution runs through direct utility tender channels for grid infrastructure and tier-1 harness supplier consignment for automotive platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification fragments procurement into compound-cable integration niches that reward captive production over merchant supply. Tier-1 harness qualification cycles compress from five years to eighteen months, creating entry windows for specialists with validated thermal cycling performance.
For Market Incumbents: Compound backward integration into EPDM feedstock through offtake agreements with Gulf Coast petrochemical complexes. Prysmian and Nexans should extend peroxide-cured certification portfolios ahead of anticipated ECHA accelerator listings. Defend margin position by locking three-year platform validation cycles with Stuttgart and Munich OEMs before silicone substitution thresholds harden.
For New Entrants and Emerging Players: Anchor in India's BIS IS 694 certification gap for flame-retardant building wire where domestic capacity lags infrastructure targets. Wireless charging pad power coils represent the most penetrable white-space specification with limited incumbent EPR supply. Pursue joint compound-cable validation partnerships with Korean automotive tier-1s bypassing traditional merchant relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated compound-cable producers with captive continuous vulcanization lines serving utility grid hardening cycles. Long-term viability over the next decade hinges on peroxide-cured formulation depth and automotive platform lock-in density. Monitor ECHA SVHC consultation outcomes as the primary inflection signal for forced reformulation costs and supplier tier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Compounding | Captive production secures margin on GB/T 12706-certified medium-voltage cables for Chinese grid tenders. |
| Peroxide-Cured Formulation Expansion | 40-year thermal aging guarantees differentiate suppliers for German and South Korean utility procurement. |
| Flame-Retardant Certification Investment | IEC 60332-3-24 compliance unlocks tunnel and mass-transit premiums in European infrastructure buildout. |
| Automotive Joint Validation Programs | Three-year platform lock-ins with Busan and Seoul OEMs bypass merchant compounder relationships. |
| Wireless Charging Coil Development | EPR-jacketed flexible power coils address emerging inductive EV charging specifications with limited supply. |
Research Methodology
Initial hypotheses were tested against primary input from continuous vulcanization line operators, tier-1 automotive harness procurement directors, utility grid planning engineers, and EPDM compound technical specialists and refined through customs trade data, IEC certification registries, SEC filings from listed cable producers, and ECHA SVHC consultation documents. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Variance decomposition separated volume growth from price-mix effects across voltage rating tiers, end-use industry concentrations, insulation chemistry categories, and regional regulatory clusters. CAGRs derived from segment-level buildups incorporating automotive platform proliferation rates, utility capital expenditure cycles, and REACH reformulation cost pass-through assumptions.
Decision-makers should treat outputs as directional under stable EPDM monomer supply and current ECHA regulatory trajectories; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as automotive silicone substitution thresholds and India BIS enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Reinforcing Chemicals Market
Rubber
Plastomers Market
Rubber
Rubber Ropes Market
Rubber
Global Rubber Market
Rubber
Global Rubber Process Oil Market
Rubber
Global Rubber Vulcanization Market
Rubber
Rubber Splicing Tape Market
Rubber
Natural Rubber Market
Rubber
Global Cast Elastomers Market
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Rubber Flooring Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Abrasion-Resistant Rubber Pipe Market
Rubber
Rubber Molding Market