
 Functional Textile Finishing Agents Market | 2026-2036
Functional Textile Finishing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Textile Finishing Agents Market Analysis
Technical textile manufacturers is collapsing the legacy dominance of apparel-first buyers in functional finishing procurement. Archroma leverages its integrated color and effects portfolio to serve industrial fabric makers with customized repellency systems. Huntsman Corporation anchors its position through captive synthesis of durable water repellent chemistries at scale. Dow Inc. competes by extending silicone-based softening and protective platforms into medical textile supply chains.
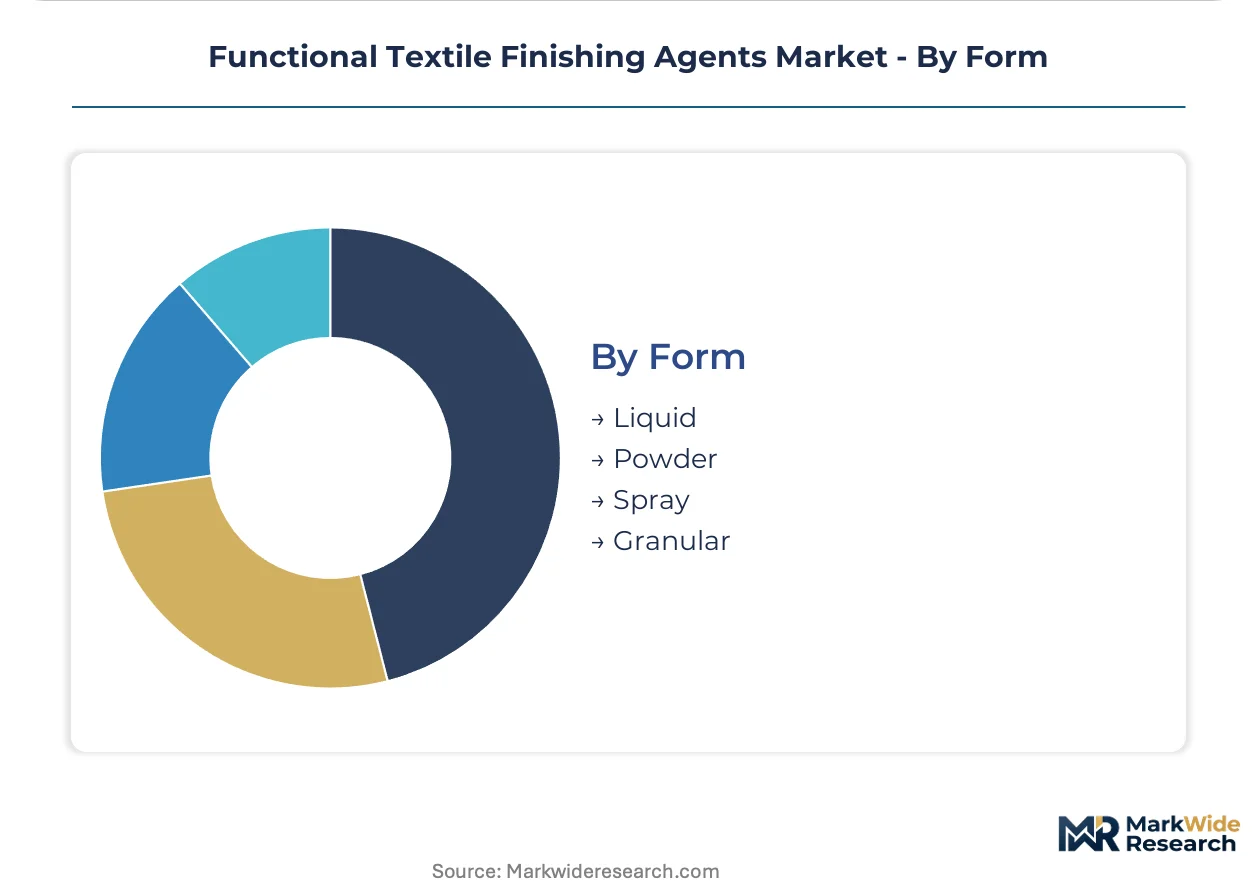
Functional textile finishing agents comprise formulated chemical treatments applied to woven, knitted, or nonwoven substrates to impart performance properties such as hydrophobicity measured by spray ratings, limited flame spread per EN ISO 15025, or bacterial reduction rates. These agents typically contain fluoropolymers, phosphonium salts, or quaternary ammonium compounds delivered via pad-dry-cure or exhaust application methods to meet end-use durability standards. Water repellent formulations retain the largest volume share across the product type dimension, while anti-microbial finishes command premium positioning in healthcare technical textiles. Liquid form factors dominate processing economics for continuous textile finishing lines, though powder variants sustain niche demand in carpet and nonwoven applications where precise dosing controls additive distribution.
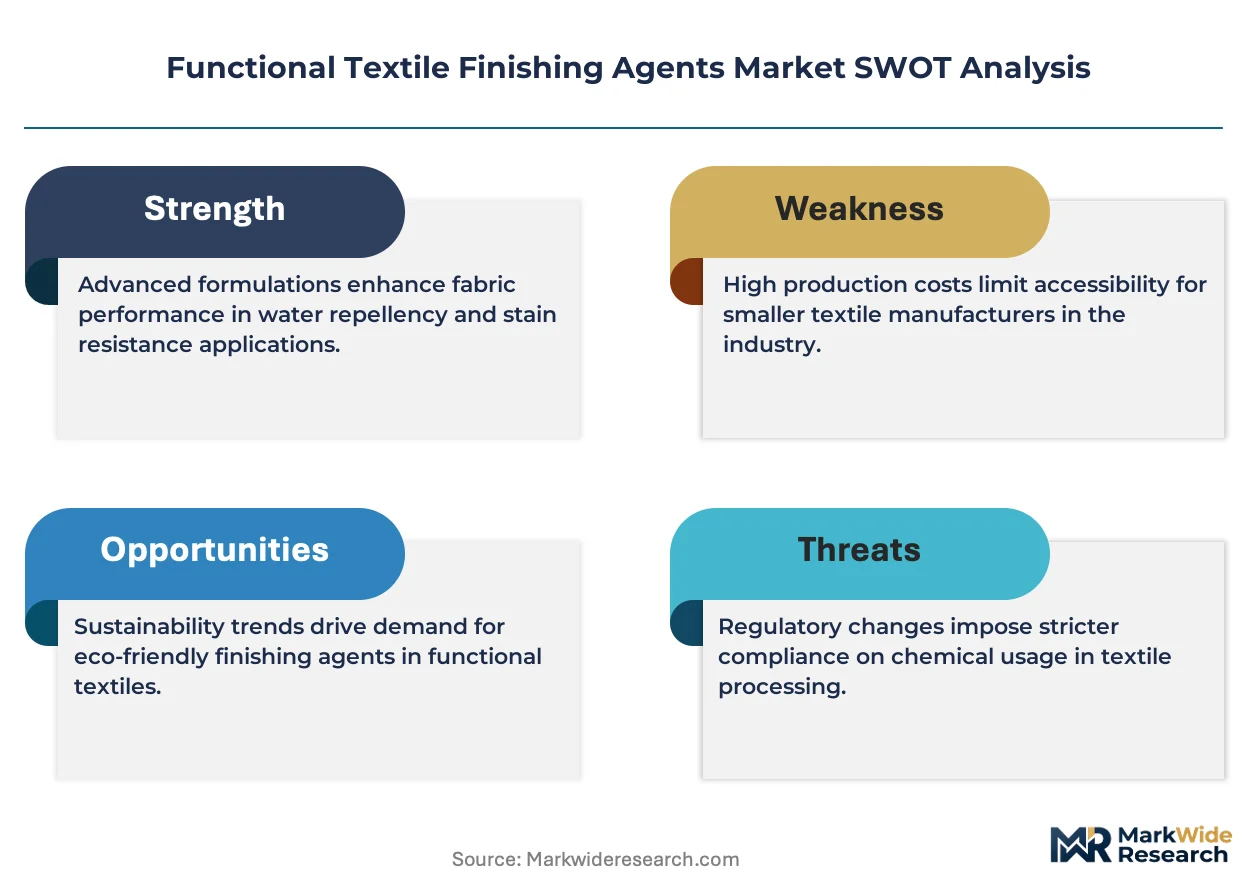
REACH in Europe and EPA regulations in the United States are restricting long-chain fluorinated chemistries, forcing reformulation toward shorter-chain or fluorine-free alternatives. ECHA's PFAS restriction proposal and state-level disclosure laws in Maine and Washington are reshaping product registration requirements and supply chain documentation obligations. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure early-mover advantage in compliant chemistry platforms.
Market Dynamics
REACH and the EU Green Deal are forcing a wholesale reformulation of fluorinated chemistries across European textile finishing supply chains. Technical textile manufacturers in Germany, France, and Italy now demand PFAS-compliant alternatives from their chemical suppliers, compressing legacy product lifecycles and redrawing procurement criteria.
Growth Catalysts
- EU Green Deal chemical transition mandates:The framework accelerates substitution timelines for per- and polyfluoroalkyl substances in textile treatments. Finish suppliers with shorter-chain or fluorine-free portfolios capture qualified supplier status with industrial fabric makers.
- Healthcare technical textile expansion:Anti-microbial finishes for medical gowns, drapes, and surgical textiles face stepped-up hospital procurement standards. German technical textile clusters around Stuttgart drive specialty finish consumption for infection control applications.
- Flame-retardant protective wear standards:EN ISO 15025 compliance requirements in industrial safety equipment create durable demand for phosphonium salt and intumescent formulations. Oil and gas sector buyers in Norway and the United Kingdom specify certified finishes for worker protection.
Market Restraints
- Fluoropolymer feedstock cost volatility:Tetrafluoroethylene and hexafluoropropylene prices fluctuate with energy input costs and capacity constraints in Chinese and German chemical parks. Formulators face margin compression when passing through raw material spikes.
- ECHA PFAS restriction proposal uncertainty:The broad regulatory scope creates stranded inventory risk for long-chain fluorinated water repellent chemistries. Suppliers delay capital deployment until final restriction lists clarify compliant chemistry boundaries.
- Silicone-based softening substitution threat:Dow Inc. and Wacker Chemie extend amino-functional silicone platforms into protective textile segments. These alternatives compete on cost and regulatory acceptance in medical and consumer applications.
Strategic Opportunities
- India technical textile manufacturing expansion:The PLI scheme for man-made fiber and technical textiles attracts finishing capacity investment. Domestic formulators can anchor supply relationships with emerging nonwoven and industrial fabric producers in Gujarat and Tamil Nadu.
- Pad-dry-cure process electrification:Infrared and radio frequency drying technologies reduce natural gas dependence in continuous finishing lines. Equipment suppliers and chemical formulators co-develop energy-optimized cure profiles for polyester and cotton substrates.
- Biocidal Product Regulation compliance services:Active substance approval timelines for quaternary ammonium compounds create advisory revenue streams. Testing laboratories and regulatory consultants bundle dossier preparation with finish formulation support.
Industry Challenges
- Cross-functional formulation chemistry expertise scarcity:Fluorine-free repellency development demands polymer science, surface chemistry, and textile engineering integration. Universities in Germany and Switzerland struggle to produce graduates with combined competencies.
- OEKO-TEX and bluesign certification timeline compression:Multi-standard compliance for European apparel brands extends product development cycles. Finish suppliers must maintain parallel certification tracks while accelerating reformulation schedules.
- Legacy pad-dry-cure line retrofit requirements:Fluorine-free chemistries often demand modified cure temperatures and dwell times. Capital investment in oven controls and tension systems strains mid-scale finishers with aged equipment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Textile Finishing Agents Market |
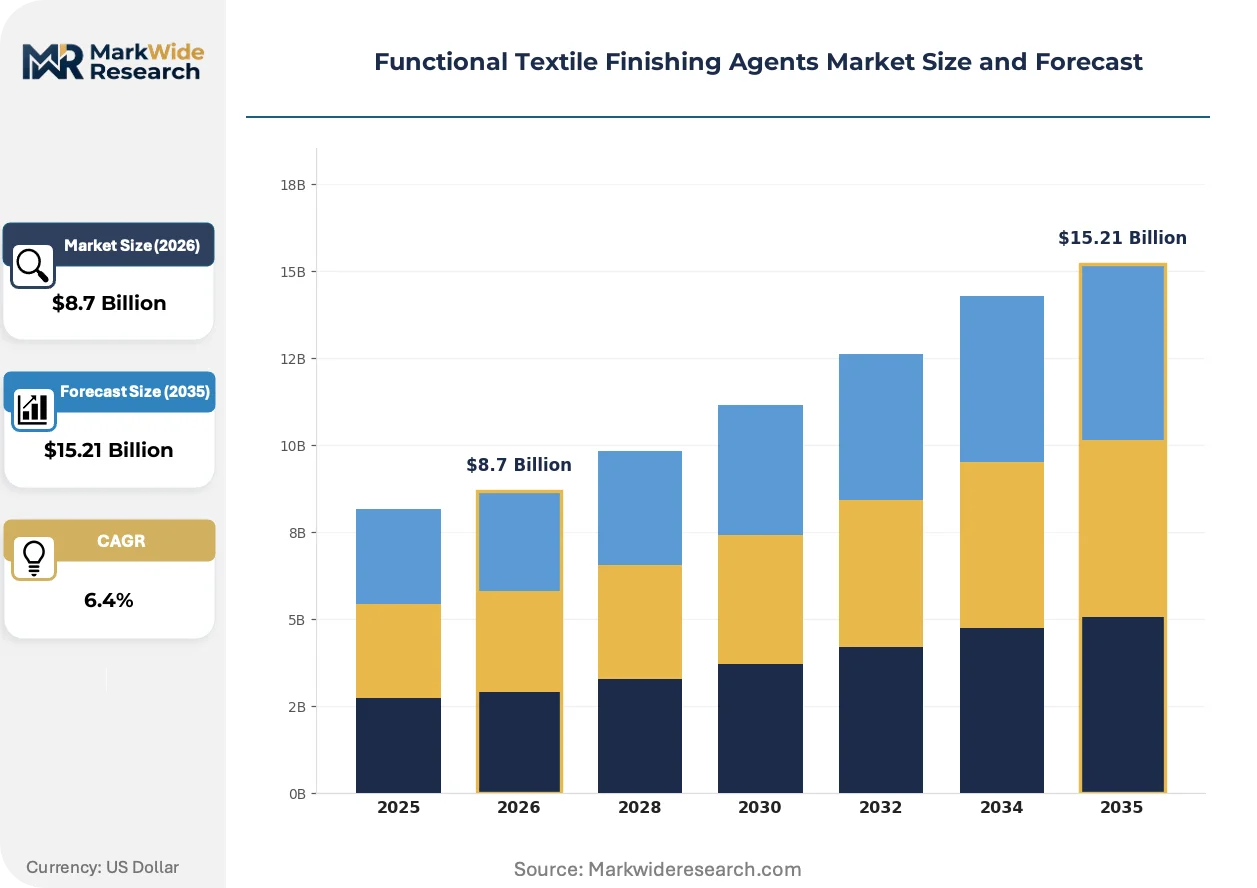
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Repellent, Flame Retardant, Anti-Microbial, Soil Release Application: Apparel, Home Textiles, Industrial Fabrics, Technical Textiles End User: Manufacturers, Retailers, Wholesalers, Distributors Form: Liquid, Powder, Spray, Granular |
| Companies Covered | Archroma, Sumitomo Chemical Co., Ltd., BASF SE, Lubrizol Corporation, Rudolf GmbH, Dow Inc., Huntsman Corporation, Wacker Chemie AG, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Textile Finishing Agents Market Emerging Trajectories
Fluorine-free water repellency technologies are compressing the performance gap with legacy C8 fluorinated systems. Plasma and nanocoating surface modification approaches now achieve spray ratings above 80 on polyester substrates.
Silane-siloxane hybrid polymers are miniaturizing surface energy reduction at the nanoscale. Medical textile manufacturers in Germany and Switzerland adopt these systems for blood and fluid barrier applications. The technology is miniaturizing the minimum effective film thickness required for durable repellency, reducing chemical loading per square meter and enabling lighter base fabric constructions.
ECHA's PFAS restriction proposal and state-level disclosure mandates in Maine and Washington reshape product registration requirements. Chemical suppliers must build supply chain documentation systems for fluorinated content traceability. Industrial protective wear segments face the steepest compliance burden, with some buyers accelerating qualification of entirely fluorine-free alternatives ahead of regulatory deadlines.
Hospital procurement departments now specify bacterial reduction rates and biocompatibility certifications as primary selection criteria. Technical textile distributors lose ground to direct manufacturer relationships as buyers demand formulation transparency and batch-level test data. This pattern concentrates most visibly in German-speaking Europe, where integrated textile clusters enable shorter qualification cycles between finish suppliers and end-use converters.
Functional Textile Finishing Agents Market Segmentation
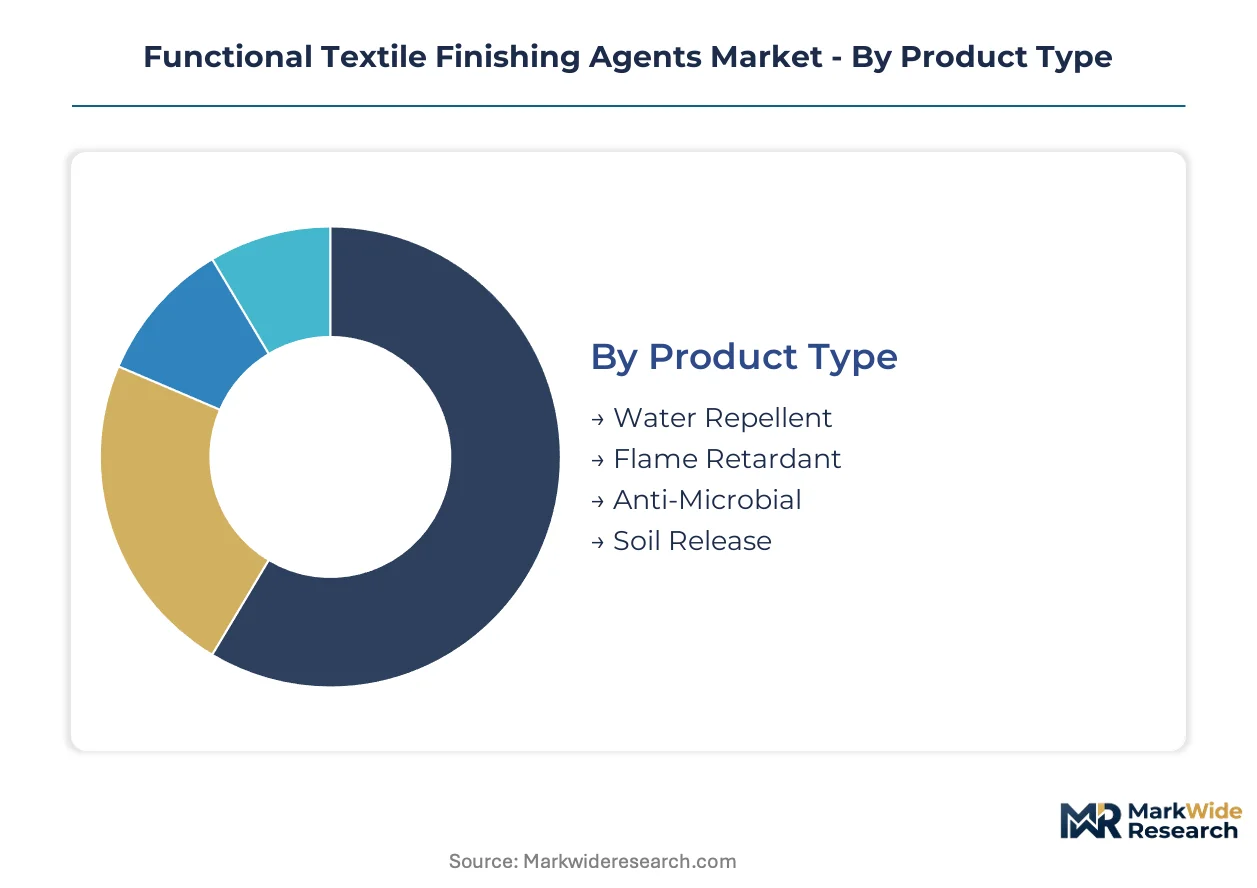
Segmentation in functional textile finishing agents reveals how regulatory pressure and processing economics split demand across chemistry platforms and supply chain tiers. Each dimension carries distinct margin profiles and compliance burdens that reshape procurement patterns.
Product Type:
REACH and EPA restrictions on fluorinated chemistries create sharp regulatory differentiation between legacy and next-generation formulations, with ECHA's PFAS proposal accelerating portfolio transitions.
- Water Repellent:Fluoropolymer-based formulations historically dominated durable water repellency for outdoor and protective applications. German technical textile clusters around Stuttgart now demand shorter-chain or fluorine-free alternatives to preempt ECHA restriction enforcement, compressing legacy product lifecycles.
- Anti-Microbial:Quaternary ammonium compounds and phosphonium salts deliver bacterial reduction rates for healthcare technical textiles. Hospital procurement departments in Germany specify biocompatibility certifications as primary selection criteria, driving direct manufacturer relationships that bypass traditional distributors.
- Flame Retardant:Intumescent and phosphonium salt formulations meet EN ISO 15025 compliance for industrial safety equipment.
- Soil Release:Hydrophilic polymer finishes ease stain removal in consumer apparel and hospitality textiles.
Water Repellent handles the majority of throughput; Anti-Microbial is climbing the fastest on share.
Application:
Cost tier differentiation separates high-specification technical textiles from commodity apparel finishing, with certification requirements widening the margin gap between segments.
- Technical Textiles:Medical, industrial, and protective applications demand validated performance against EN ISO 15025 and biocompatibility standards. Oil and gas buyers in Norway and the United Kingdom specify certified flame-retardant finishes, while German healthcare clusters drive anti-microbial consumption.
- Industrial Fabrics:Geotextiles, filtration media, and automotive interiors require durability under mechanical stress and chemical exposure. Pad-dry-cure processing dominates continuous finishing lines for these high-volume substrates.
- Apparel:Outdoor and performance wear brands balance water repellency with sustainability positioning.
- Home Textiles:Upholstery and carpet applications favor cost-optimized soil release and softening treatments.
Technical Textiles commands premium positioning; Industrial Fabrics delivers volume scale.
End User:
Customer type determines formulation transparency requirements, with direct manufacturer relationships displacing intermediary channels in regulated segments.
- Manufacturers:Technical textile converters in Germany, France, and Italy demand batch-level test data and supply chain documentation for PFAS compliance. These buyers qualify finish suppliers through integrated cluster relationships that shorten development cycles.
- Distributors:Traditional textile chemical distributors face margin compression as procurement concentrates with direct supplier relationships.
- Retailers:Apparel brands specify OEKO-TEX and bluesign certification for consumer-facing products.
- Wholesalers:Volume-oriented channels serve mid-market apparel and home textile producers with standardized formulations.
Manufacturers absorb the highest regulatory compliance burden; Retailers are expanding specification authority fastest.
Form:
Processing economics and substrate compatibility drive form selection, with liquid formulations optimized for continuous line efficiency.
- Liquid:Pumpable emulsions and solutions integrate into pad-dry-cure and exhaust application systems. Continuous finishing lines for polyester and cotton substrates rely on liquid dosing for precise chemistry distribution and energy-optimized cure profiles.
- Powder:Solid additives enable precise dosing control in carpet and nonwoven applications where uniform distribution challenges liquid penetration.
- Spray:Aerosol and pump-spray formats serve niche aftermarket and spot-treatment applications.
- Granular:Low-dust solid forms support automated feeding in specific nonwoven and fiber processing lines.
Liquid dominates processing throughput; Powder sustains defensive positioning in carpet specialties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German technical textile clusters export high-performance finishing formulations to medical and industrial buyers across France, Italy, and the United Kingdom, establishing a westward trade corridor anchored by Stuttgart and Chemnitz manufacturing bases.
Germany
Healthcare technical textile manufacturers in Stuttgart and Chemnitz drive specialty anti-microbial finish consumption for surgical drapes and infection control garments. REACH and the EU Green Deal mandate PFAS substitution timelines that compress legacy fluorinated product lifecycles. The Baden-Württemberg cluster hosts integrated supply relationships between finish suppliers and end-use converters that shorten qualification cycles.
United States
Flame-retardant protective wear producers serving the oil and gas sector specify certified finishes for worker safety equipment. EPA regulations restrict long-chain fluorinated chemistries while state-level disclosure laws in Maine and Washington reshape documentation obligations. Technical textile manufacturing concentrates in the Southeast and Mid-Atlantic regions where pad-dry-cure processing lines serve military and industrial buyers.
China
Fluoropolymer feedstock production for water repellent formulations faces capacity constraints and energy input cost volatility. The country's national chemical regulator enforces emission controls at chemical parks that affect tetrafluoroethylene and hexafluoropropylene supply. Manufacturing clusters in the Yangtze River Delta export finished textile chemicals to Southeast Asian garment producers.
India
The PLI scheme for man-made fiber and technical textiles attracts finishing capacity investment from domestic and multinational formulators. Central government production-linked incentives reduce import dependence for specialty chemicals. Emerging nonwoven and industrial fabric producers in Gujarat and Tamil Nadu anchor supply relationships with local finish suppliers.
France
Industrial protective wear manufacturers demand EN ISO 15025 compliant flame-retardant finishes for safety equipment distributed across European markets. ANSM enforces biocompatibility standards for medical textile applications that intersect with ECHA chemical restrictions. The Auvergne-Rhône-Alpes region hosts technical textile converters qualifying fluorine-free alternatives ahead of regulatory deadlines.
Functional Textile Finishing Agents Market Vendor Landscape
Listed leaders compete with private specialists across chemistry platforms and geographic coverage. The supplier base organizes into tiered groups differentiated by captive synthesis capabilities and integrated color-and-effects portfolios. Three archetypes dominate: diversified chemical conglomerates with textile divisions, mid-scale European specialists focused on technical textile niches, and Asian manufacturers leveraging feedstock proximity. Competitive moves concentrate on fluorine-free reformulation partnerships and pad-dry-cure process electrification collaborations.
Within the diversified chemical conglomerate tier, BASF SE and Dow Inc. exemplify scale-driven positioning through broad materials science portfolios that span silicone-based softening and protective platforms. Among European specialists, Rudolf GmbH and Wacker Chemie AG occupy positions defined by regional technical textile relationships and customized formulation services. Archroma represents the integrated color-and-effects archetype with captive capabilities across repellency and anti-microbial systems.
| Leading Market Players |
|---|
| Archroma |
| Sumitomo Chemical Co., Ltd. |
| BASF SE |
| Lubrizol Corporation |
| Rudolf GmbH |
| Dow Inc. |
| Huntsman Corporation |
| Wacker Chemie AG |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Captive synthesis capabilities at German and Chinese chemical parks compress unit economics for fluoropolymer-based water repellent formulations while elevating price floors for fluorine-free alternatives. Scale advantages in tetrafluoroethylene production concentrate margin leverage with integrated suppliers, forcing smaller formulators toward specialty anti-microbial and flame-retardant niches where certification premiums offset volume disadvantages.
Pricing Analysis
Next-generation fluorine-free water repellent chemistries command 15-25% premiums over legacy C8 fluorinated systems, while shorter-chain C6 formulations occupy a narrowing mid-tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with OEKO-TEX and bluesign tiers extracting measurable premiums from apparel brands. Pricing pressure stems from silicone-based softening substitution in medical textile segments, where Dow Inc. and Wacker Chemie compete on regulatory acceptance. Industrial fabric manufacturers show lowest price sensitivity due to EN ISO 15025 compliance mandates, while mid-market apparel converters face acute cost compression.
Supply Chain Analysis
China and Germany anchor fluoropolymer feedstock production for water repellent formulations, with India emerging as a technical textile manufacturing alternative under PLI scheme incentives. Tetrafluoroethylene, hexafluoropropylene, and quaternary ammonium compound precursors draw from concentrated petrochemical and phosphorus chemical streams. Single-source vulnerability runs through Chinese chemical park capacity constraints, where emission controls disrupt tetrafluoroethylene availability. Distribution runs through direct manufacturer relationships in German technical textile clusters, displacing traditional distributor channels in regulated segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, EPA, and state-level PFAS disclosure laws fragments procurement criteria, creating specialized supplier niches for compliant chemistry platforms. This demand-side shift rewards formulators with parallel certification capabilities and regional regulatory expertise.
For Market Incumbents: Shield formulation portfolios from stranded inventory risk by accelerating fluorine-free water repellent qualification ahead of ECHA restriction finalization. Prioritize backward integration into phosphonium salt synthesis for flame-retardant protective wear segments, where EN ISO 15025 certification requirements create durable margin pools against silicone substitution threats. For New Entrants and Emerging Players: Bluesign certification fast-track positions entrants for direct procurement relationships with German healthcare technical textile manufacturers. Target India's Gujarat nonwoven corridor for pad-dry-cure line partnerships, where PLI scheme incentives reduce import dependence and domestic formulators lack fluorine-free repellency expertise. Lead with biocidal product regulation advisory bundling to differentiate from commodity chemical suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European specialists with integrated color-and-effects portfolios and captive regulatory compliance services. Five-to-ten year viability hinges on PFAS substitution completion timelines, with acquisition premiums concentrating in mid-scale German formulators possessing Baden-Württemberg cluster relationships. Watch ECHA restriction list finalization as inflection indicator for stranded asset risk and compliant chemistry valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Reformulation Partnership | Archroma and Huntsman Corporation anchor supplier status with Stuttgart medical textile clusters through PFAS-compliant repellency systems. |
| Pad-Dry-Cure Electrification Collaboration | Infrared drying technology co-development reduces natural gas exposure for polyester substrate finishers in Chemnitz industrial corridors. |
| Biocidal Product Regulation Dossier Services | Testing laboratories bundle quaternary ammonium compound approval support with anti-microbial finish formulation for German hospital procurement. |
| India PLI Scheme Capacity Investment | Domestic formulators anchor supply relationships with emerging Gujarat nonwoven producers under central government production-linked incentives. |
| Silicone-Based Softening Platform Extension | Dow Inc. and Wacker Chemie penetrate protective textile segments through amino-functional silicone alternatives to fluorinated chemistries. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with technical textile plant managers, chemical procurement leads at industrial fabric OEMs, distribution channel partners in German-speaking Europe, and R&D directors at finishing agent formulators. Secondary validation drew from ECHA regulatory filings, customs and trade data for fluoropolymer feedstocks, SEC 10-K disclosures from diversified chemical conglomerates, and technical textile cluster economic development reports. Bottom-up volume modeling across chemistry platforms and application segments triangulated against top-down market sizing from national chemical association datasets.
Across the analysis window, the analytical framework segmented demand by product type, application, end-user channel, and geographic production hub, with CAGRs derived from regression analysis against fluoropolymer price indices and technical textile output forecasts. Modeled inputs included REACH compliance timeline scenarios, pad-dry-cure line capacity utilization rates, and hospital procurement standard adoption curves for bacterial reduction specifications.
Underlying assumptions cover regulatory enforcement consistency, feedstock price volatility bands, and certification timeline compression, with deviation risk concentrated in ECHA PFAS restriction scope finalization and Chinese chemical park emission control stringency. Recalibration cycles align with material shifts in EU Green Deal implementation schedules and major technical textile capacity investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Textile Dyestuff Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market