
 Leak Detection Dyes Market | 2026-2036
Leak Detection Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Leak Detection Dyes Market Outlook
A capital-intensity divergence between integrated manufacturers and formulation specialists is rotating competitive dynamics across the leak detection dyes landscape. Spectronics Corporation leverages captive ultraviolet lamp production to anchor its dye-plus-detection bundle strategy. Tracer Products competes through distributor channel control across North American automotive service chains. Errecom S.p.A. specializes in biodegradable refrigerant dye formulations for European HVAC compliance markets.
Leak detection dyes are fluorescent or non-fluorescent chemical tracers, typically formulated from naphthalimide or perylene derivatives, that emit visible light under UV-A illumination to pinpoint fluid escape points in pressurized systems. Their primary commercial purpose is to reduce refrigerant loss, prevent environmental discharge, and minimize labor hours in diagnostic protocols across automotive and industrial maintenance operations. Fluorescent dyes occupy the dominant volume position due to superior sensitivity at low concentrations, while biodegradable dyes represent the fastest-expanding category as environmental regulations harden disposal requirements. HVAC testing applications command premium pricing relative to water leak detection, reflecting the technical specificity of refrigerant-compatible carrier formulations.
The EPA SNAP program and the EU F-Gas Regulation are tightening permissible refrigerant leak rates, directly expanding mandatory dye-based inspection protocols across service industries. OSHA process safety directives and REACH chemical registration requirements are elevating formulation disclosure burdens for solvent-based products entering European and North American markets. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration investments with the geographies imposing the most stringent tracer chemical standards.
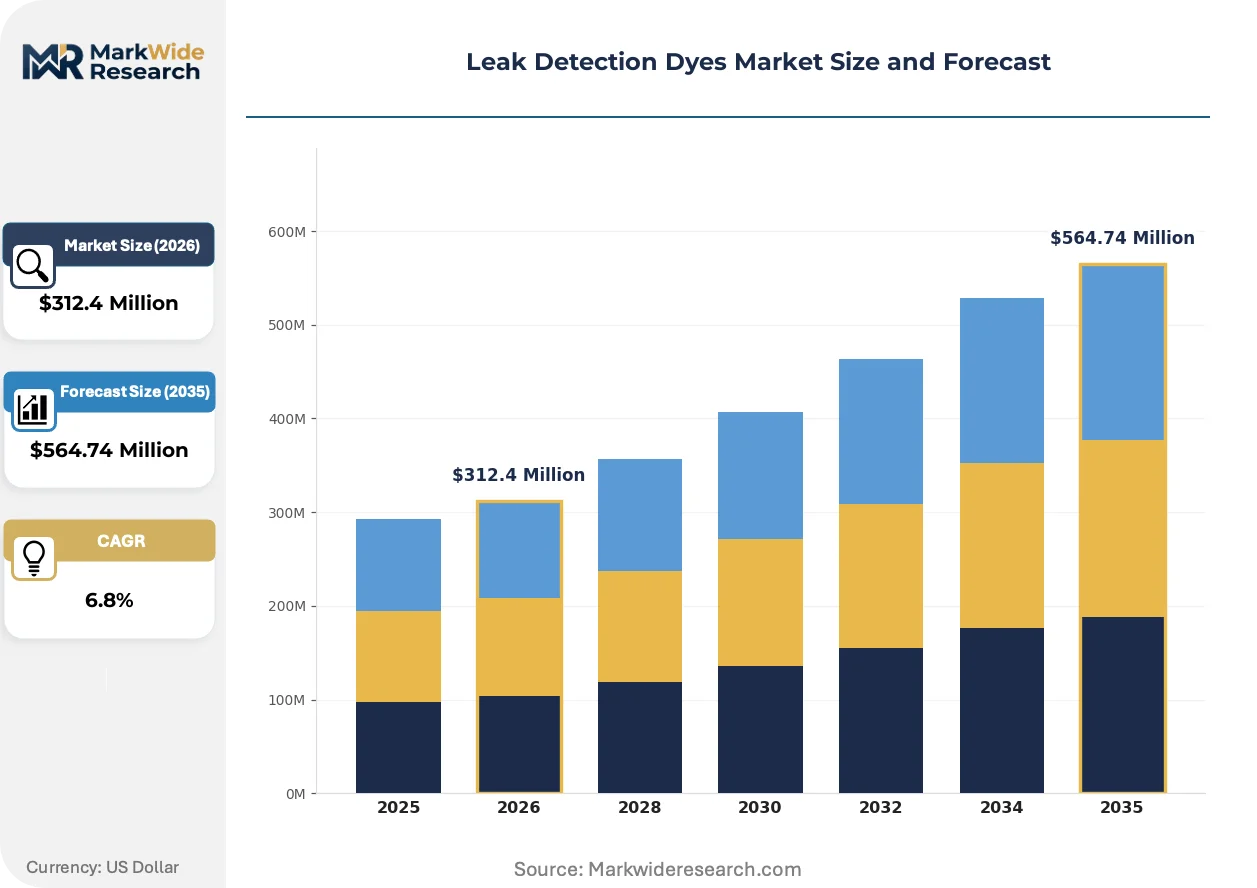
Market Dynamics
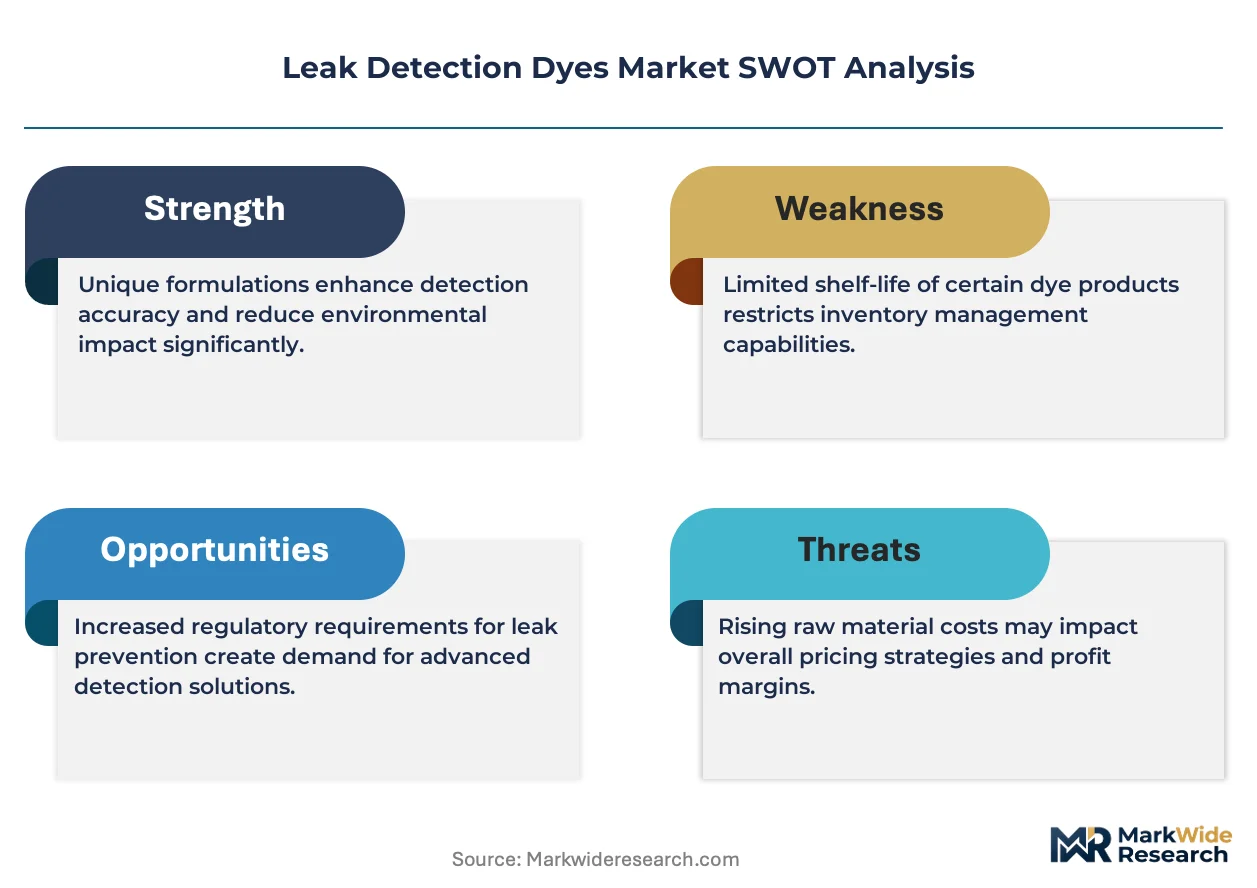
Biodegradable naphthalimide formulations are compressing the addressable market for solvent-based perylene dyes as EPA SNAP and EU F-Gas Regulation timelines harden disposal mandates across HVAC service networks.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:Mandatory leak inspection protocols for refrigeration systems above specific charge thresholds are institutionalizing dye-based diagnostic routines across European HVAC service chains.
- Automotive R-1234yf Transition:The shift to low-global-warming-potential refrigerants in vehicle air conditioning systems is expanding compatible dye formulation demand among service technicians.
- Building Energy Code Tightening:Germany's EnEV standards and comparable codes in Japan are lengthening mandatory maintenance intervals for commercial refrigeration, amplifying preventive inspection frequency.
Market Restraints
- Specialty Chemical Input Concentration:Naphthalimide precursor supply concentrates among Chinese and Indian fine chemical manufacturers, exposing formulators to freight cost volatility and customs processing delays.
- REACH Registration Burden:ECHA's substance evaluation procedures for novel carrier solvents are extending time-to-market for reformulated products by 18-36 months.
- Electronic Leak Detector Substitution:Heated diode and infrared sensing technologies are capturing share in high-volume automotive service bays where speed traces sensitivity.
Strategic Opportunities
- India Commercial Cold Chain Buildout:The country's food processing infrastructure expansion under PLI scheme incentives is creating first-time demand for industrial-grade fluorescent systems in ammonia and CO2 refrigeration.
- UV-LED Convergence:Solid-state ultraviolet excitation sources are enabling battery-powered portable detection kits that open mobile service technician segments previously served by AC-powered lamp sets.
- Water Infrastructure Rehabilitation:Municipal leak detection in buried potable water distribution networks represents an adjacent application with lower regulatory compliance burden than refrigerant tracing.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in refrigerant-compatible carrier fluid design remains concentrated among a narrow cohort of specialty chemical professionals, constraining R&D throughput at mid-tier manufacturers.
- Multi-Jurisdiction Registration Synchronization:Aligning EPA SNAP submissions with ECHA REACH dossiers and Japan METI chemical safety reporting creates compliance timeline conflicts for product launch coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leak Detection Dyes Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Dyes, Non-Fluorescent Dyes, Biodegradable Dyes, Solvent-Based Dyes Industry Vertical: Automotive, Aerospace, Construction, Oil & Gas Application: Water Leak Detection, Gas Leak Detection, HVAC Testing, Industrial Equipment Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Spectronics Corporation, Tracer Products, FJC Inc., Mastercool Inc., Errecom S.p.A., Glo-Leak LLC, UVIEW Technology Inc., Refrigeration Technologies, ChemPoint Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leak Detection Dyes Market Strategic Shifts
Formulation chemistry, excitation hardware, and service delivery models are undergoing simultaneous recalibration as environmental compliance deadlines compress product development cycles and reshape buyer procurement criteria.
Water-soluble naphthalimide derivatives engineered for direct injection into closed-loop refrigeration circuits are supplanting oil-based carrier formulations that require system evacuation and recharge. HVAC contractors in Germany and Japan are adopting these drop-in compatible chemistries to reduce labor hours per diagnostic call. The shift is compressing revenue per service event while expanding total addressable procedure volume across aging installed bases.
REACH authorization requirements for perfluorinated carrier solvents are forcing reformulation investments among European dye manufacturers before 2026 sunset dates. ECHA's restriction roadmap is accelerating biodegradable alternative development timelines by 40 percent compared to historical product refresh cycles. Formulators with early registration dossiers are securing preferred supplier status with pan-European HVAC service consolidators.
Service bundling is replacing component-only transactions as dominant procurement pattern among North American automotive dealer networks. Multi-year inspection contracts incorporating dye, detection equipment, and technician training are displacing spot purchases of consumable cartridges. This concentration is most visible across United States Midwest dealer groups where parent organizations are centralizing maintenance supply agreements.
Leak Detection Dyes Market Segmentation
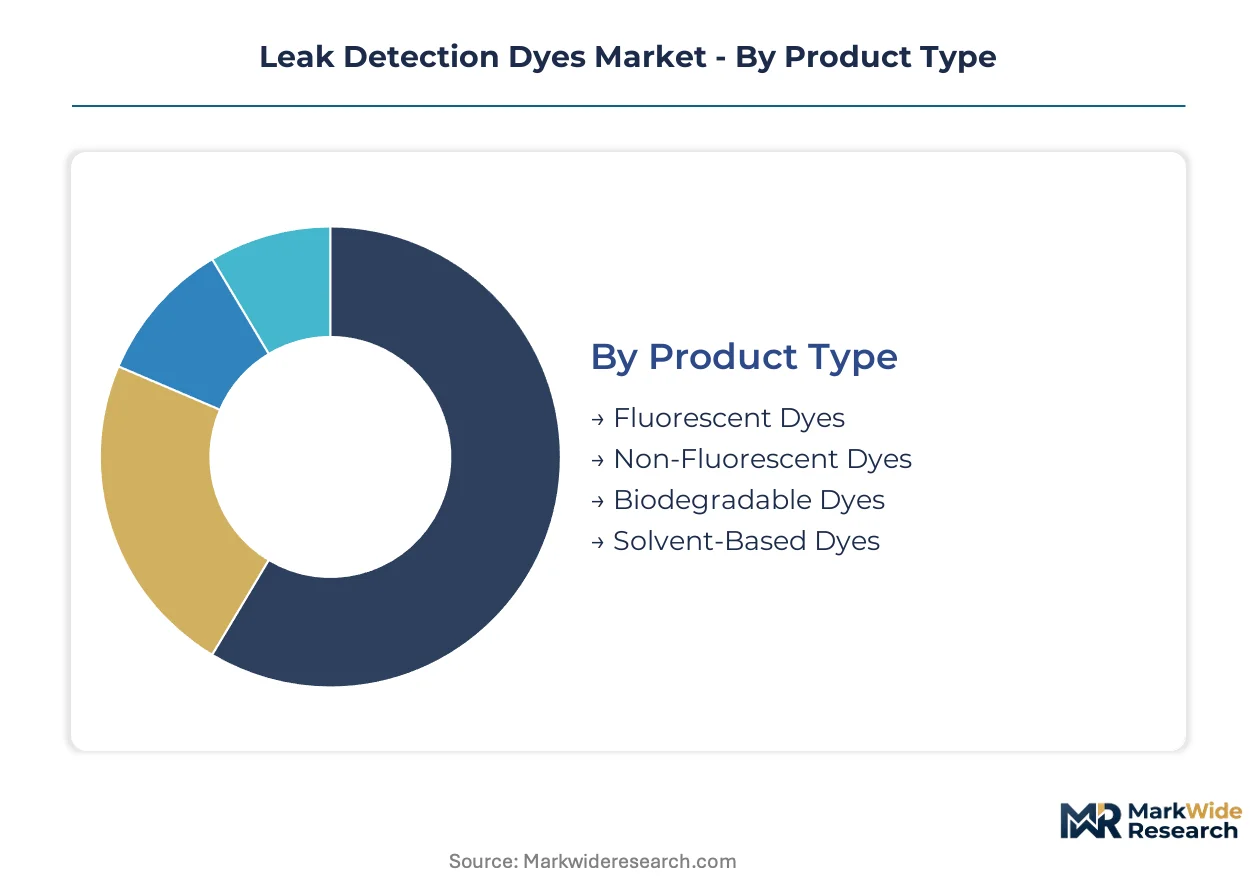
Leak detection dye procurement patterns diverge sharply across regulatory jurisdictions, with EPA SNAP and EU F-Gas Regulation timelines dictating formulation chemistry investments. Segment-level demand concentration reflects these compliance-driven purchasing cycles rather than pure price competition.
Product Type:
EPA SNAP and EU F-Gas Regulation disposal mandates are compressing the viable product mix, with biodegradable alternatives gaining preferred supplier status in European HVAC service consolidations.
- Fluorescent Dyes:Naphthalimide and perylene derivatives emit visible light under UV-A excitation, enabling sensitivity at parts-per-million concentrations. HVAC contractors in Germany and Japan specify these for preventive maintenance contracts on commercial refrigeration systems where leak thresholds tighten under building energy codes.
- Biodegradable Dyes:Water-soluble naphthalimide formulations engineered for direct injection without system evacuation. ECHA REACH authorization deadlines for perfluorinated carriers are accelerating procurement shifts toward these drop-in compatible chemistries across European service networks.
- Non-Fluorescent Dyes:Visual tracer compounds relying on color contrast rather than UV excitation, specified in cost-sensitive automotive service bays.
- Solvent-Based Dyes:Oil-carrier formulations requiring evacuation and recharge protocols, facing volume compression as disposal regulations harden.
Established volume favors fluorescent systems; emerging adoption favors biodegradable alternatives.
Industry Vertical:
Cost tier stratification separates specification-grade aerospace procurement from high-volume automotive spot purchasing.
- Automotive:R-1234yf refrigerant transition is expanding compatible dye demand across vehicle air conditioning service chains. United States Midwest dealer groups are consolidating multi-year inspection contracts that bundle dye, detection equipment, and technician training.
- HVAC Testing:Commercial refrigeration maintenance intervals are lengthening under Germany's EnEV standards and comparable Japanese codes, amplifying preventive inspection frequency and premium pricing for refrigerant-compatible formulations.
- Aerospace:MIL-SPEC certification requirements and trace documentation burdens concentrate procurement among a narrow supplier base serving MRO facilities.
- Construction:Municipal water infrastructure rehabilitation projects represent an adjacent application with lower regulatory compliance burden than refrigerant tracing.
- Oil & Gas:Pipeline integrity management protocols specify fluorescent tracers for subsea and high-pressure hydrocarbon leak identification.
Automotive channels move the highest unit volumes; aerospace commands the steepest pricing premiums.
Application:
Technical specificity of carrier fluid design creates margin differentiation between refrigerant-compatible and general-purpose water tracing applications.
- HVAC Testing:Refrigerant-compatible carrier formulations command premium pricing due to chemical stability requirements with R-134a, R-410A, and R-1234yf systems. India's commercial cold chain buildout under PLI scheme incentives is creating first-time demand for industrial-grade fluorescent systems in ammonia and CO2 refrigeration.
- Water Leak Detection:Municipal potable water distribution networks represent an expanding adjacent market with simpler registration pathways than refrigerant applications.
- Gas Leak Detection:Pressurized natural gas and industrial process gas applications specify high-visibility formulations for rapid source identification.
- Industrial Equipment:Hydraulic and lubrication system maintenance protocols incorporate dye tracing for seal integrity verification.
HVAC testing generates the highest revenue per procedure; water leak detection offers the largest addressable volume expansion.
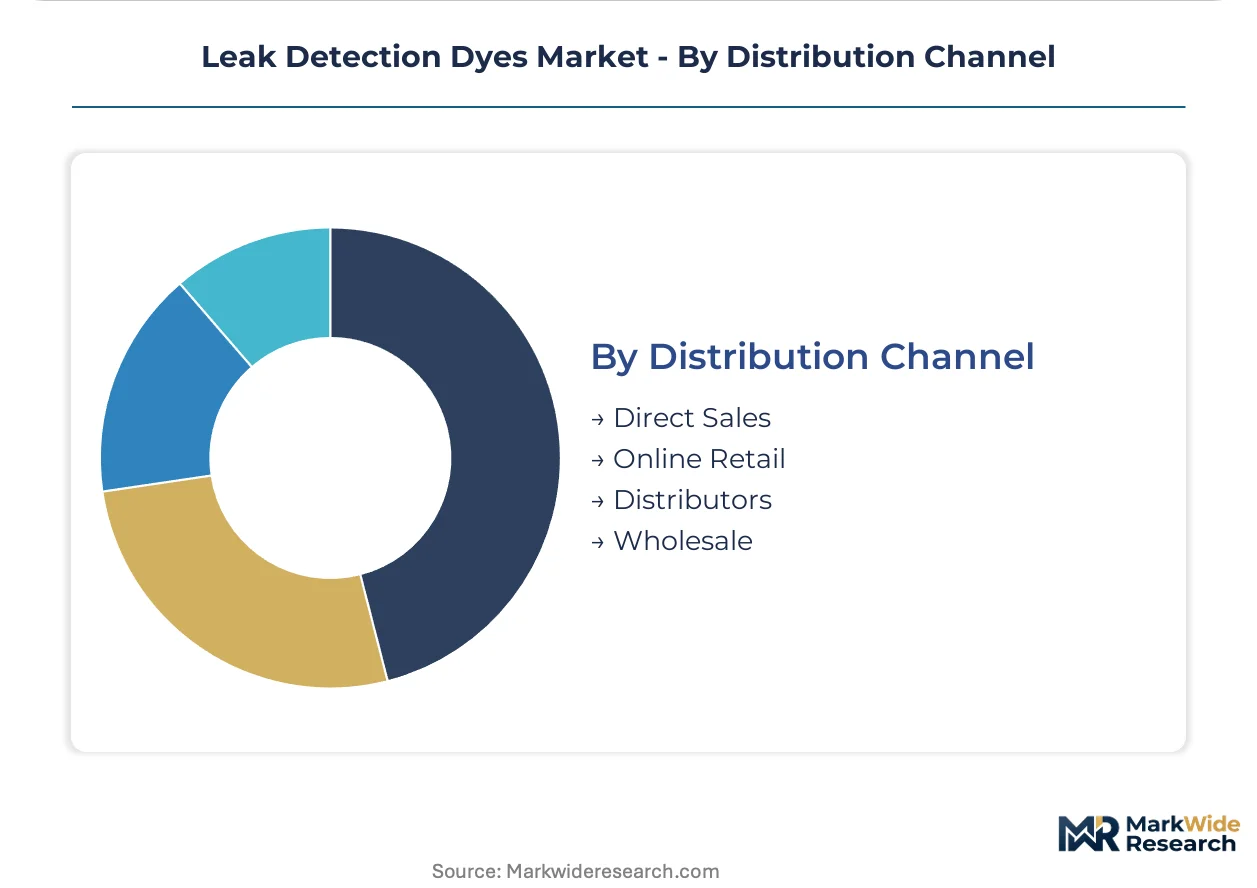
Distribution Channel:
Customer type concentration is rotating procurement patterns from component spot purchases toward integrated service contracts.
- Distributors:Channel control across North American automotive service chains enables formulation specialists to secure preferred placement in consolidated maintenance supply agreements.
- Direct Sales:Pan-European HVAC service consolidators negotiate multi-year dye-plus-detection bundles directly with manufacturers possessing early REACH registration dossiers.
- Online Retail:Mobile service technician segments are accessing UV-LED portable detection kits through e-commerce platforms, bypassing traditional industrial supply houses.
- Wholesale:Volume pricing tiers serve independent automotive repair facilities and regional HVAC contractors.
Distributor relationships defend incumbent positions; direct sales capture compliance-driven specification shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for refrigerant-compatible formulations, while Indian procurement concentrates on cost-optimized industrial-grade fluorescent systems for ammonia refrigeration. This asymmetry reflects divergent regulatory maturity and installed base age across major demand centers.
United States
Automotive dealer networks in the Midwest are consolidating multi-year inspection contracts that bundle dye, detection equipment, and technician training. EPA SNAP program timelines are hardening disposal mandates for solvent-based formulations across HVAC service chains. Houston and Dallas-Fort Worth anchor industrial procurement for oil and gas pipeline integrity applications.
Germany
Commercial refrigeration maintenance intervals are lengthening under EnEV standards, amplifying preventive inspection frequency for refrigerant-compatible dyes. ECHA REACH authorization deadlines for perfluorinated carrier solvents are accelerating shifts toward biodegradable naphthalimide alternatives. The Rhine-Ruhr industrial corridor concentrates formulation manufacturing and pan-European distribution logistics.
Japan
Building energy codes comparable to Germany's EnEV are extending mandatory maintenance intervals for commercial refrigeration systems. METI chemical safety reporting requirements are elevating formulation disclosure burdens for imported solvent-based products. The Nagoya-Tokyo industrial corridor hosts precision HVAC equipment manufacturers specifying premium dye systems for export markets.
India
The PLI scheme is incentivizing commercial cold chain buildout, creating first-time demand for industrial-grade fluorescent systems in ammonia and CO2 refrigeration. BIS certification requirements are emerging for tracer chemicals in food processing infrastructure. Maharashtra and Gujarat concentrate cold storage construction activity and associated dye procurement.
China
Naphthalimide precursor supply concentrates among fine chemical manufacturers serving global formulators, exposing downstream players to freight cost volatility. MEE environmental discharge standards are tightening for chemical manufacturing clusters. The Yangtze River Delta anchors production of fluorescent dye intermediates for export to European and North American compounders.
Leak Detection Dyes Market Competitive Environment
Concentration sits with integrated manufacturers possessing captive ultraviolet excitation source production and formulation specialists commanding early regulatory registration dossiers. The vendor base stratifies across three tiers: multinational chemical conglomerates with refrigerant industry heritage, mid-cap specialists in biodegradable carrier chemistry, and regional distributors private-labeling commodity formulations. Competitive moves center on REACH registration synchronization ahead of 2026 sunset dates and UV-LED detection kit bundling to capture mobile service technician segments.
Among North American integrated manufacturers, Spectronics Corporation exemplifies the dye-plus-detection bundle archetype through captive ultraviolet lamp production. Tracer Products occupies a position within the distributor channel control archetype across automotive service chains. Errecom S.p.A. represents the European formulation specialist tier, with S.p.A. corporate structure signaling concentrated family ownership typical of Italian specialty chemical enterprises. These three anchors illustrate the geographic and strategic segmentation defining competitive positioning in refrigerant tracer markets.
| Leading Market Players |
|---|
| Spectronics Corporation |
| Tracer Products |
| FJC Inc. |
| Mastercool Inc. |
| Errecom S.p.A. |
| Glo-Leak LLC |
| UVIEW Technology Inc. |
| Refrigeration Technologies |
| ChemPoint Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term dye-plus-detection bundles across North American automotive dealer networks lock in supply access while compressing price visibility for spot-market buyers. This contract-structure pattern concentrates procurement power among consolidated service chains and fragments pricing leverage for independent HVAC contractors facing volatile naphthalimide precursor costs.
Pricing Analysis
Configured-to-order pricing for refrigerant-compatible carrier formulations commands substantial premiums over standard visual tracer compounds. Three-tier pricing structure across premium, standard, and economy levels separates MIL-SPEC aerospace certification from automotive spot purchases and municipal water tracing applications. Price differentiation hinges on REACH registration status and UV-LED detection kit bundling. Cost compression in economy-tier solvent-based dyes is intensifying because of biodegradable formulation substitution. Independent automotive repair facilities exhibit highest price sensitivity; aerospace MRO facilities demonstrate lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate among European formulators confronting ECHA REACH authorization deadlines for perfluorinated carrier solvents. Naphthalimide precursor supply concentrates in China and India; UV-LED excitation source manufacturing anchors in Japan and South Korea. Raw material dependencies span fine chemical intermediates, semiconductor substrates, and refrigerant-compatible carrier fluids. Single-source vulnerability in Chinese naphthalimide production exposes downstream compounders to freight cost volatility. Distribution runs through pan-European HVAC service consolidators and North American automotive parts distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against electronic leak detection technologies capturing share in high-volume automotive service bays. Heated diode and infrared sensing systems threaten dye-based protocols where diagnostic speed outweighs sensitivity requirements.
For Market Incumbents: Shield market position by accelerating biodegradable naphthalimide R&D pipelines ahead of EU F-Gas Regulation enforcement timelines. Deepen backward integration into UV-LED excitation source production to anchor dye-plus-detection bundle economics against electronic detector price erosion. Secure early REACH registration dossiers to lock in preferred supplier status with pan-European HVAC consolidators.
For New Entrants and Emerging Players: Differentiate on water-soluble drop-in formulations for India's commercial cold chain buildout under PLI scheme incentives. Target ammonia and CO2 refrigeration applications in Maharashtra and Gujarat where first-time industrial-grade fluorescent demand outpaces established supply relationships. Deploy mobile-first UV-LED portable kits through e-commerce platforms to bypass entrenched distributor channels.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors formulation specialists with early registration dossiers and captive detection hardware production. Long-term viability rests on multi-jurisdiction chemical safety compliance capabilities rather than commodity scale. Acquisition candidates should demonstrate synchronized EPA SNAP and ECHA REACH submission expertise. Watch biodegradable formulation adoption rates in German HVAC networks as inflection indicator for premium pricing sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Synchronization | Aligns EPA SNAP submissions with ECHA dossiers to compress time-to-market for reformulated products. |
| UV-LED Detection Kit Bundling | Captures mobile service technician segments previously served by AC-powered lamp sets. |
| Biodegradable Formulation Scale-Up | Addresses EU F-Gas Regulation disposal mandates hardening across European HVAC service networks. |
| India Cold Chain Market Entry | Exploits PLI scheme incentives creating first-time demand for ammonia refrigeration dye systems. |
| Backward Integration into Precursor Supply | Reduces exposure to Chinese naphthalimide freight cost volatility and customs processing delays. |
Study Parameters
Cross-validation between primary interviews with HVAC service technicians, automotive aftermarket distributors, formulation chemists, and regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from EPA SNAP program filings, ECHA REACH registration databases, EU F-Gas Regulation implementation guidance, and customs trade data for naphthalimide precursor flows. Bottom-up triangulation across product-type demand curves and top-down reconciliation against end-use industry expenditure patterns ensure consistency.
Sensitivity analysis around refrigerant transition timelines and biodegradable adoption curves stress-tests projection robustness. The analytical framework segments by dye chemistry type, carrier formulation base, end-use vertical, and regional regulatory cluster across the modeling period. CAGRs derive from installed base aging profiles, maintenance interval lengthening under building energy codes, and compliance-driven specification shifts. Industry-specific inputs include R-1234yf transition velocity and UV-LED cost-down curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of leak inspection mandates would require recalibration. Forecasts reflect assumptions regarding REACH authorization timelines and EPA SNAP disposal rule adherence. Revision becomes warranted when electronic leak detector price-performance ratios cross thresholds that displace dye-based protocols in high-volume automotive segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market