
 Asia-Pacific Vaccines Market | 2026-2036
Asia-Pacific Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vaccines Market Analysis
Buyer concentration across Asia-Pacific national immunization programs is pivoting toward centralized tendering and pooled procurement alliances. Serum Institute of India leverages unmatched manufacturing scale to supply UNICEF and Gavi-eligible markets across South Asia. Sinovac anchors its position through captive fill-finish capacity and domestic distribution density in China. Chongqing Zhifei Biological Products specializes in meningococcal and pneumococcal franchises, competing on regional label expansions rather than global footprint.
Asia-Pacific vaccines comprise biologically active preparations containing attenuated, inactivated, or recombinant antigenic components, formulated with adjuvants and stabilizers to elicit protective immune responses at dosage volumes typically ranging from 0.5 mL to 1.0 mL per dose. Messenger RNA vaccines command premium positioning due to thermostability engineering requirements and lipid nanoparticle formulation complexity, while live attenuated vaccines retain cost advantages in measles-rubella and rotavirus programs where cold chain infrastructure reaches district levels. Injection delivery dominates value capture, though intranasal platforms are gaining fastest traction in influenza and COVID-19 booster segments across Japan and South Korea.
India's CDSCO and China's NMPA operate parallel approval pathways that create divergent market access timelines, with India's recent streamlined vaccine licensing reforms compressing review cycles for indigenously developed candidates. Australia's TGA and South Korea's MFDS maintain PIC/S-aligned GMP standards that function as de facto export passports for manufacturers targeting Southeast Asian procurement bodies. Stakeholders must monitor regulatory reciprocity negotiations between ASEAN member states and India's drug regulator, as mutual recognition agreements will determine which production sites qualify for accelerated national tender eligibility across the region.
Market Dynamics
India's PLI scheme for biotechnology manufacturing is redrawing production geography across Asia-Pacific vaccines, pulling fill-finish capacity toward Gujarat and Maharashtra industrial corridors while compressing lead times for UNICEF tenders.
Growth Catalysts
- CDSCO Streamlined Licensing:India's compressed review cycles for indigenously developed candidates accelerate commercialization timelines for domestic manufacturers targeting national immunization programs.
- Cold-Chain-Independent Delivery:Thermostable formulation engineering enables last-mile distribution to district health centers lacking refrigerated transport infrastructure across Indonesia and Philippines archipelagos.
- Expanded Birth Cohorts:Pediatric immunization schedules in India tighten coverage targets as annual live births exceed twenty-three million, sustaining volume demand for measles-rubella and pentavalent formulations.
Market Restraints
- Lipid Nanoparticle Input Concentration:Specialty lipid suppliers cluster in Germany and Switzerland, exposing mRNA vaccine producers to euro-denominated cost volatility and single-source qualification timelines.
- Parallel Approval Pathways:CDSCO and NMPA operate non-harmonized review standards, forcing manufacturers to duplicate stability studies and clinical bridging trials for India and China market access.
- Live Attenuated Cold Chain Dependency:Rotavirus and oral polio vaccines require sustained 2-8°C integrity through district storage, limiting penetration in Papua New Guinea and Myanmar border regions.
Strategic Opportunities
- Vietnam Manufacturing Localization:Greenfield fill-finish investments near Ho Chi Minh City position suppliers for ASEAN procurement pooling mechanisms under mutual recognition negotiations.
- Intranasal Platform Convergence:Adjuvanted live vector technologies combined with microneedle delivery systems open self-administration pathways for influenza and COVID-19 boosters in Japanese pharmacy channels.
- Australia TGA Export Passporting:PIC/S-aligned GMP certification from Sydney and Melbourne facilities qualifies manufacturers for accelerated tender eligibility across Thailand and Malaysia national programs.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Upstream cell culture and downstream purification specialists command premium compensation in Bangalore and Shanghai, constraining scale-up velocity at mid-cap facilities.
- Legacy Fill-Finish Retrofit Capex:Isolator technology upgrades and single-use system conversions demand capital allocation competing with pipeline R&D at established Pune and Beijing production sites.
- Multi-Country Label Harmonization:Divergent age-range indications and contraindication language across MFDS, TGA, and ASEAN national formularies fragment batch release workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vaccines Market |
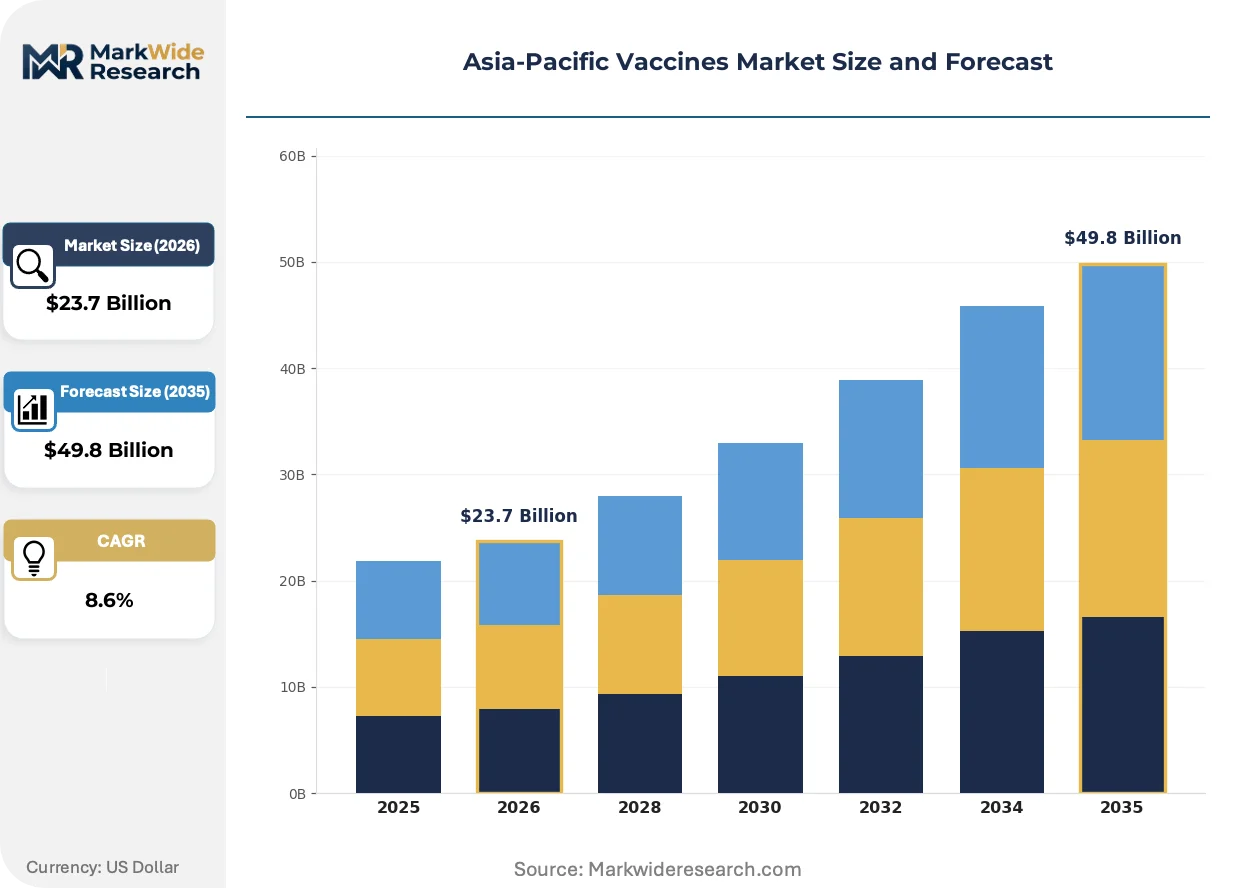
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccines, Live Attenuated Vaccines, Subunit Vaccines, Messenger RNA Vaccines Delivery Mode: Injection, Oral, Intranasal, Transdermal End User: Hospitals, Clinics, NGOs, Pharmacies Application: Pediatric Immunization, Travel Vaccination, Outbreak Control, Routine Immunization |
| Companies Covered | Serum Institute of India, Pfizer Inc., Merck & Co., Inc., GSK plc, Sanofi, AstraZeneca, Bharat Biotech, Sinovac, Chongqing Zhifei Biological Products, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vaccines Market Emerging Trajectories
Messenger RNA thermostability engineering is rewriting formulation priorities across Asia-Pacific vaccine development, compressing the gap between laboratory stability data and tropical distribution realities.
Microneedle array patches for intradermal delivery are expanding into pediatric and elderly immunization protocols where needle phobia and healthcare worker shortage constrain coverage. Japanese municipal health boards pilot seasonal influenza programs using self-administered patches, reducing clinic throughput bottlenecks during peak vaccination windows. This platform is expanding into travel medicine and occupational health segments where convenience premiums offset higher per-dose manufacturing costs.
Australia's TGA has implemented enhanced pharmacovigilance reporting mandates for novel adjuvant systems, requiring real-world safety surveillance infrastructure before provisional registration. This policy compresses development timelines for sponsors with existing post-market networks while delaying first-in-class entries from manufacturers lacking Australian clinical trial footprints. Protein subunit and virus-like particle candidates face extended review cycles compared to established aluminum-adjuvanted formulations.
Centralized tendering alliances among ASEAN member states are consolidating procurement volume under pooled negotiation frameworks, displacing bilateral manufacturer relationships. National immunization programs in Thailand, Indonesia, and Philippines now coordinate annual requirement forecasts through shared technical committees, standardizing specification language and stability requirements. This concentration is most visible in pneumococcal conjugate and human papillomavirus categories where price transparency across borders pressures incumbent suppliers.
Asia-Pacific Vaccines Market Segmentation
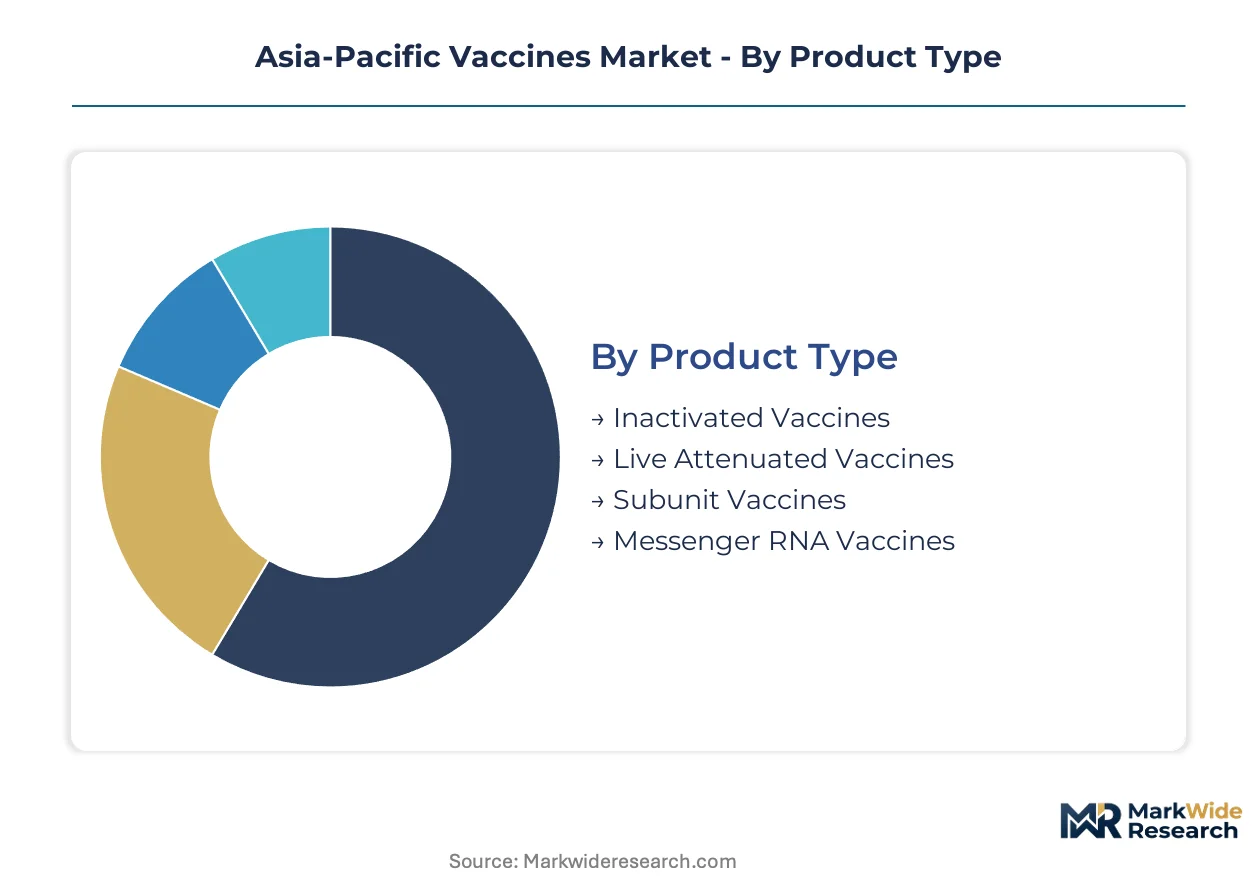
Asia-Pacific vaccine procurement operates through divergent decision frameworks across public immunization programs, private healthcare networks, and humanitarian supply chains. Segmentation reveals where formulation investments align with distribution infrastructure realities and where delivery mode innovation unlocks coverage gaps.
Product Type:
Procurement officers weigh thermostability requirements against cold-chain reach when selecting antigen platforms for national programs.
- Inactivated Vaccines:Formalin or beta-propiolactone treated whole pathogens retain immunogenicity without replication risk. India's Universal Immunization Program sources inactivated polio and hepatitis A volumes through centralized CDSCO-qualified tenders.
- Live Attenuated Vaccines:Weakened pathogen strains elicit durable cellular immunity at lower antigen doses. Measles-rubella and rotavirus liquid formulations dominate South Asian pediatric schedules where 2-8°C district storage is achievable.
- Subunit Vaccines:Purified protein or polysaccharide antigens combined with aluminum or novel adjuvants. Recombinant hepatitis B and acellular pertussis components anchor combination vaccines across ASEAN procurement pools.
- Messenger RNA Vaccines:Lipid nanoparticle-encapsulated nucleoside-modified mRNA requiring ultra-cold or engineered thermostable distribution. COVID-19 boosters and investigational influenza candidates concentrate in Japan, South Korea, and Australian private channels.
Inactivated platforms lead on scale through UNICEF supply agreements; messenger RNA leads on momentum through thermostability engineering advances.
Delivery Mode:
Last-mile infrastructure constraints and healthcare worker density determine route selection across archipelagic and mountainous geographies.
- Injection:Intramuscular or subcutaneous administration via prefilled syringes or multi-dose vials. Intradermal rabies and fractional yellow fever dosing reduces antigen requirements in Philippine and Indonesian outbreak responses.
- Oral:Live attenuated formulations bypass cold-chain-dependent needle programs. Rotavirus and oral polio vaccines penetrate Papua New Guinea highlands and Myanmar border regions where injection logistics fail.
- Intranasal:Mucosal delivery inducing IgA responses at respiratory portals. Adjuvanted live vector influenza platforms pilot in Japanese municipal pharmacy channels to reduce clinic congestion.
- Transdermal:Microneedle array patches enabling self-administration. Australian and South Korean travel medicine segments test convenience premiums against higher manufacturing costs.
Injection retains volume dominance; intranasal gains share fastest through pharmacy channel expansion.
End User:
Budget flow and patient access pathways segment procurement authority across public and private financing systems.
- Hospitals:Tertiary centers manage complex immunocompromised protocols and travel medicine consults. Australian public hospitals anchor state-level formulary decisions affecting regional procurement.
- Clinics:Primary health centers execute national immunization schedules at district level. India's Ayushman Bharat health and wellness clinics expand pentavalent and measles-rubella coverage in underserved blocks.
- NGOs:Gavi-eligible country support and humanitarian emergency response. MSF and UNICEF supply chains bypass national tender delays in conflict-affected Myanmar and flood-disaster Philippines provinces.
- Pharmacies:Retail channels capture out-of-pocket influenza, pneumococcal, and travel vaccines. Japanese and South Korean pharmacy vaccination laws unlock self-pay segments beyond clinic capacity.
Clinics anchor public program scale; pharmacies climb fastest through regulatory liberalization.
Application:
Disease burden demographics and outbreak frequency allocate R&D and manufacturing capacity across preventive and reactive demand pools.
- Pediatric Immunization:Routine schedule compliance for birth cohorts exceeding twenty-three million annually in India. Pentavalent and pneumococcal conjugate volumes concentrate in CDSCO-regulated national tenders.
- Travel Vaccination:Pre-departure prophylaxis for outbound tourism and business travel. Japanese encephalitis and typhoid Vi-polysaccharide demand clusters in Bangkok, Singapore, and Sydney travel health clinics.
- Outbreak Control:Reactive campaign deployment for epidemic-prone diseases. Cholera, meningococcal, and yellow fever stockpiles rotate through WHO prequalified manufacturers serving Pacific Island and Southeast Asian emergencies.
- Routine Immunization:Adult booster schedules and occupational health programs. Hepatitis B and tetanus-diphtheria boosters sustain volume in Chinese workplace health schemes and Australian aged care mandates.
Pediatric immunization commands manufacturing scale; outbreak control shows steepest expansion trajectory through pandemic preparedness financing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioprocess engineering specialists cluster in Bangalore and Shanghai, commanding premium compensation that constrains scale-up velocity at mid-cap manufacturing facilities across the region.
India
Annual live births exceeding twenty-three million sustain volume demand for measles-rubella and pentavalent formulations. CDSCO streamlined licensing reforms compress review cycles for indigenously developed candidates. Gujarat and Maharashtra industrial corridors pull fill-finish capacity toward UNICEF tender supply chains.
China
Domestic distribution density anchors Sinovac's position through captive fill-finish capacity. NMPA operates parallel approval pathways creating divergent market access timelines from India. Chongqing Zhifei Biological Products specializes in meningococcal and pneumococcal franchises competing on regional label expansions.
Japan
Intranasal platforms gain fastest traction in influenza and COVID-19 booster segments through pharmacy channel expansion. METI and PMDA pilot seasonal influenza programs using self-administered microneedle patches. Municipal health boards reduce clinic throughput bottlenecks during peak vaccination windows.
Australia
PIC/S-aligned GMP standards from TGA function as de facto export passports for manufacturers targeting Southeast Asian procurement bodies. Sydney and Melbourne facilities qualify for accelerated tender eligibility across Thailand and Malaysia national programs. Enhanced pharmacovigilance reporting mandates for novel adjuvant systems compress development timelines for sponsors with existing post-market networks.
South Korea
MFDS maintains PIC/S-aligned GMP standards supporting regional export positioning. Pharmacy vaccination laws unlock self-pay segments beyond clinic capacity for influenza and pneumococcal demand. Seoul Capital Area concentrates regulatory expertise and clinical trial infrastructure for accelerated product registration.
Asia-Pacific Vaccines Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered manufacturing scales. The market structure concentrates around three strategic archetypes: integrated biopharmaceutical conglomerates with captive vaccine divisions, specialized domestic manufacturers leveraging regulatory proximity, and research-intensive innovators pursuing novel delivery platforms. Competitive dynamics center on manufacturing scale attainment and regulatory pathway acceleration rather than price competition alone.
Within the specialized domestic manufacturer tier, Serum Institute of India exemplifies scale-driven supply positioning for national immunization programs. Sinovac occupies a position reflecting captive distribution density advantages. Chongqing Zhifei Biological Products represents regional franchise specialization over global footprint expansion.
| Leading Market Players |
|---|
| Serum Institute of India |
| Pfizer Inc. |
| Merck & Co., Inc. |
| GSK plc |
| Sanofi |
| AstraZeneca |
| Bharat Biotech |
| Sinovac |
| Chongqing Zhifei Biological Products |
| Others |
Supply Flow & Price Mechanics
Thermostable formulation engineering simultaneously compresses distribution economics and redistributes manufacturing leverage toward CDSCO-qualified Indian facilities capable of cold-chain-independent UNICEF tender fulfillment. This technical transition concentrates premium pricing power with mRNA lipid nanoparticle specialists while eroding margins for legacy live-attenuated suppliers locked into district-level refrigeration dependencies.
Pricing Analysis
Bundled tender pricing dominates Asia-Pacific national immunization programs while unbundled per-dose procurement persists in Japanese and South Korean pharmacy channels. Three-tier pricing structure across premium thermostable mRNA, standard aluminum-adjuvanted subunits, and economy live-attenuated liquid formulations reflects CDSCO versus NMPA regulatory qualification tiers. Price differentiation hinges on GMP certification alignment with PIC/S standards and UNICEF prequalification status. Cost compression in economy rotavirus and measles-rubella segments intensifies as Serum Institute of India scales fill-finish capacity under PLI subsidies. Government procurement officers in Indonesia and Philippines exhibit highest price sensitivity; Australian private travel medicine clinics demonstrate lowest sensitivity to per-dose premiums.
Supply Chain Analysis
Regional distribution centers in Mumbai, Shanghai, and Singapore anchor hub-and-spoke vaccine logistics across archipelagic Southeast Asian markets. Manufacturing concentrates in India, China, and South Korea, with fill-finish capacity clustering in Gujarat industrial corridors and Seoul Capital Area biotech parks. Specialty lipid inputs for mRNA platforms draw from German and Swiss chemical suppliers, creating euro-denominated cost exposure. Single-source vulnerability in lipid nanoparticle excipients threatens production continuity for thermostable COVID-19 and influenza candidates. Distribution runs through temperature-controlled air freight lanes into Jakarta, Manila, and Bangkok, with last-mile cold chain extension to district health centers determining coverage penetration in Papua New Guinea and Myanmar border regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific vaccines function as a geographic-arbitrage play where CDSCO streamlined licensing reforms compress commercialization timelines relative to NMPA parallel approval burdens, enabling Indian manufacturers to capture UNICEF tender volume before Chinese competitors achieve equivalent market access.
For Market Incumbents: Anticipate regulatory reciprocity negotiations between ASEAN member states and India's drug regulator by pre-qualifying additional production lines for mutual recognition eligibility. Consolidate backward integration into specialty lipid supply through captive partnerships with German chemical suppliers to defuse single-source mRNA input risk. Prioritize TGA-aligned GMP certification upgrades at Sydney and Melbourne facilities to maintain accelerated tender access across Thailand and Malaysia national programs.
For New Entrants and Emerging Players: Pharmacy channel partners in Japan and South Korea offer the most penetrable entry vector for intranasal and transdermal delivery platforms seeking self-administration market positioning. Target Vietnam manufacturing localization near Ho Chi Minh City to secure ASEAN procurement pooling qualification under evolving mutual recognition frameworks. Pursue co-development alliances with established CDSCO-registered manufacturers to bypass duplicative stability study requirements for Indian market access.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap facilities possessing PIC/S-aligned GMP certification but lacking UNICEF prequalification scale. Long-term viability across the analysis window hinges on thermostability engineering capabilities and cold-chain-independent distribution infrastructure. Acquisition screening should prioritize Bangalore and Shanghai bioprocess engineering talent density as the inflection indicator for scale-up velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Streamlined Licensing Compliance | Accelerated review cycles compress commercialization timelines for indigenously developed candidates targeting national immunization programs. |
| TGA Export Passport Certification | PIC/S-aligned GMP standards from Sydney facilities qualify manufacturers for accelerated tender eligibility across Thailand and Malaysia. |
| Vietnam Manufacturing Localization | Greenfield fill-finish investments near Ho Chi Minh City position suppliers for ASEAN procurement pooling mechanisms. |
| Intranasal Platform Development | Adjuvanted live vector technologies combined with microneedle delivery open self-administration pathways in Japanese pharmacy channels. |
| Specialty Lipid Backward Integration | Captive supply partnerships with German chemical suppliers defuse euro-denominated cost volatility for mRNA lipid nanoparticle inputs. |
Methodological Framework
Direct dialogue with vaccine development executives, regulatory affairs leads at CDSCO and NMPA, UNICEF procurement officers, and hospital formulary directors grounded primary intelligence. Secondary validation drew from CDSCO licensing databases, WHO prequalification listings, ClinicalTrials.gov entries, and ASEAN procurement pooling framework documents. Bottom-up demand modeling across pediatric immunization schedules, travel medicine protocols, and outbreak control stockpiles triangulated against top-down national health expenditure forecasts.
Bottom-up volume builds aggregated antigen platform demand across inactivated, live-attenuated, subunit, and mRNA categories, segmented by delivery mode and end-user channel. Top-down macro validation referenced national immunization program budget allocations and Gavi-eligible country financing envelopes. Modeled dimensions included product type, delivery mode, end-user institution, and application category across the projection horizon. CAGRs derived from logistic curve penetration modeling for novel platforms and linear extrapolation for mature schedule compliance. Forecast inputs incorporated birth cohort projections, regulatory approval velocity differentials, and cold-chain infrastructure investment pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory reciprocity negotiation timelines, lipid nanoparticle supply concentration, and thermostability engineering breakthroughs. Outputs reflect documented assumptions around CDSCO reform implementation pace and ASEAN mutual recognition progression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Traveler's Diarrhea Treatment Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market