
 Gabapentin Market | 2026-2036
Gabapentin Market Size, Share, and Industry Trends Forecast 2026-2036
Gabapentin Market Intelligence
Hospital and retail pharmacy procurement is rewriting competitive access for gabapentin suppliers across North America and Europe. Pfizer Inc. anchors the branded legacy segment through its original Neurontin franchise and sustained physician familiarity. Teva Pharmaceutical Industries Ltd. dominates the generic capsule and tablet landscape through manufacturing scale and FDA-approved abbreviated new drug applications. Sun Pharmaceutical Industries Ltd. extends its position through aggressive pricing in retail pharmacy channels and emerging market registrations.
Gabapentin is a gamma-aminobutyric acid analog with a cyclohexane ring and aminomethyl side chain, formulated as immediate-release or extended-release solid oral dosage forms for seizure control and neuropathic pain modulation. The drug functions by binding to the alpha-2-delta subunit of voltage-gated calcium channels, reducing excitatory neurotransmitter release without direct GABA receptor agonism. Capsule and tablet formulations occupy the mature volume core, while extended-release formulations command premium positioning due to compliance advantages and patent-protected delivery technologies. Neuropathic pain indications generate the largest revenue pool, though anxiety disorder prescribing is expanding fastest in psychiatric and primary care settings where off-label protocols proliferate.
FDA bioequivalence standards for narrow therapeutic index anticonvulsants constrain generic substitution protocols, while the DEA's state-level scheduling variations for gabapentin in Kentucky, West Virginia, and Tennessee reshape dispensing controls and prescription monitoring requirements. The EMA's pharmacovigilance directives for central nervous system active substances impose additional post-market surveillance obligations on European suppliers. Stakeholders must monitor evolving state-level scheduling decisions and payer prior-authorization criteria, as these regulatory levers will determine which formulation categories and distribution channels retain unrestricted growth trajectories.
Market Dynamics
FDA bioequivalence standards for narrow therapeutic index anticonvulsants are compressing generic substitution windows, forcing manufacturers to recalibrate formulation investments around compliance rather than pure cost minimization.
Growth Catalysts
- DEA state-level scheduling expansion:Kentucky, West Virginia, and Tennessee have implemented prescription monitoring requirements that normalize gabapentin tracking, expanding the addressable patient pool through controlled-substance protocols.
- Off-label psychiatric prescribing:Primary care physicians are expanding anxiety disorder protocols to include gabapentin, creating volume pull from psychiatric and general practice settings.
- Extended-release formulation uptake:Patent-protected delivery technologies are capturing premium positioning through compliance advantages in chronic pain management.
Market Restraints
- Active pharmaceutical ingredient concentration:Manufacturing of gabapentin API clusters in select Asian supply zones, exposing finished dose producers to single-source geographic risk.
- FDA bioequivalence testing costs:Narrow therapeutic index classification mandates expensive pharmacokinetic studies that erode generic developer margins.
- Pregabalin substitution pressure:Pfizer's Lynda franchise captures overlapping neuropathic pain indications with superior pharmacokinetic profiles in some patient subsets.
Strategic Opportunities
- Brazilian regulatory pathway acceleration:ANVISA's streamlined abbreviated new drug application process for established anticonvulsants reduces time-to-market for generic entrants.
- Hospital formulary consolidation:Health system procurement centralization creates volume aggregation points for manufacturers with integrated distribution capabilities.
- Telehealth prescribing expansion:Remote consultation platforms are extending gabapentin access into rural and underserved primary care markets.
Industry Challenges
- Pharmacovigilance workforce scarcity:EMA post-market surveillance obligations for central nervous system active substances require specialized safety monitoring expertise that outpaces available talent pools.
- Legacy ERP integration:Track-and-trace serialization mandates are forcing wholesale distributors to reconfigure inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gabapentin Market |
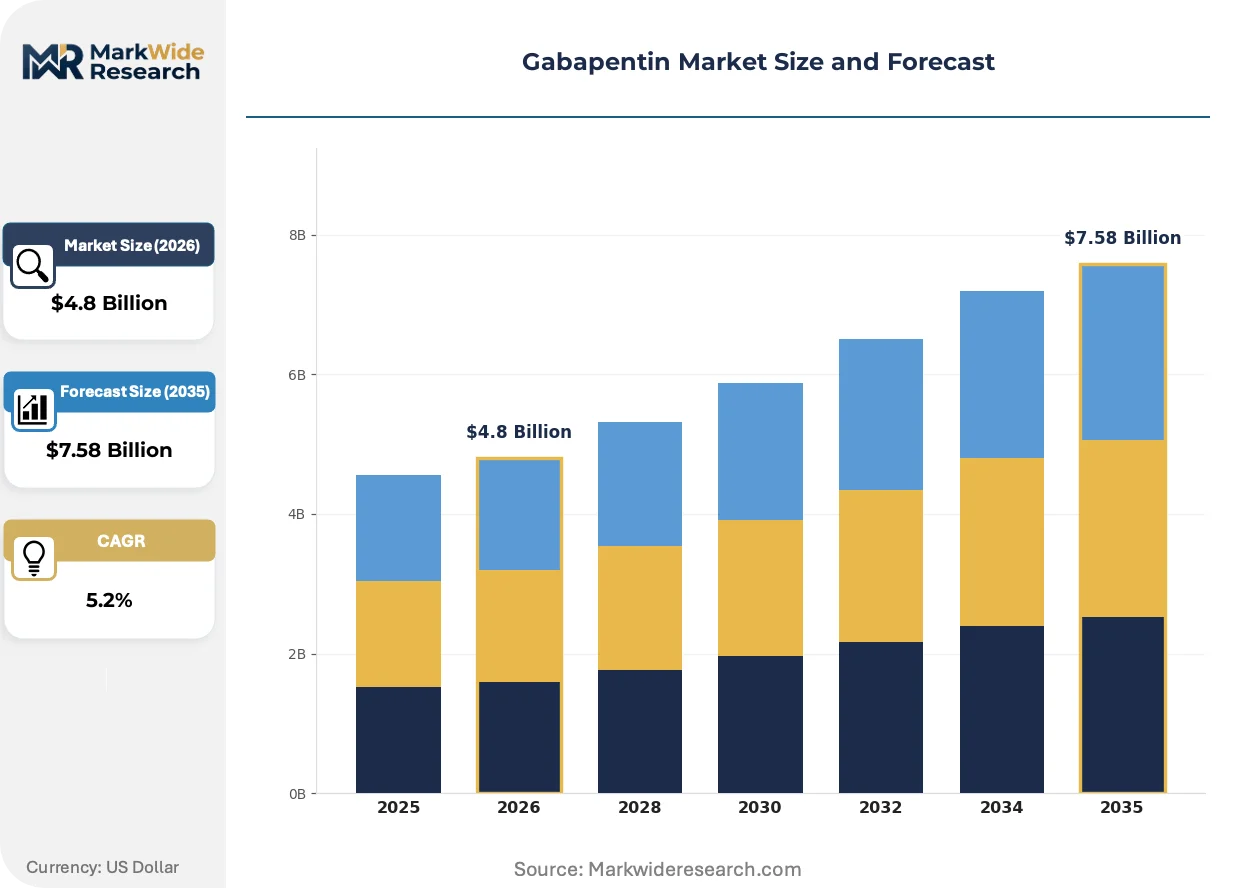
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Oral Solution, Injectable Indication: Neuropathic Pain, Epilepsy, Anxiety Disorders, Restless Legs Syndrome Formulation: Immediate Release, Extended Release, Combination Therapy, Topical Formulation Distribution Channel: Hospitals, Retail Pharmacies, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., Viatris, Sun Pharmaceutical Industries Ltd., Aurobindo Pharma Ltd., Dr. Reddy's Laboratories Ltd., Apotex Inc., Glenmark Pharmaceuticals Ltd., Hikma Pharmaceuticals PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gabapentin Market Strategic Shifts & Innovations
Formulation science and regulatory architecture are converging to reshape competitive positioning, with delivery technology investments separating premium from commodity supply tiers.
Extended-release matrix systems are collapsing the compliance advantage gap between branded and generic offerings. Hospital systems adopting these formulations for chronic pain protocols are reducing pill burden while manufacturers with proprietary polymer platforms capture formulary preference. The technology is collapsing price elasticity in the maintenance therapy segment.
EMA pharmacovigilance directives for central nervous system active substances are extending post-market surveillance obligations across European suppliers. Drug safety databases must now capture real-world neurological adverse events with accelerated reporting timelines. Generic manufacturers without established pharmacovigilance infrastructure face compliance cost disadvantages in Germany, France, and Italy.
Hospital procurement centralization is consolidating purchasing authority into integrated delivery networks. Independent retail pharmacies are losing volume to health system-owned dispensaries with captive patient flows. The shift is most visible in United States metropolitan markets where vertical health system integration has advanced furthest.
Gabapentin Market Segmentation
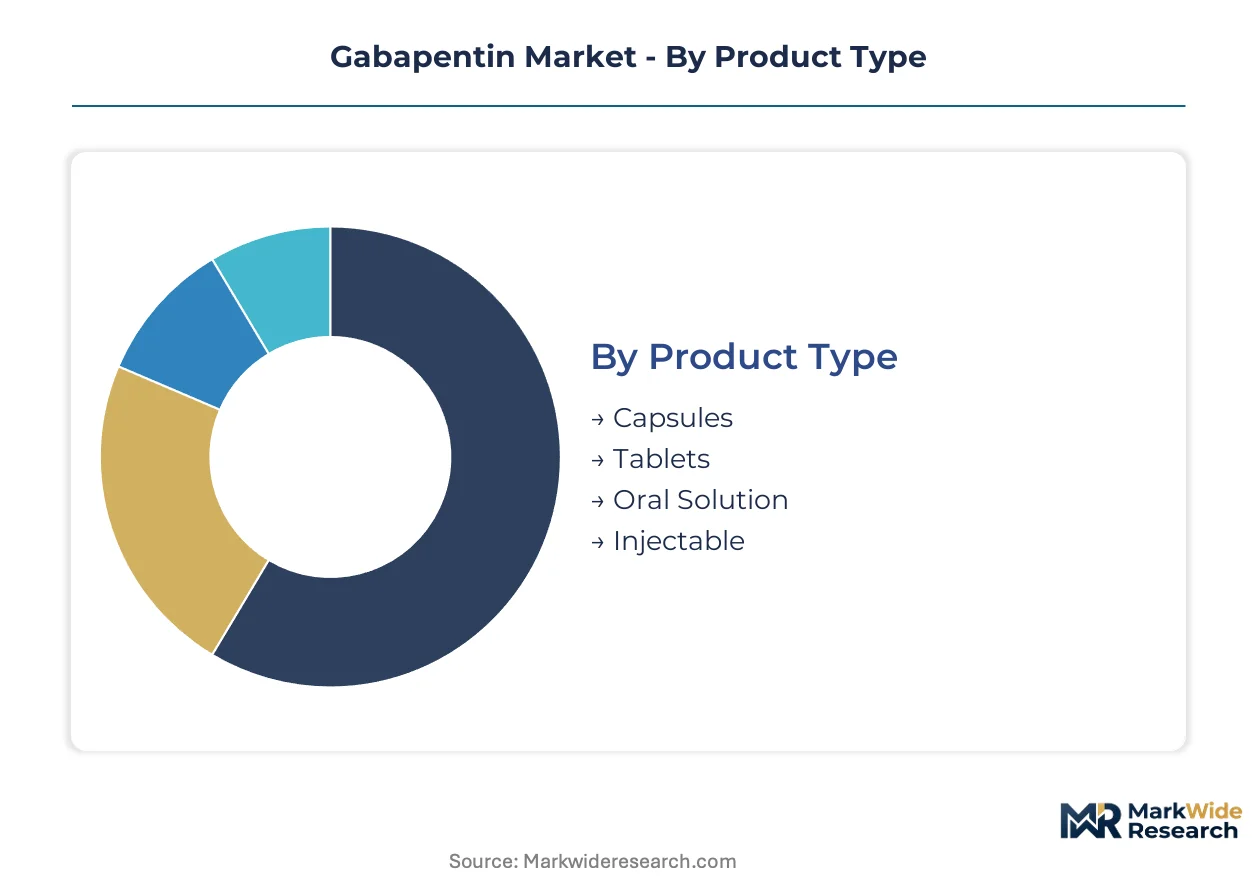
Formulation differentiation and distribution channel access determine competitive positioning in gabapentin supply. Manufacturers must align product development with specific indication requirements and procurement consolidation trends across health systems.
Product Type:
After-sales service intensity varies sharply across solid oral and liquid dosage forms, with packaging stability and patient counseling demands driving support cost structures.
- Capsules:Gelatin or HPMC shells containing gabapentin powder offer precise unit dosing and moisture protection. Demand concentrates in United States retail pharmacy chains where 30-day and 90-day dispensing protocols dominate chronic pain management. FDA dissolution specifications for gelatin-based shells constrain supplier flexibility.
- Tablets:Compressed solid dosage forms enable cost-efficient high-volume production through direct compression or wet granulation. European hospital procurement in Germany and France favors scored tablets for dose titration flexibility in epilepsy protocols. EMA bioequivalence requirements for narrow therapeutic index classification elevate testing costs.
- Oral Solution:Aqueous suspensions provide swallowing alternatives for pediatric and geriatric populations with dysphagia.
- Injectable:Parenteral formulations serve perioperative and acute care settings where oral administration is contraindicated.
Capsules hold the largest share; momentum sits with tablets as hospital formulary standardization accelerates.
Indication:
Prescribing volume clusters around neurologic and psychiatric applications, with reimbursement pathways and clinical guideline acceptance shaping segment economics.
- Neuropathic Pain:Diabetic peripheral neuropathy and postherpetic neuralgia drive the core revenue pool through long-term maintenance therapy. United States Medicare Part D claims data shows concentration in primary care networks across Florida, Texas, and California. FDA-approved labeling for this indication anchors prior authorization pathways.
- Anxiety Disorders:Off-label prescribing in generalized anxiety and social anxiety protocols is expanding fastest in United States psychiatric and primary care settings. Kentucky, West Virginia, and Tennessee prescription monitoring programs now track gabapentin dispensing alongside controlled substances.
- Epilepsy:Adjunctive therapy for partial seizures maintains steady volume through pediatric and adult neurologist prescribing.
- Restless Legs Syndrome:Symptomatic treatment for moderate-to-severe primary RLS captures sleep medicine specialty volume.
Neuropathic pain holds the largest share; anxiety disorders are climbing the fastest as off-label protocols proliferate.
Formulation:
Release kinetics and delivery technology investments separate premium positioning from commodity supply tiers in manufacturer portfolios.
- Immediate Release:Rapid dissolution formulations achieve peak plasma concentrations within 2-3 hours for acute symptom control. United States generic manufacturers compete on FDA-approved abbreviated new drug application volume and manufacturing scale. Teva Pharmaceutical Industries and Sun Pharmaceutical Industries dominate this tier through cost positioning.
- Extended Release:Matrix or osmotic pump systems sustain plasma levels over 12-24 hours, reducing pill burden for chronic pain patients. Hospital systems in United States metropolitan markets with vertical integration are adopting these for formulary preference. Patent-protected polymer platforms command premium pricing.
- Combination Therapy:Fixed-dose combinations with NSAIDs or other analgesics target multimodal pain management protocols.
- Topical Formulation:Transdermal or gel preparations deliver localized action with reduced systemic exposure for peripheral neuropathy.
Immediate release holds the largest share; extended release is gaining share fastest through compliance advantages in health system procurement.
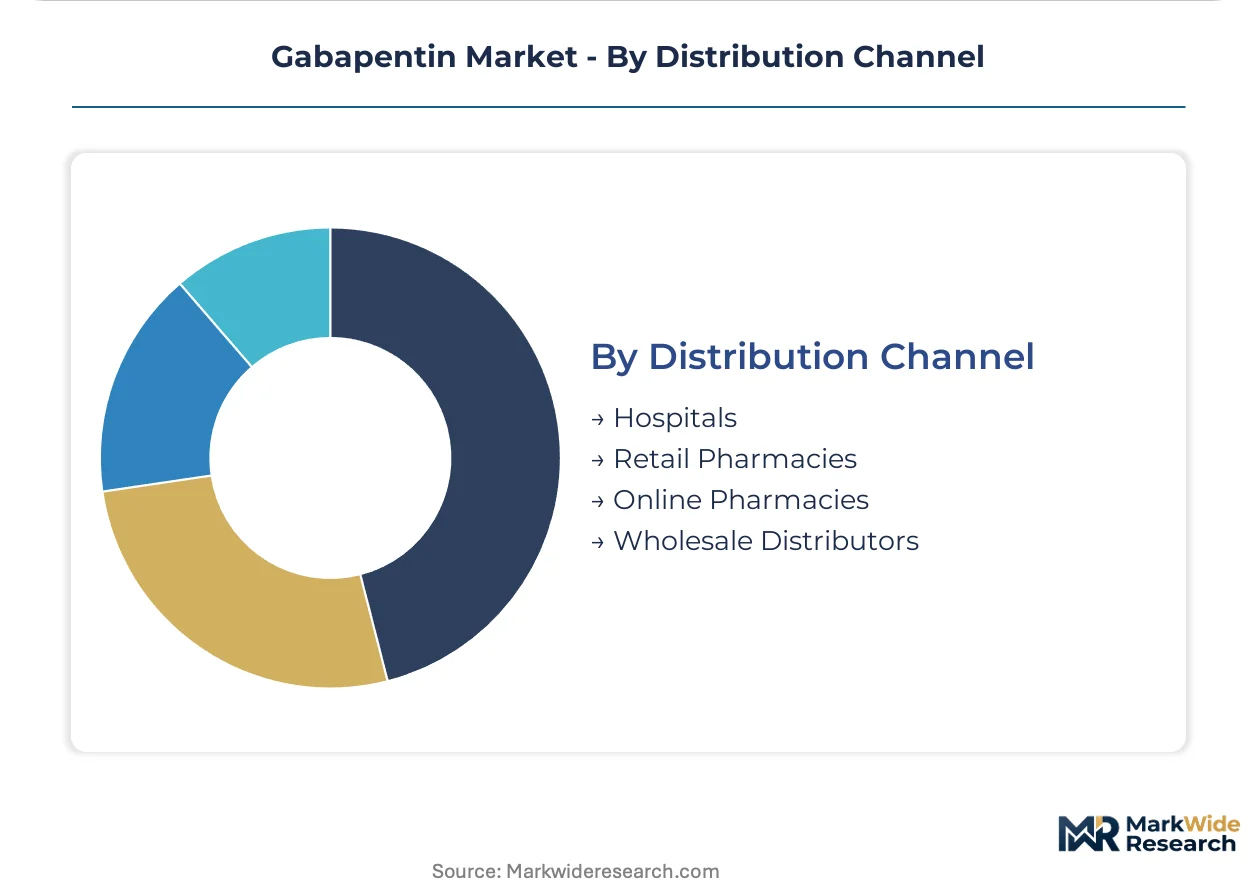
Distribution Channel:
Channel concentration reflects health system consolidation and regulatory tracking requirements for controlled-substance-equivalent monitoring.
- Hospitals:Integrated delivery network procurement centralizes purchasing authority for inpatient and outpatient dispensing. United States health systems in metropolitan markets with captive patient flows are consolidating formulary decisions. DEA state-level scheduling in Kentucky, West Virginia, and Tennessee requires enhanced inventory tracking.
- Retail Pharmacies:Independent and chain pharmacies serve the majority of chronic maintenance prescriptions. CVS Health and Walgreens Boots Alliance volume aggregates in United States suburban and rural markets. Prior authorization requirements from commercial payers constrain substitution flexibility.
- Online Pharmacies:Mail-order and digital platforms extend access for 90-day maintenance supplies.
- Wholesale Distributors:McKesson, AmerisourceBergen, and Cardinal Health aggregate volume for downstream pharmacy supply.
Retail pharmacies hold the largest share; hospitals are expanding most quickly through vertical integration and formulary consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA bioequivalence mandates and DEA state-level scheduling protocols anchor United States demand, while EMA pharmacovigilance frameworks reshape European supplier obligations. Geographic concentration reflects hospital procurement consolidation and prescription monitoring expansion.
United States
Off-label psychiatric prescribing and chronic pain management protocols drive volume across primary care networks. Kentucky, West Virginia, and Tennessee DEA scheduling variations impose prescription monitoring requirements that normalize controlled-substance-equivalent tracking. Hospital formulary consolidation in metropolitan markets with vertical health system integration accelerates extended-release adoption.
Germany
EMA pharmacovigilance directives for central nervous system active substances elevate post-market surveillance costs for generic manufacturers. Scored tablet demand concentrates in hospital epilepsy protocols requiring dose titration flexibility. Industrial pharmaceutical clusters in North Rhine-Westphalia and Bavaria host formulation facilities adapting to narrow therapeutic index compliance standards.
Brazil
ANVISA streamlined abbreviated new drug application processes reduce time-to-market for established anticonvulsant entrants. Generic manufacturer registrations accelerate as neuropathic pain protocols expand through public health system formularies. São Paulo and Rio de Janeiro metropolitan markets concentrate distribution infrastructure for southeastern patient access.
India
Active pharmaceutical ingredient manufacturing clusters in Gujarat and Maharashtra supply global finished dose producers with concentrated geographic exposure. CDSCO regulatory harmonization with FDA standards elevates export compliance investments for domestic manufacturers. Hyderabad and Ahmedabad formulation hubs scale output for emerging market registrations.
United Kingdom
NHS formulary standardization around cost-effective generic capsules constrains branded extended-release penetration. MHRA post-Brexit regulatory autonomy maintains EMA-aligned pharmacovigilance obligations for central nervous system therapeutics. London and Southeast England procurement networks consolidate purchasing authority through integrated care systems.
Gabapentin Market Key Industry Players
Originator legacy franchises and high-volume generic manufacturers split the market into distinct strategic tiers. Branded incumbents leverage physician familiarity and patent-protected delivery technologies, while commodity suppliers compete on FDA abbreviated new drug application scale and manufacturing throughput. Three archetypes dominate: portfolio-diversified multinationals, API-integrated Indian generics, and regional hospital-contract specialists. Competitive moves center on M&A for formulary consolidation access and polymer platform licensing for extended-release differentiation.
Within the portfolio-diversified tier, Pfizer Inc. anchors the branded legacy segment through sustained physician familiarity with its original franchise. Among high-volume generic manufacturers, Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Ltd. occupy positions defined by manufacturing scale and FDA-approved abbreviated new drug application volume. These three exemplify the structural division between premium delivery technology and cost-driven commodity supply.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Viatris |
| Sun Pharmaceutical Industries Ltd. |
| Aurobindo Pharma Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Apotex Inc. |
| Glenmark Pharmaceuticals Ltd. |
| Hikma Pharmaceuticals PLC |
| Others |
Cost & Logistics Intelligence
Single-source API dependency in Gujarat and Maharashtra manufacturing clusters determines both pricing tier spreads and supply chain shape, as finished dose producers face geographic concentration risk that compresses generic margins while sustaining premium positioning for polymer-platform extended-release formulations.
Pricing Analysis
The customization-premium spread separates immediate-release commodity capsules from patent-protected extended-release tablets, with three-tier pricing structure across premium, standard, and economy levels anchored by FDA bioequivalence testing costs and polymer delivery technology licensing. Price differentiation hinges on formulation complexity and EMA pharmacovigilance compliance infrastructure. Pricing pressure stems from pregabalin substitution in neuropathic pain protocols. Retail pharmacy chains exhibit highest price sensitivity; hospital integrated delivery networks show lowest.
Supply Chain Analysis
Export-control regime angles from India's DGFT on active pharmaceutical ingredient shipments create regulatory chokepoints limiting flows to European and North American finished dose facilities. Supply concentrates in India, China, and the United States for API and formulation manufacturing. Raw material dependencies include gabapentin API, gelatin or HPMC capsule shells, and polymer excipients for extended-release matrices. Single-source geographic vulnerability represents the dominant structural risk. Distribution runs through wholesale distributors McKesson, AmerisourceBergen, and Cardinal Health to downstream hospital and retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gabapentin market functions as a service-attach opportunity where pharmacovigilance infrastructure and patient compliance programs generate recurring revenue layers expanding faster than commodity capsule volumes.
For Market Incumbents: Build regulatory compliance moats through EMA-aligned pharmacovigilance databases and FDA-approved abbreviated new drug application scale. Invest in polymer platform R&D to defend against pregabalin substitution pressure. Acquire Brazilian ANVISA registration capabilities to capture emerging market volume aggregation.
For New Entrants and Emerging Players: Establish a beachhead in extended-release formulation segments where patent-protected delivery technologies command premium positioning. Target anxiety disorder off-label prescribing protocols in United States primary care networks as the most penetrable application. Deploy telehealth partnership channels for rural market access.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors API-integrated manufacturers with captive supply chains. Long-term viability over the next decade hinges on backward integration into Indian API production. Watch DEA state-level scheduling expansion as the signal indicating formulary access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Platform Licensing | Captures premium positioning through FDA-approved extended-release bioequivalence pathways. |
| EMA Pharmacovigilance Infrastructure Buildout | Enables European market access by satisfying post-market surveillance obligations for CNS actives. |
| ANVISA Registration Acceleration | Reduces time-to-market for generic entrants in Brazilian public health system formularies. |
| Hospital System Partnership | Secures formulary preference through integrated delivery network procurement centralization. |
| Telehealth Channel Integration | Extends gabapentin access into rural United States primary care markets via remote consultation platforms. |
Research Approach
Operator-level perspectives from formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and Medicare Part D claims data. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to ensure consistency.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions including formulation type, indication category, distribution channel, and regional regulatory cluster. CAGRs were derived from patient population epidemiology, prescribing protocol adoption curves, and health system procurement trend analysis. Forecast inputs incorporated DEA scheduling expansion trajectories and EMA pharmacovigilance cost escalations.
Stress conditions across API supply disruption, pregabalin substitution rates, and state-level scheduling variations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance cost structures and hospital consolidation velocity. Material shifts in FDA narrow therapeutic index classification standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Egypt Diabetes Drugs Market