
 Cell Therapy Contract Development and Manufacturing Organization Market | 2026-2036
Cell Therapy Contract Development and Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Therapy Contract Development and Manufacturing Organization Market Insights
FDA's regenerative medicine advanced therapy designation is broadening the cost-of-entry calculus for new CDMO entrants by compressing development timelines and raising validation benchmarks. Lonza Group leverages its end-to-end manufacturing platform to anchor autologous cell therapy production across multiple continents. Catalent sustains competitive differentiation through integrated plasmid supply and viral vector capabilities that span clinical to commercial scale.
A Cell Therapy Contract Development and Manufacturing Organization provides outsourced process development, GMP manufacturing, and quality control for living therapeutic products requiring cryopreservation, aseptic processing, and patient-specific or donor-derived cell handling. These organizations enable pharmaceutical and biotechnology developers to commercialize therapies without building captive cleanroom infrastructure. Manufacturing services commands the largest service type revenue pool due to capital intensity and batch failure risks, while gene-modified cell therapy represents the fastest-growing technology segment driven by CAR-T and CRISPR applications. Cancer treatment dominates application demand, though autoimmune disorder programs are expanding fastest as allogeneic platforms reduce per-patient production costs.
FDA, EMA, and WHO standards collectively govern cell therapy CDMO operations through GMP, gene therapy guidance, and donor material traceability requirements that determine market access and inspection readiness. Compliance with these frameworks shapes facility investment priorities, with dual FDA-EMA certification becoming a baseline for multinational sponsor contracts. Stakeholders must monitor evolving potency assay harmonization and decentralized manufacturing regulations that will determine which CDMOs capture next-generation platform contracts.
Market Dynamics
Autologous cell therapy manufacturing is concentrating production capacity among CDMOs capable of FDA dual-inspection readiness, as sponsor companies abandon in-house buildouts under compressed regenerative medicine advanced therapy timelines.
Growth Catalysts
- FDA regenerative medicine advanced therapy designation:Compressed approval pathways pull sponsor manufacturing decisions toward established CDMOs with prior successful inspections. This accelerates contract velocity for qualified facilities.
- Allogeneic platform maturation:Off-the-shelf cell therapies reduce per-patient manufacturing complexity. CDMOs capturing donor-derived master cell bank capabilities secure multi-year supply agreements.
- Gene-modified cell therapy:CRISPR and CAR-T applications expand addressable therapeutic categories. Viral vector integration demands force CDMOs to consolidate plasmid-to-final-product offerings.
Market Restraints
- Plasmid DNA supply concentration:Limited qualified suppliers for GMP-grade starting material create single-source vulnerabilities. Batch release timelines extend when supplier audits fail.
- FDA-EMA inspection divergence:Differing potency assay validation requirements force dual documentation tracks. Small CDMOs lack resources to maintain parallel quality systems.
- Aseptic processing facility scarcity:Grade A cleanroom construction costs exceed standard biologics infrastructure by multiples. Financing availability constrains new entrant capacity additions.
Strategic Opportunities
- Decentralized manufacturing models:Point-of-care cell processing near treatment centers reduces cryogenic logistics burdens. CDMOs developing closed-system automation capture regional hospital network contracts.
- Autoimmune disorder expansion:Allogeneic platforms lower cost thresholds for lupus and multiple sclerosis indications. Manufacturing scale economics improve across larger addressable patient populations.
- Japan PMDA regenerative medicine framework:Accelerated conditional approval pathways attract sponsor investment. CDMOs with Japanese facility presence secure Asia-Pacific commercialization partnerships.
Industry Challenges
- Cell therapy-specific workforce scarcity:Aseptic operators with living therapeutic handling experience command premium compensation. Training pipelines fail to match facility expansion rates.
- Supply chain reconfiguration friction:Patient-specific autologous logistics require cryogenic chain integrity across multiple handoffs. Temperature excursion events invalidate entire therapy batches.
- Legacy quality system integration:Small molecule CDMOs entering cell therapy struggle to adapt electronic batch records for living product traceability. Software validation timelines delay GMP certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Therapy Contract Development and Manufacturing Organization Market |
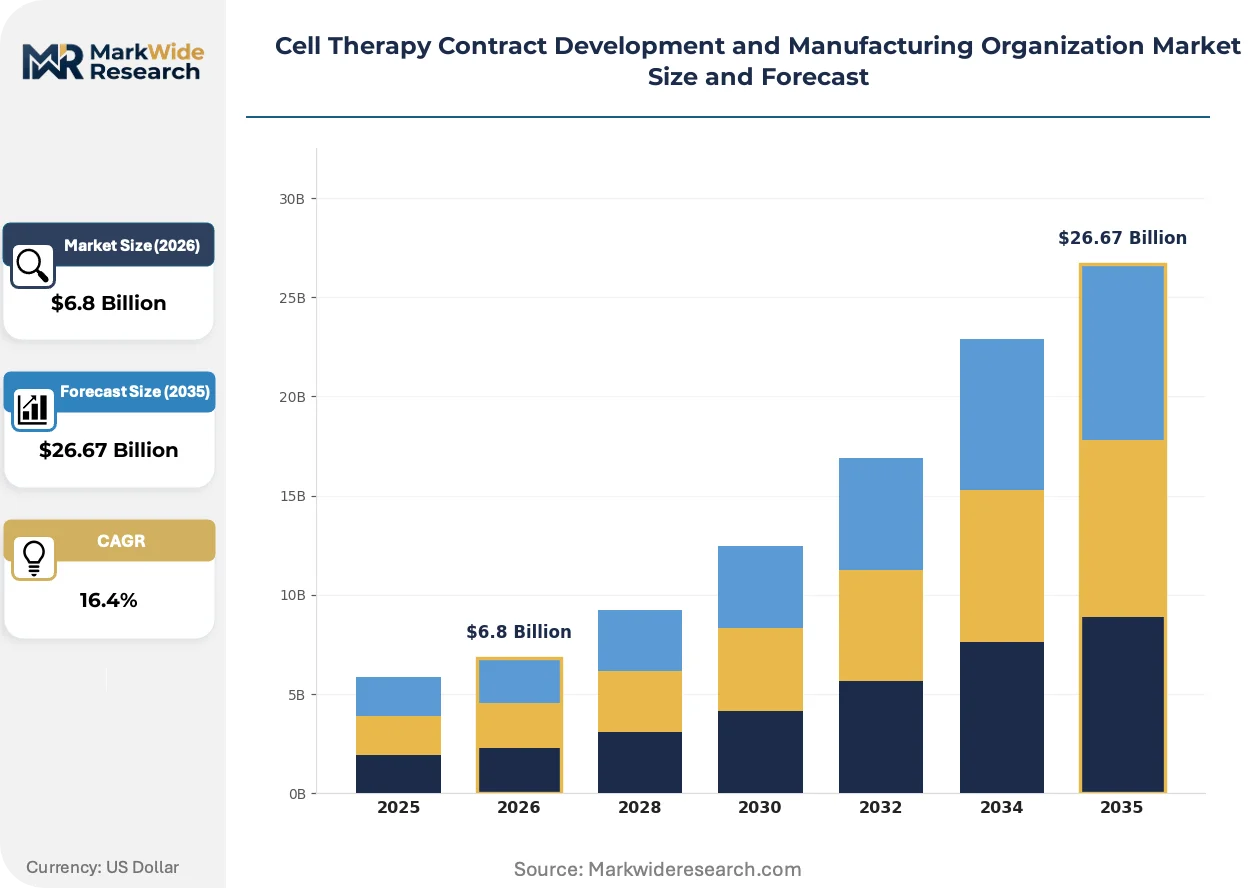
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Research Services, Process Development, Manufacturing Services, Quality Control End User: Biotechnology Companies, Pharmaceutical Companies, Research Institutions, Academic Organizations Technology: Autologous Cell Therapy, Allogeneic Cell Therapy, Gene-Modified Cell Therapy, Stem Cell Therapy Application: Cancer Treatment, Autoimmune Disorders, Genetic Disorders, Regenerative Medicine |
| Companies Covered | Lonza Group, Catalent, Thermo Fisher Scientific, FUJIFILM Diosynth Biotechnologies, WuXi Advanced Therapies, Charles River Laboratories, Recipharm, Patheon, Almac Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Therapy Contract Development and Manufacturing Organization Market Trends and Innovations
Closed-system automation and portable manufacturing platforms are compressing the geographic radius between production and patient, while regulatory harmonization efforts attempt to keep pace with platform evolution.
Modular cleanroom pods equipped with single-use bioreactors are decentralizing cell therapy manufacturing from centralized mega-sites to regional hospital-adjacent facilities. Academic medical centers in the United States and Germany are piloting these systems for autologous CAR-T processing at bedside-adjacent scale. This architecture collapses cold chain logistics requirements and enables same-day vein-to-vein treatment timelines previously impossible under centralized models.
EMA's forthcoming revision to gene therapy GMP annexes is tightening environmental monitoring requirements for viral vector production suites. European CDMOs are retrofitting facility HVAC systems to meet anticipated particle classification thresholds before formal adoption. Viral vector manufacturing capacity in Belgium and the Netherlands faces the steepest compliance investment burden given existing facility ages.
Sponsor procurement teams are unbundling analytical services from integrated manufacturing contracts, creating standalone CRO relationships for potency assay development. Large pharmaceutical buyers in the United States now require CDMOs to demonstrate third-party validated assay transfer capabilities before manufacturing award. This bifurcation pressures mid-size CDMOs to build captive analytical development headcount or surrender margin to specialized testing partners.
Cell Therapy Contract Development and Manufacturing Organization Market Segmentation
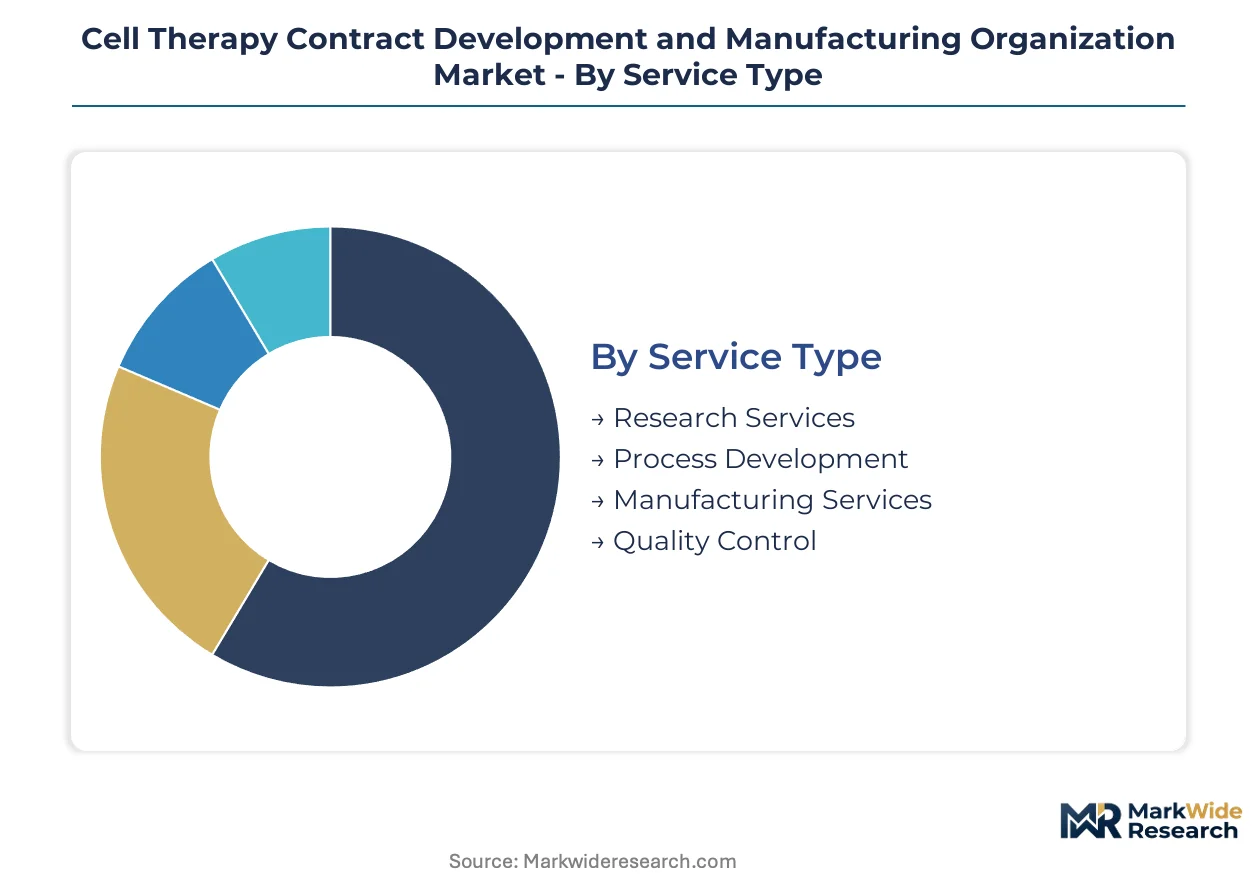
Cell therapy CDMOs structure their commercial offerings around distinct service bundles and technology platforms that carry divergent regulatory burdens. Understanding these segment boundaries clarifies where capital deployment concentrates and which capabilities command pricing premiums.
Service Type:
FDA dual-inspection readiness and EMA GMP Annex 1 compliance requirements vary sharply across these service categories, determining which CDMOs qualify for sponsor shortlists.
- Manufacturing Services:GMP-grade production of clinical and commercial batches demands Grade A cleanrooms, isolator technology, and validated aseptic processing lines. Pharmaceutical sponsors in the United States concentrate procurement here due to capital intensity and batch failure risks that disqualify inexperienced operators.
- Process Development:Scale-up optimization, media formulation, and tech transfer activities bridge research-grade protocols to manufacturable processes. Biotechnology companies in Germany and Switzerland drive demand as they advance CAR-T candidates toward regulatory submission.
- Research Services:Early-stage cell line characterization and proof-of-concept studies precede formal GMP engagement.
- Quality Control:Potency assay validation, sterility testing, and release analytics ensure batch compliance.
Manufacturing Services sits at the top of the volume ranking, with Process Development climbing the fastest.
End User:
Customer scale and internal manufacturing sophistication create distinct procurement patterns across these organization types.
- Pharmaceutical Companies:Large sponsors with regenerative medicine advanced therapy designations outsource commercial-scale production while retaining process development in-house. Their contracts demand multi-continent facility networks and prior successful FDA inspections.
- Biotechnology Companies:Venture-backed developers lack captive cleanroom infrastructure and require full-service partnerships from plasmid supply through final fill-finish. United States and United Kingdom clusters generate concentrated deal flow.
- Research Institutions:Academic medical centers pilot autologous processing for investigator-initiated trials.
- Academic Organizations:University-based cell therapy programs seek fee-for-service manufacturing for grant-funded studies.
Pharmaceutical Companies anchor contract value, though Biotechnology Companies are expanding their procurement footprint most aggressively.
Technology:
Platform complexity and donor material handling requirements differentiate regulatory pathways and facility investment priorities.
- Gene-Modified Cell Therapy:CRISPR-edited and CAR-T products require viral vector integration, creating plasmid-to-final-product consolidation imperatives. FDA gene therapy guidance and EMA's forthcoming GMP annex revisions impose the steepest compliance burdens.
- Allogeneic Cell Therapy:Off-the-shelf products derived from donor master cell banks reduce per-patient manufacturing complexity. CDMOs with cryopreserved cell banking capabilities capture multi-year supply agreements.
- Autologous Cell Therapy:Patient-specific manufacturing demands vein-to-vein logistics and cryogenic chain integrity.
- Stem Cell Therapy:Pluripotent and adult stem cell platforms face distinct potency assay validation requirements.
Gene-Modified Cell Therapy leads revenue concentration, while Allogeneic Cell Therapy gains share fastest as scale economics improve.
Application:
Therapeutic category determines batch size, reimbursement trajectory, and manufacturing location strategy.
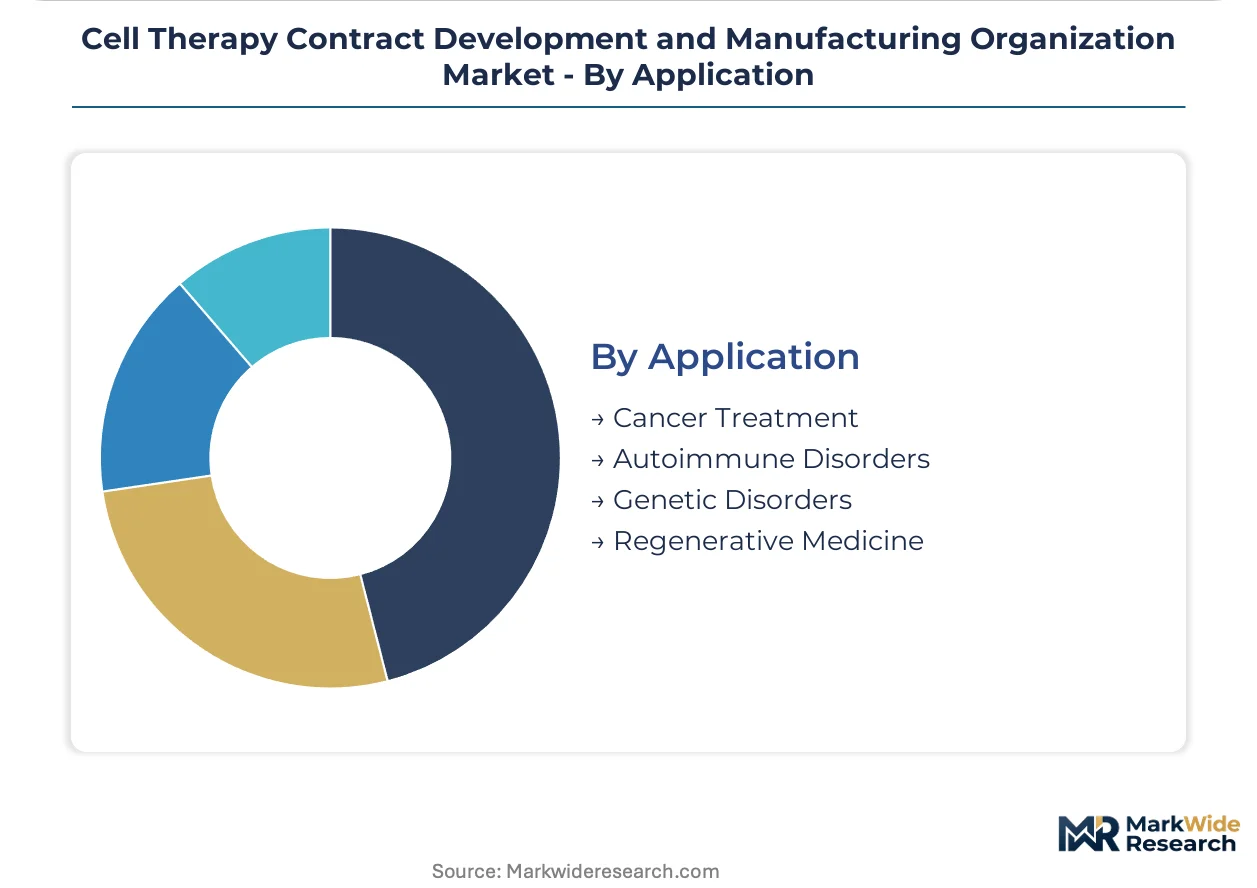
- Cancer Treatment:Hematologic malignancy indications dominate commercialized cell therapy volume, with CAR-T products requiring complex logistics coordination between apheresis centers and manufacturing sites. United States academic medical centers anchor demand.
- Autoimmune Disorders:Lupus and multiple sclerosis programs are expanding as allogeneic platforms reduce cost thresholds. Manufacturing scale economics improve across larger addressable patient populations.
- Genetic Disorders:Rare disease indications require specialized potency assays and extended follow-up protocols.
- Regenerative Medicine:Tissue repair applications face distinct reimbursement and regulatory pathways.
Cancer Treatment maintains volume leadership, with Autoimmune Disorders showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cell therapy CDMO industry traces its commercial roots to Swiss and German pharmaceutical manufacturing traditions, with Basel and Munich serving as early centers for biologics process development before CAR-T platforms demanded specialized living-therapeutic infrastructure.
United States
FDA regenerative medicine advanced therapy designations compress development timelines toward qualified CDMOs with prior successful inspections. The agency's gene therapy guidance and potency assay validation requirements shape facility investment priorities across Massachusetts and California clusters. Boston's academic medical centers anchor autologous CAR-T processing demand, while San Francisco Bay Area biotech sponsors drive plasmid-to-final-product outsourcing.
Germany
EMA's forthcoming GMP Annex 1 revisions tighten environmental monitoring for viral vector production, forcing HVAC retrofits across existing facilities. The country's national pharmaceutical regulator coordinates with Länder authorities on decentralized manufacturing pilot programs. Heidelberg and Munich host concentrated CDMO capacity serving both domestic sponsors and cross-border EMA-aligned contracts.
Switzerland
Swissmedic's alignment with FDA and EMA standards enables dual-certification facilities serving multinational sponsors. Basel's historical pharmaceutical manufacturing density supports integrated plasmid supply and viral vector capabilities. The canton's CDMOs capture commercial-scale autologous production contracts from European biotechnology companies lacking captive cleanroom infrastructure.
Japan
PMDA's regenerative medicine framework offers accelerated conditional approval pathways, attracting sponsor investment into local manufacturing partnerships. The regulator's gene therapy guidance harmonizes with ICH standards while maintaining distinct potency assay documentation requirements. Osaka and Tokyo clusters concentrate CDMO facility development for Asia-Pacific commercialization strategies.
United Kingdom
The Medicines and Healthcare products Regulatory Agency maintains GMP inspection readiness standards post-Brexit, with mutual recognition agreements pending for FDA-aligned facilities. London and Oxford academic medical centers pilot point-of-care cell processing for investigator-initiated trials. CDMOs with MHRA certification capture contracts from UK-based biotechnology companies advancing allogeneic platforms.
Cell Therapy Contract Development and Manufacturing Organization Market Competitive Landscape
The competitive structure tilts toward integrated platform providers capable of spanning plasmid supply through final fill-finish. Large pharmaceutical sponsors concentrate procurement among CDMOs with multi-continent facility networks and prior successful FDA-EMA dual inspections. Three archetypes dominate: end-to-end manufacturing platforms, viral vector specialists with captive plasmid capabilities, and regional pure-play cell therapy operators. Capacity expansion and strategic partnerships constitute the primary competitive moves, with sponsor procurement teams prioritizing third-party validated assay transfer capabilities.
Within the integrated platform tier, Lonza Group and Catalent exemplify archetype positioning through end-to-end manufacturing footprints spanning multiple continents. Thermo Fisher Scientific occupies a scale-driven position leveraging analytical instrumentation integration. These three anchors represent the procurement shortlist threshold for large pharmaceutical sponsors with regenerative medicine advanced therapy designations, where prior inspection history and dual-certification status determine contract eligibility.
| Leading Market Players |
|---|
| Lonza Group |
| Catalent |
| Thermo Fisher Scientific |
| FUJIFILM Diosynth Biotechnologies |
| WuXi Advanced Therapies |
| Charles River Laboratories |
| Recipharm |
| Patheon |
| Almac Group |
| Others |
Pricing and Supply Chain Analysis
FDA-EMA dual-certification premiums versus single-agency-qualified capacity bifurcate contract economics and geographic sourcing patterns across the cell therapy CDMO landscape. Pharmaceutical sponsors in the United States pay substantial premiums for facilities with prior successful FDA inspections, while European biotechnology companies accept longer batch release timelines to access lower-cost EMA-only certified capacity in Germany and Switzerland.
Pricing Analysis
Bundled plasmid-to-final-product contracts command substantial premiums over unbundled manufacturing-only arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and viral vector integration depth. Cost compression in standard-tier autologous manufacturing is intensifying because sponsor procurement teams are unbundling analytical services. Biotechnology companies with limited venture funding exhibit the highest price sensitivity, while large pharmaceutical sponsors with regenerative medicine advanced therapy designations prioritize inspection history over unit cost.
Supply Chain Analysis
Qualification gating for GMP-grade plasmid DNA concentrates upstream supply among United States, Belgium, and Netherlands facilities with validated master cell bank capabilities. The cell therapy supply chain draws from cryopreserved donor material, single-use bioreactor components, and viral vector production suites. Single-source vulnerability plagues plasmid DNA starting material, where limited qualified suppliers create batch release bottlenecks. Distribution runs through cryogenic logistics networks connecting apheresis centers to manufacturing sites and treatment facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell therapy CDMO market functions as a geographic-arbitrage play where facility investment in Japan's PMDA-aligned regulatory cluster captures lower construction costs and accelerated approval pathways compared to FDA-dominated United States capacity expansion.
For Market Incumbents: Lock in multi-year supply agreements with allogeneic platform sponsors before decentralized manufacturing technologies mature and displace centralized mega-site economics. Prioritize captive plasmid supply capabilities to defend against single-source vulnerabilities that trigger sponsor procurement penalties. Expand Grade A cleanroom capacity in Switzerland to capture dual-certification premiums from European biotechnology companies lacking captive infrastructure. For New Entrants and Emerging Players: Begin with autoimmune disorder manufacturing services, where allogeneic platform demand is expanding fastest and FDA inspection history requirements remain less stringent than oncology indications. Target United Kingdom academic medical centers piloting point-of-care cell processing, where MHRA certification barriers sit below FDA thresholds. Pursue modular cleanroom pod partnerships with hospital networks as a capital-light entry mechanism. For Investors and Strategic Acquirers: Asymmetric upside sits with regional pure-play cell therapy operators possessing Swissmedic or PMDA certification and established master cell bank capabilities. Long-term viability hinges on CDMOs capturing decentralized manufacturing platform contracts as point-of-care processing matures. Monitor EMA GMP Annex 1 revision implementation timelines as an inflection indicator for European facility retrofit requirements and stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Plasmid Supply Backward Integration | Captive GMP-grade starting material production eliminates single-source vulnerabilities and accelerates batch release timelines. |
| Decentralized Manufacturing Platform Development | Closed-system automation for hospital-adjacent processing reduces cryogenic logistics burdens and enables same-day vein-to-vein treatment. |
| Dual FDA-EMA Certification Investment | Swissmedic-aligned facilities capture multinational sponsor contracts requiring prior successful inspection history across both agencies. |
| Autoimmune Disorder Manufacturing Scale-Up | Allogeneic platform expansion into lupus and multiple sclerosis indications improves manufacturing scale economics across larger patient populations. |
| Japan PMDA Facility Establishment | Local manufacturing presence secures Asia-Pacific commercialization partnerships under accelerated conditional approval pathways. |
Research Methodology
Bottom-up biotechnology company procurement modeling reconciled against top-down CDMO capacity tracking forms the analytical core of this study. Primary interviews with cell therapy process development executives, regulatory affairs leads at sponsor companies, GMP facility quality directors, and hospital procurement managers combined with secondary validation from FDA filings, EMA inspection databases, ClinicalTrials.gov, and Swissmedic certification records. Cross-referencing sponsor manufacturing outsourcing announcements against facility expansion permits enables supply-side triangulation.
Historical trendline analysis of contract value and capacity utilization rates informs the projection framework across the analysis window. Segmentation dimensions include service type, technology platform, therapeutic application, and regional regulatory cluster. CAGRs derive from sponsor pipeline advancement rates and facility commissioning timelines. Forecast inputs incorporate regenerative medicine advanced therapy designation velocity and allogeneic platform clinical trial progression.
Several conditions sit outside the modeled scope, including unforeseen potency assay harmonization failures, decentralized manufacturing regulatory precedents, and cryogenic logistics infrastructure disruptions. Forecasts reflect documented assumptions regarding sponsor outsourcing propensity and inspection readiness timelines. A model refresh is warranted upon material change in FDA gene therapy guidance or EMA GMP Annex 1 adoption schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Inherited Orphan Blood Disorders Therapeutics Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market