
 Global High Performance Thermoplastics Market | 2026-2036
Global High Performance Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Performance Thermoplastics Market Intelligence
ISO 10993 biocompatibility certification is rotating the competitive set in medical-grade high performance thermoplastics, filtering out suppliers lacking validated clean-room extrusion capabilities. Victrex plc leverages its proprietary polyetheretherketone polymerization chain to sustain premium positioning across implantable device applications. Solvay S.A. anchors European supply through backward integration into specialty monomer production. Evonik Industries AG differentiates via high-temperature polyamide-imide formulations for semiconductor manufacturing equipment.
High performance thermoplastics are aromatic or semi-crystalline polymers with continuous use temperatures exceeding 150°C, glass transition points above 180°C, and tensile moduli ranging from 3 to 13 GPa, produced via nucleophilic substitution, polycondensation, or ring-opening polymerization for metal replacement in load-bearing and thermally stressed environments. Polyetheretherketone dominates value pools due to its bone-like modulus and sterilization resilience across spinal implant and dental abutment applications. Polyphenylene sulfide captures expanding share in electrical connectors and motor housings as OEMs prioritize halogen-free flame retardancy. Liquid crystal polymer competes in 5G telecommunications equipment where dielectric stability at millimeter-wave frequencies determines signal integrity.
FDA 21 CFR 177.2415, EU MDR, and REACH Annex XIV constrain material selection for medical and electronics applications, pushing compounders toward full substance traceability and restricted substance elimination. EPA TSCA Section 5 pre-manufacture notifications add compliance layers for novel monomer introductions in the United States. Stakeholders must monitor regulatory divergence between FDA device clearance pathways and EU MDR technical documentation requirements when allocating R&D across Atlantic supply chains.
Market Dynamics
REACH Annex XIV substance restrictions and EU MDR technical documentation requirements are forcing compounders to eliminate legacy plasticizers and flame retardants, compressing supplier margins while opening certification premiums for clean-room extrusion specialists.
Growth Catalysts
- EU Green Deal circularity mandates:Automotive OEMs in Germany and France now specify recyclable thermoplastic assemblies for battery housings and thermal management modules, displacing metal stampings.
- 5G millimeter-wave infrastructure rollout:Base station manufacturers prioritize liquid crystal polymer for antenna substrates due to dielectric stability at 28 GHz and above, creating dedicated demand pools in South Korea and Taiwan.
- FAA airworthiness certification pathways:Aerospace fabricators accelerate polyetheretherketone adoption for interior bracketry and cable management systems to meet smoke-toxicity standards without halogenated additives.
Market Restraints
- Fluoropolymer monomer supply concentration:Specialty monomer production clusters in China and Germany, exposing compounders to force majeure risk and volatile feedstock pricing.
- High-temperature polyamide-imide curing energy intensity:Batch polymerization requires sustained thermal input above 300°C, constraining capacity expansion in jurisdictions with carbon pricing mechanisms.
- Metal-to-plastic substitution ceiling in load-bearing structures:Continuous fiber-reinforced thermoplastics face stiffness limitations below 15 GPa tensile modulus, blocking penetration in primary aircraft wing spars and heavy-equipment frames.
Strategic Opportunities
- India PLI scheme for medical devices:Domestic manufacturers qualify for production-linked incentives by localizing clean-room compounding of implant-grade polyetheretherketone, reducing import dependence on European suppliers.
- Semiconductor capital equipment thermal barrier applications:Wafer processing chambers require polyimide and polyamide-imide components with plasma erosion resistance, opening specification work with Tokyo Electron and Applied Materials procurement teams.
- Direct-to-device-maker distribution platforms:Specialized thermoplastic distributors in the United States bypass traditional resin merchants to offer lot-traceable medical grades with validated sterilization documentation.
Industry Challenges
- ISO 10993-5 cytotoxicity testing timeline:Biocompatibility validation for new colorant packages extends qualification cycles by 18-24 months, freezing formulation innovation for spinal implant applications.
- Ring-opening polymerization reactor scale-up:Moving from pilot to commercial batch sizes for cyclic olefin thermoplastics demands precision temperature control within 2°C across 10,000-liter vessels, requiring specialized engineering talent scarce in North American labor markets.
- Legacy injection molding asset retrofit:Converting standard PET and nylon lines to process 400°C melt-temperature resins necessitates screw-and-barrel replacement, heater band upgrades, and mold temperature unit installation, complicating capacity reallocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Performance Thermoplastics Market |
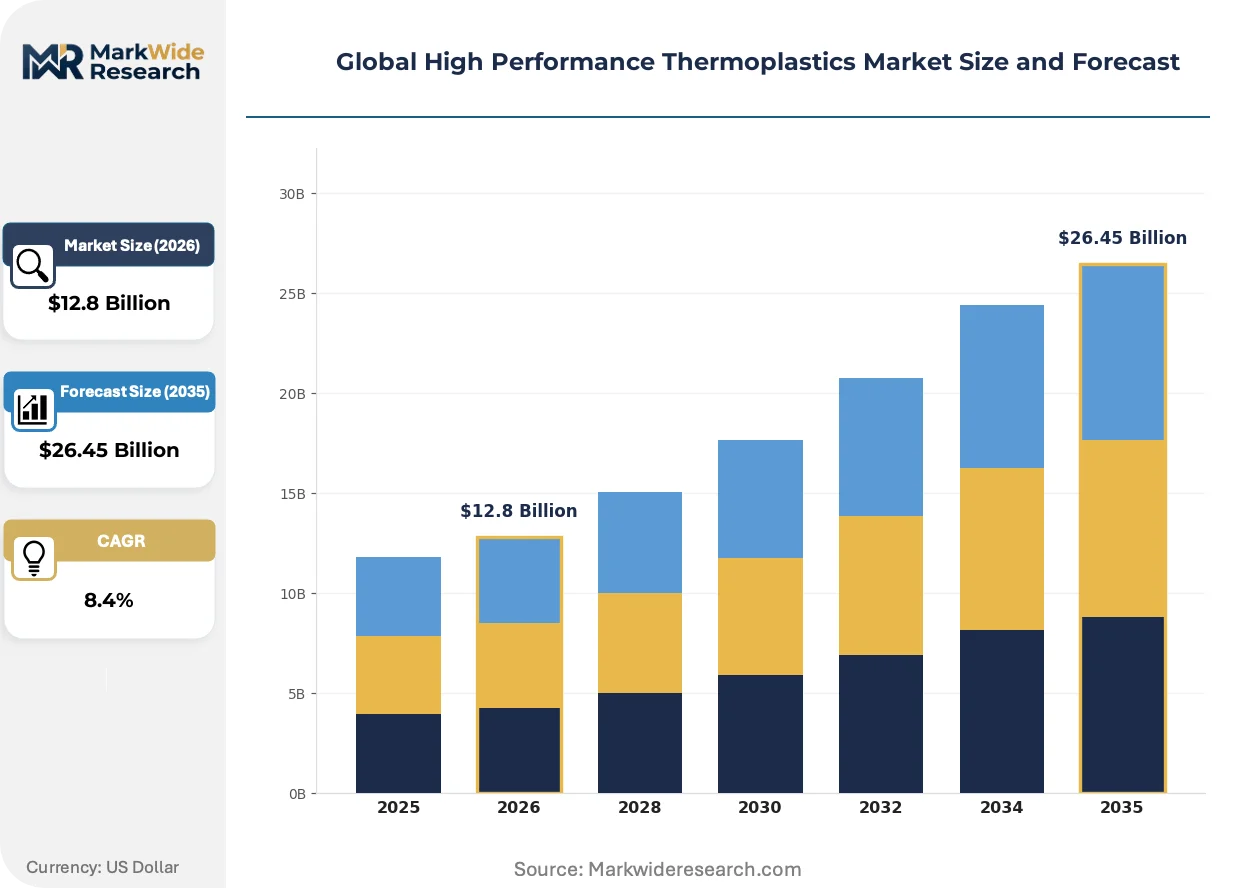
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyetheretherketone, Polyphenylene Sulfide, Polyetherimide, Polyamide-imide, Polyphenylene Oxide, Liquid Crystal Polymer Application: Electrical & Electronics, Aerospace Components, Industrial Machinery, Medical Devices, Consumer Goods, Telecommunications Equipment End User Industry: Automotive Suppliers, Aerospace Manufacturers, Electronic Device Makers, Medical Equipment Producers, Industrial Fabricators, Consumer Electronics Firms Form: Pellets, Powder, Film & Sheet, Rod & Tube, Granules, Fiber |
| Companies Covered | BASF SE, DuPont de Nemours, Inc., Celanese Corporation, Toray Industries, Inc., Mitsubishi Chemical Corporation, Solvay S.A., Evonik Industries AG, Victrex plc, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Performance Thermoplastics Market Strategic Shifts & Innovations
Multi-material hybrid processing and bio-based feedstock substitution are fragmenting traditional supply relationships while creating new specification tiers based on carbon intensity disclosure rather than mechanical performance alone.
Carbon fiber-reinforced thermoplastic composites are fragmenting the metal-dominated structural component market. Automotive seating suppliers in Stuttgart and Munich now specify continuous-fiber polyamide 66 for seat back frames, achieving 40% mass reduction versus steel stampings. This shift compresses the addressable market for traditional short-fiber compounds while expanding tooling and joining technology vendor ecosystems.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin blowing agent adoption in foam-core sandwich structures. Insulated panel manufacturers serving cold-chain logistics must reformulate polyurethane interlayers to maintain lambda values below 20 mW/mK without perfluorinated gases. German refrigeration OEMs lead compliance, pressuring compounders to validate alternative nucleating agents for polyphenylene sulfide foam cores.
Specification authority is migrating from resin merchants to device-maker procurement teams with dedicated polymer scientists. Medtronic and Stryker now maintain internal compounding guidelines that override supplier datasheets for implantable polyetheretherketone grades. This concentration of technical decision-making in Minneapolis and Dublin reduces price competition while elevating audit requirements for clean-room extrusion facilities.
Global High Performance Thermoplastics Market Segmentation
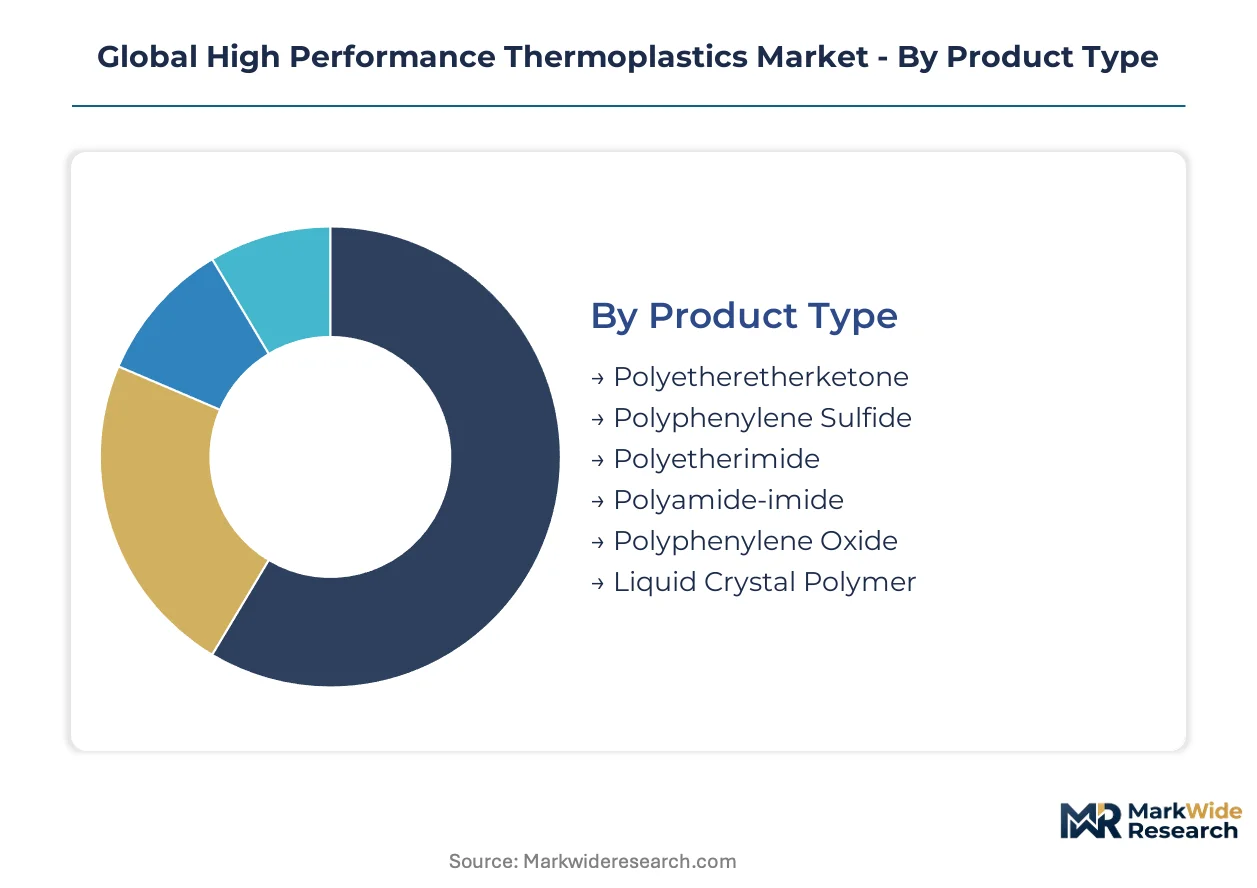
High performance thermoplastics command specification premiums through differentiated thermal and mechanical portfolios. Segmentation reveals where substitution economics favor aromatic polymers over metal assemblies and where regulatory certification creates captive demand pools.
Product Type:
Polyetheretherketone faces intensifying substitution pressure from lower-cost high-temperature polyamides in automotive thermal management, while fluoropolymer alternatives threaten polyphenylene sulfide in electrical housing applications.
- Polyetheretherketone:Semi-crystalline aromatic polymer with continuous use temperature of 260°C and bone-matching elastic modulus. Spinal implant manufacturers in Germany and Switzerland specify this grade for load-bearing orthopedic devices requiring gamma sterilization resilience.
- Polyphenylene Sulfide:Partially crystalline polymer with inherent flame retardancy and chemical resistance to automotive fluids. Motor housing producers in Stuttgart specify halogen-free grades to meet EU ELV directive requirements without secondary additives.
- Polyetherimide:Amorphous thermoplastic with amber transparency and dielectric stability. Medical sterilization tray fabricators specify this grade for repeated autoclave cycling.
- Polyamide-imide:Highest temperature capability among melt-processable thermoplastics. Semiconductor capital equipment manufacturers specify this for wafer handling components exposed to plasma environments.
- Polyphenylene Oxide:Blended primarily with polystyrene for dimensional stability in electrical enclosures. Appliance connector producers favor modified grades for hydrolysis resistance.
- Liquid Crystal Polymer:Anisotropic melt behavior delivering exceptional dimensional precision. 5G antenna substrate manufacturers in Taiwan specify this for millimeter-wave signal integrity at 28 GHz frequencies.
Polyetheretherketone retains volume leadership; liquid crystal polymer holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-grade medical and aerospace applications from price-sensitive consumer segments where engineering thermoplastics compete.
- Electrical & Electronics:Connectors, circuit breakers, and motor housings requiring UL 94 V-0 flame ratings. E-mobility battery module producers specify polyphenylene sulfide for busbar insulation.
- Aerospace Components:Interior bracketry, cable management, and ventilation ducting governed by FAA smoke-toxicity standards. Tier 1 fabricators specify polyetheretherketone to eliminate halogenated additives.
- Industrial Machinery:Seals, bearings, and pump components exposed to corrosive process fluids. Chemical processors specify polyamide-imide for compressor valve plates.
- Medical Devices:Implantable spinal cages, dental abutments, and surgical instruments requiring ISO 10993 biocompatibility. Clean-room extrusion capabilities filter supplier participation.
- Consumer Goods:Cookware handles and appliance housings where heat resistance justifies premium pricing over standard engineering plastics.
- Telecommunications Equipment:Antenna substrates and high-frequency connectors where dielectric constant stability determines signal performance.
Medical devices command the widest specification premiums; telecommunications equipment is gaining share fastest.
End User Industry:
Customer type concentration creates divergent procurement patterns, with automotive suppliers driving volume through platform standardization while medical equipment producers enforce lot-traceable qualification protocols.
- Automotive Suppliers:Tier 1 and Tier 2 component manufacturers specifying thermoplastics for thermal management modules and electrical architecture. Battery housing producers in Germany displace aluminum stampings with recyclable assemblies.
- Aerospace Manufacturers:OEMs and subcontractors governed by AS9100 quality systems and FAA production certification. Interior systems integrators specify polyetheretherketone for weight reduction without smoke toxicity compromises.
- Electronic Device Makers:Smartphone and laptop manufacturers sourcing miniaturized connectors and antenna components. 5G infrastructure OEMs drive liquid crystal polymer specifications.
- Medical Equipment Producers:Implantable device manufacturers with internal compounding guidelines overriding supplier datasheets. Stryker and Medtronic procurement teams enforce clean-room audit requirements.
- Industrial Fabricators:Pump, valve, and processing equipment manufacturers specifying corrosion-resistant components for chemical and oilfield service.
- Consumer Electronics Firms:Appliance and personal electronics manufacturers balancing heat resistance against cost targets in mature product categories.
Automotive suppliers anchor volume demand; medical equipment producers sustain the highest margin tiers.
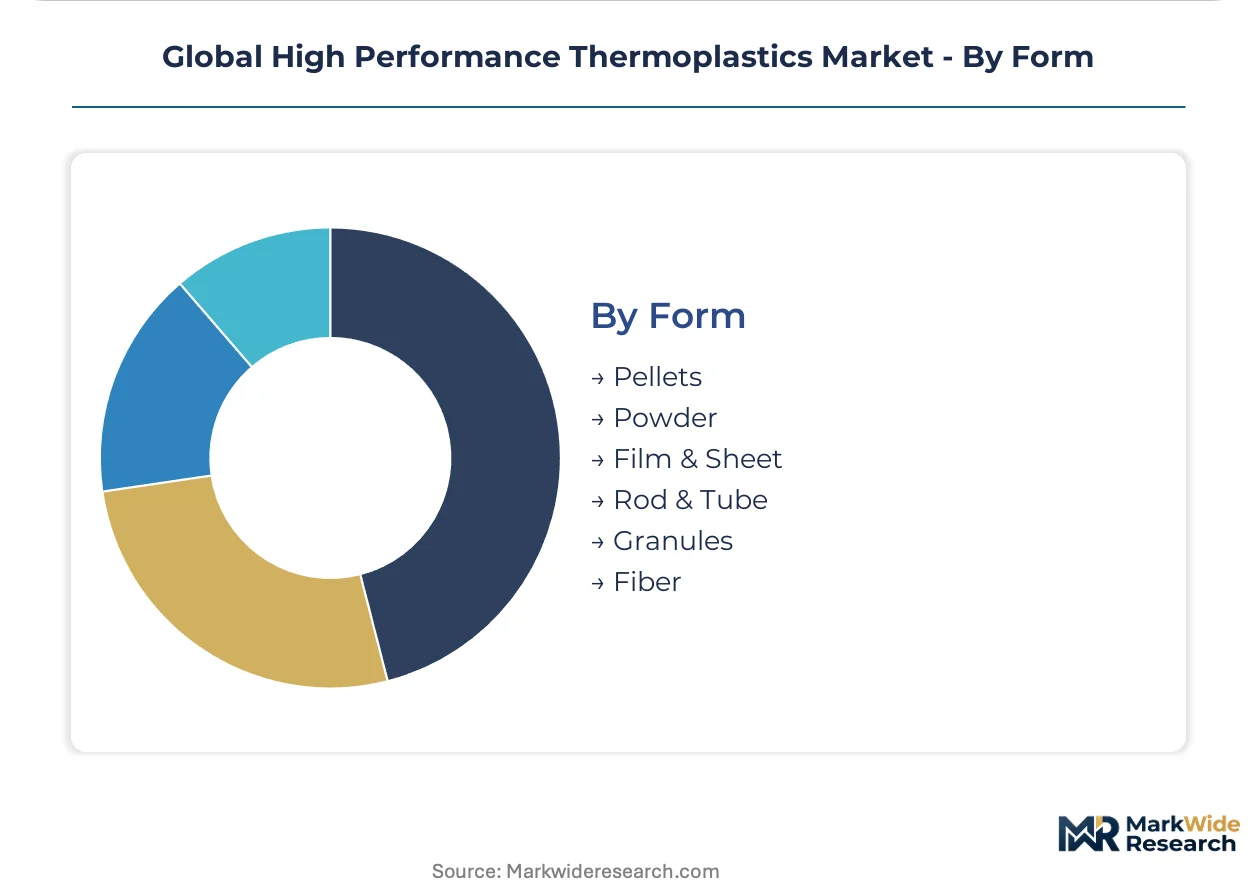
Form:
Supply concentration in pellet and powder formats reflects injection molding and compression molding dominance, while film and fiber forms serve specialized coating and composite reinforcement applications.
- Pellets:Standard extrusion and injection molding feedstock. Automotive and electrical component producers specify color-matched lots with full material traceability.
- Powder:Compression molding and coating applications. Medical implant manufacturers specify fine particle sizes for selective laser sintering of patient-specific devices.
- Film & Sheet:Thin-gauge stock for diaphragms, insulators, and flexible circuits. Semiconductor equipment manufacturers specify polyimide films for thermal barrier applications.
- Rod & Tube:Machining stock for prototype and low-volume production. Aerospace machine shops specify polyetheretherketone rod for bracketry requiring tight tolerances.
- Granules:Alternative pellet form for specific feeding systems. Compounders serving Asian processing markets favor this format.
- Fiber:Continuous and chopped reinforcement for thermoplastic composites. Automotive seating suppliers specify continuous-fiber polyamide for seat back frames.
Pellets retain volume leadership; powder holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal circularity mandates and production-linked incentive schemes are redirecting capital toward localized compounding capacity across Germany, the United States, India, China, and Japan. National regulators are tightening substance traceability requirements while automotive and medical OEMs qualify alternative suppliers.
Germany
Automotive battery housing producers specify recyclable thermoplastic assemblies to meet EU ELV directive requirements. REACH Annex XIV substance restrictions force compounders to eliminate legacy plasticizers. Stuttgart and Munich clusters concentrate specialized injection molding capabilities for seat back frames and thermal management modules.
United States
FAA airworthiness certification pathways accelerate polyetheretherketone adoption for interior bracketry and cable management systems. EPA TSCA Section 5 pre-manufacture notifications add compliance layers for novel monomer introductions. Minneapolis hosts procurement teams at major medical device makers enforcing clean-room audit requirements.
India
Domestic manufacturers qualify for PLI scheme production-linked incentives by localizing clean-room compounding of implant-grade materials. CDSCO medical device regulations constrain import dependence on European suppliers. Gujarat and Maharashtra industrial corridors attract specialty polymer investments.
China
Specialty monomer production clusters expose compounders to force majeure risk and volatile feedstock pricing. MIIT standards govern 5G telecommunications equipment specifications. Yangtze River Delta fabricators supply liquid crystal polymer for antenna substrates at millimeter-wave frequencies.
Japan
Semiconductor capital equipment manufacturers specify polyimide and polyamide-imide components with plasma erosion resistance. METI industrial policy supports domestic materials innovation. Tokyo Electron and Applied Materials procurement teams drive specification work for wafer processing chambers.
Global High Performance Thermoplastics Market Key Industry Players
Player mix skews toward diversified chemical conglomerates with captive monomer supply and specialized polymer pure-plays with medical-grade certification. The vendor base concentrates around three strategic archetypes: backward-integrated resin producers controlling specialty monomer production, clean-room extrusion specialists holding ISO 10993 validation premiums, and compounders serving automotive platform standardization. Dominant competitive moves include capacity expansion in jurisdictions with carbon pricing exemptions and technology licensing for high-temperature polyamide-imide formulations.
Within the backward-integrated tier, Solvay S.A. and BASF SE represent European resin producers with captive specialty monomer capabilities. Victrex plc exemplifies the pure-play polymer specialist archetype with proprietary polyetheretherketone polymerization chains. Evonik Industries AG occupies a position among German chemical conglomerates differentiating via high-temperature formulations.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours, Inc. |
| Celanese Corporation |
| Toray Industries, Inc. |
| Mitsubishi Chemical Corporation |
| Solvay S.A. |
| Evonik Industries AG |
| Victrex plc |
| SABIC |
| Others |
Cost & Logistics Intelligence
Specialized reactor scale economies in Germany and China concentrate polyetheretherketone monomer production among three integrated suppliers, creating asymmetric pricing power that elevates floor prices for non-integrated compounders while compressing margins for distributors lacking clean-room certification assets.
Pricing Analysis
Certification level creates the primary spread across ISO 10993 medical-grade, FAA airworthiness-qualified, and standard industrial tiers. Three-tier pricing structure across premium implant-grade, qualified aerospace, and economy industrial levels reflects sterilization validation costs and lot-traceability investments. Cost compression in automotive thermal management grades is intensifying because high-temperature polyamide substitution erodes polyetheretherketone volume premiums. Electronic device makers exhibit highest price sensitivity; spinal implant manufacturers show least.
Supply Chain Analysis
Specialty fluoropolymer monomer production clusters in China and Germany expose compounders to force majeure vulnerability and feedstock volatility. Cyclic ether and aromatic dihalide precursors draw from petrochemical complexes in the US Gulf Coast and Rotterdam-Antwerp corridor. Single-source vulnerability concentrates in pharmaceutical-grade colorant packages. Distribution runs through authorized distributors with validated sterilization documentation for medical segments and direct mill relationships for automotive platform suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal circularity mandates and FAA smoke-toxicity certification pathways are accelerating metal-to-thermoplastic substitution across battery housings and aerospace interiors, creating a high-growth disruption window for qualified suppliers.
For Market Incumbents: Fortify backward integration into specialty monomer production to offset feedstock volatility from Chinese and German supply concentration. Expand clean-room extrusion capacity in jurisdictions with carbon pricing exemptions before REACH Annex XIV restrictions tighten. Defensive consolidation around ISO 10993 validation assets blocks emerging entrants from spinal implant specifications. For New Entrants and Emerging Players: CDSCO fast-track pathways for implant-grade polyetheretherketone production under India's PLI scheme offer the most penetrable entry point. Target Gujarat and Maharashtra industrial corridors where domestic compounding incentives reduce European import dependence. Go-to-market angle emphasizes lot-traceable medical grades with validated gamma sterilization documentation for device-maker procurement teams. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clean-room extrusion specialists with captive ISO 10993 validation over commodity compounders facing high-temperature polyamide substitution pressure. Five-to-ten year viability hinges on regulatory certification moats rather than scale economies alone. Signal to monitor: FDA 21 CFR 177.2415 pathway expansions for novel aromatic polymer formulations that could fragment polyetheretherketone dominance in load-bearing orthopedic applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomer Production | Solvay and BASF anchor European supply security against Chinese force majeure exposure. |
| Clean-Room Extrusion Capacity Expansion | Victrex sustains medical-grade premiums through validated implantable device supply chains. |
| ISO 10993 Biocompatibility Certification Investment | Evonik differentiates polyamide-imide formulations for semiconductor plasma erosion resistance. |
| Long-Term Supply Agreement with Automotive OEMs | German battery housing producers lock in recyclable thermoplastic assemblies for EU ELV compliance. |
| Joint Venture for 5G Antenna Substrate Development | Taiwanese fabricators secure liquid crystal polymer dielectric stability at millimeter-wave frequencies. |
Research Approach
A spread of perspectives from polymerization plant managers, automotive Tier 1 procurement leads, medical device GPO contracts managers, and semiconductor equipment technical directors converged on the working assumptions. Primary interviews combined with secondary validation from customs/trade data, SEC 10-K filings, Cefic industry reports, and FDA 510(k) clearance databases. Bottom-up resin volume estimates and top-down end-use demand triangulation anchored the analytical framework.
Segmentation dimensions modeled span product type, application, end-user industry, and form factor across the projection horizon. CAGRs derived from regression analysis against automotive production forecasts, aerospace delivery schedules, and medical device approval trajectories. Industry-specific inputs included REACH Annex XIV substance restriction timelines and FAA airworthiness certification queue depths.
Decision-makers should treat outputs as directional under sustained EU Green Deal implementation and stable specialty monomer supply; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as CDSCO regulatory enforcement and India PLI scheme disbursement rhythms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Hexagonal Boron Nitride (HBN) Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Carbon Prepreg Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Global Core Materials Market
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Global Aerogel Insulation Market