
 Borophene Market | 2026-2036
Borophene Market Size, Share, and Industry Trends Forecast 2026-2036
Borophene Market Analysis
Buyer concentration across the electronics sector is rebalancing as original equipment manufacturers diversify supplier rosters beyond traditional graphene vendors. Graphenea S.A. leverages its European fabrication infrastructure to sustain premium borophene wafer output. Nanjing XFNANO Materials Tech Co., Ltd. anchors Asia-Pacific supply channels through specialized nanostructure catalogs. US Research Nanomaterials, Inc. competes on domestic fulfillment speed for research-grade quantities.
Borophene denotes a monolayer allotrope of boron atoms arranged in a buckled honeycomb lattice with metallic character and theoretical carrier mobility exceeding conventional 2D materials, synthesized primarily via molecular beam epitaxy on silver substrates or chemical vapor deposition for scalable transfer. Thin films command current volume leadership due to immediate compatibility with existing semiconductor lithography, while nanostructures represent the fastest-growing product type as quantum dot architectures mature. Energy storage applications concentrate margin pools where borophene's theoretical capacity for lithium-ion intercalation attracts battery developers, though electronics maintains absolute revenue scale through sensor and interconnect procurement.
The EPA governs nanomaterial discharge thresholds under TSCA Section 5 premanufacture notification rules, compelling domestic producers to document environmental fate before commercial scale-up. ISO/TS 80004-13 nanotechnology terminology standards shape customer qualification protocols for cross-border procurement. REACH registration requirements in Europe add compliance cost layers for thin film exporters. Stakeholders must monitor how FDA device classification evolves for borophene-enabled biosensors before committing to dedicated cleanroom capacity.
Market Dynamics
The borophene market pivots on federal nanotechnology funding flows that prioritize domestic 2D material supply chains over import-dependent sourcing, compressing procurement timelines for electronics manufacturers seeking qualified domestic vendors.
Growth Catalysts
- US Federal Nanotechnology Initiatives:Direct funding channels accelerate domestic molecular beam epitaxy capacity expansion. Research institutions convert grants into pilot production lines.
- Chemical Vapor Deposition Advances:Scalable transfer techniques reduce substrate preparation costs. Semiconductor fabs adopt modified CVD reactors for borophene thin film integration.
- Electronics Sector Procurement:Next-generation interconnect and sensor architectures specify borophene for carrier mobility advantages. OEM qualification programs now include borophene wafer vendors.
Market Restraints
- Silver Substrate Cost Volatility:Molecular beam epitaxy requires atomically flat silver surfaces. Precious metal price swings compress synthesis margins unpredictably.
- EPA TSCA Section 5 Friction:Premanufacture notification rules mandate extensive environmental fate documentation. Scale-up timelines extend 18-24 months for domestic producers.
- Graphene Incumbency:Established graphene supply chains offer immediate volume and qualified specifications. Switching costs deter risk-averse procurement teams.
Strategic Opportunities
- Quantum Dot Architecture Maturation:Borophene nanostructures enable precise exciton confinement. Photonics developers in Germany and Japan prototype quantum emitters.
- India PLI Scheme Alignment:Domestic electronics manufacturing incentives create qualified demand for 2D material suppliers. Local sourcing mandates favor early entrants.
- Energy Storage Convergence:Lithium-ion intercalation capacity attracts battery developers. Joint development agreements with cell manufacturers accelerate application-specific formulations.
Industry Challenges
- MBE Technician Scarcity:Molecular beam epitaxy operation requires ultra-high vacuum expertise. Workforce pipelines from physics and materials science departments remain narrow.
- ISO/TS 80004-13 Qualification Timelines:Cross-border procurement protocols demand extensive terminology standard compliance. Certification cycles delay revenue recognition for thin film exporters.
- Cleanroom Capital Intensity:Contamination-sensitive synthesis requires Class 1000 or better facilities. Depreciation schedules strain emerging producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Borophene Market |
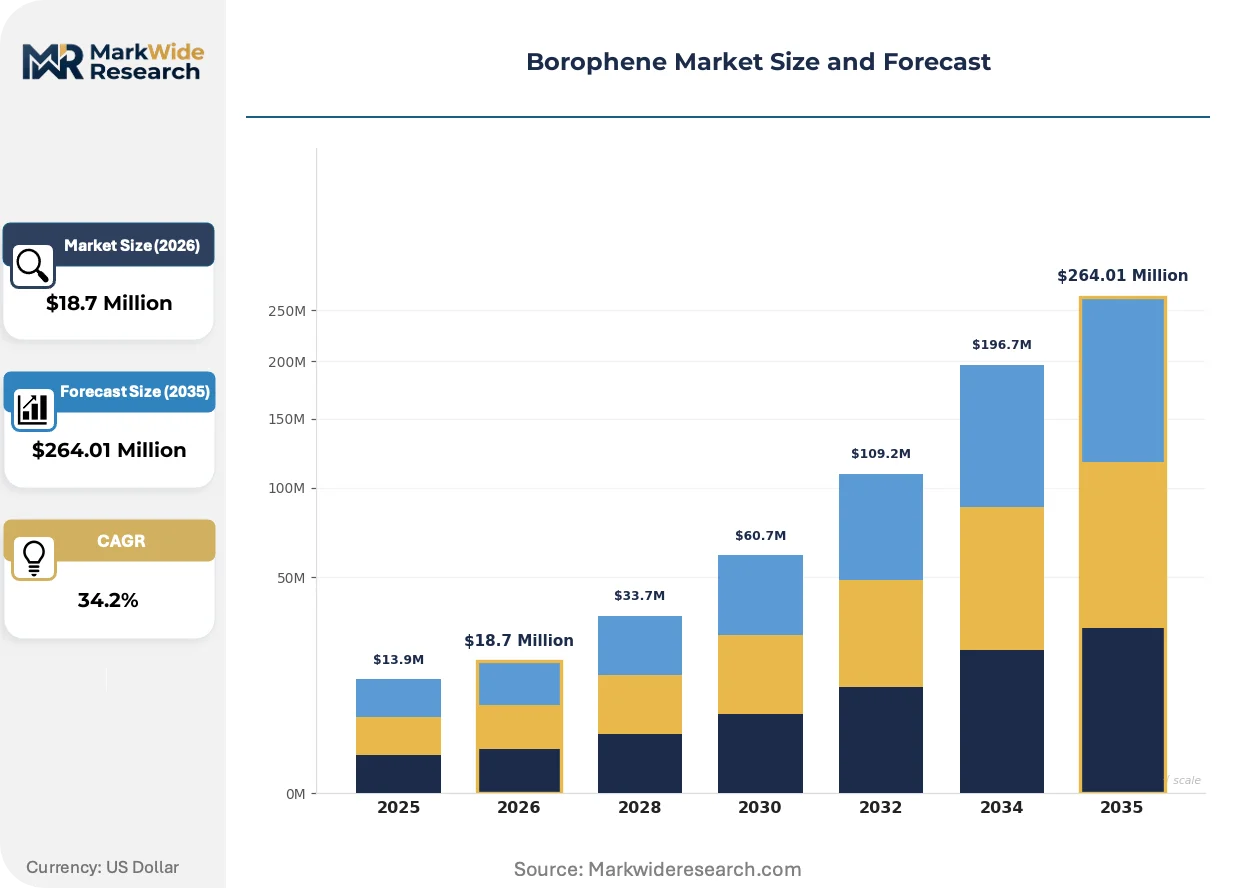
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $264.01 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Films, Nanostructures, Membranes, Composite Materials Application: Electronics, Energy Storage, Sensors, Coatings End User: Consumer Electronics, Aerospace, Automotive, Research Institutions Technology: CVD, Laser Ablation, Exfoliation, Chemical Vapor Deposition |
| Companies Covered | Angstron Materials, Inc., Nanochemazone, Nanjing XFNANO Materials Tech Co., Ltd., Graphenea S.A., Nano Pro Ceramic, US Research Nanomaterials, Inc., SUNUM, Advanced Graphene Products GmbH, ACS Material, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Borophene Market Emerging Trajectories
Process innovation and regulatory alignment are compressing development cycles while reshaping how buyers qualify and procure borophene materials across electronics and energy storage verticals.
Plasma-enhanced chemical vapor deposition is integrating into semiconductor foundry workflows as a drop-in modification to existing graphene reactor infrastructure. Memory and logic device manufacturers in Taiwan and South Korea pilot borophene interconnect layers. This integration is compressing the traditional 36-month new material qualification window toward 18-month cycles.
REACH registration requirements in Europe are forcing exporters to pre-document substance volumes and exposure scenarios before commercial shipments. ECHA compliance costs favor larger producers with dedicated regulatory affairs functions. Battery-grade thin film suppliers are responding by segregating EU-bound production lines to isolate registration liabilities.
Buyer qualification protocols now weight ISO nanotechnology terminology adherence above historical supplier relationships. Distributor networks in the United States are consolidating around vendors with pre-certified documentation packages. This behavioral shift concentrates procurement influence with domestic fulfillment specialists who maintain EPA premanufacture notification clearances.
Borophene Market Segmentation
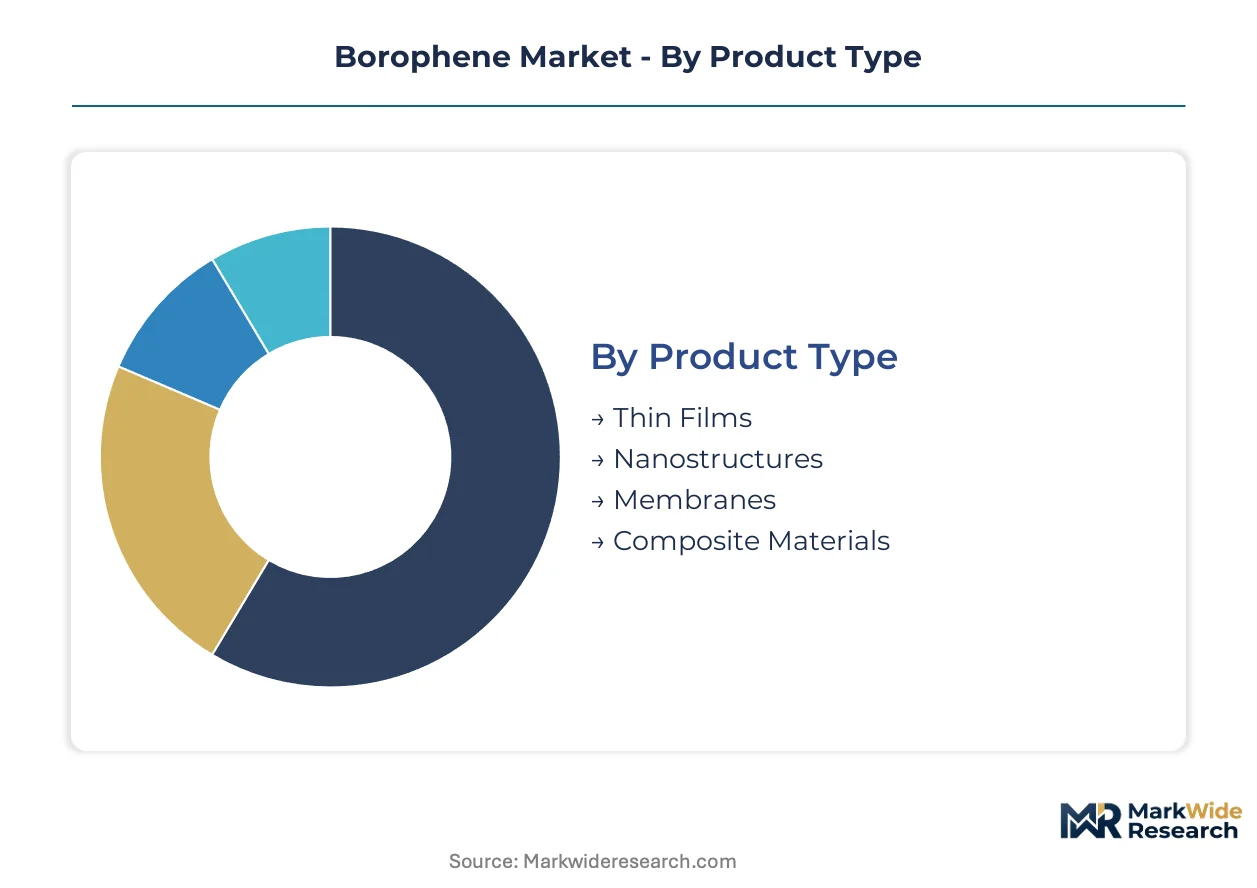
Borophene's commercial trajectory diverges sharply across product formats and synthesis routes. Electronics manufacturers prioritize specifications that align with existing semiconductor infrastructure, while emerging applications demand customized morphologies.
Product Type:
Technical specifications determine integration feasibility across semiconductor lithography, battery electrode coating, and membrane separation systems.
- Thin Films:Monolayer borophene sheets synthesized via molecular beam epitaxy on silver substrates deliver metallic conductivity with theoretical carrier mobility exceeding graphene alternatives. Semiconductor fabs in Taiwan and South Korea specify these for interconnect layers in next-generation logic devices. Compatibility with existing 300mm wafer processing drives procurement concentration among memory manufacturers.
- Nanostructures:Quantum dots and nanoribbons enable exciton confinement for photonic applications. German and Japanese research consortia prototype quantum emitters using these architectures. Battery developers explore nanostructured borophene for lithium-ion intercalation electrodes where surface area advantages outweigh thin film conductivity.
- Membranes:Porous borophene sheets suit gas separation and water filtration applications.
- Composite Materials:Polymer-borophene hybrids target structural reinforcement and thermal management.
Mature deployment sits with Thin Films. Newer deployment is concentrated in Nanostructures.
Application:
End-use requirements reshape synthesis priorities and qualification timelines across the value chain.
- Electronics:Interconnects, sensors, and transparent electrodes consume the majority of commercial volumes. OEM qualification programs now include borophene wafer vendors alongside traditional graphene suppliers. Carrier mobility specifications from Taiwan Semiconductor Manufacturing compress development cycles for domestic producers.
- Energy Storage:Lithium-ion battery anodes and supercapacitor electrodes represent the steepest expansion trajectory. Joint development agreements with cell manufacturers accelerate application-specific formulations. Theoretical capacity metrics attract venture funding despite manufacturing scale constraints.
- Sensors:Biosensing and environmental detection applications leverage borophene's surface reactivity.
- Coatings:Corrosion-resistant and anti-fouling surface treatments target industrial equipment.
Revenue scale favors Electronics. Technology maturation is accelerating fastest in Energy Storage.
End User:
Procurement sophistication varies dramatically across customer categories, from research-scale purchases to integrated supply agreements.
- Consumer Electronics:Smartphone and wearable manufacturers drive thin film demand through sensor miniaturization requirements. Apple and Samsung supplier qualification protocols mandate ISO/TS 80004-13 documentation. Volume commitments remain constrained by graphene incumbent pricing.
- Research Institutions:Universities and national laboratories anchor early-stage demand with small-batch, high-specification procurement. US Department of Energy grants convert directly into pilot production contracts. Federal nanotechnology funding flows prioritize domestic molecular beam epitaxy capacity.
- Aerospace:Lightweight composite applications target satellite and unmanned vehicle platforms.
- Automotive:Battery integration and thermal management systems attract tier-one supplier interest.
Procurement volume concentrates with Consumer Electronics. Technical specification leadership resides with Research Institutions.
Technology:
Synthesis route selection determines capital requirements, scalability, and contamination sensitivity.
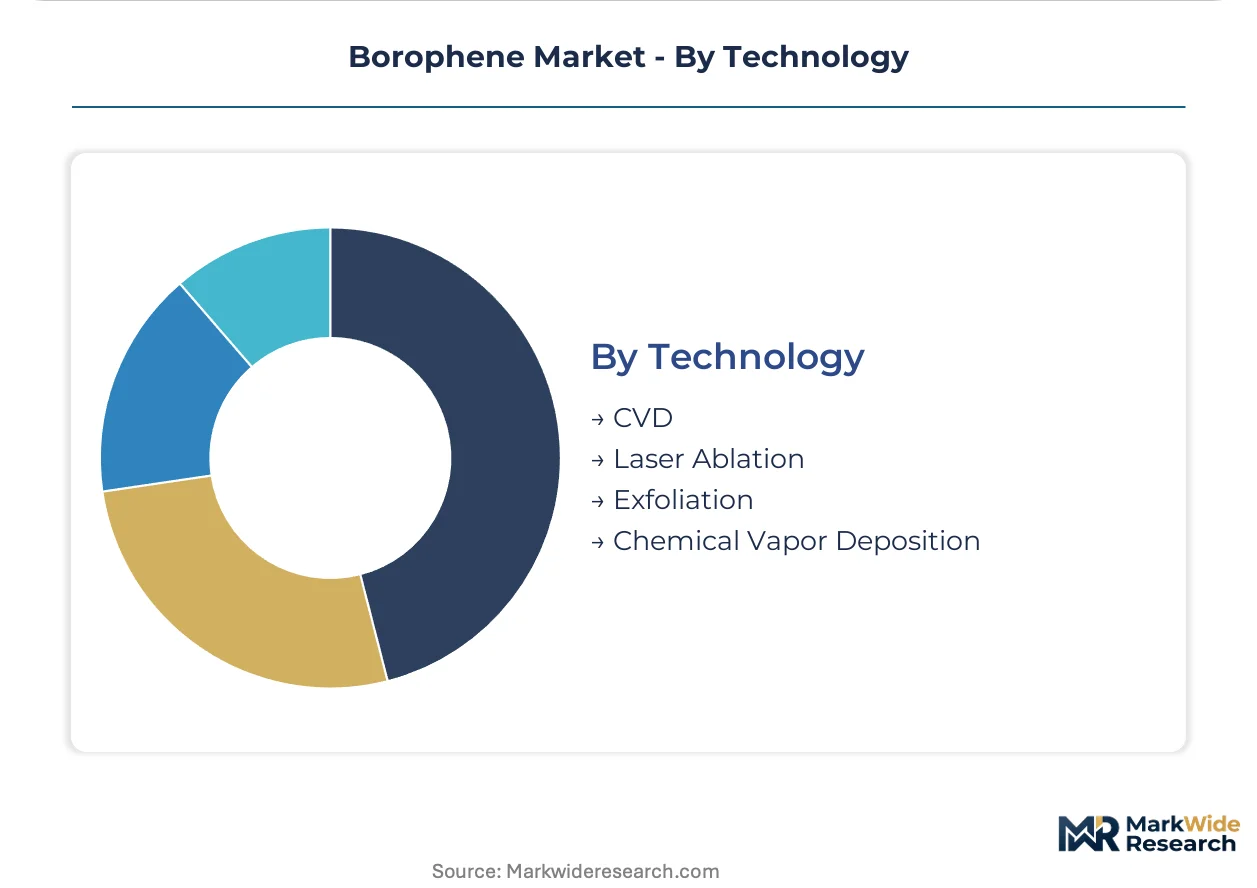
- Chemical Vapor Deposition:Modified reactor designs enable transfer from growth substrates to device wafers. Semiconductor foundries adopt this as a drop-in modification to existing graphene infrastructure. Scalable transfer techniques reduce substrate preparation costs and compress qualification timelines toward 18-month cycles.
- Molecular Beam Epitaxy:Ultra-high vacuum deposition on silver substrates yields atomically precise monolayers. Workforce scarcity in MBE operation limits capacity expansion despite federal funding availability. Precious metal price volatility compresses synthesis margins unpredictably.
- Laser Ablation:Pulsed laser techniques produce nanostructured borophene for research applications.
- Exfoliation:Mechanical and liquid-phase methods target low-cost, lower-quality material for composite fillers.
Production scale favors Chemical Vapor Deposition. Process control precision peaks with Molecular Beam Epitaxy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics manufacturers cluster procurement decisions around three primary jurisdictions where federal nanotechnology funding intersects with established semiconductor infrastructure. The United States, Germany, and South Korea concentrate qualified demand for borophene thin films through distinct regulatory and industrial pathways.
United States
Federal nanotechnology initiatives channel Department of Energy grants toward domestic molecular beam epitaxy capacity expansion. EPA TSCA Section 5 premanufacture notification rules compel producers to document environmental fate before commercial scale-up, extending timelines 18-24 months. Research Triangle Park in North Carolina anchors pilot production lines converting federal funding into qualified wafer output.
Germany
Photonics developers in Munich and Stuttgart prototype quantum emitters using borophene nanostructures for exciton confinement applications. ECHA REACH registration requirements add compliance cost layers for thin film exporters targeting EU markets. The Dresden semiconductor cluster integrates modified chemical vapor deposition reactors into existing 300mm foundry workflows.
South Korea
Memory and logic device manufacturers specify borophene interconnect layers for next-generation fabrication nodes. The national semiconductor strategy prioritizes 2D material supply chain security alongside advanced packaging investments. Samsung and SK Hynix supplier qualification programs in Gyeonggi Province compress development cycles for domestic producers.
Japan
METI funding supports joint research consortia exploring borophene quantum dot architectures for photonic applications. JIS nanotechnology terminology standards shape buyer qualification protocols for cross-border procurement. The Tsukuba research corridor maintains specialized molecular beam epitaxy facilities for atomically precise monolayer synthesis.
China
Domestic electronics manufacturing scale creates volume demand for chemical vapor deposition-derived thin films. MIIT industrial standards for 2D materials guide procurement specifications for state-backed semiconductor projects. The Yangtze River Delta cluster houses modified reactor infrastructure adapted from existing graphene production lines.
Borophene Market Vendor Landscape
United States producers anchor one tier through federal funding access and domestic fulfillment speed; European specialists hold premium positioning through established fabrication infrastructure. The vendor base organizes around three strategic archetypes: research-grade suppliers serving institutional procurement, semiconductor-qualified fabricators targeting OEM qualification programs, and diversified nanomaterial houses leveraging graphene production lines. Competitive moves concentrate on capacity expansion through pilot line conversion and strategic partnerships with foundry operators seeking qualified 2D material sources.
Within the research-grade tier, US Research Nanomaterials, Inc. exemplifies domestic fulfillment specialists maintaining EPA premanufacture notification clearances. Graphenea S.A. occupies a position among European fabricators with dedicated regulatory affairs functions for REACH compliance. Nanjing XFNANO Materials Tech Co., Ltd. represents Asia-Pacific supply channel anchors through specialized nanostructure catalogs serving regional electronics procurement.
| Leading Market Players |
|---|
| Angstron Materials, Inc. |
| Nanochemazone |
| Nanjing XFNANO Materials Tech Co., Ltd. |
| Graphenea S.A. |
| Nano Pro Ceramic |
| US Research Nanomaterials, Inc. |
| SUNUM |
| Advanced Graphene Products GmbH |
| ACS Material, LLC |
| Others |
Supply Flow & Price Mechanics
Federally-funded pilot production lines in the United States anchor supply discipline through constrained molecular beam epitaxy capacity, translating silver substrate volatility into tiered wafer pricing that separates research-grade from semiconductor-qualified volumes.
Pricing Analysis
Volume leadership in thin films trades at compressed margins against premium pricing for nanostructures serving quantum dot developers. Three-tier pricing structure across semiconductor-qualified, research-grade, and composite filler tiers reflects ISO/TS 80004-13 certification status and carrier mobility specifications. Cost compression in research-grade material is intensifying because graphene incumbents discount legacy 2D material contracts to defend socket positions. Battery developers exhibit highest price sensitivity due to lithium-ion intercalation performance uncertainty, while Taiwan Semiconductor Manufacturing qualification programs tolerate premium wafer costs for interconnect layer trials.
Supply Chain Analysis
Freight costs for silver substrate ingots from refiners in Germany, Mexico, and Canada compound synthesis margin pressure for domestic MBE operators. Raw material draws from precious metal exchanges, ultra-high vacuum chamber components, and lithography-grade transfer substrates. Single-source vulnerability concentrates in atomically flat silver surface preparation where qualified vendors number fewer than five globally. Distribution runs through specialized nanomaterial distributors maintaining EPA TSCA Section 5 premanufacture notification clearances for domestic fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Borophene supply remains bottlenecked by molecular beam epitaxy technician scarcity, propping pricing power for qualified domestic producers despite chemical vapor deposition scale-up efforts.
For Market Incumbents: Deepen backward integration into silver substrate refining partnerships to isolate precious metal price volatility from wafer margins. Expand pilot line capacity in Research Triangle Park before competitor qualification programs mature. Graphene vendor discounting and EPA notification delays threaten incumbent pricing power; early certification investment locks OEM socket positions. For New Entrants and Emerging Players: Begin with India PLI scheme-aligned supply agreements targeting domestic electronics manufacturing incentives. Research institutions and battery joint development agreements represent the most penetrable demand tiers. Go-to-market leverage rests on plasma-enhanced CVD reactor deployment as drop-in graphene infrastructure modifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor CVD-specialized mid-caps in South Korea and Taiwan facing temporary qualification timeline extensions. Long-term viability hinges on semiconductor fab integration rather than research-grade volume scale. Watch Samsung and SK Hynix supplier program announcements as inflection signals for domestic producer revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| MBE Pilot Line Conversion | Federal DOE grants accelerate domestic atomically precise monolayer capacity beyond import dependence. |
| Plasma-Enhanced CVD Integration | Taiwan Semiconductor Manufacturing modified reactor adoption compresses 36-month qualification toward 18-month cycles. |
| REACH Registration Pre-Documentation | ECHA compliance investment isolates EU-bound production liabilities for thin film exporters. |
| Battery Joint Development Agreements | Lithium-ion intercalation formulation partnerships with cell manufacturers de-risk energy storage revenue streams. |
| EPA Premanufacture Notification Clearance | TSCA Section 5 documentation maintenance secures procurement influence with domestic distributor consolidation. |
Methodological Framework
SEC 10-K filings, ECHA REACH registration databases, and US Department of Energy grant award records formed the secondary backbone. Primary interviews with molecular beam epitaxy technicians, semiconductor fab procurement officers, nanomaterial distributor account managers, and battery cell R&D directors combined with secondary validation. Bottom-up triangulation across synthesis route capacity estimates and top-down cross-check against federal funding flows anchored volume projections.
Historical trendline analysis of graphene market maturation patterns informed borophene adoption curve assumptions across the projection horizon. Segmentation modeling spanned product type, application vertical, synthesis technology, and end-user procurement sophistication. CAGRs derived from segment-level growth rate differential analysis. Forecast inputs included EPA notification approval timelines and OEM qualification program conversion rates.
Underlying measurement precision varies by segment; thin film electronics applications carry tighter precision than emerging energy storage formulations. Forecasts reflect assumptions about federal nanotechnology funding continuity and silver price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Curable Materials Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Bioactive Glass Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market